
 Fe EDDHA Market | 2026-2036
Fe EDDHA Market Size, Share, and Industry Trends Forecast 2026-2036
Fe EDDHA Market Insights
Direct-to-grower channels in the specialty fertilizer sector is narrowing as manufacturers consolidate distribution partnerships. BASF SE leverages its global logistics backbone to sustain supply continuity across European horticulture clusters. Yara International ASA anchors its position through backward integration into chelate synthesis. Haifa Group competes by specializing in water-soluble formulations for drip irrigation systems.
Fe EDDHA denotes ferric ethylenediamine-N,N'-bis(2-hydroxyphenylacetic acid), an iron chelate with a molecular stability constant enabling sustained nutrient availability in calcareous soils above pH 7.5. The compound prevents iron chlorosis in high-value fruit and vegetable crops through soil application or fertigation. Powder formulations dominate volume sales in bulk agricultural procurement, while liquid concentrates capture margin pools in greenhouse and hydroponics applications where precision dosing commands premium positioning. Granular grades retain share in broad-acre farming where mechanized spreading reduces labor costs.
EU REACH registration requirements and EFSA residue guidelines shape product composition standards and market access conditions for chelated micronutrient suppliers. The EPA regulates iron chelate tolerances under the Federal Insecticide, Fungicide, and Rodenticide Act in the United States, affecting import eligibility and label claims. Stakeholders must monitor evolving soil carbon certification frameworks and fertilizer efficiency regulations that could redefine value capture in micronutrient supply chains.
Market Dynamics
EU REACH compliance is compressing allowable heavy-metal thresholds in micronutrient formulations, forcing reformulation investments across the specialty fertilizer supply chain while Mediterranean horticulture clusters absorb premium-grade Fe EDDHA to maintain export eligibility.
Growth Catalysts
- EFSA Residue Guidelines:Tightening maximum residue limits for cadmium and lead in food-grade crops compel Spanish and Italian growers toward certified low-impurity chelates.
- Calcareous Soil Expansion:Rising pH levels in irrigated agricultural zones across Spain's Almería province and California's Central Valley expand addressable acreage for stable iron chelates.
- Drip Irrigation Density:Precision fertigation infrastructure in Dutch greenhouse complexes and Israeli desert agriculture creates pull for liquid concentrate formulations with calibrated dosing compatibility.
Market Restraints
- Ethylenediamine Feedstock Volatility:Petrochemical-derived diamine precursors expose manufacturers to naphtha price swings and European energy cost spikes.
- Synthesis Concentration Risk:Bulk powder production concentrates in northwest European chemical corridors, creating single-source vulnerability for agricultural distributors.
- EDDHA-Analog Substitution:Fe EDDHMA and Fe HBED chelates with comparable pH stability threaten to displace standard-grade EDDHA in high-value greenhouse applications.
Strategic Opportunities
- Soil Carbon Certification Frameworks:Emerging EU carbon farming verification protocols reward micronutrient efficiency metrics, creating premium positioning for documented chelate performance.
- Sub-Saharan Horticulture:Underpenetrated protected cultivation in Morocco and South Africa offers expansion corridors for water-soluble formulations adapted to saline irrigation water.
- Biostimulant Convergence:Integration of Fe EDDHA with microbial inoculants and seaweed extracts opens blended product categories commanding margin premiums in organic transition markets.
Industry Challenges
- REACH Registration Timeline Compression:ECHA's substance evaluation deadlines force simultaneous toxicology package updates and supply chain disclosure overhauls.
- Analytical Method Standardization:Inconsistent o,o-EDDHA isomer measurement protocols between ISO methods and national fertilizer regulations create batch rejection risks at customs.
- Legacy Formulation Integration:Retrofitting granular spreading equipment for liquid concentrate compatibility requires capital outlays that smaller Spanish cooperatives defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fe EDDHA Market |
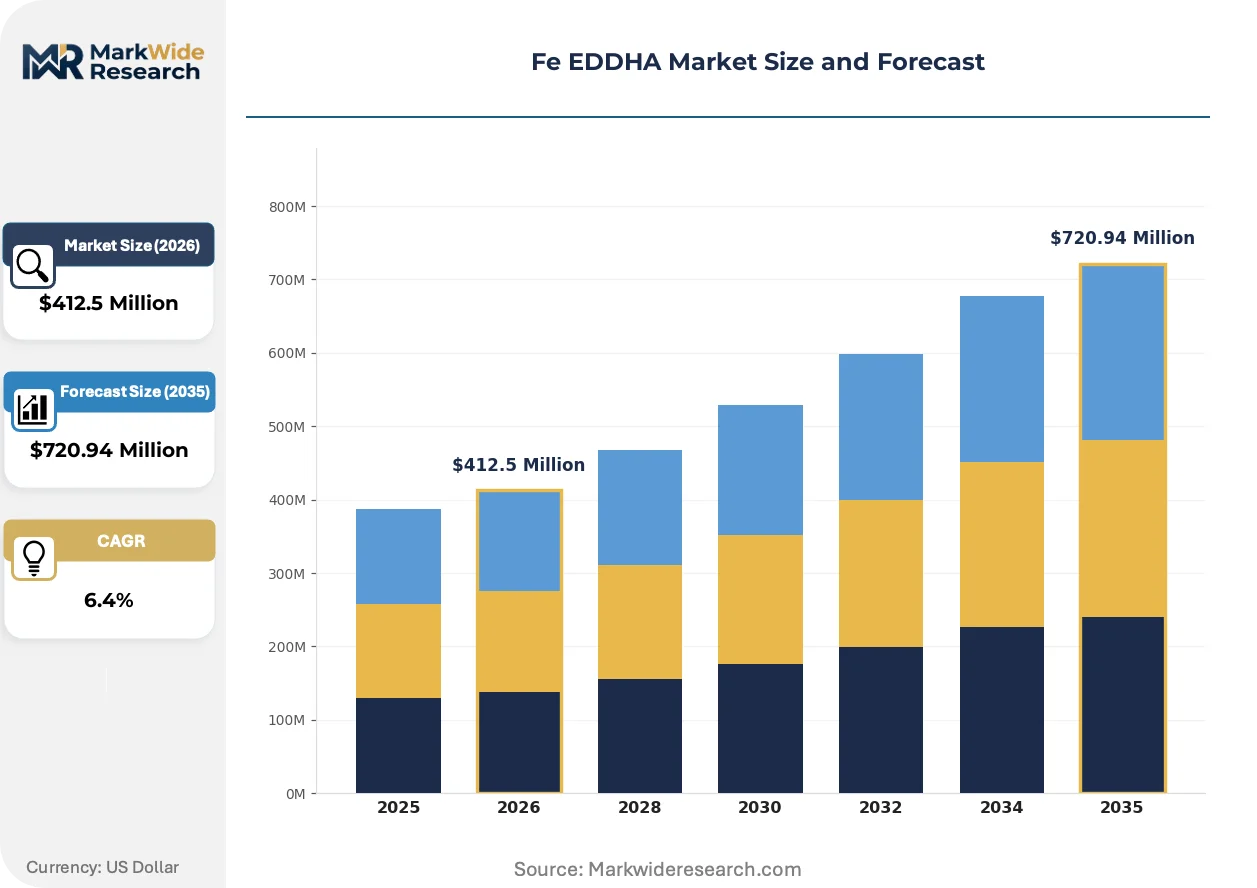
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Liquid, Chelate Application: Agronomy, Horticulture, Turf Management, Hydroponics End User: Farming, Landscaping, Greenhouses, Retail Packaging Type: Bags, Drums, Containers, Bulk |
| Companies Covered | BASF SE, Yara International ASA, Haifa Group, Nufarm Limited, Adama Agricultural Solutions Ltd., Syngenta AG, Nutrien Ltd., Nouryon Holding B.V., FMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fe EDDHA Market Trends and Innovations
Formulation chemistry and regulatory verification protocols are converging to redefine value capture in iron chelate markets, with stability metrics and carbon intensity documentation emerging as competitive differentiators alongside traditional agronomic performance.
Microencapsulated Fe EDDHA delivery systems are hybridizing controlled-release kinetics with conventional chelate chemistry. Dutch greenhouse operators in Westland municipalities pilot these hybrid formulations to synchronize iron availability with tomato flowering stages. The technology is hybridizing product categories previously segmented by application method, compressing differentiation between soil-applied and fertigation-grade portfolios.
EU Fertilizing Products Regulation (FPR) harmonization is mandating CE-marked conformity assessment for all chelated micronutrients placed on the single market. Manufacturers must now compile module D quality assurance documentation and engage notified bodies for ongoing production surveillance. Spanish formulation plants serving Almería's export-oriented horticulture are prioritizing FPR-compliant labeling to maintain shelf access across member states.
Certification-driven procurement now dominates buyer evaluation protocols in California's Central Valley vegetable cooperatives. Third-party verified low-impurity grades displace uncertified alternatives in annual supply agreements, with documentation of o,o-EDDHA isomer content replacing price-per-kilogram as the primary negotiation axis. This behavioral pivot is most visible in organic transition zones where residue testing protocols intersect with retailer sustainability audits.
Fe EDDHA Market Segmentation
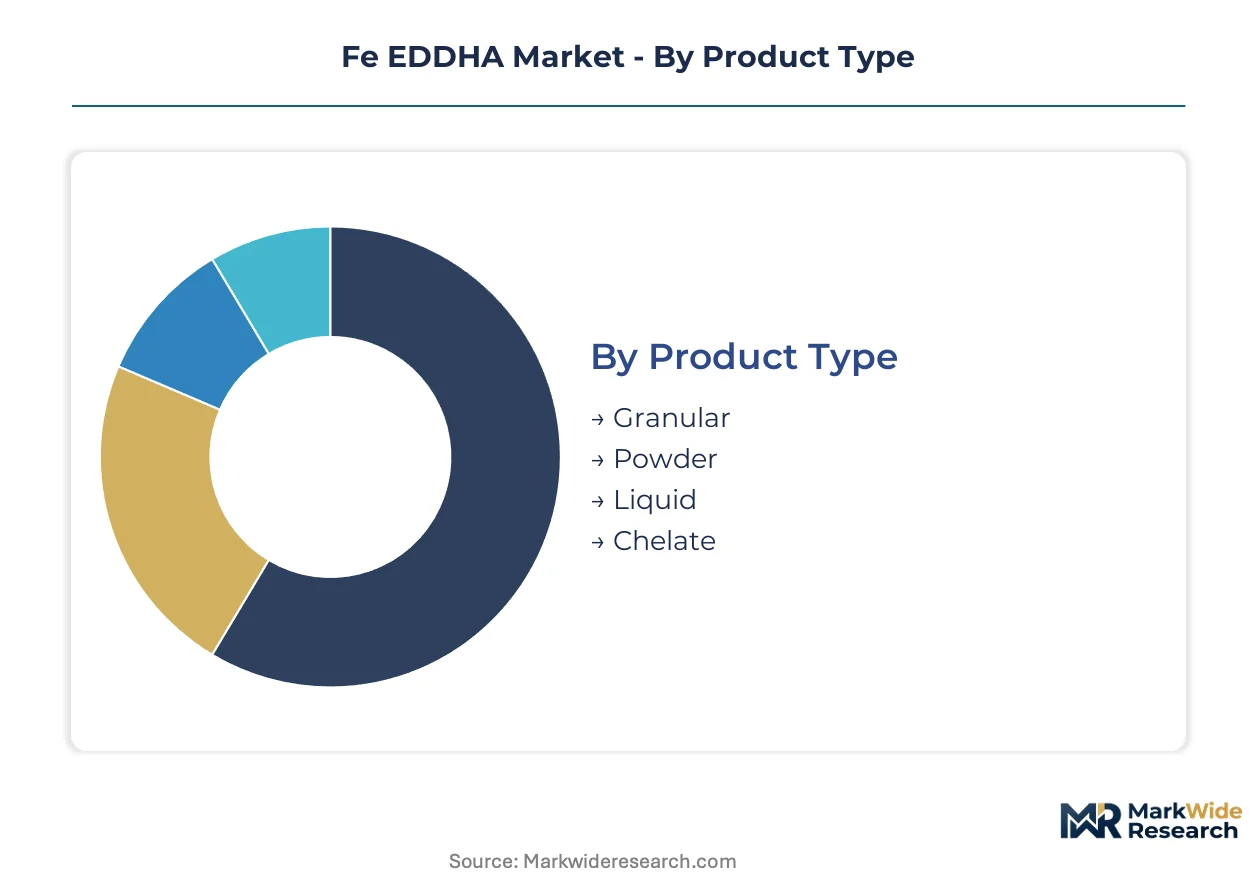
Fe EDDHA formulations diverge sharply across application contexts, with soil chemistry, irrigation infrastructure, and labor economics dictating product selection. Segmentation reveals how manufacturers align physical form factors with specific value-chain positions.
Product Type:
Physical state determines compatibility with spreading equipment, dissolution kinetics, and storage logistics across the use-case spectrum from broad-acre field crops to precision greenhouse systems.
- Granular:Slow-dissolving pellets suit mechanized spreading in Spanish almond orchards and California pistachio groves where labor minimization outweighs dissolution speed. Almería cooperatives favor this grade for pre-planting soil incorporation despite slower iron release kinetics.
- Powder:Fine-ground formulations dominate volume procurement through agricultural distributors serving Dutch vegetable cooperatives and Israeli desert farms. The physical form enables rapid tank dissolution for batch-prepared fertigation solutions.
- Liquid:Concentrated solutions integrate directly with drip-line injectors in Westland greenhouse complexes. Precision dosing compatibility commands margin premiums where automated fertigation systems predominate.
- Chelate:High-purity grades with documented o,o-EDDHA isomer ratios serve export-oriented horticulture facing EFSA residue scrutiny. REACH-registered variants access premium shelf positioning in EU fertilizing product catalogs.
Established volume favors Powder; emerging adoption favors Liquid.
Application:
Soil pH regimes and crop value density create divergent performance requirements across cultivation systems.
- Agronomy:Field-scale cereal and oilseed production in calcareous Spanish soils employs standard-grade chelates for chlorosis prevention. Cost sensitivity here limits uptake to high-value rotations rather than commodity grains.
- Horticulture:Intensive vegetable and fruit cultivation in California's Central Valley and Italy's Po Valley absorbs the majority of certified low-impurity tonnage. EFSA-compliant grades maintain export eligibility for supermarket supply chains.
- Turf Management:Golf course and sports field maintenance in arid US Sun Belt states drives seasonal demand for rapid-greening formulations. Saline irrigation tolerance distinguishes premium offerings in desert municipalities.
- Hydroponics:Closed-loop nutrient film systems in Dutch greenhouse clusters and Israeli net-house operations demand ultra-pure soluble grades. Recirculating solution chemistry mandates absence of precipitating impurities.
Revenue concentration sits with Horticulture; steepest expansion trajectory emerges in Hydroponics.
End User:
Procurement scale and technical sophistication segment the customer base across divergent buying behaviors.
- Farming:Large-scale agricultural enterprises in Spain's Murcia region negotiate annual supply contracts with documented heavy-metal certificates. Volume purchasing power compresses per-unit margins while ensuring supply security.
- Landscaping:Municipal parks departments and commercial grounds maintenance contractors in California's urban centers source seasonal quantities through horticultural wholesalers. Specification compliance matters less than visual response speed.
- Greenhouses:Controlled-environment agriculture operators in the Netherlands and Belgium prioritize liquid concentrates compatible with automated dosing systems. Technical support integration influences supplier selection.
- Retail:Garden center and e-commerce channels serve home horticulture enthusiasts with small-package powder and liquid formats. Brand recognition and application guidance dominate purchase decisions.
Procurement scale favors Farming; margin capture favors Greenhouses.
Packaging Type:
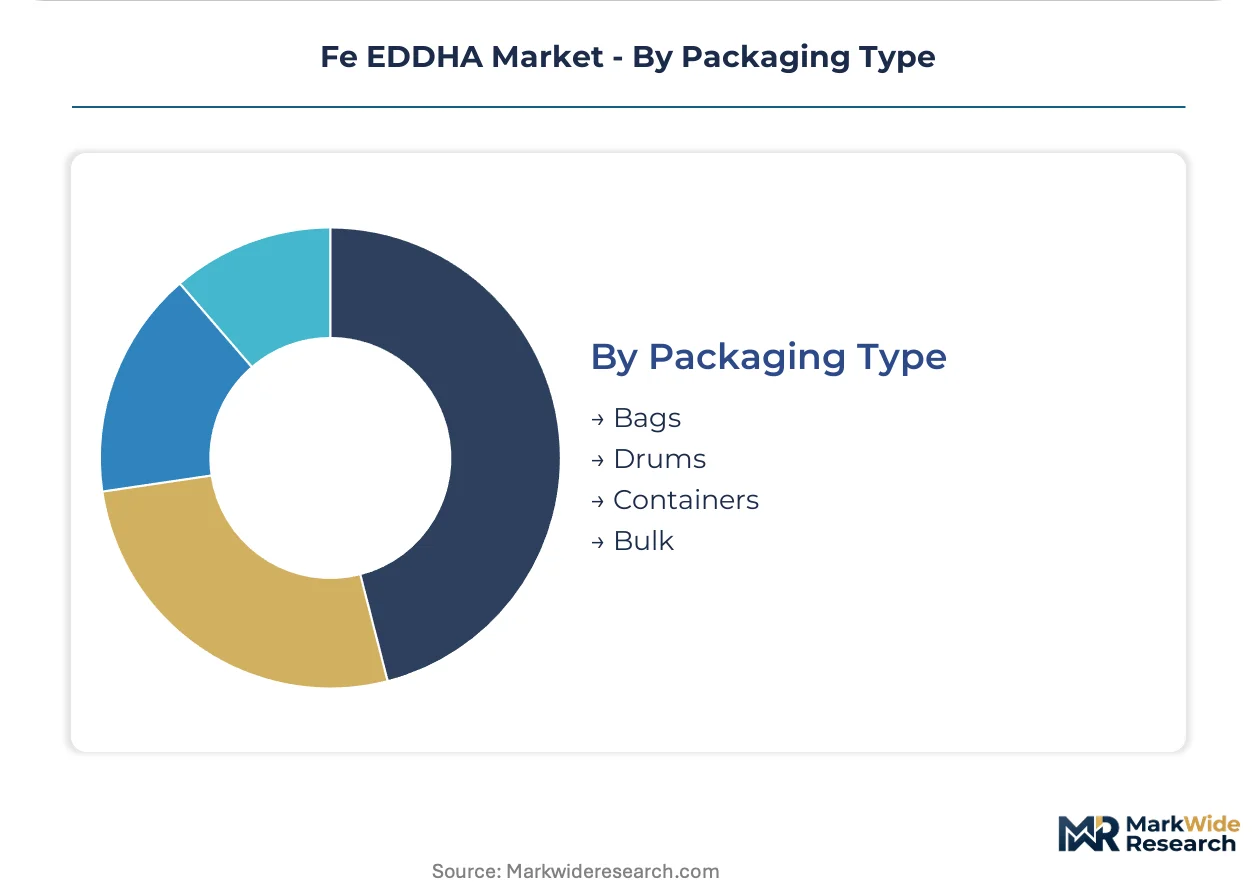
Logistics economics and handling infrastructure dictate container selection across distribution tiers.
- Bags:Multi-layer laminated sacks protect hygroscopic powders during Mediterranean summer storage. Spanish distributor warehouses favor 25kg units for palletized handling efficiency.
- Drums:Steel and HDPE containers secure liquid concentrates against UV degradation in Israeli desert supply chains. Returnable drum programs reduce per-shipment packaging costs for high-volume greenhouse accounts.
- Containers:Intermediate bulk containers serve Dutch cooperative purchasing pools with shared storage facilities. Reduced handling frequency offsets higher unit capital commitment.
- Bulk:Tanker and pneumatic trailer delivery eliminates packaging entirely for integrated greenhouse operations with on-site storage silos. Minimum order thresholds restrict access to largest cultivation enterprises.
Flexibility and working capital efficiency favor Bags; total landed cost optimization favors Bulk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA residue guidelines anchor European demand calibration for Fe EDDHA formulations. Spain's Almería intensive horticulture belt absorbs certified low-impurity grades to maintain supermarket export eligibility. California's Central Valley vegetable cooperatives drive parallel procurement intensity under EPA FIFRA tolerances.
Spain
Almería's greenhouse complex generates concentrated pull for REACH-registered liquid concentrates compatible with drip-line infrastructure. The country's national fertilizer regulator enforces EU Fertilizing Products Regulation conformity assessment for all chelated micronutrients. Murcia's citrus and stone-fruit orchards deploy granular grades for pre-planting soil incorporation despite slower dissolution kinetics.
United States
California's Central Valley vegetable production absorbs premium-grade Fe EDDHA to satisfy retailer sustainability audit protocols. EPA regulates iron chelate tolerances under FIFRA, affecting import eligibility and label claims for European suppliers. Arizona and Texas desert municipalities deploy saline-tolerant formulations for turf management under municipal water reuse programs.
Netherlands
Westland greenhouse clusters pilot microencapsulated delivery systems to synchronize iron availability with tomato flowering stages. The Dutch national agricultural authority enforces EU FPR module D quality assurance documentation for ongoing production surveillance. Eindhoven-region automated fertigation infrastructure creates sustained demand for liquid concentrate formulations with calibrated dosing compatibility.
Israel
Negev Desert net-house operations demand ultra-pure soluble grades for closed-loop nutrient film systems with recirculating solution chemistry. The country's national standards institute mandates absence of precipitating impurities in hydroponic-grade chelates. Jordan Valley date palm cultivation absorbs powder formulations through bulk procurement channels serving cooperative purchasing pools.
Italy
Po Valley fruit cultivation absorbs certified low-impurity tonnage to satisfy EFSA tightening of cadmium and lead maximum residue limits. The national agricultural regulator coordinates with ECHA on substance evaluation deadlines forcing toxicology package updates. Sicily's protected vegetable production retrofits granular spreading equipment for liquid concentrate compatibility under cooperative capital programs.
Fe EDDHA Market Competitive Landscape
Vertically integrated chemical conglomerates and specialized agricultural input suppliers split the market into distinct capability tiers. The vendor base concentrates around northwest European synthesis corridors and Israeli formulation expertise. Three archetypes dominate: petrochemical majors with captive diamine supply, regional blenders with distribution anchoring, and precision-agriculture specialists with fertigation technical integration. Competitive moves center on backward integration into chelate synthesis and consolidation of distribution partnerships across Mediterranean horticulture clusters.
Among diversified chemical majors with agricultural divisions, BASF SE and Yara International ASA occupy positions representing scale-driven supply continuity and logistics backbone depth. Haifa Group exemplifies the precision-agriculture specialist archetype, anchoring water-soluble formulation expertise for drip irrigation systems. These three entities collectively illustrate the strategic segmentation between petrochemical-integrated supply security and application-specific technical service capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Yara International ASA |
| Haifa Group |
| Nufarm Limited |
| Adama Agricultural Solutions Ltd. |
| Syngenta AG |
| Nutrien Ltd. |
| Nouryon Holding B.V. |
| FMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Northwest European chemical corridors around Antwerp and Rotterdam concentrate bulk powder synthesis capacity, creating asymmetric pricing power for REACH-registered grades that Spanish cooperatives cannot easily substitute. ECHA registration timelines compress supply alternatives, allowing incumbent manufacturers to capture premium spreads on documented low-impurity formulations.
Pricing Analysis
Price spreads between northwest European liquid concentrates and standard-grade powders widen during ethylenediamine feedstock volatility. Contract-based long-term offtake dominates procurement for Dutch greenhouse operators, while spot purchasing persists among smaller Spanish agricultural cooperatives. Certification grade and volume scale drive differentiation, with EFSA-compliant low-cadmium variants commanding substantial premia over uncertified alternatives. Price erosion runs through standard powder tiers as EDDHMA and HBED analogs gain technical acceptance in greenhouse applications. Farming enterprises exhibit highest price sensitivity, deferring liquid concentrate upgrades despite labor savings.
Supply Chain Analysis
Ethylenediamine precursors draw from petrochemical naphtha streams concentrated in northwest Europe, with additional synthesis capacity in Israel and China. Fe EDDHA production hinges on ortho-ortho EDDHA isomer separation technology, specialized chelation reactor infrastructure, and analytical certification laboratories. Single-source vulnerability concentrates in Belgian and Dutch formulation plants serving Almería's export horticulture. Distribution runs through agricultural cooperatives in Spain's intensive cultivation belts, with secondary channels through Dutch horticultural wholesalers and Israeli desert farming supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Fertilizing Products Regulation harmonization is transforming Fe EDDHA procurement into a platform ecosystem where REACH registration databases, carbon certification protocols, and automated fertigation systems interoperate to determine supplier viability.
For Market Incumbents: Harden supply continuity through captive ethylenediamine supply arrangements or long-term feedstock offtakes with northwest European petrochemical complexes. Accelerate FPR module D documentation across all production facilities to preempt notified body bottlenecks. Fe EDDHMA substitution technology represents the primary technical threat requiring formulation R&D response. For New Entrants and Emerging Players: Sub-Saharan protected cultivation in Morocco and South Africa represents the most penetrable entry point, with saline irrigation tolerance and water-soluble formulation adaptation as the critical technical wedge. Biostimulant convergence products—Fe EDDHA blended with microbial inoculants—offer a differentiated go-to-market angle in organic transition zones where incumbent chemical majors lack positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-agriculture specialists with fertigation technical integration capabilities over commodity-grade powder manufacturers. Long-term viability rests on carbon farming verification protocol alignment and soil carbon certification framework participation. Watch for ECHA substance evaluation deadline compression as an inflection signal forcing consolidation among undercapitalized regional blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chelate Synthesis | Captive ethylenediamine supply insulates margins from petrochemical volatility in European energy markets. |
| FPR Module D Quality Assurance Certification | CE-marked conformity assessment unlocks shelf access across EU member state fertilizing product catalogs. |
| Microencapsulated Delivery System Development | Synchronized nutrient release with tomato flowering stages commands premium positioning in Dutch greenhouse clusters. |
| Sub-Saharan Distribution Partnership | Morocco and South African cooperative networks offer first-mover advantage in underpenetrated protected cultivation. |
| Biostimulant Convergence Product Launch | Blended formulations with microbial inoculants access organic transition market premia. |
Research Methodology
A standing panel of chelate synthesis plant managers, agricultural cooperative procurement leads, Dutch greenhouse technical directors, and ECHA regulatory affairs specialists provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against EU Fertilizing Products Regulation submission databases, ECHA REACH registration dossiers, Spanish agricultural ministry fertilizer catalogs, and customs trade data tracking iron chelate flows. Bottom-up volume estimates from individual formulation plants were triangulated against top-down demand models built on irrigated acreage expansion and pH monitoring datasets.
Scenario-bracketing framed the analytical approach, with low-case assumptions incorporating EDDHMA substitution acceleration and high-case assumptions modeling carbon farming subsidy expansion. Segmentation dimensions spanned physical form factor, application system compatibility, certification grade tier, and regional regulatory cluster. CAGRs were derived from regression analysis against historical price-volume relationships and forward-projected acreage trends. Key forecast inputs included ethylenediamine contract price indices and EFSA maximum residue limit revision timelines.
Stress conditions across feedstock cost spikes, REACH registration timeline compression, and EDDHA-analog substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization pace and cooperative capital availability for equipment retrofitting. Quarterly review of ECHA substance evaluation deadlines and carbon certification protocol adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Global Mannosylerythritol Lipids Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
US Post Laser Recovery Products Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Cellulose Acetate Phthalate Market
Specialty Chemicals
Perfluoroalkoxy Alkane (PFA) Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Sodium Adipate Market