
 Radiation Detection Monitoring and Safety Market | 2026-2036
Radiation Detection Monitoring and Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Detection Monitoring and Safety Market Insights
Aftermarket service revenue for calibration, certification, and detector refurbishment is rewriting profitability models across the radiation safety value chain. Mirion Technologies leverages its installed base of power plant monitoring systems to sustain recurring service contracts with utilities. Thermo Fisher Scientific anchors its position through R&D intensity in scintillation materials, while Fortive competes by dominating industrial hygiene channels with integrated safety platforms.
Radiation detection monitoring and safety encompasses instruments and systems that measure ionizing radiation exposure through detection principles including gas ionization, semiconductor charge collection, or luminescence conversion, with sensitivity thresholds spanning nanosieverts to grays depending on application. These technologies serve to protect personnel, secure facilities, and ensure environmental compliance across nuclear, medical, and industrial operations. Personal dosimeters and area monitors lead product type revenue due to mandated wear programs and perimeter security requirements at nuclear installations. Scintillation detectors represent the fastest-growing technology segment as sodium iodide and lanthanum bromide crystals achieve superior energy resolution for isotope identification. Emergency response applications command premium pricing owing to ruggedization requirements and rapid deployment protocols.
The Nuclear Regulatory Commission enforces 10 CFR Part 20 standards for occupational exposure limits, compelling facilities to maintain active dosimetry programs with accredited vendors. The EPA RadNet system and FDA 21 CFR Subchapter J radiological health regulations further shape product specifications and market access for domestic manufacturers. Stakeholders must monitor evolving homeland security grant allocations and NRC license renewal schedules to anticipate replacement cycles and compliance-driven procurement waves.
Market Dynamics
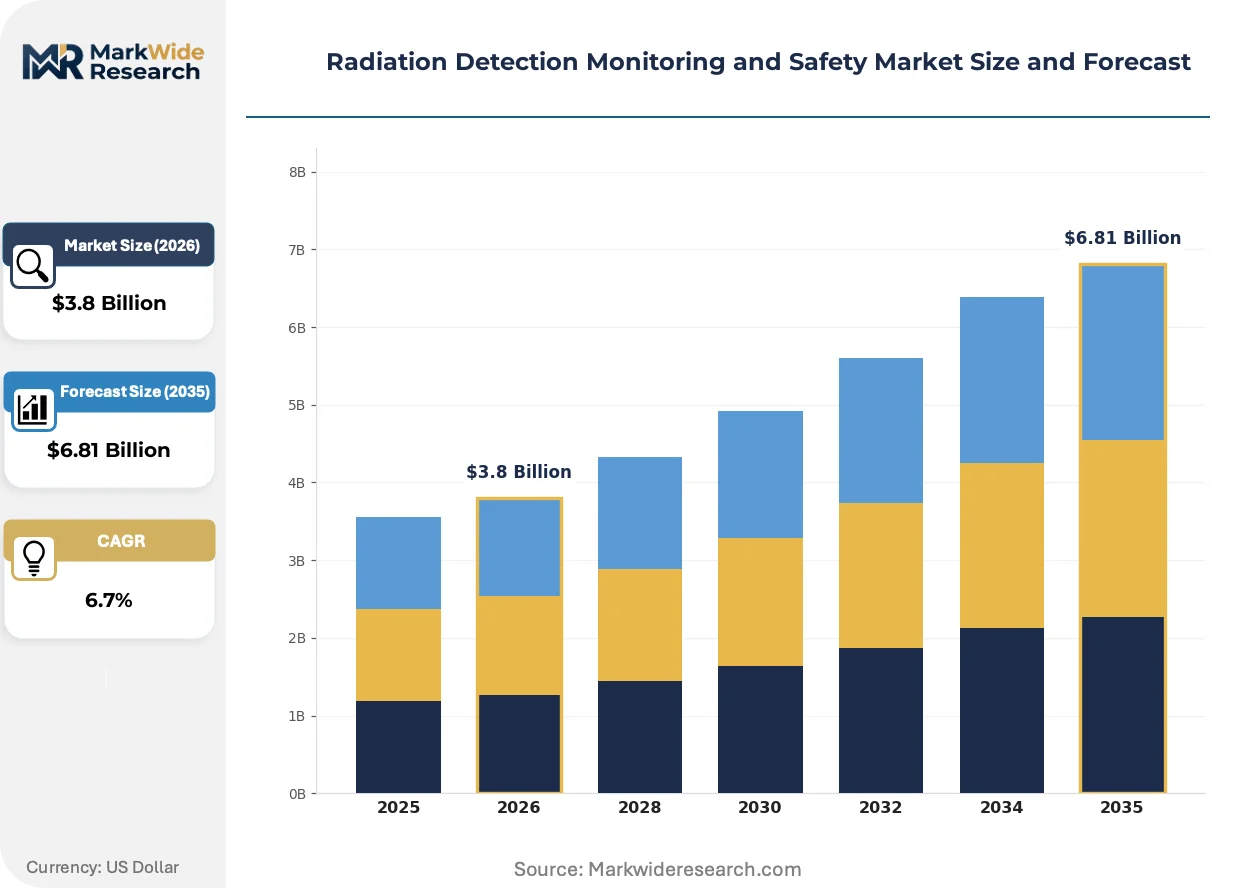
The Radiation Detection Monitoring and Safety Market is being fundamentally reshaped by the EPA's RadNet expansion and NRC reactor oversight tightening, which together mandate wholesale replacement of aging detection infrastructure across nuclear facilities, medical centers, and environmental monitoring stations.
Growth Catalysts
- 10 CFR Part 20 compliance mandates:The Nuclear Regulatory Commission enforces strict occupational exposure limits, compelling nuclear power plants and medical facilities to maintain active dosimetry programs with accredited vendors.
- Scintillation crystal advances:Sodium iodide and lanthanum bromide detectors achieve superior energy resolution for isotope identification, driving replacement cycles in homeland security and nuclear medicine applications.
- Hospital network consolidation:United States health systems are centralizing radiology safety programs, creating pooled procurement volumes for personal dosimeters and area monitoring systems.
Market Restraints
- Helium-3 supply concentration:The United States dominates neutron detector gas supply through national stockpile management, creating vulnerability for manufacturers dependent on this critical input.
- Semiconductor detector cost structure:High-purity germanium crystal growth requires specialized foundry capacity concentrated in Germany and the United States, limiting price elasticity for high-resolution spectroscopy systems.
- FDA 21 CFR Subchapter J friction:Radiological health device approvals impose lengthy premarket notification timelines, delaying product launches for domestic manufacturers.
Strategic Opportunities
- India's nuclear power expansion:The Atomic Energy Regulatory Board is licensing new reactor capacity, creating demand for perimeter monitoring and personnel dosimetry systems at greenfield installations.
- Artificial intelligence convergence:Machine learning algorithms integrated with gamma spectroscopy are enabling real-time isotope identification without human analyst intervention.
- Homeland security grant programs:Federal emergency response funding is channeling portable detection systems to metropolitan radiation response teams.
Industry Challenges
- Calibration technician scarcity:Qualified personnel for accredited dosimetry laboratory operations are concentrated at a handful of national laboratories, constraining service expansion.
- Legacy system integration friction:New solid-state detectors must interface with decades-old plant monitoring architectures, complicating deployment at nuclear facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Detection Monitoring and Safety Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Dosimeters, Area Monitors, Survey Meters, Radiation Portal Monitors Technology: Geiger-Muller Counters, Solid-State Detectors, Scintillation Detectors, Ionization Chambers End User: Nuclear Power Plants, Medical Facilities, Research Laboratories, Industrial Applications Application: Radiological Safety, Environmental Monitoring, Nuclear Waste Management, Emergency Response |
| Companies Covered | Mirion Technologies, Thermo Fisher Scientific, Fortive, AMETEK, Ludlum Measurements, Fuji Electric, LANDAUER, Kromek Group, Teledyne FLIR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Detection Monitoring and Safety Market Trends and Innovations
Digital signal processing architectures and artificial intelligence are compressing detection response times while expanding autonomous monitoring capabilities across nuclear, medical, and environmental applications.
Cadmium zinc telluride semiconductor arrays are rendering obsolete traditional scintillation-based spectrometers in portable isotope identification devices. Nuclear security teams at border crossings and ports of entry are adopting these solid-state systems for their room-temperature operation and superior energy resolution. The technology is rendering obsolete the liquid nitrogen cooling requirements that previously constrained field deployment of high-resolution gamma spectroscopy.
The EPA RadNet monitoring expansion is mandating upgraded air sampling and particulate detection infrastructure at monitoring stations nationwide. Station operators must deploy automated high-volume air samplers with real-time data transmission capabilities to meet new quality assurance protocols. Environmental monitoring contractors are responding by consolidating maintenance contracts and standardizing on interoperable data formats.
Service unbundling is separating hardware procurement from calibration and certification obligations across hospital radiology departments. Third-party dosimetry laboratories are capturing recurring revenue streams that equipment manufacturers previously controlled through bundled service agreements. This pattern is most visible in the United States, where health system procurement offices are aggressively disaggregating capital and operating expenditures.
Radiation Detection Monitoring and Safety Market Segmentation
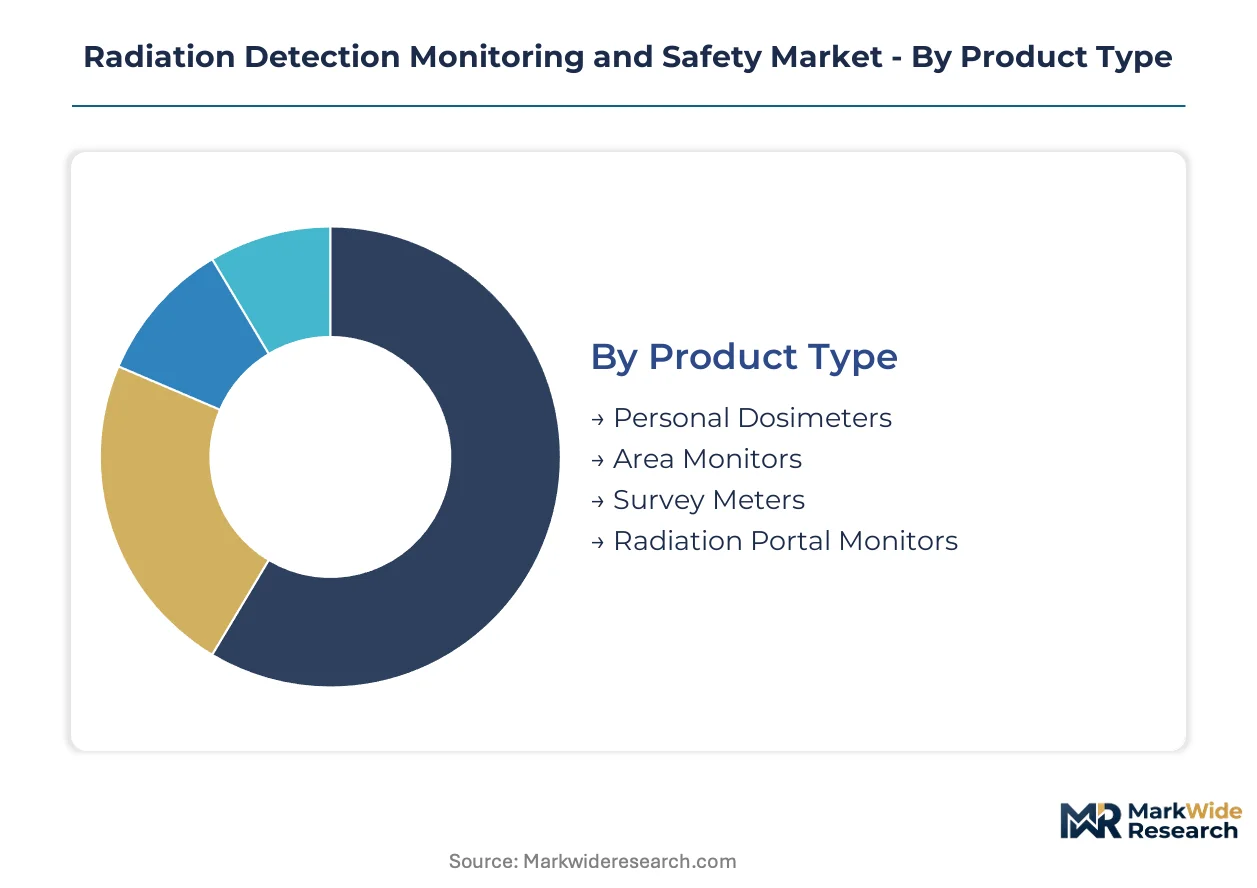
Segmentation in radiation detection reveals distinct procurement patterns across hardware categories, with service intensity varying dramatically between disposable dosimetry badges and capital-intensive portal monitor installations. Understanding these structural differences enables vendors to calibrate pricing models and aftermarket capture strategies.
Product Type:
Aftermarket service intensity diverges sharply across product categories, with personal dosimeters generating recurring laboratory processing fees while area monitors demand on-site calibration contracts.
- Personal Dosimeters:Film badge and thermoluminescent devices accumulate cumulative exposure readings through quarterly or monthly exchange cycles. Hospital networks in the United States centralize procurement through group purchasing organizations, pooling volumes that exceed ten thousand units annually for large health systems.
- Area Monitors:Fixed-position gamma and neutron detectors require semi-annual calibration certification under 10 CFR Part 20 mandates. Nuclear power plant installations generate fifteen-year service contracts encompassing detector replacement, firmware updates, and regulatory documentation.
- Survey Meters:Handheld contamination instruments serve decommissioning crews and emergency responders with battery-dependent portability.
- Radiation Portal Monitors:Vehicle and pedestrian screening arches at border crossings incorporate plastic scintillator panels with centralized remote monitoring.
By volume, Personal Dosimeters leads. By growth pace, Radiation Portal Monitors is ahead.
Technology:
Cost tier stratification separates commodity gas-filled tubes from semiconductor arrays requiring specialized foundry partnerships.
- Geiger-Muller Counters:Halogen-quenched tubes dominate educational and low-cost industrial applications where energy discrimination is unnecessary. The EPA RadNet expansion sources these for gross beta monitoring at environmental stations.
- Scintillation Detectors:Sodium iodide crystals doped with thallium achieve superior energy resolution for isotope identification in homeland security applications. Lanthanum bromide variants are displacing legacy NaI(Tl) in spectroscopic portals due to improved light yield and faster decay times.
- Solid-State Detectors:Cadmium zinc telluride arrays operate at room temperature, eliminating liquid nitrogen logistics for field spectroscopy.
- Ionization Chambers:Pressurized argon or nitrogen-filled chambers measure high-dose-rate fields in reactor containment areas with exceptional stability.
By installed base, Geiger-Muller Counters dominates. By technology substitution momentum, Solid-State Detectors is climbing fastest.
End User:
Customer type determines procurement sophistication, with nuclear utilities running multi-year tenders while medical facilities prioritize accreditation compliance.
- Nuclear Power Plants:Reactor operators maintain redundant safety systems with triple-modular redundant area monitoring architectures. The NRC license renewal schedule drives replacement waves every twenty years.
- Medical Facilities:Radiology departments and nuclear medicine suites mandate occupational dosimetry for all personnel with potential exposure. United States hospital consolidation creates enterprise-wide safety program standardization.
- Research Laboratories:National laboratories and university physics departments deploy high-resolution germanium spectrometers for fundamental research.
- Industrial Applications:Oil well logging and pipeline inspection services utilize ruggedized gamma sources with associated survey instrumentation.
By procurement value concentration, Nuclear Power Plants leads. By contract velocity, Medical Facilities is expanding most quickly.
Application:
Margin structure varies by application maturity, with environmental monitoring commoditizing while emergency response commands specification premiums.
- Radiological Safety:Personnel protection systems encompass dosimetry programs, contamination control, and access monitoring at controlled areas. Regulatory enforcement intensity in the United States sustains vendor accreditation requirements.
- Emergency Response:Portable detection networks for metropolitan radiation response teams require rapid deployment protocols and interoperable data formats. Federal homeland security grants channel funding through state emergency management agencies.
- Environmental Monitoring:Air sampling networks and water analysis stations track fallout and effluent releases with automated data transmission.
- Nuclear Waste Management:Drum assay systems and dry cask monitoring verify inventory and containment integrity at storage facilities.
By program longevity, Environmental Monitoring leads. By funding trajectory, Emergency Response shows steepest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector fabrication concentrates in Germany and the United States, where specialized foundries for high-purity germanium and scintillation crystal growth command irreplaceable technical capacity. Procurement patterns diverge sharply across major economies, with regulatory enforcement intensity and nuclear infrastructure age determining replacement cycle timing.
United States
Hospital network consolidation and NRC license renewal schedules drive dosimetry program standardization. The EPA RadNet expansion mandates upgraded air sampling infrastructure at monitoring stations nationwide. National laboratory complexes at Oak Ridge and Argonne anchor domestic detector R&D and calibration services.
Germany
High-purity germanium crystal growth foundries supply spectroscopy systems to research and security applications. The country's nuclear phase-out redirects detection demand toward decommissioning workforce protection and environmental monitoring. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate radiation safety service providers.
Japan
Post-Fukushima regulatory tightening sustains perimeter monitoring upgrades at remaining reactor sites. METI oversight of occupational exposure limits compels utilities to maintain redundant detection architectures. Tokyo and Osaka metropolitan areas channel homeland security procurement toward portable identification systems.
China
Nuclear power capacity expansion under MEE environmental oversight creates demand for personnel dosimetry at greenfield installations. Domestic scintillation crystal production scales to reduce import dependency for sodium iodide and lanthanum bromide materials. Yangtze River Delta industrial zones concentrate detector assembly operations.
India
Atomic Energy Regulatory Board licensing of new reactor capacity drives procurement of area monitors and portal detection systems. BIS standards alignment for medical device safety shapes import specifications for radiology equipment. Mumbai and Chennai anchor national laboratory networks handling accredited dosimetry processing.
Radiation Detection Monitoring and Safety Market Competitive Landscape
Integrated safety platforms and specialized detector component suppliers split the market across distinct value capture models. Consolidation pressure concentrates among service-intensive segments where calibration accreditation creates switching costs. Three archetypes dominate: full-spectrum safety conglomerates leveraging installed base service contracts, semiconductor foundry-integrated detector specialists, and regional dosimetry laboratories capturing recurring processing revenue. Competitive moves center on backward integration into scintillation crystal supply and geographic expansion through national laboratory partnerships.
Within the conglomerate tier, Mirion Technologies and Thermo Fisher Scientific exemplify divergent platform strategies. Mirion anchors utility sector relationships through power plant monitoring system installations. Thermo Fisher occupies a position emphasizing materials science depth in scintillation technology development. Fortive represents the industrial hygiene channel integration archetype, bundling radiation detection into broader safety equipment portfolios.
| Leading Market Players |
|---|
| Mirion Technologies |
| Thermo Fisher Scientific |
| Fortive |
| AMETEK |
| Ludlum Measurements |
| Fuji Electric |
| LANDAUER |
| Kromek Group |
| Teledyne FLIR |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in high-purity germanium crystal growth foundries across Germany and the United States compresses supply elasticity while amplifying pricing power for spectroscopy system vendors serving nuclear medicine and homeland security applications.
Pricing Analysis
Aftermarket service contracts for calibration, certification, and detector refurbishment generate lifetime value multiples exceeding hardware margins across hospital networks and nuclear utilities. Three-tier pricing structure across premium, standard, and economy levels separates NRC-accredited laboratory services from unbundled equipment procurement and basic film-badge processing. Price differentiation hinges on certification tier under 10 CFR Part 20 mandates and geographic density of service technician deployment. Cost compression in commodity dosimetry badges intensifies as hospital group purchasing organizations consolidate volumes. Medical facilities exhibit highest price sensitivity for capital equipment, while nuclear utilities prioritize compliance assurance over unit economics.
Supply Chain Analysis
Helium-3 supply concentration between the United States national stockpile and neutron detector manufacturers creates single-source vulnerability for portal monitor and reactor instrumentation production. High-purity germanium crystal growth concentrates in Germany and the United States, while sodium iodide and lanthanum bromide scintillation crystal supply draws from China and Japan. Raw material dependencies span rare earth activators, halogen-quenched tube gases, and cadmium zinc telluride semiconductor substrates. Distribution runs through national laboratory calibration networks and authorized dosimetry service centers with NRC accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiation detection monitoring and safety sits in early-cycle expansion as EPA RadNet infrastructure mandates and NRC license renewal schedules synchronize replacement demand across environmental monitoring stations and nuclear facilities.
For Market Incumbents: Build switching-cost moats through captive calibration laboratory accreditation tied to long-term utility service contracts. Deepen backward integration into lanthanum bromide crystal supply to secure energy-resolution advantages against solid-state detector substitution. Expand technician training pipelines to preempt scarcity constraints in accredited dosimetry operations. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield reactor perimeter monitoring segment where Atomic Energy Regulatory Board licensing creates first-mover procurement windows. Target decommissioning workforce protection in Germany's nuclear phase-out zones with portable contamination instrumentation. Pursue AI-integrated gamma spectroscopy partnerships with homeland security grant administrators as the go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across solid-state detector fabrication as cadmium zinc telluride foundry scale economies emerge. Five-to-ten year viability favors semiconductor-integrated specialists with captive materials science capabilities over pure-play dosimetry processors. Watch NRC license renewal acceleration as the signal indicating replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Scintillation Crystal Backward Integration | Captive lanthanum bromide supply secures energy-resolution leadership against CZT substitution. |
| AI-Integrated Spectroscopy Development | Machine learning algorithms enable autonomous isotope identification without human analyst intervention. |
| National Laboratory Partnership Expansion | Calibration accreditation alliances with Oak Ridge and Argonne create geographic service density. |
| Portable Detector Ruggedization Programs | MIL-STD compliance opens federal emergency response grant funding channels. |
| Hospital GPO Contract Consolidation | Enterprise-wide dosimetry standardization captures recurring processing volumes from health system mergers. |
Research Methodology
Desk research of NRC license renewal databases, EPA RadNet infrastructure disclosures, and FDA 510(k) radiological health filings preceded structured interviews with nuclear utility safety officers, hospital biomedical engineering directors, and accredited dosimetry laboratory managers. Primary fieldwork with scintillation crystal suppliers and semiconductor detector foundries combined with secondary validation against SEC filings of listed safety conglomerates. Bottom-up unit economics for personal dosimeters, area monitors, and portal detection systems triangulated against top-down market sizing from procurement aggregation at national laboratories.
Assumptions held fixed include NRC enforcement intensity for 10 CFR Part 20 compliance, helium-3 national stockpile allocation policies, and hospital network consolidation velocity across the projection horizon. Modeled segmentation dimensions span detection technology, end-user archetype, and application criticality with regional regulatory cluster overlays. CAGRs derived from replacement cycle analysis synchronized to reactor license renewal schedules and RadNet infrastructure upgrade timelines. Forecast inputs incorporated scintillation crystal yield improvements and solid-state detector cost curves.
Sensitivities concentrate around helium-3 supply disruption, NRC regulatory enforcement variance, and AI spectroscopy adoption acceleration. Forecasts reflect documented assumptions regarding hospital procurement centralization and nuclear power plant operational life extensions. Material shifts in EPA RadNet funding allocation or Atomic Energy Regulatory Board licensing pace would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Senior Cat Food Market
Others
Air Purification Systems Market
Others
Grna Market
Others
Mexico Retail Market
Others
Africa Smart Card Market
Others
Taiwan Retail Market
Others
Wearable AI Market
Others
Profiling Floats Market
Others
Nuclear Power Cables Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Europe Air Separation Unit Market
Others
ASEAN Agricultural Logistics Market
Others
Astrology Market
Others
Cloud Advertising Market
Others
Global Smart Home Installation Service Market
Others
Turkey Health and Medical Insurance Market