
 Lunch Takeout Market | 2026-2036
Lunch Takeout Market Size, Share, and Industry Trends Forecast 2026-2036
Lunch Takeout Market Foresight
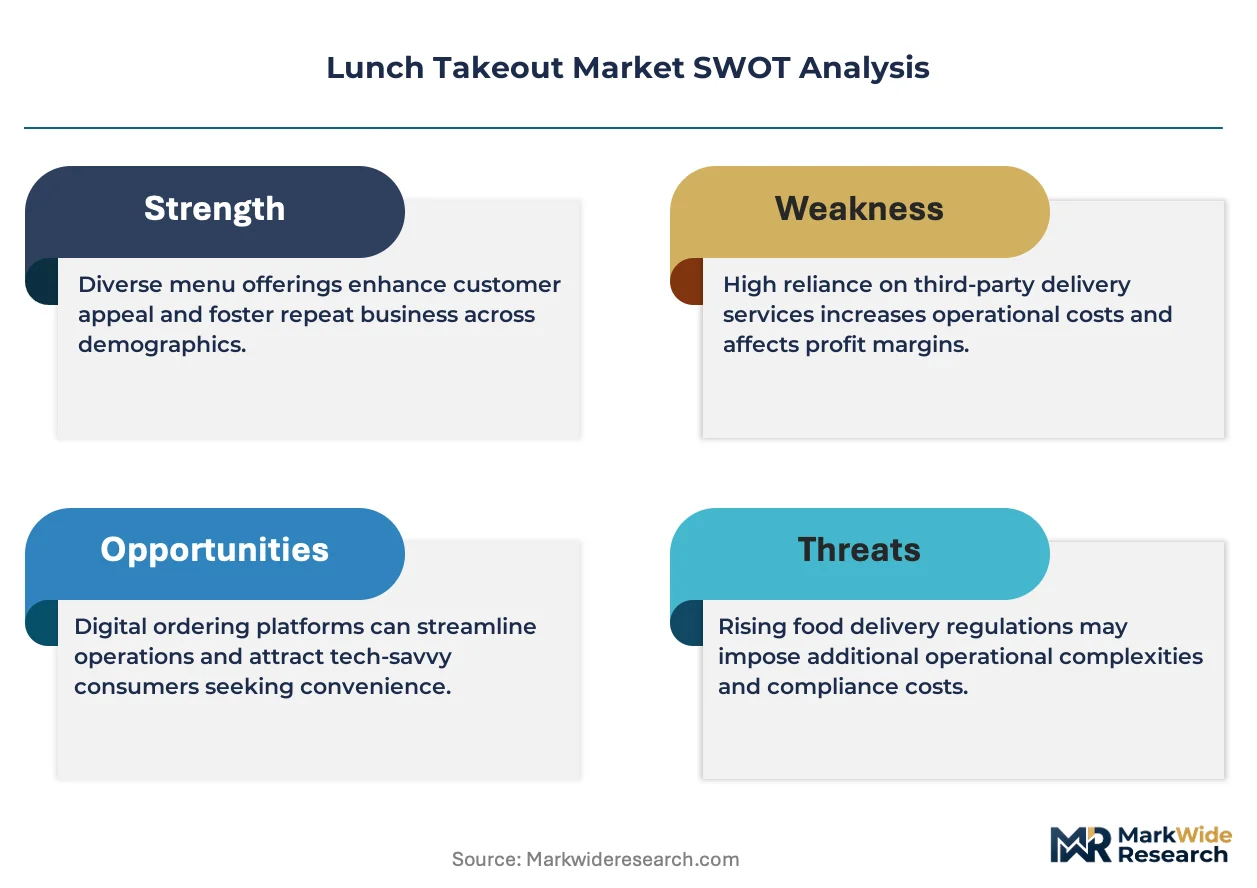
Asset-light franchising is tilting competitive dynamics toward operators who minimize real estate exposure. McDonald's Corporation leverages its vast franchise network to sustain capital-efficient expansion across dense metropolitan corridors. Chipotle Mexican Grill differentiates through vertical integration into fresh supply chains, controlling ingredient quality and throughput speed. DoorDash competes by aggregating demand across fragmented local restaurants, extending platform economics that smaller chains cannot replicate independently.
Lunch takeout comprises prepared meals designed for immediate consumption away from home, typically requiring temperature maintenance between 140°F hot-holding standards or 40°F cold-chain parameters, with packaging engineered for transport integrity over 15–45 minute delivery windows. Sandwiches and bowls anchor volume due to their assembly-line production efficiency and customization tolerance, while sushi commands premium price tiers where margin pools concentrate despite tighter spoilage windows. Online ordering and food apps now capture the dominant share of transaction flow, though in-store pickup retains structural importance for corporate catering contracts where bulk consolidation reduces per-unit delivery cost.
The FDA enforces Hazard Analysis Critical Control Point protocols across commercial kitchens, while state and municipal health departments impose graded inspection systems that determine operational eligibility. The USDA monitors protein sourcing standards that directly shape supplier qualification and menu composition for chain operators. Stakeholders must monitor how evolving delivery-app labor classification rulings from the Department of Labor reshape last-mile cost structures and platform fee economics.
Market Dynamics
The FDA's Food Safety Modernization Act traceability mandates are compressing supply chain timelines for prepared meal operators, forcing real-time inventory visibility investments that reshape unit economics across urban delivery corridors.
Growth Catalysts
- Corporate Digital Adoption:Enterprise procurement departments are mandating platform-integrated ordering systems for employee meal programs, consolidating transaction flow through centralized dashboards that reduce administrative overhead.
- FSMA Rule 204:The FDA's enhanced record-keeping requirements for high-risk foods are accelerating cold-chain infrastructure upgrades that simultaneously improve spoilage control and delivery radius extension.
- Urban Density Clustering:Metropolitan United States markets with 10,000+ employees per square mile generate sufficient order density to sustain sub-20-minute delivery windows at profitable unit economics.
Market Restraints
- Protein Input Volatility:USDA commodity price swings for chicken and beef directly compress margin pools for operators lacking forward-contract coverage or captive poultry processing.
- Last-Mile Labor Reclassification:Department of Labor rulings on delivery-app worker status threaten fee-structure disruption in California, New York, and Illinois metropolitan zones.
- Packaging Cost Concentration:Petroleum-derived container and insulation material costs track crude price movements with limited near-term biodegradable substitution at scale.
Strategic Opportunities
- Suburban Corridor Expansion:Secondary United States metropolitan rings with 5,000-8,000 employees per square mile remain underserved by premium lunch operators, presenting first-mover consolidation potential.
- AI-Driven Demand Forecasting:Machine learning models trained on corporate calendar data and weather patterns are reducing pre-production waste by 12-18 percentage points for early adopters.
- Reusable Container Mandates:Municipal ordinances in Seattle, San Francisco, and Washington D.C. are creating compliant infrastructure requirements that favor operators with established circular logistics partnerships.
Industry Challenges
- Kitchen Automation Integration:Robotic assembly line deployment requires 18-24 month retrofit timelines and specialized maintenance technician recruitment that outpaces available labor pools.
- Multi-Platform Order Orchestration:Operators managing simultaneous DoorDash, Uber Eats, and direct-channel fulfillment face kitchen throughput bottlenecks and error-rate spikes during peak windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lunch Takeout Market |
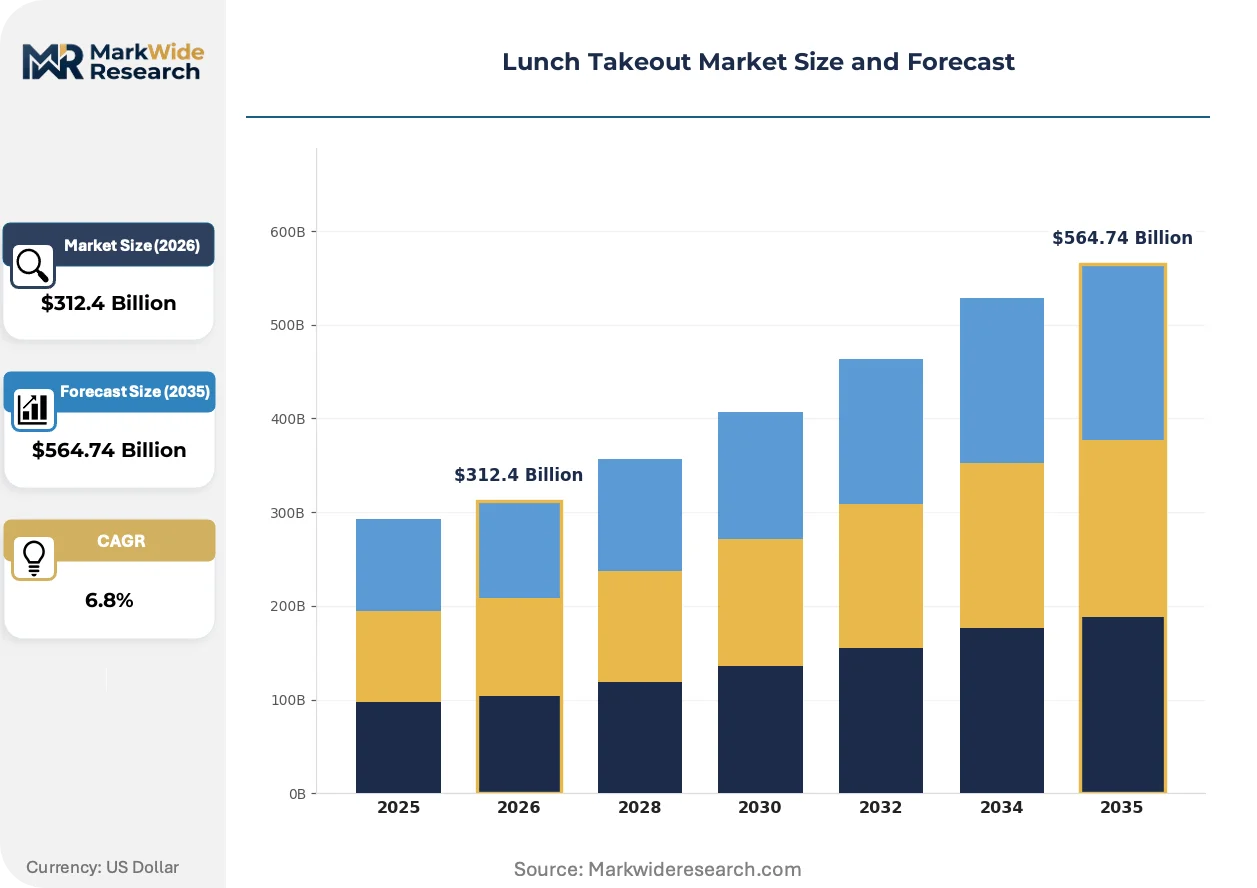
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $564.74 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandwiches, Salads, Sushi, Bowls Distribution Channel: Online Ordering, Food Apps, Delivery Services, In-store Pickup Customer Type: Corporate Employees, Students, Families, Health-conscious Consumers Price Tier: Budget-friendly, Mid-range, Premium, Gourmet |
| Companies Covered | McDonald’s Corporation, DoorDash, Uber Eats, Domino's Pizza Inc., Subway, Restaurant Brands International Inc., Chipotle Mexican Grill Inc., Panda Express, Grubhub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lunch Takeout Market Shifts & Advancements
Digital-native ordering infrastructure is compressing the traditional lunch procurement cycle from scheduled catering contracts to impulse-driven individual transactions, restructuring kitchen capacity planning and inventory management protocols.
Dynamic pricing algorithms are migrating from ride-hailing platforms into lunch delivery apps, adjusting menu item costs in 15-minute increments based on kitchen queue depth and courier availability. Enterprise cafeteria managers are resisting this volatility for contracted corporate accounts, creating a bifurcated pricing architecture between individual and bulk channels. The technology is enabling demand flattening that protects margin during peak windows.
California's CalRecycle regulations and New York City's expanded foam ban are prohibiting single-use petroleum-based food containers in phased implementations through 2025. Operators must certify fiber-based or reusable alternatives through third-party compostability validation, adding 8-12 cents per unit in packaging costs. Quick-service chains with centralized procurement leverage are absorbing this friction faster than independent delis.
Individual employees are abandoning group catering coordinators for direct mobile ordering, fragmenting order sizes from 20-person platters to single-item transactions. Human resources departments are responding with subsidized individual meal allowances that replace traditional conference room lunch budgets. This pattern is most pronounced in technology sector headquarters across Austin, Seattle, and Boston metropolitan zones.
Lunch Takeout Market Segmentation
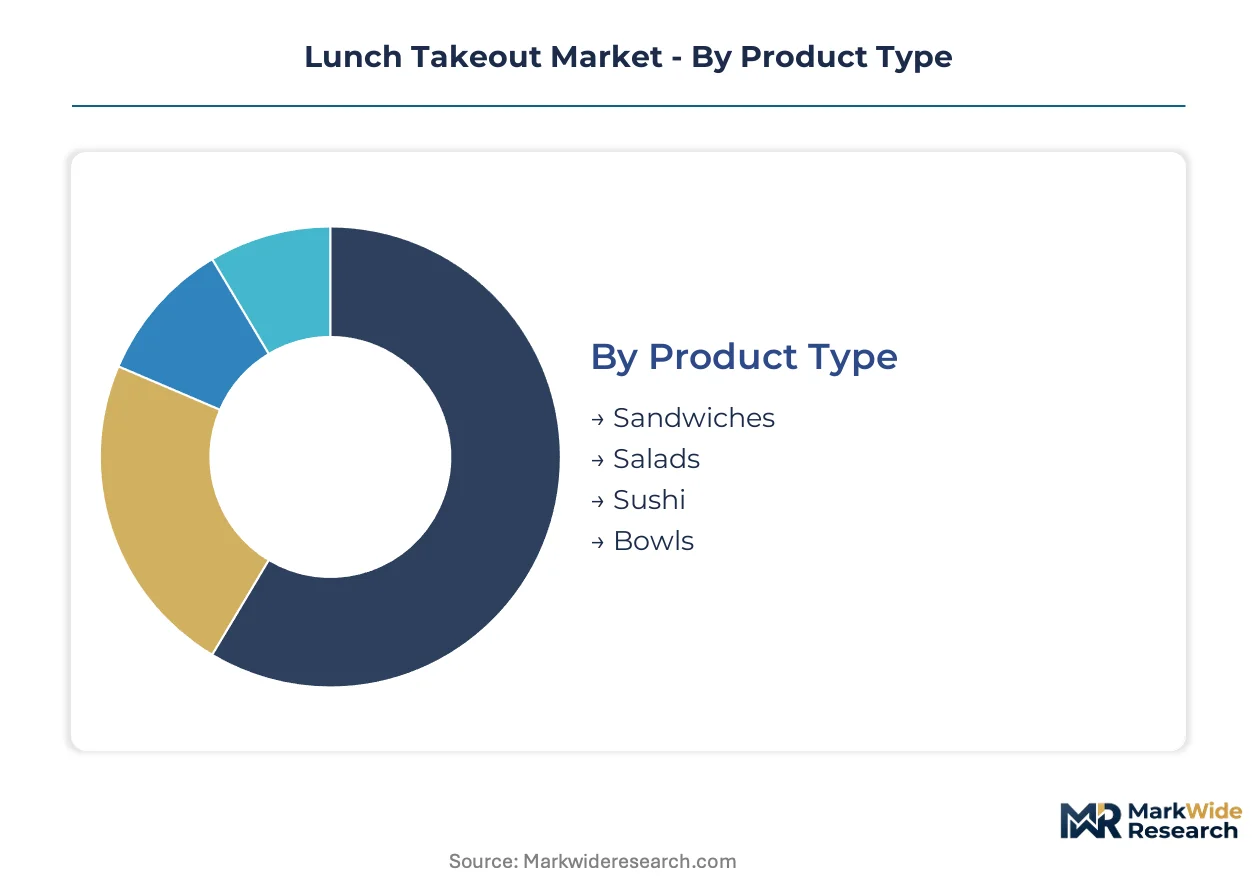
Segmentation in the lunch takeout market reveals how purchasing behavior fragments across convenience preferences, dietary priorities, and corporate procurement protocols. Understanding these divides enables operators to configure kitchen capacity, packaging specifications, and delivery radius investments against addressable demand pools.
Product Type:
Product type captures the core format of prepared meals, determining production equipment requirements, spoilage windows, and margin architecture across operator kitchens.
- Sandwiches:Cold and hot formats built on bread, wrap, or roll substrates with protein and vegetable layering. Corporate catering contracts in dense United States metropolitan zones sustain high-volume throughput during weekday lunch windows.
- Bowls:Grain or greens bases with customizable protein and topping configurations. Health-conscious consumers in Austin, Seattle, and Boston metropolitan corridors are concentrating demand for nutrient-dense, portable formats.
- Salads:Leaf-based or grain-based cold preparations requiring strict cold-chain maintenance. Limited spoilage tolerance constrains delivery radius extension.
- Sushi:Raw fish and rice combinations demanding precise temperature control and rapid consumption windows. Premium price tiers concentrate margin despite tighter operational constraints.
Sandwiches hold installed capacity. Bowls is rotating up the share rankings.
Distribution Channel:
Distribution channel maps how transaction flow splits between platform-mediated discovery and direct operator relationships, reshaping customer acquisition economics and order fulfillment complexity.
- Online Ordering:Direct-to-consumer digital transactions through operator-owned websites or apps. Large technology sector employers in Austin and Seattle are mandating platform-integrated systems for employee meal programs.
- Food Apps:Third-party aggregator platforms consolidating restaurant discovery and payment. DoorDash and Uber Eats capture dominant transaction share in urban United States corridors.
- Delivery Services:Courier-mediated fulfillment extending operator reach beyond walkable radius. Last-mile labor reclassification rulings from the Department of Labor threaten fee-structure disruption in California and New York.
- In-store Pickup:Customer-retrieved orders prepared for scheduled collection. Corporate catering contracts retain structural importance where bulk consolidation reduces per-unit logistics cost.
Food apps hold installed capacity. Online ordering is rotating up the share rankings.
Customer Type:
Customer type segments demand by institutional affiliation and dietary motivation, determining order size distribution, frequency patterns, and price sensitivity thresholds.
- Corporate Employees:Individual and group purchasers within employer-subsidized meal programs. Enterprise procurement departments are consolidating transaction flow through centralized dashboards that reduce administrative overhead.
- Health-conscious Consumers:Purchasers prioritizing nutritional transparency and ingredient provenance. This segment is expanding most quickly as municipal wellness initiatives reshape workplace foodservice specifications.
- Students:Price-sensitive purchasers concentrated near educational institutions with limited disposable income. High frequency, low ticket size patterns dominate.
- Families:Multi-person household purchasers seeking value-oriented combination meals. Weekend and evening demand concentration differs from weekday lunch patterns.
Corporate employees hold installed capacity. Health-conscious consumers is rotating up the share rankings.
Price Tier:
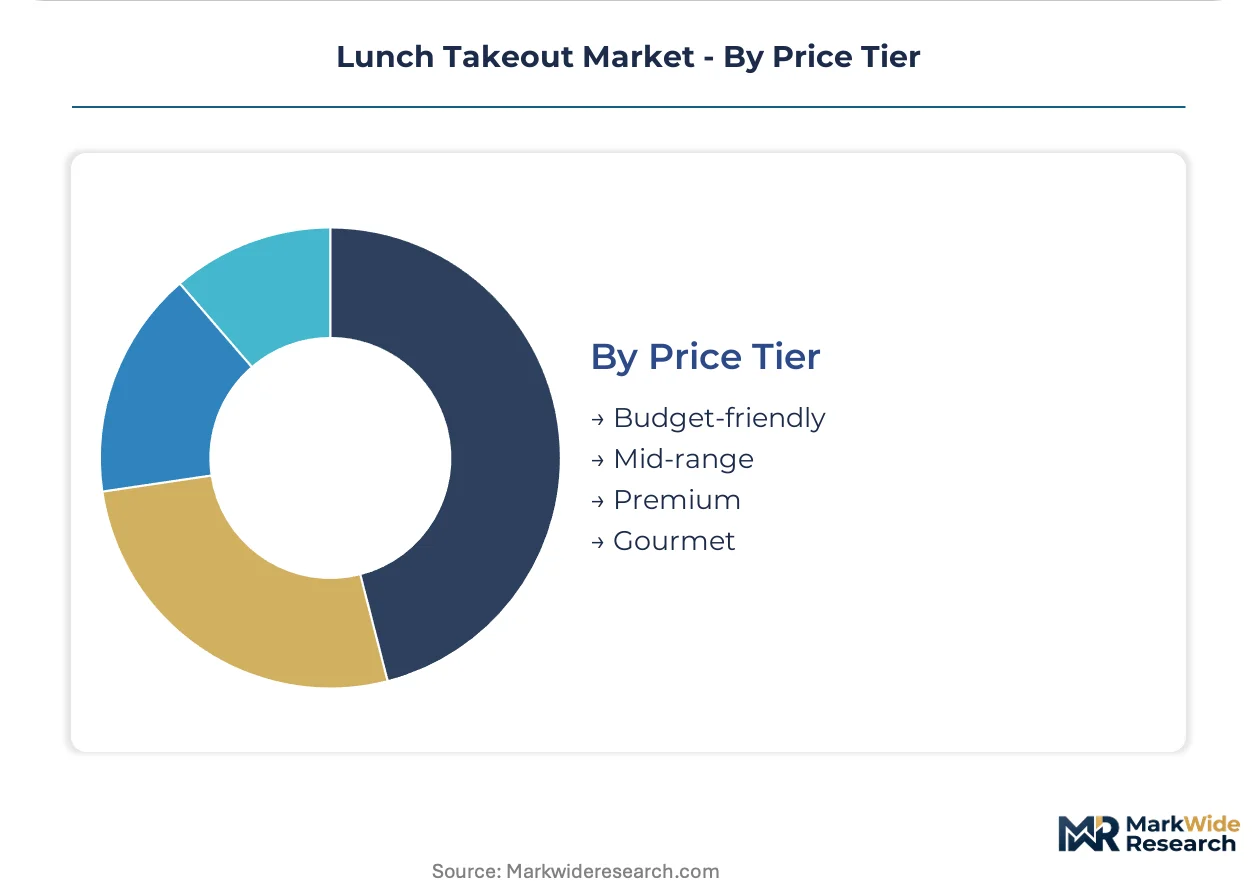
Price tier stratifies the market across willingness-to-pay thresholds, connecting ingredient quality signals, portion architecture, and brand positioning investments.
- Premium:Chef-driven preparations with protein-forward composition and elevated ingredient sourcing. Urban professional corridors in San Francisco and Washington D.C. sustain demand density.
- Mid-range:Balanced quality and convenience positioning for routine weekday lunch occasions. Chipotle Mexican Grill and comparable chains dominate this tier through assembly-line customization.
- Budget-friendly:Value-engineered formats prioritizing caloric density and speed. Limited margin pools constrain operator investment in packaging sustainability upgrades.
- Gourmet:Limited-availability preparations with seasonal menu rotation and provenance documentation. Smallest volume tier with highest per-unit margin capture.
Mid-range holds installed capacity. Premium is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate employees in dense metropolitan zones drive demand concentration, with technology sector employers and financial services firms generating the highest per-capita transaction frequencies during weekday lunch windows.
United States
Enterprise procurement departments in Austin, Seattle, and Boston mandate platform-integrated ordering systems for subsidized employee meal programs. The FDA's Food Safety Modernization Act traceability rules compress supply chain timelines for prepared meal operators. Urban corridors with 10,000+ employees per square mile sustain sub-20-minute delivery windows at profitable unit economics.
Canada
Corporate campus expansions in Toronto and Vancouver generate concentrated demand for premium bowl formats and health-conscious menu configurations. Health Canada monitors protein sourcing standards that shape supplier qualification for chain operators. The Greater Toronto Area anchors national volume through financial services and technology sector headquarters.
Germany
Industrial employer meal voucher programs sustain mid-range pricing tiers across manufacturing-heavy regions. The EFSA governs food contact material safety for packaging used in prepared meal transport. Berlin and Munich metropolitan zones concentrate demand for sustainable packaging alternatives under municipal circular economy mandates.
United Kingdom
Financial services employers in London retain structured corporate catering contracts alongside individual mobile ordering adoption. The Food Standards Agency enforces Hazard Analysis Critical Control Point protocols across commercial kitchen operations. The City of London and Canary Wharf districts generate peak density for premium sandwich and bowl formats during weekday windows.
Japan
Corporate bento culture persists alongside digital platform adoption in Tokyo and Osaka metropolitan corridors. The Ministry of Health, Labour and Welfare sets strict temperature maintenance standards for prepared meal distribution. The Tokyo Station and Marunouchi district concentrate premium demand for sushi and rice-based formats with rapid consumption windows.
Lunch Takeout Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a bifurcated structure. Platform aggregators capture transaction flow through demand-side density, while restaurant chains defend margin through kitchen throughput optimization and supply chain control. Three archetypes dominate: vertically integrated fast-casual operators, asset-light franchise networks, and third-party delivery platforms. Competitive moves concentrate on geographic densification and technology licensing for order orchestration.
Among platform-based aggregators, DoorDash and Uber Eats occupy positions defined by network effects and courier density. McDonald's Corporation exemplifies the franchise-network archetype through capital-efficient metropolitan expansion. Chipotle Mexican Grill sits within the vertically integrated tier, representing backward integration into fresh supply chains.
| Leading Market Players |
|---|
| McDonald's Corporation |
| DoorDash |
| Uber Eats |
| Domino's Pizza Inc. |
| Subway |
| Restaurant Brands International Inc. |
| Chipotle Mexican Grill Inc. |
| Panda Express |
| Grubhub |
| Others |
Supply & Pricing Matrix
Overcapacity in United States urban kitchen infrastructure is pressuring operators toward dynamic pricing models while compressing procurement leverage against protein suppliers. This utilization imbalance simultaneously erodes margin pools for independent delis and rewards chains with centralized sourcing contracts.
Pricing Analysis
Cost-plus contracts with USDA commodity indexation dominate procurement agreements for chicken and beef inputs across mid-range operators. Three-tier pricing structure across premium, standard, and economy levels segments customers by order frequency and corporate subsidy eligibility. Cost compression in the budget tier is intensifying because petroleum-derived packaging lacks biodegradable substitution at scale. Students exhibit highest price sensitivity, while technology sector employers absorbing subsidized meal allowances show lowest elasticity.
Supply Chain Analysis
Upstream feedstock for prepared proteins draws from United States, Brazil, and Canada poultry operations, with grain inputs sourced from Midwest agricultural corridors. Cold-chain packaging materials hinge on petroleum derivatives and imported fiber-based alternatives. Single-source vulnerability concentrates in last-mile courier networks where DoorDash and Uber Eats control urban density corridors. Distribution runs through platform aggregators for individual transactions and direct-operator relationships for corporate catering contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is widening as individual mobile ordering displaces group catering coordinators, creating niche openings for specialized bowl operators and sustainable packaging innovators.
For Market Incumbents: Build data moats through AI-driven demand forecasting trained on corporate calendar patterns and weather signals. Consolidate suburban corridor presence in secondary metropolitan rings with 5,000-8,000 employees per square mile before premium competitors establish density. Threat from delivery-app labor reclassification in California and New York demands proactive compliance infrastructure investment. Vertical integration into fresh supply chains protects margin against USDA commodity volatility. For New Entrants and Emerging Players: Pursue health-conscious consumer segments in Austin, Seattle, and Boston where nutrient-dense bowl formats show fastest rotation. Target suburban corridors with reusable container logistics partnerships ahead of municipal mandate expansion. White-space exists in corporate cafeteria replacement models where HR departments seek subsidized individual allowance platforms. Go-to-market through enterprise procurement dashboards bypasses consumer acquisition costs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-enabled kitchen automation as robotic assembly retrofits extend payback periods. Long-term viability favors operators with established circular logistics partnerships and cold-chain infrastructure ownership. Acquisition targets should demonstrate platform-integrated ordering systems with enterprise procurement penetration. Signal to watch is Department of Labor rulings on delivery-app worker status across California, New York, and Illinois.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Upgrade | FSMA Rule 204 compliance extends delivery radius while reducing spoilage loss. |
| AI-Driven Demand Forecasting | Machine learning models reduce pre-production waste for urban kitchen operators. |
| Reusable Container Logistics | Seattle and San Francisco municipal mandates favor circular supply partnerships. |
| Enterprise Procurement Integration | Platform-connected dashboards capture subsidized technology sector meal allowances. |
| Suburban Corridor Expansion | Secondary metropolitan rings with 5,000-8,000 employees per square mile remain underserved. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with restaurant chain procurement directors, third-party delivery platform operations leads, corporate cafeteria managers, and municipal health department inspectors; and secondary validation through FDA FSMA filings, USDA commodity price databases, state health inspection records, and SEC 10-K disclosures from publicly traded operators. Bottom-up restaurant unit economics triangulated against top-down market size estimates derived from transaction volume proxies.
Forecast inputs considered product type segmentation across sandwiches, bowls, salads, and sushi; distribution channel splits between platform aggregators and direct ordering; and customer archetypes from corporate employees to health-conscious consumers. CAGRs were computed from historical transaction velocity trends projected across the analysis window. Industry-specific inputs included urban employee density thresholds and cold-chain infrastructure penetration rates.
Sensitivities concentrate around Department of Labor delivery-app labor reclassification rulings, USDA protein commodity price volatility, and municipal packaging mandate implementation timelines. Forecasts reflect documented assumptions about technology sector employer subsidy retention and urban density migration patterns. Cross-checking against state health department inspection grade distributions and DoorDash merchant concentration disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food & Beverage in Asia Market
Food Service
Ship Catering Service Market
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Air Fryer Meal Kits Market
Food Service
Popcorn Making Cart Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
West Africa Food Services Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
Europe Inflight Catering Market
Food Service
North America Online Grocery Delivery Market
Food Service
Global Combi Ovens Market