
 Global Combi Ovens Market | 2026-2036
Global Combi Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Global Combi Ovens Market Analysis
Multi-source component procurement is expanding across the combi oven supply chain as manufacturers diversify away from single-source dependency for control systems and heating elements. RATIONAL leverages in-house production of its patented cooking intelligence software to sustain margin control. Electrolux Professional competes through broad geographic manufacturing footprints across multiple continents. Middleby anchors its position via specialized brands serving distinct price tiers and kitchen formats.
Combi ovens integrate convection heat, steam injection, and programmable control logic within a single chamber, typically operating between 30°C and 300°C to execute roasting, baking, steaming, and regeneration cycles. The equipment serves commercial kitchens requiring volume flexibility, energy recovery, and HACCP-compliant documentation. Electric units dominate installed base across European foodservice operations where grid infrastructure supports high-load kitchen equipment. Stand-alone configurations capture the largest revenue pool among installation types due to retrofit demand in existing kitchen layouts. Large-capacity models concentrate margin contribution through premium pricing tied to throughput guarantees and connected service subscriptions.
CE marking under the EU Machinery Directive governs safety compliance for units sold across European member states, while the EPA ENERGY STAR program in the United States shapes procurement specifications for institutional buyers seeking operating cost reduction. The EU F-Gas Regulation progressively restricts hydrofluorocarbon use in refrigeration-dependent holding cabinets paired with combi systems. Stakeholders must monitor evolving carbon border adjustment mechanisms and local content requirements as these frameworks increasingly determine competitive access across major national markets.
Market Dynamics
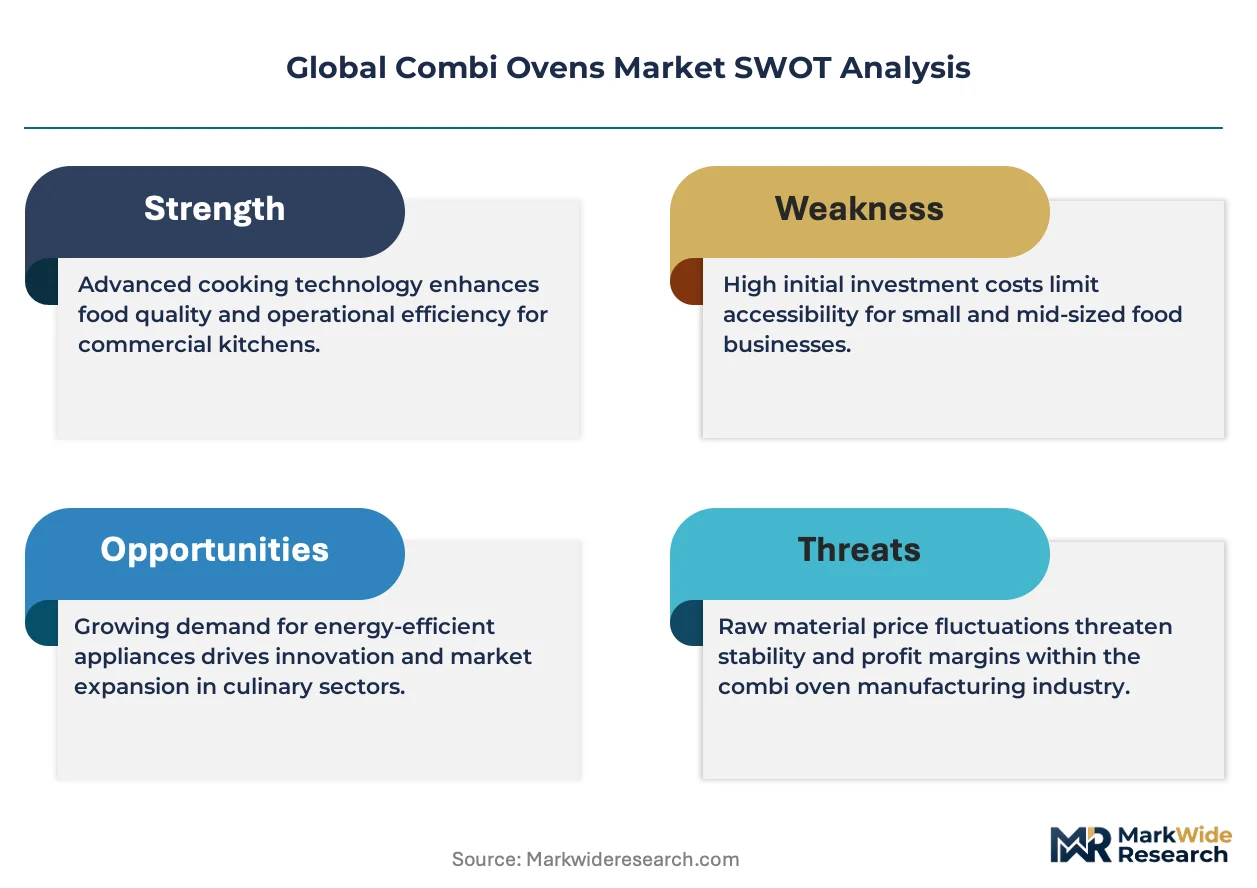
Energy efficiency mandates across European member states are forcing accelerated equipment replacement cycles as commercial kitchens face compliance deadlines under the EU Ecodesign Directive and escalating carbon border adjustment exposure.
Growth Catalysts
- Institutional Foodservice Modernization:Hospital and school kitchen operators in Germany are retiring steam-only equipment in favor of multi-function units that reduce footprint and labor hours.
- F-Gas Phase-Down:The EU F-Gas Regulation progressively restricts hydrofluorocarbon refrigerants in holding cabinets paired with combi systems, creating pull-through demand for integrated replacement platforms.
- Connected Service Subscriptions:Cloud-based cooking intelligence platforms enable remote diagnostics and recipe management, locking in recurring revenue streams for equipment vendors.
Market Restraints
- Stainless Steel Input Volatility:Chamber fabrication depends on nickel-alloy grades subject to price swings tied to Indonesian and Philippine ore export policies.
- Control System Concentration:Proprietary cooking logic software remains concentrated among German and Swiss automation specialists, creating single-source vulnerability for second-tier assemblers.
- Grid Infrastructure Limits:Electric unit penetration in Southern Europe faces headwinds from aging distribution networks unable to support high-load kitchen equipment without costly facility upgrades.
Strategic Opportunities
- India Foodservice Formalization:Quick-service restaurant chains in Mumbai and Bangalore are adopting Western-format kitchen layouts, opening first-mover positioning for mid-capacity electric models.
- Carbon Border Adjustment Arbitrage:Manufacturers with EU-based final assembly and local content certification can defend margin position against imported units facing embedded emissions tariffs.
- Convection-Steam Convergence:Hybrid cooking platforms integrating sous-vide precision with high-volume roasting cycles are capturing premium positioning in fine-dining commissary operations.
Industry Challenges
- Mechatronics Talent Scarcity:Integration of thermal engineering with programmable logic control requires cross-functional technicians in short supply across industrial regions.
- CE Marking Timeline Compression:Evolving EU Machinery Directive interpretations extend type-approval durations, delaying product launches and freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Combi Ovens Market |
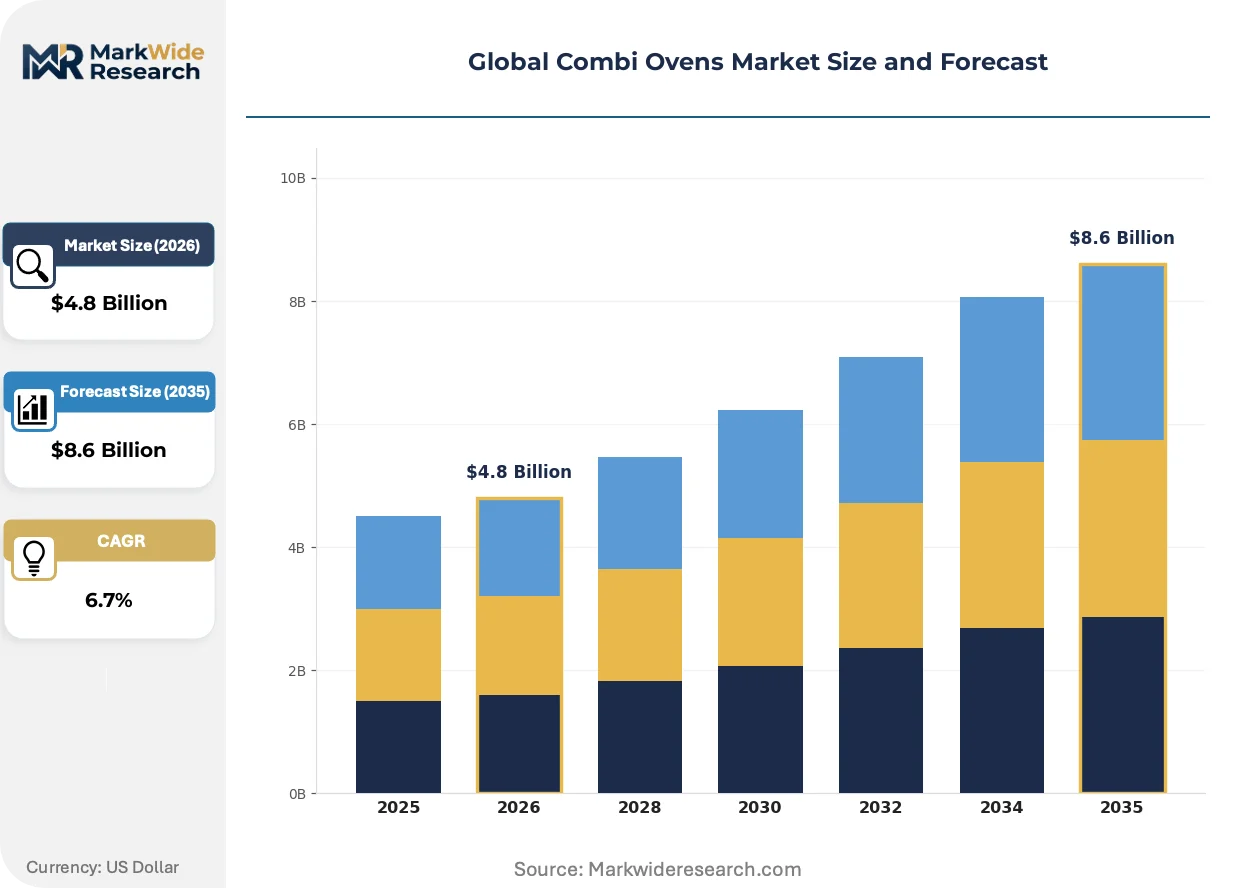
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Steam, Wood-fired End User: Restaurants, Cafes, Catering Services, Bakeries Installation Type: Built-in, Stand-alone, Modular, Portable Capacity: Small, Medium, Large, Extra Large |
| Companies Covered | Alto-Shaam, Welbilt, RATIONAL, Retigo, Lainox, Electrolux Professional, Middleby, Convotherm, UNOX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Combi Ovens Market Emerging Trajectories
Intelligent cooking platforms are displacing manual intervention across commercial kitchen workflows, with sensor-driven automation and predictive maintenance reshaping both equipment specifications and vendor business models.
Self-learning cooking intelligence is expanding into high-throughput catering operations by automatically adjusting humidity and airflow profiles based on probe feedback and load sensors. Hotel banquet kitchens in France and Spain are deploying these systems to reduce skilled labor dependency during peak service windows. The technology is expanding into smaller footprint formats previously served by conventional convection ovens, compressing the addressable market for single-function equipment.
The EU F-Gas Regulation is tightening refrigerant containment standards for holding cabinets and blast chillers paired with combi oven lines, forcing redesign of sealed system architectures. Manufacturers serving institutional buyers must now certify lifecycle leakage rates below specified thresholds to maintain CE marking validity. German and Austrian hospital foodservice directors are prioritizing compliant integrated systems to avoid procurement disqualification under public tender rules.
Cloud-native equipment monitoring is unbundling traditional service contracts as buyers demand usage-based maintenance pricing tied to actual operating hours. Restaurant groups in the United Kingdom are negotiating performance guarantees covering energy consumption and uptime rather than fixed annual service fees. This shift concentrates vendor risk on reliability engineering while transferring operational optimization accountability to equipment suppliers.
Global Combi Ovens Market Segmentation
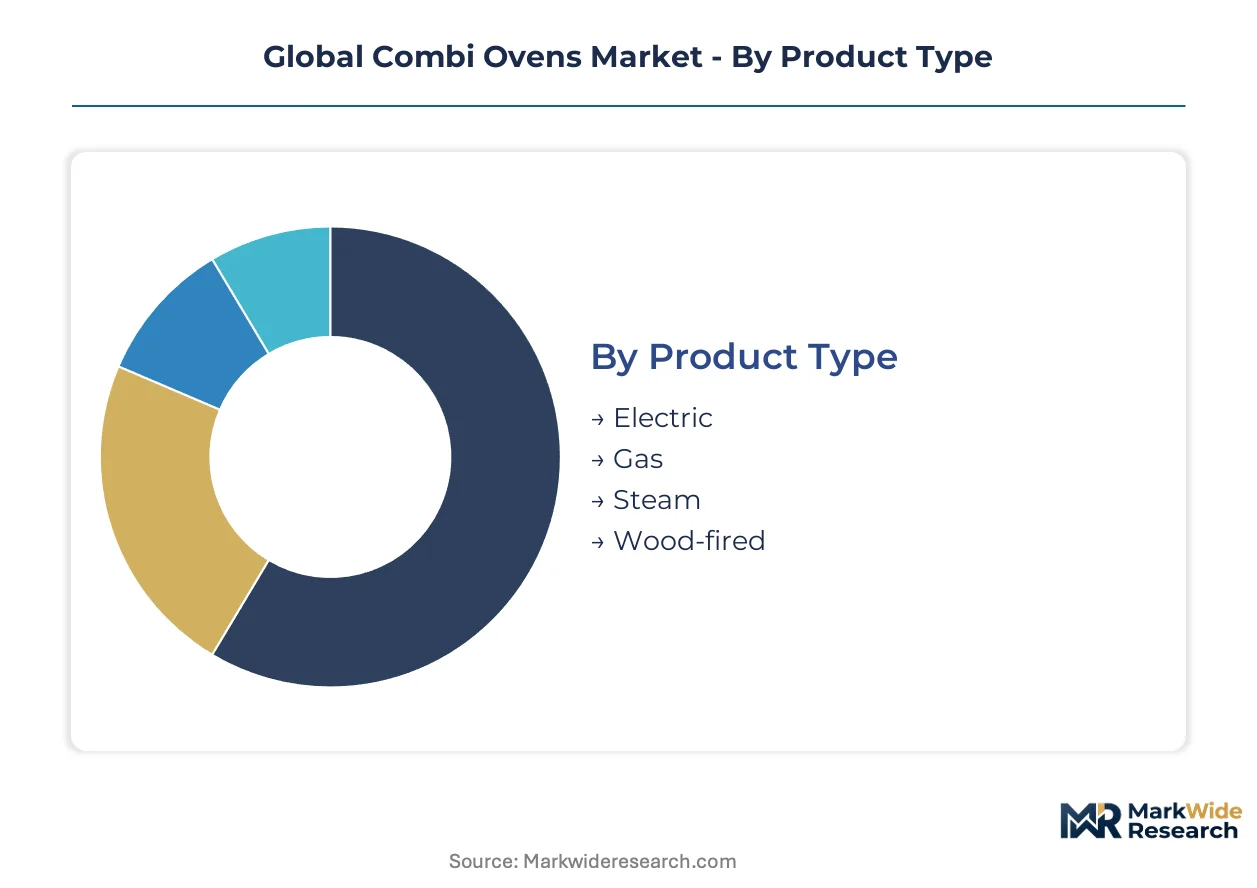
Combi oven purchasing decisions diverge sharply across kitchen formats, with energy infrastructure, throughput requirements, and real estate constraints creating distinct buyer profiles. Equipment specifications must align with operational workflows rather than generic performance benchmarks.
Product Type:
Buyer differentiation hinges on utility availability and regulatory pressure rather than cooking preference alone.
- Electric:Grid-connected kitchens in Germany, France, and the Netherlands specify these units to meet EU Ecodesign Directive efficiency mandates. German hospital foodservice directors prioritize electric models for their compatibility with building energy management systems and lower carbon intensity under national grid decarbonization targets.
- Gas:Natural gas infrastructure in older Italian and Spanish commercial buildings sustains demand where electrical panel upgrades prove cost-prohibitive. Operators in Milan and Barcelona retain gas units for high-heat roasting cycles that electric resistive elements struggle to replicate at equivalent operating cost.
- Steam:Central steam plant connections in institutional campuses and cruise ship galleys drive specification. The segment serves buyers with captive boiler infrastructure seeking to eliminate onboard combustion.
- Wood-fired:Premium positioning in artisan bakery and specialty restaurant segments emphasizes flavor differentiation over throughput. Italian and Portuguese traditional bread producers specify these for certified origin product lines.
Volume sits with Electric; growth tilts toward Steam as institutional buyers retire dedicated boiler systems.
End User:
Operational scale and menu complexity separate buyers more than cuisine category.
- Restaurants:Full-service operators in Paris and London deploy combi ovens for protein finishing and vegetable roasting within tight line-cook stations. The segment demands rapid heat recovery and compact footprints for open-kitchen layouts.
- Catering Services:High-volume banquet and event operators in Dubai and Singapore specify large-capacity units with regeneration cycles for pre-cooked protein holding. HACCP documentation capabilities rank above cooking precision in procurement scoring.
- Cafes:Limited-menu operators in Australian urban centers favor countertop formats for pastry finishing and sandwich warming. The segment tolerates reduced functionality in exchange for capital efficiency and minimal ventilation requirements.
- Bakeries:Artisan producers in Copenhagen and Vienna prioritize steam injection precision for crust development in sourdough and Viennoiserie. Temperature uniformity across multiple rack positions determines vendor selection.
Revenue concentrates in Restaurants; Catering Services expand most quickly as contract foodservice consolidates across Middle Eastern and Southeast Asian markets.
Installation Type:
Real estate constraints and kitchen lifecycle stage dictate configuration choice.
- Stand-alone:Freestanding units dominate retrofit installations in existing European hotel kitchens where structural modifications face heritage preservation restrictions. German and Austrian operators favor these for flexibility during renovation cycles.
- Built-in:New-construction commercial kitchens in Saudi Arabia and the UAE specify custom-integrated configurations for seamless front-of-house sightlines. The segment commands premium pricing for finishing and panel coordination.
- Modular:Central commissary operators in Brazil and Mexico adopt stackable configurations for volume scaling without footprint expansion. The format supports phased capital deployment as production volumes ramp.
- Portable:Temporary kitchen operators and outdoor catering specialists in the United States specify caster-mounted units for rapid deployment. NSF certification and propane conversion capability determine vendor qualification.
Installed base skews toward Stand-alone; Built-in gains share fastest in Gulf Cooperation Council hospitality developments.
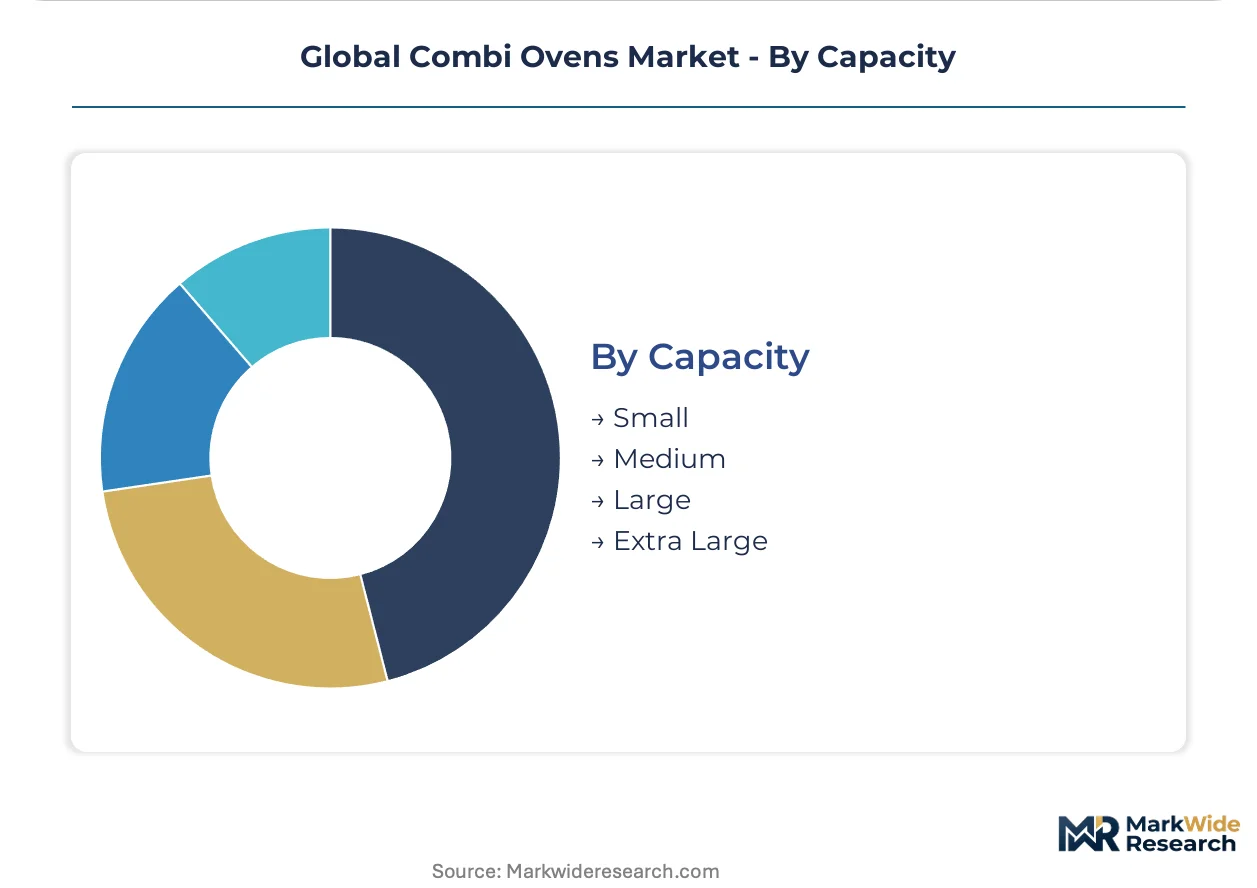
Capacity:
Throughput guarantees and labor substitution economics scale non-linearly with chamber size.
- Large:Twenty-rack and greater configurations serve airline catering facilities in Frankfurt and Amsterdam with single-batch processing for thousands of meals. The segment justifies premium pricing through throughput-based service contracts.
- Medium:Six-to-ten rack units dominate independent restaurant and hotel kitchen specifications in Tokyo and Seoul. The format balances batch flexibility with space efficiency in high-rent urban locations.
- Small:Two-to-four rack countertop models penetrate cafe and quick-service formats in Mumbai and Jakarta where kitchen square footage commands severe constraint. Ventless and hoodless certification expands addressable placement.
- Extra Large:Custom-engineered tunnel and batch configurations serve military and prison foodservice operations in the United States and United Kingdom with dedicated procurement channels and extended service intervals.
Margin contribution peaks with Large; Small climbs fastest as Asia-Pacific foodservice formalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from Indonesian and Philippine ore deposits anchors combi oven fabrication economics across major manufacturing geographies. Chamber fabrication costs fluctuate with nickel-alloy grade availability, compressing margins for European fabricators dependent on Asian raw material flows. Procurement managers in Frankfurt and Singapore monitor ore export policy shifts to hedge input volatility.
Germany
Hospital and school kitchen operators in Bavaria and North Rhine-Westphalia are retiring steam-only equipment for multi-function units that reduce labor hours and footprint. The EU Ecodesign Directive enforces accelerated replacement cycles for commercial cooking appliances with compliance deadlines tightening through 2027. RATIONAL and Convotherm anchor production clusters in Landsberg and Wiesbaden, where captive software development sustains margin control against Asian competitors.
United States
Institutional buyers in Chicago and Atlanta specify EPA ENERGY STAR-certified units to secure operating cost reductions under federal procurement guidelines. The EPA program shapes specifications for school districts and hospital systems seeking utility rebate qualification. Middleby's specialized brand portfolio serves distinct price tiers across quick-service and fine-dining formats from manufacturing footprints in Ohio and Texas.
Japan
Compact kitchen formats in Tokyo and Osaka drive demand for medium-capacity electric models compatible with building energy management systems. METI efficiency standards for commercial kitchen equipment tighten test protocols for thermal recovery and standby power consumption. Electrolux Professional operates assembly presence in Chubu to serve regional hospitality chains with localized control interfaces.
India
Quick-service restaurant chains in Mumbai and Bangalore are adopting Western-format kitchen layouts, opening positioning for mid-capacity electric models in formalizing foodservice. BIS certification requirements for commercial cooking equipment create compliance barriers for unbranded imports. UNOX and Lainox distributors concentrate inventory in Maharashtra and Karnataka to capture first-mover advantage among expanding QSR operators.
United Arab Emirates
Gulf Cooperation Council hospitality developments in Dubai and Abu Dhabi specify built-in configurations for seamless front-of-house sightlines in luxury hotel constructions. MOHAP food safety regulations mandate HACCP documentation capabilities for commercial kitchen equipment in healthcare and institutional catering. Alto-Shaam and Welbilt serve project developers through Dubai-based specification teams coordinating with Saudi and Qatari rollout timelines.
Global Combi Ovens Market Vendor Landscape
Global majors compete with regional champions across control system architecture and service network density. The vendor base stratifies into three tiers: integrated manufacturers with captive software development, assembly specialists dependent on third-party automation, and regional fabricators serving price-sensitive replacement demand. Strategic moves concentrate on geographic manufacturing footprint expansion and cloud-native service platform development to lock in recurring revenue streams.
Among German-integrated manufacturers, RATIONAL AG exemplifies the software-captive archetype through in-house production of cooking intelligence platforms, while Convotherm GmbH occupies a parallel position in specialized heating system engineering. Middleby Corporation represents the multi-brand portfolio approach, anchoring distinct price tier coverage through specialized subsidiaries rather than unified product lines. These three patterns—captive software control, heating system specialization, and brand-tier segmentation—define competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Alto-Shaam |
| Welbilt |
| RATIONAL |
| Retigo |
| Lainox |
| Electrolux Professional |
| Middleby |
| Convotherm |
| UNOX |
| Others |
Supply Flow & Price Mechanics
Institutional foodservice procurement programs in Germany and the United States anchor pricing power for combi oven manufacturers, with EPA ENERGY STAR certification and EU Ecodesign Directive compliance creating tiered qualification thresholds that segment vendors into bundled service and unbundled equipment-only channels. This buyer concentration enables premium capture for integrated manufacturers with captive software development, while assembly-dependent competitors face margin compression from input volatility and certification cost absorption.
Pricing Analysis
Extended warranty and connected service subscription bundling separates premium vendors from transactional equipment sellers, with cloud-native diagnostics and remote recipe management now standard inclusions for hospital and hotel procurement scoring. Pricing stratifies across premium, standard, and economy tiers based on control system sophistication and CE marking tier. Cost compression in mid-capacity electric segments is intensifying because Asian competitors are penetrating European markets with unbundled hardware offerings. Quick-service restaurant chains in India exhibit highest price sensitivity, while German hospital systems prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Ocean freight rate volatility from Asia to Europe and North America directly impacts landed costs for stainless steel chamber components and control system modules, compressing margins for fabricators without regional assembly presence. Manufacturing concentrates in Germany, Italy, and China, with chamber fabrication drawing from Indonesian and Philippine nickel-alloy feedstock. Single-source vulnerability in programmable logic controllers from German and Swiss automation specialists creates supply chain risk. Distribution runs through authorized dealer networks for specification-heavy institutional sales, while e-commerce channels serve replacement demand in fragmented foodservice operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Combi oven manufacturing capacity concentrates among German-integrated producers with captive software development, creating supply constraints that prop pricing power for qualified vendors against import competition facing carbon border adjustment exposure.
For Market Incumbents: Lock in recurring revenue streams by expanding cloud-native service platforms with usage-based maintenance pricing, while deepening backward integration into heating element production to offset nickel-alloy price volatility from Indonesian ore export policy shifts. RATIONAL and Convotherm anchor production clusters that emerging Asian competitors struggle to replicate without local content certification under tightening EU procurement rules. For New Entrants and Emerging Players: Enter via mid-capacity electric models targeting quick-service restaurant chains in Mumbai and Bangalore, where BIS certification requirements create compliance barriers for unbranded imports but leave positioning open for first-movers with Western-format kitchen expertise. Partner with established distributors in Maharashtra and Karnataka to bypass capital-intensive direct service network buildout. For Investors and Strategic Acquirers: The window for entry favors assembly specialists with regional manufacturing footprints and third-party automation partnerships, as control system concentration among German and Swiss vendors creates acquisition targets with distribution scale but technology gaps. Monitor CE marking timeline compression under evolving EU Machinery Directive interpretations as an inflection indicator for R&D amortization stress among second-tier assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Service Platform Development | Enables usage-based maintenance pricing for UK restaurant groups demanding performance guarantees. |
| Backward Integration into Heating Elements | Reduces nickel-alloy price exposure from Indonesian ore export policy volatility. |
| Regional Manufacturing Footprint Expansion | Secures local content certification against EU carbon border adjustment mechanisms. |
| CE Marking Compliance Investment | Maintains market access as EU Machinery Directive interpretations extend type-approval durations. |
| Quick-Service Restaurant Channel Partnership | Captures first-mover positioning in India's formalizing foodservice sector. |
Methodological Framework
Document review covered regulatory filings with the EPA and EU Ecodesign Directive compliance databases, complemented by interviews with hospital foodservice directors, commercial kitchen equipment procurement managers, and aftermarket service heads. Secondary validation drew from SEC 10-K filings, customs and trade data for stainless steel feedstock flows, and hospital procurement databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across the analysis window.
Segmented outputs across product type, end user, installation configuration, and capacity tier fed into analytical framework development over the projection horizon. CAGRs were derived from regression analysis against macroeconomic indicators and regulatory compliance timelines. Industry-specific forecast inputs included EU F-Gas Regulation phase-down schedules and grid infrastructure investment patterns in Southern Europe.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU carbon border adjustment implementation or abrupt Indonesian nickel ore export restrictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
A La Carte Market
Food Service
Stirrers Market
Food Service
Europe Vending Machine Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Commercial Restaurant Rangers Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Europe Food Away from Home Market
Food Service
Train Catering Service Market
Food Service
Restaurant Takeout Market
Food Service
Beverage Napkins Market
Food Service
Lunch Takeout Market
Food Service
Chained Consumer Foodservice Market
Food Service
Commercial Tandoor Oven Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Breakfast Takeout Market
Food Service
South Korea Foodservice Market