
 Centerfold Laminated Bags Market | 2026-2036
Centerfold Laminated Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Centerfold Laminated Bags Market Analytics
Polyethylene is consolidating its position as the dominant substrate in centerfold laminated construction, displacing heavier multi-layer alternatives in cost-sensitive applications. Pregis Innovative Packaging leverages vertical integration across film extrusion and converting to sustain margin control in North American supply chains. Strubl GmbH anchors European demand through specialized high-barrier configurations for sensitive food products. PPC Flexible Packaging competes on geographic breadth, operating converting assets across multiple U.S. manufacturing corridors.
Centerfold laminated bags are multi-ply flexible packaging structures manufactured by folding a single web along its longitudinal center and sealing the open edges, typically incorporating barrier layers of metalized film or coextruded polymers to achieve oxygen transmission rates below 0.1 cc per square meter per day. These constructions serve primarily to extend product freshness in moisture-sensitive and oxygen-critical applications across food, industrial, and consumer goods sectors. Gusseted bags command the largest volume share within product type classifications due to their cubic efficiency in palletization and retail shelf presentation. Stand-up pouches represent the fastest-expanding format as brand owners convert from rigid containers to flexible alternatives. Recyclable packaging types are capturing disproportionate investment attention as European and North American brand sustainability mandates tighten material specifications.
The U.S. Food and Drug Administration governs direct food-contact compliance for laminated film structures, while the EU REACH framework restricts certain adhesive and coating chemistries in multi-layer packaging bound for European consumer markets. California's SB 54 legislation and extended producer responsibility programs in multiple U.S. states are forcing converters to redesign legacy multi-material laminations toward mono-polymer or certified recyclable constructions. Stakeholders must monitor evolving state-level packaging laws and invest in compatible substrate platforms before compliance deadlines harden competitive access barriers.
Market Dynamics
Material transitions toward recyclable mono-polymer substrates are compressing legacy multi-layer supply chains as EU Green Deal mandates harden compliance deadlines across European converting operations.
Growth Catalysts
- EU Green Deal packaging waste directives:Germany's converting infrastructure is capturing disproportionate investment as brand sustainability commitments intersect with regulatory enforcement timelines.
- Food & Beverage shelf-life extension demand:Processors are specifying high-barrier laminated constructions for oxygen-critical applications requiring transmission rates below 0.1 cc per square meter per day.
- Stand-up pouch format conversion:Brand owners across North American retail channels are accelerating flexible packaging substitution for rigid containers in moisture-sensitive product categories.
Market Restraints
- Adhesive chemistry restrictions:EU REACH framework limitations on specific coating compounds are forcing reformulation of legacy lamination bonds.
- Multi-material separation complexity:Mechanical recycling infrastructure cannot process conventional metalized film laminations, creating end-of-life liability for converters.
- Rigid container residual preference:Premium food categories maintain glass and metal packaging for perceived quality differentiation.
Strategic Opportunities
- California SB 54 extended producer responsibility:State-level compliance deadlines are creating first-mover advantage for domestic converters with certified recyclable platforms.
- Industrial gusseted bag underpenetration:Construction chemicals and agricultural inputs in Midwestern U.S. manufacturing corridors remain served by conventional woven alternatives.
- Digital printing convergence with short-run converting:Brand localization strategies are compressing minimum order quantities and rewarding agile production assets.
Industry Challenges
- Mono-polymer barrier performance gaps:Replacing metalized layers with coextruded alternatives requires extended R&D validation cycles with food safety regulators.
- Legacy equipment reconfiguration:Heat-sealing parameters for recyclable substrates demand capital-intensive line modifications at established converting facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centerfold Laminated Bags Market |
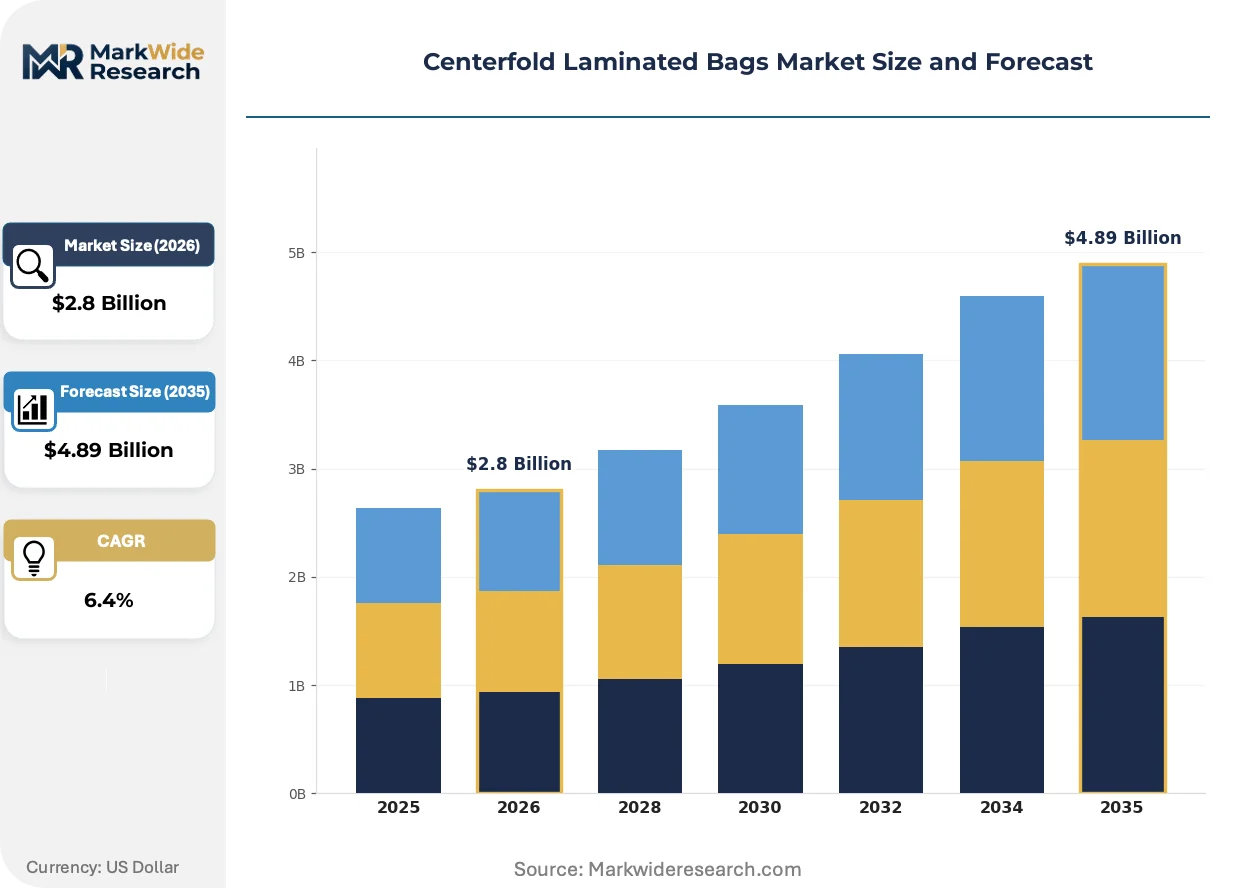
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Stand-Up Pouches, Roll Bags Material: Polyethylene, Polypropylene, Nylon, Vacuum Film End Use: Food & Beverage, Personal Care, Household Products, Industrial Packaging Type: Recyclable, Biodegradable, Resealable, Standard |
| Companies Covered | Pregis Innovative Packaging, PPC Flexible Packaging, Strubl GmbH, Griff Paper and Film, Brent Wood Plastics, Integrated Packaging Films, Apple Converting, QIS Packaging, International Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centerfold Laminated Bags Market Evolving Landscape
Active developments across substrate chemistry, regulatory compliance architecture, and procurement models are compressing traditional competitive moats in flexible packaging supply chains.
Polyethylene-rich coextrusion systems are unifying barrier and structural functions previously served by discrete metalized layers. Food processors in refrigerated dairy and snack categories are specifying these constructions for store-dropoff recyclable certification. The technology is unifying what were separate supply chains for barrier film and sealant web into single-source procurement relationships with integrated extrusion-converting operations.
California's SB 54 extended producer responsibility legislation is mandating 30% post-consumer recycled content thresholds and fund contributions based on packaging recyclability classifications. Converters operating in the state are redesigning legacy multi-material laminations toward mono-polymer constructions ahead of 2032 compliance deadlines. The regulatory pressure is most acute for mid-size brands lacking in-house packaging engineering resources to navigate certification complexity.
Brand owners are consolidating supplier relationships around converters with integrated substrate production and regional distribution networks. Direct procurement from extrusion-capable facilities is displacing layered distributor relationships in the North American market. This concentration is most visible in snack food and pet care verticals where sustainability scorecard requirements now precede price negotiations in vendor selection criteria.
Centerfold Laminated Bags Market Segmentation
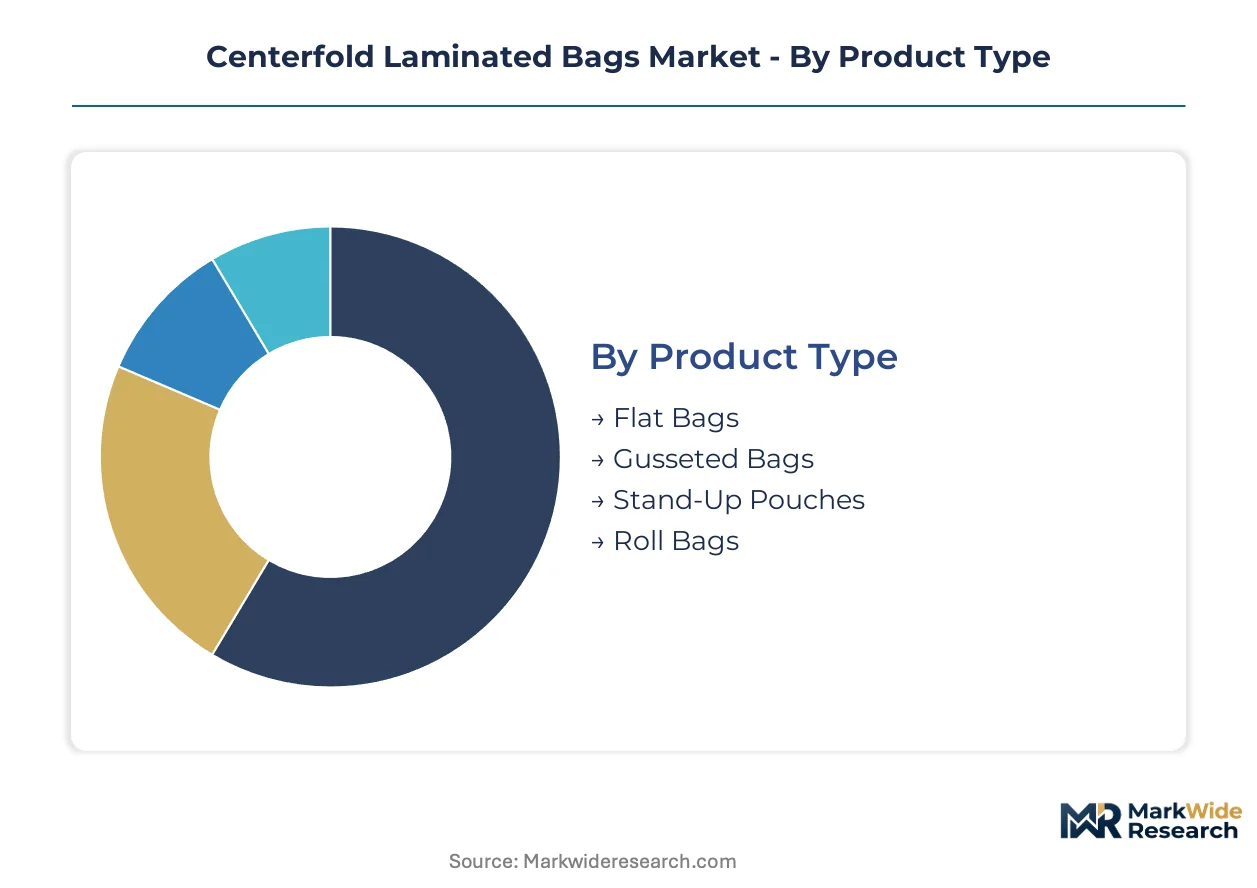
Centerfold laminated bag specifications diverge sharply across certification regimes. FDA compliance governs food-contact substrates in the United States, while EU REACH restricts adhesive chemistries in European multi-layer constructions. California SB 54 mandates recyclable certification thresholds that reshape procurement priorities by packaging category.
Product Type:
Certification burden varies by structural complexity — stand-up pouches face extended validation cycles for zipper seal integrity, while flat bags navigate simpler compliance pathways.
- Gusseted Bags:Multi-panel side folds expand cubic capacity for palletization efficiency. German food processors specify these configurations for extended shelf-life dairy applications under EU Green Deal waste reduction timelines.
- Stand-Up Pouches:Bottom gusset and vertical orientation replace rigid containers in retail environments. North American pet care brands are converting volume to this format fastest as sustainability scorecards prioritize lightweighting metrics.
- Flat Bags:Simple two-seam construction minimizes material usage for cost-sensitive industrial applications.
- Roll Bags:Continuous web format serves automated filling lines in high-volume snack manufacturing corridors.
Leading the category by volume: Gusseted Bags. Growing fastest: Stand-Up Pouches.
Material:
Substrate selection determines barrier performance tiers and recyclability certification eligibility under emerging extended producer responsibility frameworks.
- Polyethylene:Dominant coextruded construction unifies sealant and structural layers in mono-polymer configurations. U.S. converters with captive extrusion capacity are capturing procurement consolidation as brand owners seek store-dropoff recyclable certification.
- Polypropylene:Higher temperature resistance suits hot-fill and retort applications. European demand concentrates in Italy and Spain where pasta and prepared meal processors specify oriented polypropylene for clarity and moisture barrier.
- Nylon:Oxygen barrier properties serve vacuum packaging for protein products requiring extended distribution cycles.
- Vacuum Film:Multi-layer coextrusion achieves sub-0.1 cc oxygen transmission rates for sensitive food categories.
Highest volume concentration: Polyethylene. Steepest expansion trajectory: Vacuum Film in premium protein applications.
End Use:
Customer procurement sophistication separates segments — multinational food processors impose sustainability scorecards that mid-size industrial buyers have not yet adopted.
- Food & Beverage:Oxygen-critical applications dominate specification intensity. German dairy and French cheese processors are specifying high-barrier laminated constructions with metalized or coextruded layers to achieve extended refrigerated shelf life under EU packaging waste directives.
- Personal Care:Premium positioning drives cosmetic and skincare brands toward matte-finish laminations with tactile differentiation. California-based clean beauty companies are mandating recyclable mono-polymer substrates ahead of SB 54 compliance deadlines.
- Household Products:Concentrated detergents and cleaning formulations require chemical resistance in multi-ply constructions.
- Industrial:Construction chemicals and agricultural inputs in Midwestern U.S. manufacturing corridors remain underpenetrated by laminated alternatives versus conventional woven packaging.
Dominant procurement volume: Food & Beverage. Fastest sustainability-driven conversion: Personal Care.
Packaging Type:
Regulatory compliance timelines now precede price negotiations in vendor selection, with certification status determining market access eligibility.
- Recyclable:Mono-polymer or compatible multi-layer constructions qualify for store-dropoff or curbside collection streams. California SB 54 mandates 30% post-consumer recycled content thresholds by 2032, forcing converters to redesign legacy laminations and secure certification through How2Recycle or equivalent programs.
- Biodegradable:Industrial composting certification serves niche applications in European markets with established organic waste infrastructure. French and Italian regulatory frameworks provide clearer certification pathways than fragmented U.S. state-level standards.
- Resealable:Zipper and press-to-close mechanisms extend consumer convenience in snack and pet care categories.
- Standard:Conventional multi-material laminations without sustainability certification face shrinking procurement pools.
Fastest certification adoption: Recyclable. Steepest volume decline: Standard non-certified constructions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the German state of North Rhine-Westphalia concentrate converting capacity near the Benelux border. EU Green Deal implementation timelines accelerate substrate transitions in these clusters.
United States
Food processors in Wisconsin and California specify high-barrier laminated constructions for extended shelf-life dairy and snack applications. California SB 54 mandates 30% post-consumer recycled content thresholds by 2032. Midwestern manufacturing corridors around Chicago sustain demand for industrial gusseted bag formats serving construction chemical distributors.
Germany
Brand sustainability commitments from dairy and cheese processors intersect with REACH adhesive chemistry restrictions in Baden-Württemberg converting clusters. EU packaging waste directives enforce recyclability certification through How2Recycle-equivalent programs. The Rhine-Main region around Frankfurt anchors specialized high-barrier production for oxygen-critical food categories.
France
Prepared meal processors in the Île-de-France region specify oriented polypropylene laminations for retort applications. National organic waste infrastructure supports industrial composting certification pathways for biodegradable alternatives. Lyon-based converters supply matte-finish constructions to cosmetic brands under clean beauty procurement mandates.
China
Snack food manufacturers in the Yangtze River Delta convert volume from rigid containers to stand-up pouch formats. SAMR food-contact compliance governs substrate specifications for export-bound production. Zhejiang province extrusion operations supply coextruded polyethylene constructions to domestic brand owners prioritizing cost efficiency.
Italy
Pasta and prepared meal processors in Emilia-Romagna specify polypropylene-rich laminations for moisture barrier and optical clarity. Extended producer responsibility frameworks in the EU drive redesign of legacy multi-material constructions. Bologna-area converting facilities serve Mediterranean export markets with certified recyclable substrate platforms.
Centerfold Laminated Bags Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated extrusion-converting operations capturing procurement consolidation from sustainability-driven brand owners. The vendor base organizes around three strategic archetypes: captive film producers with downstream bag fabrication, independent converters sourcing substrate from merchant markets, and regional specialists serving single end-use verticals. Dominant competitive moves include backward integration into film extrusion capacity and geographic expansion through distribution network densification.
Among North American integrated producers, Pregis Innovative Packaging and PPC Flexible Packaging exemplify the captive-extrusion archetype, controlling substrate supply chains against merchant-market volatility. Strubl GmbH anchors European positioning through specialized high-barrier configurations, representing the regional-specialist model concentrated in sensitive food applications. These three entities occupy distinct competitive terrain: scale-driven integration, geographic breadth across multiple U.S. manufacturing corridors, and technical specialization for oxygen-critical specifications respectively.
| Leading Market Players |
|---|
| Pregis Innovative Packaging |
| PPC Flexible Packaging |
| Strubl GmbH |
| Griff Paper and Film |
| Brent Wood Plastics |
| Integrated Packaging Films |
| Apple Converting |
| QIS Packaging |
| International Plastics |
| Others |
Value Network & Pricing Analysis
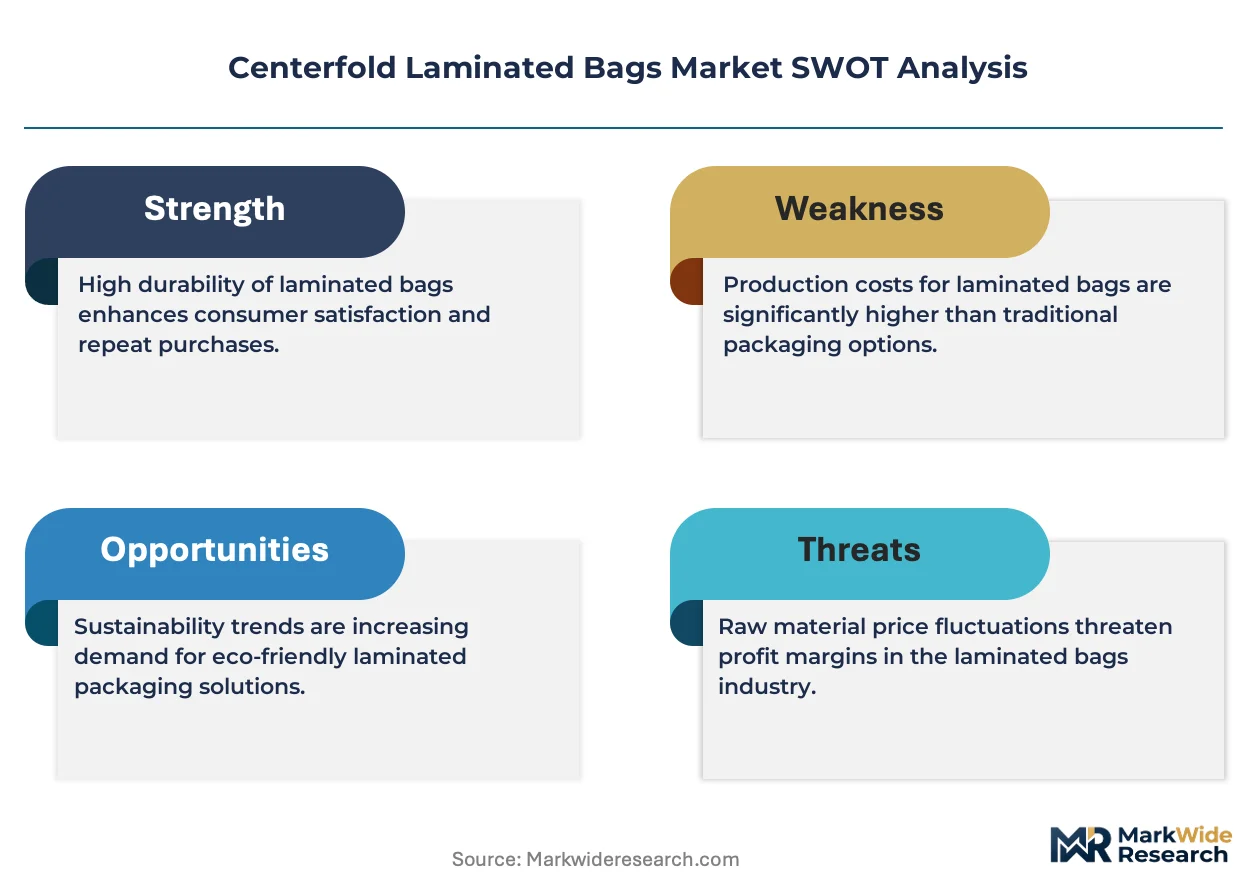
Brand mandates for store-dropoff recyclable certification are forcing substrate redesigns that compress converter margins and reward backward integration into captive polyethylene extrusion. California SB 54 compliance deadlines and EU Green Deal waste directives are accelerating procurement consolidation around integrated producers with certified mono-polymer platforms.
Pricing Analysis
Short lead-time premiums apply to certified recyclable constructions as brand owners compress product development cycles ahead of regulatory deadlines. Three-tier pricing structure across premium, standard, and economy levels separates high-barrier metalized configurations from mono-polymer alternatives and conventional multi-material laminations. Cost compression in standard-grade constructions is intensifying because merchant-market substrate buyers face resin price volatility without upstream hedging. Mid-size food processors exhibit highest price sensitivity, while multinational brand owners prioritize sustainability scorecard compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with German extrusion operations supplying high-barrier film to EU converting clusters under REACH adhesive restrictions. Raw material flows draw from Saudi Arabian polyethylene feedstock, U.S. Gulf Coast resin production, and Belgian adhesive formulation facilities. Tariff exposure on imported substrate creates margin pressure for North American independent converters without captive extrusion. Distribution runs through direct procurement relationships with extrusion-capable facilities, displacing layered distributor networks in snack food and pet care verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in centerfold laminated bags is becoming a vertical-integration race as brand owners consolidate procurement around converters with captive substrate production and regional distribution networks.
For Market Incumbents: Anticipate margin compression from merchant-market resin volatility by securing backward integration into polyethylene extrusion capacity in Wisconsin or North Rhine-Westphalia clusters. Defend market position through early certification investment in How2Recycle-approved mono-polymer platforms ahead of California SB 54 enforcement timelines. For New Entrants and Emerging Players: Launch via digital printing convergence with short-run converting to capture brand localization strategies compressing minimum order quantities. Target underpenetrated industrial gusseted bag demand in Midwestern U.S. manufacturing corridors serving construction chemical distributors with cost-competitive polyethylene-rich alternatives to woven packaging. For Investors and Strategic Acquirers: Re-rating potential sits with mid-size converters possessing regional distribution density and recyclable certification progress given EU Green Deal implementation timelines. Long-term viability favors acquisition targets with demonstrated substrate redesign capabilities and established brand owner sustainability scorecard relationships. Monitor California SB 54 fund contribution schedules as inflection indicator for compliance-driven procurement consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Extrusion Capacity | Captive polyethylene supply insulates margins from resin price volatility in merchant markets. |
| Recyclable Certification Investment | How2Recycle approval unlocks procurement from California SB 54-compliant brand owners. |
| Digital Printing Platform Deployment | Short-run agility captures brand localization compressing minimum order quantities in snack verticals. |
| Geographic Expansion in Midwest Industrial Corridors | Proximity to construction chemical distributors addresses underpenetrated gusseted bag demand. |
| High-Barrier R&D Partnership | Metalized layer replacement with coextruded alternatives accelerates mono-polymer validation with FDA. |
Research Methodology
Independent corroboration across converter operations data, resin trade flow databases, and brand owner procurement specifications underwrites the qualitative findings. Primary interviews with film extrusion plant managers, flexible packaging procurement leads at multinational food processors, distribution channel partners, and regulatory compliance officers combined with secondary validation from FDA food-contact guidance documents, EU REACH substance restriction lists, California SB 54 implementation materials, and SEC 10-K filings from disclosed packaging suppliers. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Rate-of-change decomposition separates volume growth into format conversion from rigid containers, substrate transition toward mono-polymer constructions, and end-use expansion across food, personal care, and industrial categories. Segmentation dimensions modeled include product type, material substrate, end-use vertical, packaging certification status, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements across the analysis window. Industry-specific inputs incorporate EU Green Deal waste reduction targets and California extended producer responsibility fund schedules.
The model assumes a particular technology adoption path; alternative pathways for metalized film replacement with coextruded barrier layers would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement timelines, brand sustainability mandate adoption curves, and mechanical recycling infrastructure development. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Freezing Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Type-C Bulk Bags Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Global Bubble Lined Courier Bag Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Insulated Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Carry Bag Market
Bags and Containers
Child Resistant Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Loose-Fill Peanuts Market