
 Low Voltage Switchgear Market | 2026-2036
Low Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage Switchgear Market Analysis
Digital twin integration with switchgear design is reconfiguring how manufacturers validate thermal and electrical performance before physical prototyping. Siemens AG leverages its automation software portfolio to anchor digital lifecycle services alongside hardware sales. Schneider Electric sustains competitive density through deep specialization in smart distribution architectures for commercial buildings. ABB Ltd dominates medium-to-large industrial installations with integrated motor control centers tied to low voltage switchgear lines.
Low voltage switchgear encompasses electrical distribution equipment rated up to 1,000 volts AC or 1,500 volts DC, comprising metal-enclosed assemblies of circuit breakers, busbars, instruments and protective relays that receive power from transformers and distribute it to downstream loads with fault isolation capability. Circuit breakers represent the most technically intensive product category, with vacuum and air-break technologies commanding margin premiums over molded-case alternatives in heavy industrial settings. The utilities end-user segment is shifting toward hybrid technology architectures that combine electromechanical reliability with digital monitoring overlays, creating upgrade cycles across aging substation infrastructure. Smart technology deployments in commercial real estate are accelerating fastest where building management systems require protocol-compatible switchgear for centralized energy analytics.
The European Committee for Electrotechnical Standardization (CENELEC) enforces IEC 61439 series compliance for switchgear assemblies sold across EU member states, while the US National Electrical Manufacturers Association (NEMA) maintains UL 891 and UL 1558 benchmarks that govern busway and switchgear safety certification for North American projects. India's Bureau of Indian Standards (BIS) mandates IS 8623 conformity for domestic switchgear production, shaping import substitution patterns as local manufacturing scales under production-linked incentive frameworks. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring global product portfolios.
Market Dynamics
IEC 61439 compliance mandates are compressing product development cycles while digital twin adoption is reconfiguring how manufacturers validate thermal performance before physical prototyping.
Growth Catalysts
- Data center power distribution intensification:Hyperscale facilities in India and Germany are procuring modular switchgear assemblies with integrated busbar monitoring for redundant power architectures.
- IS 8623 domestic production incentives:India's PLI scheme for electrical equipment is accelerating local manufacturing substitution and import displacement across distribution switchgear categories.
- Vacuum interruption technology maturation:Air-break and vacuum circuit breaker platforms are displacing oil-immersed alternatives in heavy industrial settings due to maintenance interval advantages.
Market Restraints
- Copper and silver contact material volatility:Precious metal price swings in commodity markets are compressing gross margins on high-current breaker assemblies.
- UL 891/UL 1558 certification timeline friction:North American safety validation cycles extend 14-18 months, gating product launches behind European competitors with faster IEC pathways.
- Solid-state power controller substitution:Silicon carbide-based static transfer switches are capturing select data center applications below 600A ratings.
Strategic Opportunities
- Grid modernization in Indian states:Maharashtra and Tamil Nadu distribution utilities are tendering for smart switchgear with remote monitoring capabilities under central government rural electrification frameworks.
- Digital twin convergence with predictive maintenance:Real-time thermal modeling integrated with asset management platforms is creating service revenue attachment opportunities alongside hardware sales.
- Commercial building management system integration:BACnet and Modbus protocol-native switchgear is capturing specification preference in LEED-certified developments across Singapore and UAE.
Industry Challenges
- Electromechanical engineering talent scarcity:Shortages of designers fluent in both thermal modeling and arc flash containment are extending R&D staffing cycles.
- Legacy MCC integration complexity:Retrofit projects requiring protocol translation between 1990s-era motor control centers and modern IEC 61850 architectures are inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage Switchgear Market |
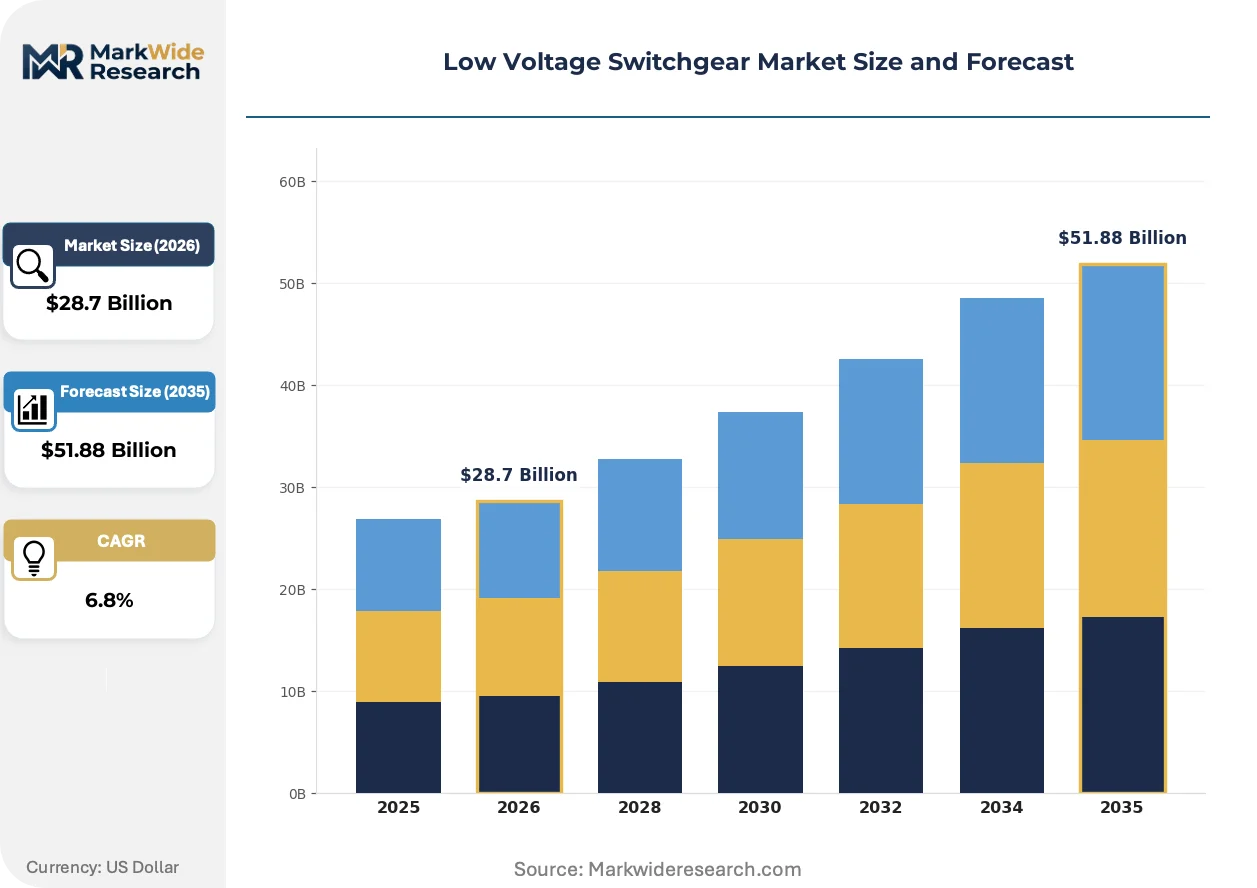
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breakers, Disconnectors, Fuse Combinations, Switches End User: Commercial, Industrial, Residential, Utilities Installation Type: Indoor, Outdoor, Portable, Fixed Technology: Digital, Analog, Hybrid, Smart |
| Companies Covered | Mitsubishi Electric, General Electric, Siemens AG, WEG, Rockwell Automation, Schneider Electric, Eaton, S&C Electric Company, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage Switchgear Market Emerging Trajectories
Software-defined validation workflows are displacing physical prototyping sequences across switchgear development pipelines, compressing time-to-certification while tightening performance tolerances.
Digital twin platforms are virtualizing thermal and electrical stress testing across circuit breaker and busbar configurations before metal is cut. Data center operators in Singapore and Frankfurt are specifying these validated designs for mission-critical redundancy tiers. The technology is virtualizing traditional prototype-build-test cycles into simulation-first workflows that cut development expenditure by half.
REACH substance restrictions on hexavalent chromium plating are forcing contact material substitutions across European-manufactured switchgear assemblies. Manufacturers are migrating to silver-graphite and tungsten-copper composites for arcing contacts. Industrial end-users in Germany and Italy are absorbing modest cost premiums to maintain CE marking compliance and avoid supply exclusion.
Energy-as-a-service procurement models are unbundling switchgear ownership from operational responsibility in commercial real estate portfolios. Facility managers in London and New York are contracting for guaranteed uptime with equipment refresh obligations shifting to specialized operators. This restructuring concentrates specification authority with finance and sustainability officers rather than traditional electrical engineering functions.
Low Voltage Switchgear Market Segmentation
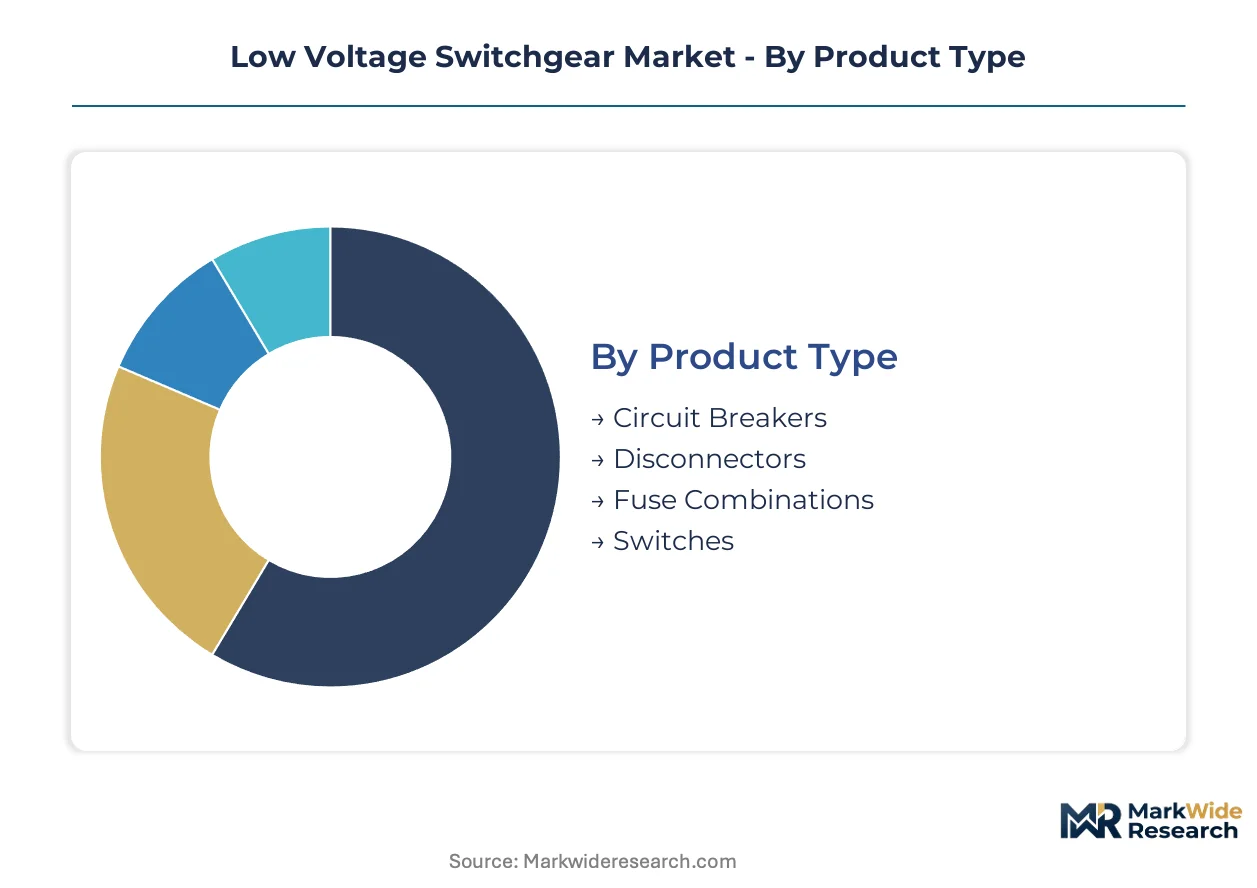
Low voltage switchgear segmentation reveals distinct procurement patterns across installation environments and operational requirements. Each dimension carries specific certification burdens and lifecycle cost profiles that reshape vendor selection criteria.
Product Type:
Circuit breakers and disconnectors anchor the use-case spectrum, spanning from precision motor protection to bulk power isolation in heavy industrial feeds.
- Circuit Breakers:Vacuum and air-break configurations dominate ratings above 630A, with thermal-magnetic trip units integrating digital monitoring modules. Data center operators in India and Germany specify these for redundant busbar architectures where fault isolation speed determines uptime SLAs.
- Disconnectors:Visible-blade designs provide mechanical isolation assurance for maintenance lockout procedures. Manufacturing expansion across Maharashtra and Tamil Nadu is driving procurement of motorized variants with remote operation capabilities.
- Fuse Combinations:HRC fuse-switch units serve cost-sensitive distribution boards in commercial retrofit projects.
- Switches:Load-break switches handle routine switching cycles in feeder panels where full breaker protection is economically unjustified.
The dominant share belongs to Circuit Breakers, while Disconnectors is closing the gap fastest.
End User:
Cost tier stratification separates mission-critical infrastructure from price-sensitive building applications.
- Commercial:Office complexes and retail centers specify IEC 61439-compliant assemblies with BACnet protocol compatibility for building management integration. LEED-certified developments in Singapore and UAE require arc fault detection and energy metering subsystems.
- Industrial:Motor control centers and heavy feeder applications demand vacuum interruption technology with 50kA short-circuit withstand ratings. Steel and cement producers absorb premium pricing for maintenance interval extensions.
- Residential:Distribution boards and consumer units prioritize compact footprints and consumer-accessible reset functions.
- Utilities:Distribution substations are retrofitting electromechanical gear with digital monitoring overlays under rural electrification frameworks.
Industrial installations command the highest unit values, though Commercial is expanding most quickly.
Installation Type:
Environmental exposure determines enclosure ratings and thermal derating requirements across deployment scenarios.
- Indoor:IP31 to IP54 enclosures serve climate-controlled electrical rooms with standardized busbar configurations.
- Outdoor:IP65-rated housings with anti-condensation heaters protect feeder pillars in tropical climates.
- Portable:Trailer-mounted switchgear serves construction sites and temporary event power distribution.
- Fixed:Permanent bolted installations dominate utility substations and industrial plant infrastructure.
Fixed installations retain volume leadership, while Outdoor configurations are gaining share fastest.
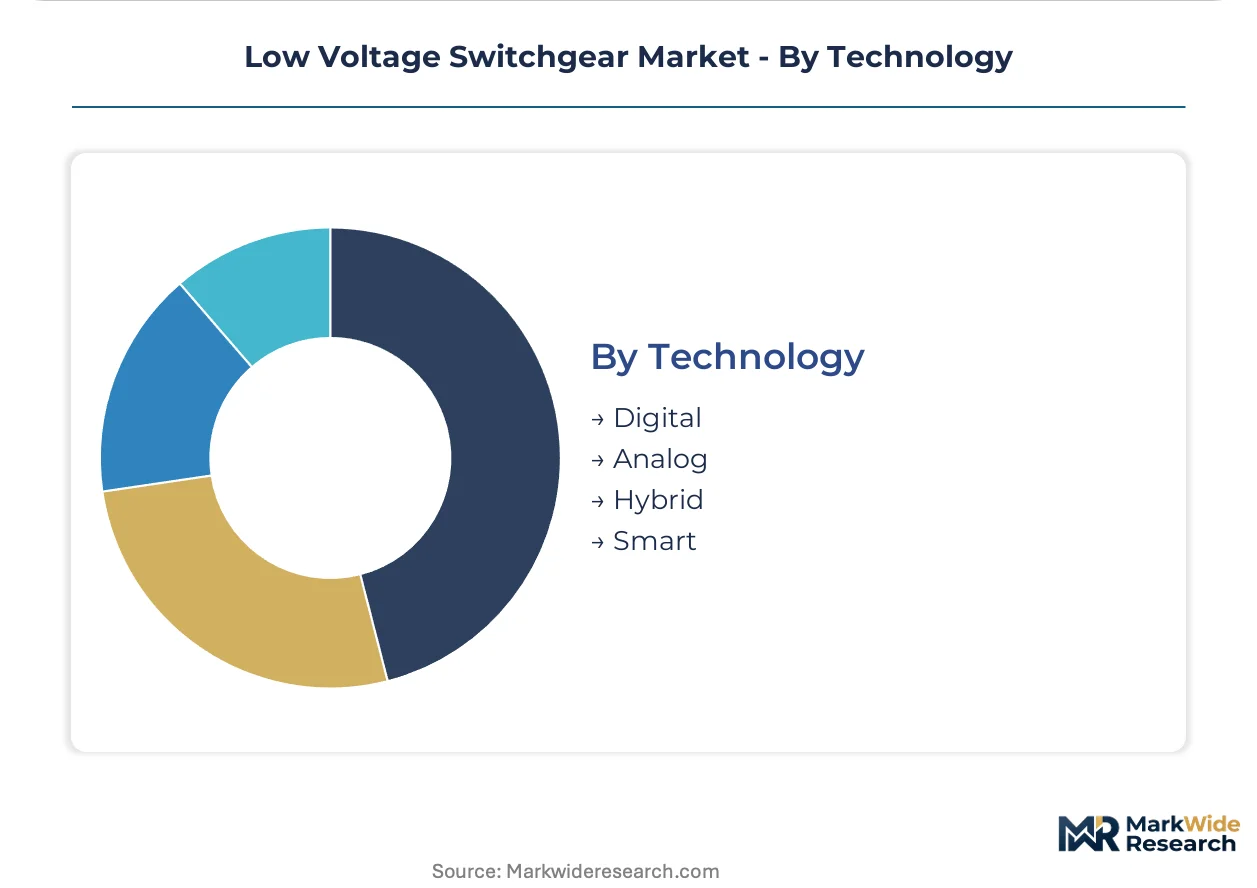
Technology:
Maturity gradients separate legacy electromechanical platforms from digitally native architectures.
- Digital:Microprocessor-based protection relays with IEC 61850 communication enable centralized asset management and predictive maintenance algorithms.
- Analog:Thermal-magnetic and electromagnetic trip mechanisms persist in cost-constrained applications and legacy system extensions.
- Hybrid:Electromechanical switching elements paired with digital monitoring overlays bridge upgrade cycles in aging substation infrastructure.
- Smart:Edge-computing enabled switchgear with embedded sensors and cloud connectivity serves data center and smart grid pilots.
Hybrid platforms hold the largest installed base, while Smart technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators and industrial power engineers concentrate procurement authority across four distinct national markets, each shaped by divergent regulatory compliance timelines and infrastructure investment cycles.
India
Hyperscale data center construction in Mumbai and Hyderabad is absorbing modular switchgear assemblies with integrated busbar monitoring. The Bureau of Indian Standards enforces IS 8623 conformity for domestic production, accelerating local manufacturing substitution under production-linked incentive frameworks. Maharashtra and Tamil Nadu distribution utilities are tendering for smart switchgear with remote monitoring capabilities under central government rural electrification programs.
Germany
Industrial motor control center retrofits and steel sector capacity expansions are driving vacuum circuit breaker demand. The European Committee for Electrotechnical Standardization enforces IEC 61439 series compliance across EU member states, compressing product development cycles for assembly verification. The Ruhr industrial cluster and Bavarian manufacturing belt are specifying electromechanical gear with digital monitoring overlays for predictive maintenance integration.
United States
Commercial building management system integration and data center redundancy architectures are propelling BACnet-protocol switchgear specification. The National Electrical Manufacturers Association maintains UL 891 and UL 1558 benchmarks governing busway and switchgear safety certification, with validation cycles extending 14-18 months. Northern Virginia's data center corridor and Texas's industrial expansion zones are absorbing premium-tier assemblies with arc flash containment systems.
China
Grid modernization investments and manufacturing base electrification are concentrating procurement in coastal industrial zones. The Ministry of Industry and Information Technology oversees GB standards compliance for electrical equipment safety and performance benchmarking. The Yangtze River Delta and Pearl River Delta manufacturing clusters are deploying hybrid technology architectures combining electromechanical reliability with digital monitoring overlays.
Singapore
LEED-certified commercial developments and tropical climate outdoor installations are demanding IP65-rated enclosures with anti-condensation heating systems. The country's national electrical regulator mandates conformity with IEC 61439-derived standards for assembly verification in tropical environments. The Jurong industrial estate and downtown commercial core are specifying protocol-native switchgear for centralized energy analytics integration.
Low Voltage Switchgear Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation pressures favor integrated automation conglomerates with software portfolios anchoring digital lifecycle services alongside hardware sales. Product specialists defend position through deep certification expertise in regional regulatory pathways. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with technology licensing agreements accelerating time-to-market for digital twin validation workflows.
Among diversified electrical equipment conglomerates, Siemens AG, Schneider Electric, and ABB Ltd occupy positions spanning automation software through hardware integration. Siemens AG exemplifies the channel-controlling archetype through digital lifecycle service attachment. Schneider Electric represents specialization density in smart distribution architectures for commercial building applications. ABB Ltd anchors the industrial installation tier with integrated motor control center positioning. These three entities collectively illustrate the competitive structure's concentration around electromechanical-digital hybrid capabilities.
| Leading Market Players |
|---|
| Mitsubishi Electric |
| General Electric |
| Siemens AG |
| WEG |
| Rockwell Automation |
| Schneider Electric |
| Eaton |
| S&C Electric Company |
| ABB Ltd |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster concentrates vacuum interrupter and molded-case breaker capacity, translating upstream component availability into tiered pricing power for system integrators serving data center and industrial segments.
Pricing Analysis
Cost-plus contracts indexed to copper and silver spot markets dominate procurement for high-current breaker assemblies. Pricing stratifies across IEC 61439-certified premium tiers, UL-listed North American variants, and economy-grade IS 8623 domestic Indian production. Cost compression in standard-tier molded-case breakers is intensifying because of precious metal volatility and Chinese manufacturing overcapacity. Commercial building developers exhibit highest price sensitivity, while hyperscale data center operators absorb premiums for arc flash containment and digital monitoring integration.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard procurement instruments for Indian and Southeast Asian distribution channel partners. Manufacturing concentrates in China, India, and Germany for circuit breaker assemblies, with vacuum interrupters drawing from specialized ceramic-metal sealing operations in Japan and Austria. Raw material dependencies span copper busbar, silver-graphite contacts, and epoxy resin insulation systems. Single-source vulnerability in vacuum interrupter ceramic housings represents the dominant structural risk. Distribution runs through authorized electrical distributors and direct OEM relationships for large industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electromechanical engineering talent capable of integrating thermal modeling with arc flash containment design is the constraining asset across product development pipelines, forcing strategic choices about build-versus-buy capability acquisition.
For Market Incumbents: Entrench digital lifecycle service attachment alongside hardware sales to lock in switching costs against solid-state power controller substitution. Prioritize backward integration into vacuum interrupter manufacturing to secure ceramic-metal sealing capacity and buffer precious metal contact volatility. Accelerate IEC 61439 certification investments to compress time-to-market versus UL-gated North American competitors.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point given protocol-agnostic specification standards and limited incumbent service density. Smart switchgear retrofits for Indian state distribution utilities under rural electrification frameworks offer tender-accessible volume. Lead with BACnet-native designs and localized assembly partnerships to bypass capital-intensive certification barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical-digital hybrid specialists with captive vacuum interrupter supply and installed base service contracts. Long-term viability hinges on predictive maintenance platform attachment rates and recurring revenue conversion. Monitor silicon carbide static transfer switch adoption curves in sub-600A data center applications as inflection signal for substitution risk timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Validation Platform | Compresses IEC 61439 certification cycles by virtualizing thermal stress testing before physical prototyping. |
| Backward Integration into Vacuum Interrupters | Secures ceramic-metal sealing capacity against Japanese and Austrian supply concentration. |
| IS 8623 Domestic Manufacturing Certification | Unlocks Indian PLI scheme incentives and displaces import-dependent procurement patterns. |
| Predictive Maintenance Service Contracts | Converts hardware sales into recurring revenue streams tied to thermal monitoring data. |
| Protocol-Native Building Management Integration | Captures specification preference in Singapore and UAE LEED-certified commercial developments. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with electrical engineering directors at hyperscale data center operators, procurement leads at Indian state distribution utilities, plant engineers at German steel and cement producers, and channel managers at authorized electrical distributors. Secondary validation drew from IEC 61439 certification registries, BIS IS 8623 conformity listings, UL 891/1558 safety validation databases, and customs trade data for copper busbar and vacuum interrupter imports. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts from power sector planning authorities.
Calibration against historical substitution patterns between air-break, vacuum, and oil-immersed breaker technologies anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product type, end-user vertical, installation environment, and technology maturity tier, with additional granularity on certification pathway and protocol compatibility. CAGRs were derived from fitted growth curves applied to utility capital expenditure cycles, data center construction pipelines, and manufacturing capacity expansion announcements. Forecast inputs incorporated PLI scheme disbursement schedules and REACH substance restriction compliance timelines.
Practitioners should monitor silicon carbide power semiconductor cost curves and solid-state switch reliability maturation for early signals of substitution acceleration in mission-critical power distribution. Forecasts reflect assumptions about regulatory compliance timeline stability, precious metal price volatility bands, and electromechanical engineering labor market tightness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Pressure Switch Market
Switches
China Reed Sensors Switches Market
Switches
Japan Reed Sensors Switches Market
Switches
North America Low Voltage Switchgear Market
Switches
Europe Low Voltage Switchgear Market
Switches
Solid State Relay Market
Switches
Italy Reed Sensors Switches Market
Switches
Power Load Switches Market
Switches
Paralleling Switchgear Market
Switches
Panel Mounted Disconnect Switch Market
Switches
5G Electromechanical RF Switch Market
Switches
Smart Home Switches Market
Switches
Europe Switchgear Market
Switches
Campus Switches Market
Switches
Asia Pacific Safety Switches Market