
 Paralleling Switchgear Market | 2026-2036
Paralleling Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Paralleling Switchgear Market Analysis
NFPA 110 is rebalancing the cost-of-entry calculus for paralleling switchgear manufacturers by mandating stricter generator-set synchronization and load-transfer protocols. Cummins Inc. leverages its captive engine-generator portfolio to anchor integrated paralleling solutions across North American critical infrastructure. Schneider Electric competes through its EcoStruxure platform, which extends digital monitoring into switchgear control architectures. Siemens AG specializes in medium-voltage paralleling systems for utility-scale microgrids, occupying a niche where voltage regulation complexity screens out smaller suppliers.
Paralleling switchgear comprises electromechanical or solid-state assemblies that synchronize multiple power sources—typically engine-generators or utility feeds—to a common bus, maintaining voltage, frequency, and phase-angle alignment within tolerance bands. Automatic transfer switches dominate product-type revenue due to their ubiquity in data center and healthcare applications where sub-cycle load transfer prevents operational disruption. Indoor installations generate the largest service-type attach rate, as confined electrical rooms demand engineered airflow, arc-flash containment, and preventive maintenance contracts that lock in multi-year vendor relationships.
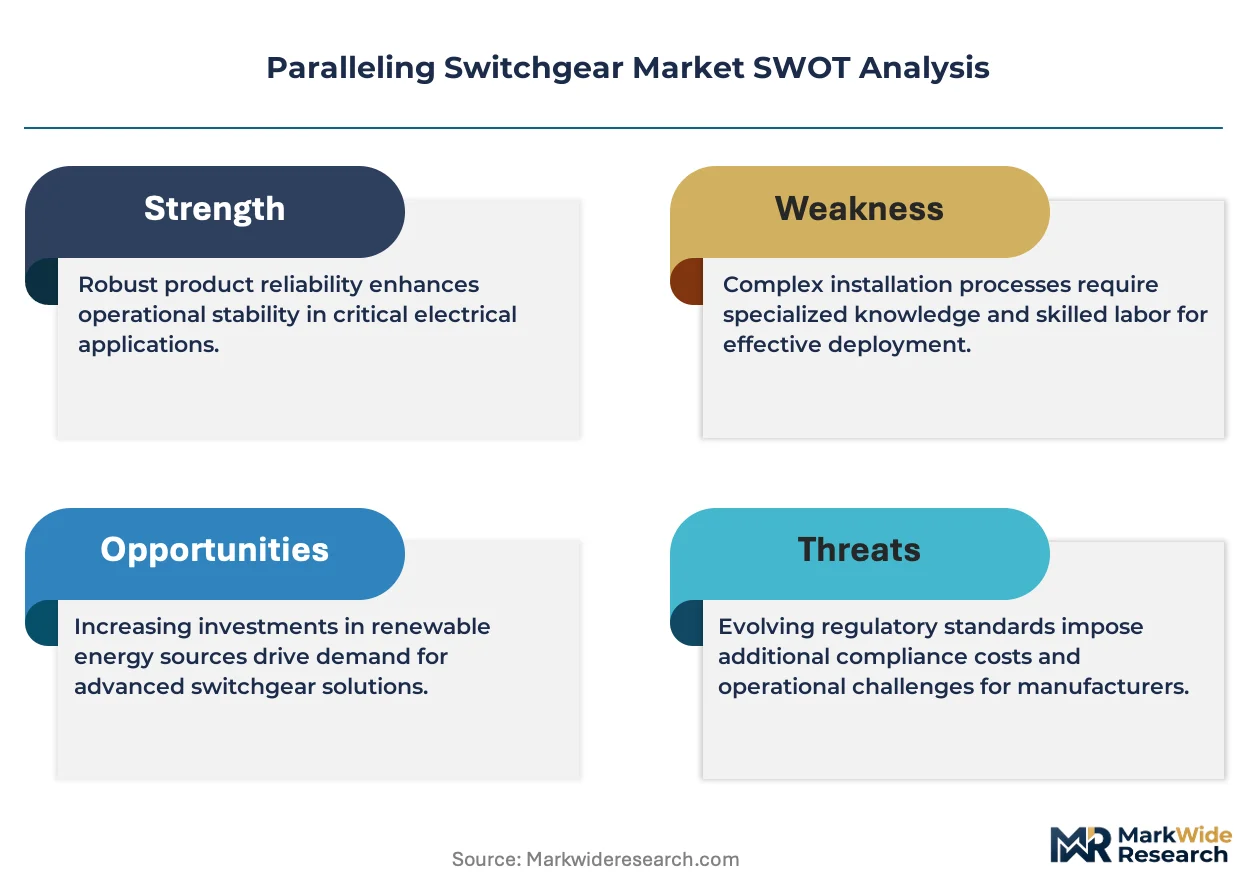
The US National Electrical Code, IEEE 1547 interconnection standards, and OSHA arc-flash regulations collectively shape product design, installation labor costs, and market access for non-compliant imports. The EPA's stationary engine emission tiers further constrain generator-set pairing options, indirectly filtering which switchgear architectures qualify for permitted installations. Stakeholders must monitor evolving grid-interconnection rules as distributed energy resource penetration rises, since bi-directional paralleling requirements will favor vendors with software-defined control platforms over hardware-centric legacy portfolios.
Market Dynamics
Data center operators are compressing backup power commissioning timelines while NFPA 110 synchronization mandates intensify engineering complexity, forcing switchgear vendors to absorb compliance costs or cede procurement decisions to integrated generator-set suppliers.
Growth Catalysts
- Hyperscale facility construction:United States-based cloud infrastructure operators are expanding redundant N+1 power architectures that mandate paralleling switchgear for seamless generator synchronization.
- NFPA 110 synchronization standards:Stricter load-transfer protocols are retrofitting existing critical infrastructure, compelling healthcare and financial institutions to upgrade aging electromechanical controls.
- Diesel-electric hybrid microgrids:Battery energy storage integration with traditional engine-generator sets is creating new paralleling architectures for islanded operation.
Market Restraints
- Copper and silver commodity volatility:Busbar and contactor material costs swing with London Metal Exchange pricing, compressing gross margins on fixed-price infrastructure contracts.
- Specialized switchgear engineering talent:North American utilities and EPC firms face scarcity of power systems engineers capable of medium-voltage paralleling design.
- EPA Tier 4 Final emissions compliance:Generator-set pairing restrictions filter qualified engine options, indirectly constraining compatible switchgear control platforms.
Strategic Opportunities
- Bi-directional grid interconnection:IEEE 1547-2018 revision requirements favor software-defined control platforms over legacy hardware-centric architectures.
- India data center buildout:Domestic cloud infrastructure investment under the country's digital sovereignty initiatives creates demand for localized paralleling expertise.
- Predictive maintenance service contracts:IoT-enabled switchgear monitoring transforms vendor relationships from equipment sales to multi-year performance agreements.
Industry Challenges
- Arc-flash hazard mitigation:OSHA 1910.269 compliance demands engineered containment and personnel training that extend project commissioning schedules.
- Legacy electromechanical control integration:Solid-state paralleling systems must interface with decades-old generator-set governors, creating commissioning complexity and warranty disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paralleling Switchgear Market |
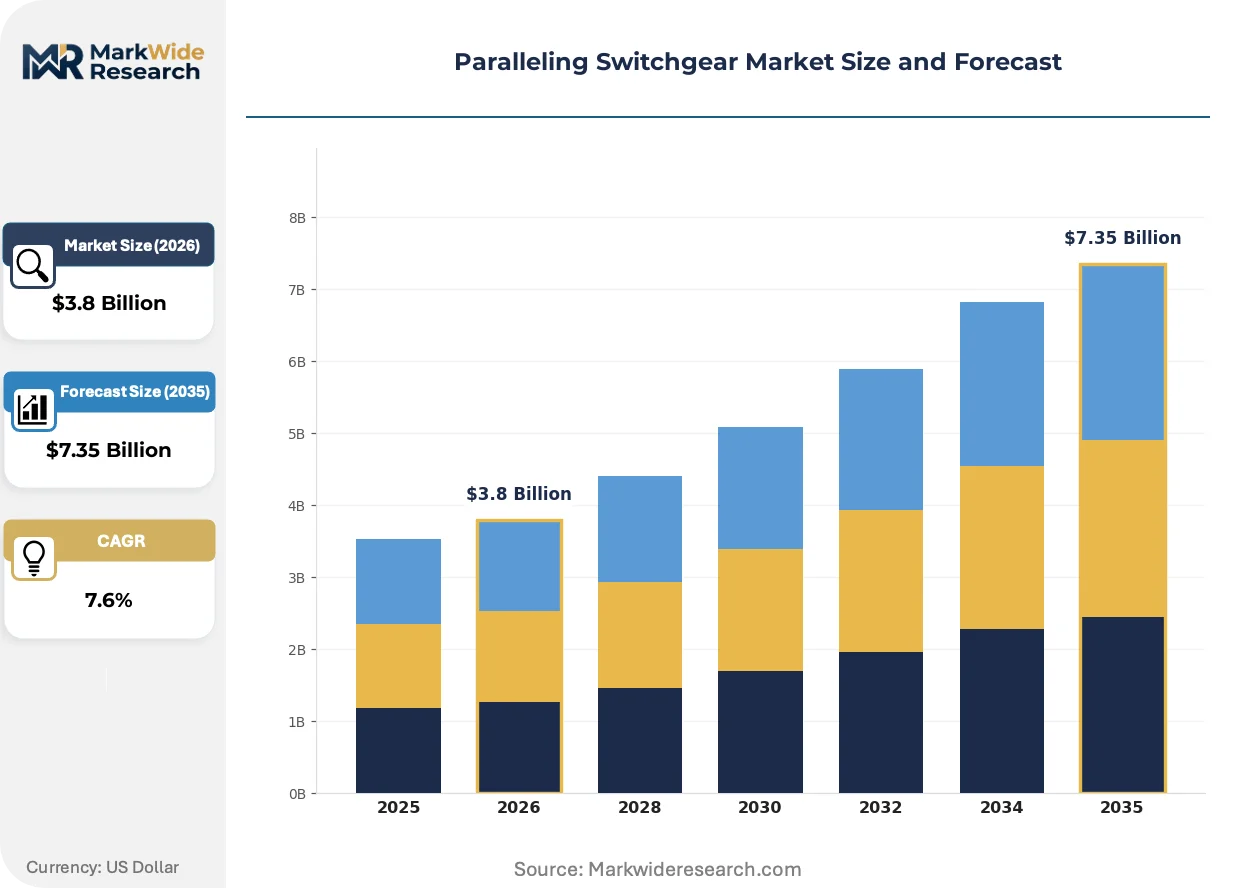
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Transfer Switch, Manual Transfer Switch, Static Transfer Switch, Bypass Switch End User: Data Centers, Industrial Facilities, Commercial Buildings, Healthcare Facilities Installation: Indoor, Outdoor, Wall-Mounted, Ground-Mounted Service Type: Installation Services, Maintenance Services, Emergency Services, Customization Services |
| Companies Covered | ABB Ltd, Cummins Inc., Eaton Corporation, ASCO Power Technologies, Caterpillar Inc., Schneider Electric, General Electric, Mitsubishi Electric Corporation, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paralleling Switchgear Market Emerging Trajectories
Digitalization is penetrating switchgear control architectures while regulatory pressure tightens synchronization tolerances, compressing the viable vendor set to those with captive software development and field service infrastructure.
Silicon-controlled rectifier-based static transfer switches are absorbing market share from electromechanical contactor assemblies in sub-cycle transfer applications. Hyperscale data center operators specify solid-state devices for 4-millisecond load transfers that prevent server reboots. The technology is absorbing engineering talent and R&D budgets previously allocated to conventional breaker-based paralleling, compressing legacy supplier margins.
EPA stationary engine emission tiers are tightening generator-set pairing constraints that cascade into switchgear qualification protocols. Tier 4 Final compliance filters engine options to those with electronic governing systems capable of precise frequency control. Data center and healthcare procurement teams now specify integrated generator-switchgear packages from single-source vendors rather than assembling multi-brand systems.
After-sales service unbundling is fragmenting traditional vendor relationships as facility operators separate equipment procurement from long-term maintenance obligations. Third-party engineering firms are capturing preventive maintenance contracts for installed paralleling switchgear, displacing original manufacturer service revenues. This pattern concentrates in United States metropolitan markets with dense critical infrastructure clusters and mature independent service organization ecosystems.
Paralleling Switchgear Market Segmentation
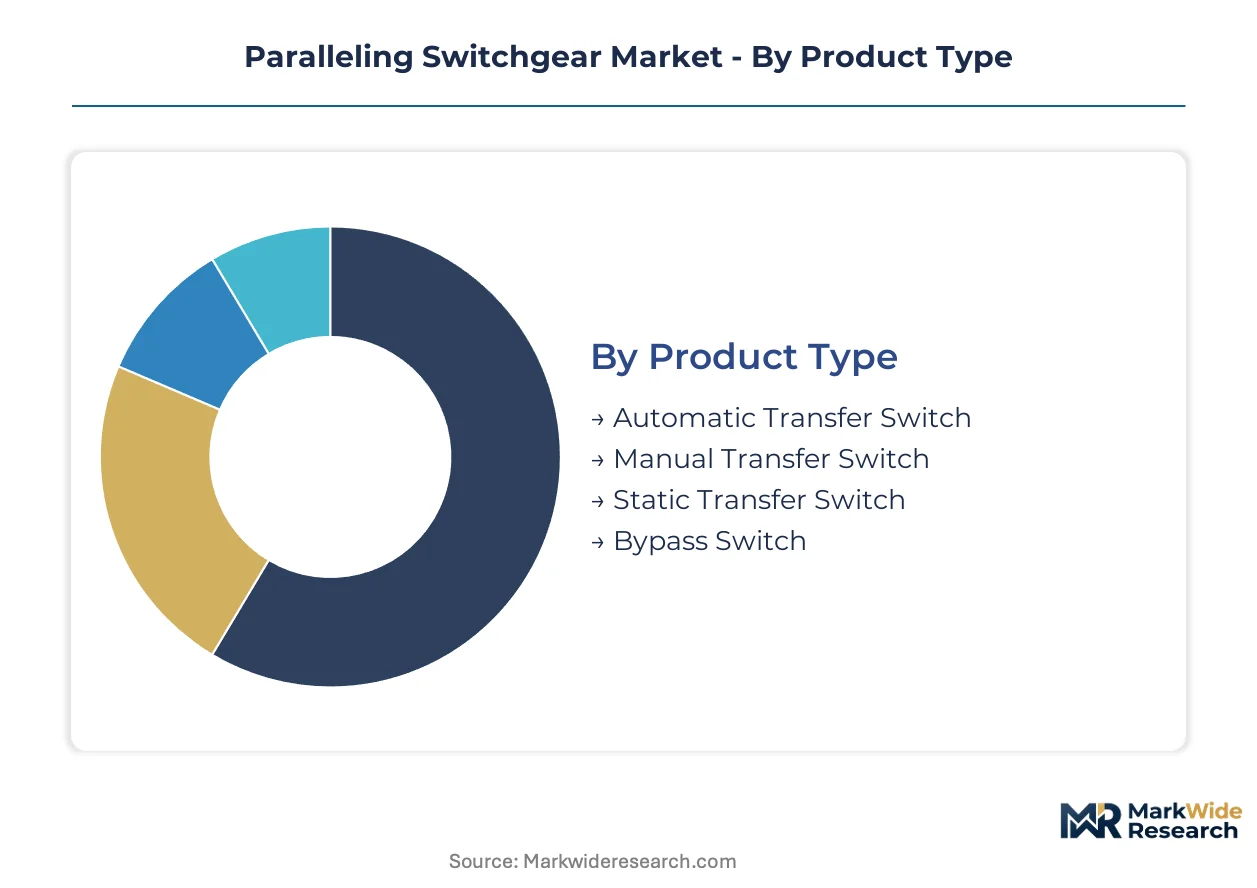
Paralleling switchgear procurement decisions split across technical specifications, facility constraints, and lifecycle service requirements. Capital allocation patterns diverge sharply between mission-critical data center deployments and cost-sensitive commercial installations.
Product Type:
Capital intensity peaks in solid-state architectures where semiconductor components and precision engineering dominate bill-of-materials costs.
- Automatic Transfer Switch:Electromechanical assemblies with motorized transfer mechanisms synchronize generator sets to utility feeds within IEEE 1547 tolerances. Data center operators in Northern Virginia and Dallas-Fort Worth specify these for N+1 redundancy architectures where sub-second transfer prevents server disruption. NFPA 110 synchronization mandates are retrofitting aging healthcare and financial infrastructure across the United States.
- Static Transfer Switch:Silicon-controlled rectifier arrays execute 4-millisecond load transfers through zero-crossing detection circuits. Hyperscale cloud operators in Phoenix and Ashburn demand these for hypersensitive IT loads where electromechanical latency risks equipment damage. Solid-state topology absorbs engineering talent and R&D budgets previously allocated to breaker-based systems.
- Manual Transfer Switch:Operator-actuated rotary or knife-blade mechanisms provide basic isolation for non-critical loads. Small commercial facilities and municipal buildings deploy these where automated synchronization exceeds operational requirements.
- Bypass Switch:Maintenance isolation devices enable hot-swapping of active switchgear components without load interruption. Industrial microgrids and utility substations integrate these for extended service windows.
Most installed capacity flows through Automatic Transfer Switch configurations. Expansion is steepest in Static Transfer Switch deployments.
End User:
Facility uptime requirements and regulatory exposure determine procurement sophistication and service contract attach rates.
- Data Centers:Hyperscale and colocation operators mandate paralleling switchgear for redundant power architectures serving cloud computing and AI training workloads. EPA Tier 4 Final emissions compliance filters generator-set pairing options, indirectly constraining compatible switchgear control platforms for new construction in Oregon and Iowa.
- Healthcare Facilities:Joint Commission accreditation and CMS emergency power standards compel hospitals to maintain uninterrupted life-safety systems. NFPA 99 and NFPA 110 synchronization requirements are retrofitting aging electromechanical controls in tertiary care centers.
- Industrial Facilities:Manufacturing plants and process industries deploy paralleling systems for islanded operation during utility disturbances. Chemical processing and semiconductor fabrication prioritize voltage regulation precision.
- Commercial Buildings:Office towers and retail complexes specify basic transfer switching for code-compliant emergency lighting and elevator backup. Cost pressures favor standardized packages over engineered solutions.
Data Centers command the highest average selling prices per megawatt of protected load. Healthcare Facilities show the steepest retrofit-driven expansion trajectory.
Installation:
Environmental exposure and spatial constraints dictate enclosure engineering and thermal management costs.
- Indoor:Confined electrical rooms demand engineered airflow, arc-flash containment, and seismic bracing. Preventive maintenance contracts lock in multi-year vendor relationships for critical infrastructure in dense metropolitan markets.
- Outdoor:NEMA 3R and 4X enclosures protect against precipitation and particulate intrusion for distributed generation and utility substations. Coastal installations require salt-spray-resistant finishes.
- Wall-Mounted:Compact assemblies conserve floor space in retrofit applications and smaller facilities. Load ratings typically cap below 800 amperes.
- Ground-Mounted:Pad-mounted or skid-based configurations accommodate large-scale generator paralleling for industrial microgrids and campus utilities.
Indoor configurations generate the largest service-type attach rate. Outdoor installations are climbing fastest as distributed energy resource penetration rises.
Service Type:
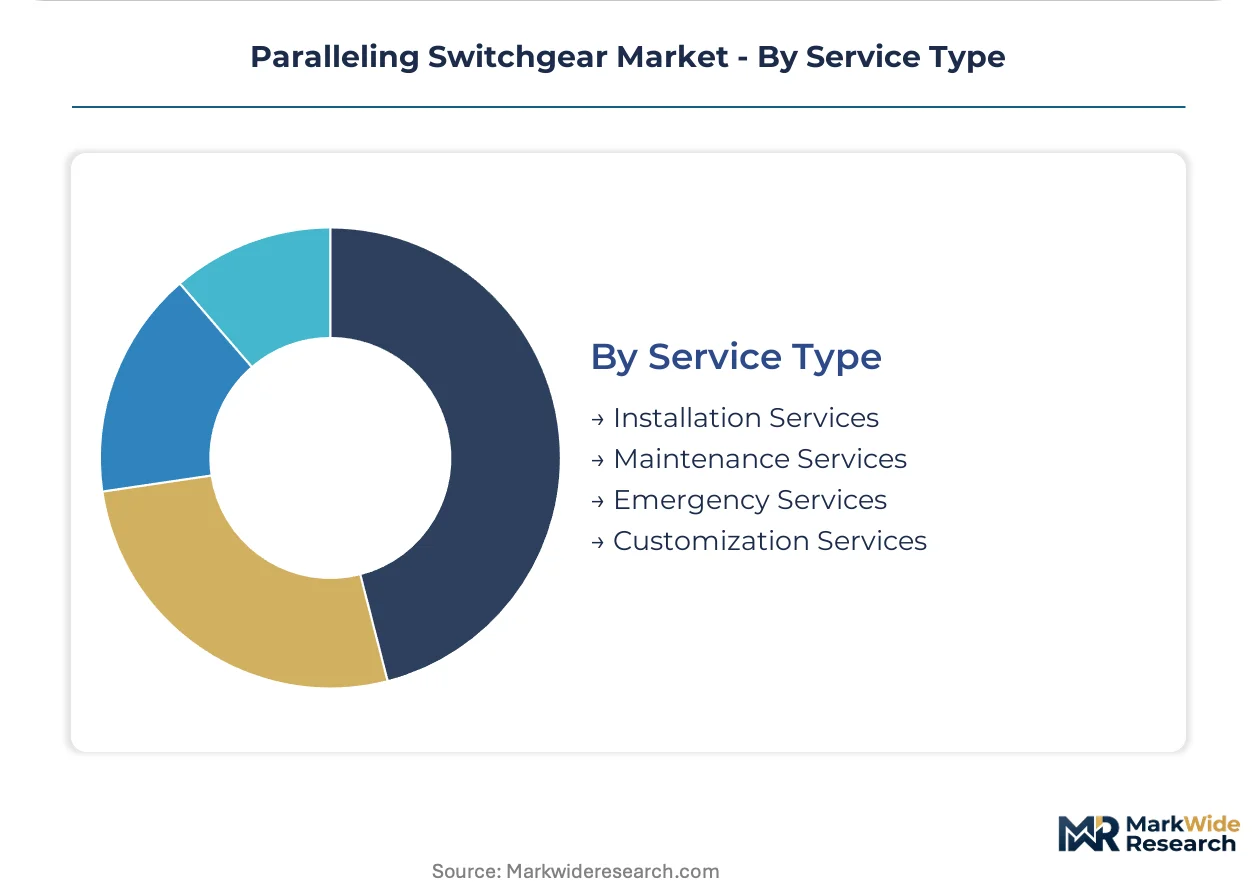
Revenue mix is shifting from equipment margins to recurring performance contracts as facility operators unbundle procurement from long-term obligations.
- Maintenance Services:Scheduled inspection, contactor replacement, and control calibration preserve synchronization accuracy. Third-party engineering firms are capturing these contracts in United States metropolitan markets with dense critical infrastructure clusters.
- Installation Services:Factory-authorized startup and commissioning ensures warranty validity and code compliance. OSHA 1910.269 arc-flash regulations extend project timelines and labor costs.
- Emergency Services:24-hour response capabilities for control failure or synchronization loss command premium pricing. Healthcare and financial institutions mandate guaranteed response times.
- Customization Services:Application-specific programming, protocol conversion, and legacy system integration address unique facility requirements. Solid-state systems interfacing with decades-old generator governors create commissioning complexity.
Maintenance Services represent the largest revenue pool by volume. Customization Services are expanding most quickly as bi-directional grid interconnection requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paralleling switchgear manufacturing first achieved industrial scale in the United States during the post-war electrification era, when utility reliability standards demanded synchronized backup power for critical infrastructure. The technology subsequently diffused to Germany and Japan through industrial automation partnerships, then to China and India via foreign direct investment in power infrastructure.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives procurement of N+1 redundant paralleling architectures. NFPA 110 synchronization mandates are retrofitting aging healthcare and financial infrastructure nationwide. Ashburn and Phoenix clusters specify solid-state transfer switches for sub-cycle load protection of AI training workloads.
Germany
Industrial microgrid deployment for manufacturing resilience propels medium-voltage paralleling system demand. The EU Green Deal and national Energiewende policies accelerate diesel-electric hybrid integrations with battery storage. Bavaria and Baden-Württemberg host precision engineering clusters where voltage regulation specifications screen out non-European suppliers.
China
Cloud infrastructure buildout under digital sovereignty initiatives creates demand for localized paralleling expertise in Yangtze River Delta and Pearl River Delta zones. GB standards for grid interconnection and MIIT industrial policy shape product qualification protocols. Beijing-Tianjin-Hebei corridor concentrates domestic switchgear manufacturing capacity.
India
Data center investment under the country's digital sovereignty push generates procurement for localized paralleling engineering. CEA grid codes and state-level industrial policies determine interconnection compliance requirements. Maharashtra and Karnataka host the densest clusters of hyperscale facility construction, with Mumbai and Bangalore as primary demand centers.
Japan
Semiconductor fabrication and precision manufacturing prioritize voltage stability through advanced paralleling controls. METI energy security directives promote islanded microgrid capabilities for industrial resilience. Kanto and Kansai regions concentrate demand from Tokyo-Osaka manufacturing belts with zero-tolerance power quality requirements.
Paralleling Switchgear Market Vendor Landscape
The competitive structure tilts toward integrated power system providers with captive generator-set portfolios. Tier-one vendors combine switchgear manufacturing with engine-generator production or digital control platforms, while tier-two specialists focus on regional service density and retrofit expertise. Dominant competitive moves include backward integration into generator-set manufacturing and geographic expansion through EPC partnerships in hyperscale data center corridors.
Within the integrated-systems tier, Cummins Inc. and Caterpillar Inc. anchor positions through captive engine-generator portfolios that streamline compliance with EPA Tier 4 Final emissions protocols. Schneider Electric exemplifies the digital-platform archetype, extending software-defined control architectures into switchgear management systems. Siemens AG occupies a specialized position in medium-voltage utility-scale applications where voltage regulation complexity filters market access.
| Leading Market Players |
|---|
| ABB Ltd |
| Cummins Inc. |
| Eaton Corporation |
| ASCO Power Technologies |
| Caterpillar Inc. |
| Schneider Electric |
| General Electric |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
London Metal Exchange copper pricing volatility cascades through paralleling switchgear supply chains, compressing margins on fixed-price infrastructure contracts while forcing tiered pricing stratification across premium engineered systems, standard modular assemblies, and economy-grade commercial packages.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by synchronization precision and arc-flash certification grade. Premium tiers absorb semiconductor component costs for solid-state transfer switches serving hyperscale data centers, while economy tiers face price erosion from commoditized electromechanical assemblies. Healthcare and financial institutions show lowest price sensitivity due to Joint Commission and NFPA 110 compliance mandates, whereas commercial building operators drive procurement toward lowest-qualified bids.
Supply Chain Analysis
Power systems engineering talent scarcity in North American manufacturing geographies constrains medium-voltage paralleling system production capacity. Supply draws from the United States, Germany, and China for precision contactor assemblies, silicon-controlled rectifiers, and busbar fabrication. Single-source vulnerability concentrates in semiconductor components for static transfer switches. Distribution runs through factory-authorized EPC partnerships and direct OEM channels to hyperscale data center developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in paralleling switchgear hinges on software-defined control platform premiums displacing hardware-centric legacy systems, while copper commodity hedging and captive generator-set integration compress input cost volatility.
For Market Incumbents: Acquire field service infrastructure and predictive maintenance software capabilities to lock in multi-year performance contracts. Consolidate backward into generator-set electronic governing systems to streamline EPA Tier 4 Final compliance integration. Defend against third-party engineering firms capturing maintenance revenues in dense metropolitan markets by embedding IoT monitoring into standard equipment packages. For New Entrants and Emerging Players: Enter via bi-directional grid interconnection specialization for distributed energy resource penetration, targeting India data center buildout under digital sovereignty initiatives. White-space exists in localized paralleling engineering for Maharashtra and Karnataka hyperscale clusters. Pursue EPC partnership routes rather than direct OEM competition to bypass captive generator-set bundling advantages. For Investors and Strategic Acquirers: Asymmetric upside sits with software-defined control platform specialists possessing IEEE 1547-2018 compliance architectures. Long-term viability favors vendors with integrated digital monitoring and field service density across 5-10 year utility-scale microgrid deployment windows. Monitor EPA stationary engine emission tier revisions as inflection signals for generator-set pairing constraint shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Generator-Set Manufacturing | Cummins and Caterpillar anchor positions through captive engine portfolios streamlining EPA Tier 4 Final compliance protocols. |
| Software-Defined Control Platform Development | Schneider Electric extends EcoStruxure digital monitoring into switchgear architectures for bi-directional grid interconnection. |
| Predictive Maintenance Service Contract Expansion | IoT-enabled monitoring transforms vendor relationships from equipment sales to multi-year performance agreements in dense infrastructure clusters. |
| Geographic Expansion via EPC Partnerships | Hyperscale data center corridors in Northern Virginia and Dallas-Fort Worth demand localized commissioning expertise and rapid response capabilities. |
| Medium-Voltage System Specialization | Siemens AG occupies utility-scale microgrid niches where voltage regulation complexity filters market access for smaller suppliers. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with data center engineering directors, healthcare facility managers, EPC contractors, and switchgear procurement officers alongside secondary validation through IEEE standards documentation, EPA regulatory filings, and customs trade data. Bottom-up and top-down triangulation cross-references equipment shipment volumes with installed capacity estimates across hyperscale facility construction databases.
Rate-of-change decomposition separates volume expansion from value-per-unit shifts across the analysis window, modeling segmentation dimensions including product type architecture, end-use facility criticality tier, installation environment constraints, and service contract attach rates. CAGRs derive from curve-fitting historical procurement patterns against regulatory mandate implementation timelines, with specific inputs from NFPA 110 retrofit cycle analysis and data center N+1 redundancy penetration rates.
Inputs from hyperscale developer capex disclosures and healthcare construction permit databases were available through the study window; gaps in third-party maintenance contract pricing introduce uncertainty bands around service revenue projections. Forecasts reflect assumptions regarding EPA emission tier enforcement consistency and copper commodity stabilization. Material deviation in grid-interconnection rulemaking or semiconductor component availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Vibration Level Switch Market
Switches
Cross Point Switch Market
Switches
Power Load Switches Market
Switches
Proximity Switches Market
Switches
North America MV Switchgear Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Pressure Switch Market
Switches
United States X by Wire Systems Market
Switches
Reed Switch Market
Switches
DC Switchgear Market
Switches
Global Light Control Switches Market
Switches
Timer Switch Socket Market
Switches
Brazil Switchgear Market
Switches
Navigation Switches Market
Switches
North America Medium Voltage Switchgear Market
Switches
Tactile Switch Keyboard Market