
 China Reed Sensors Switches Market | 2026-2036
China Reed Sensors Switches Market Size, Share, and Industry Trends Forecast 2026-2036
China Reed Sensors Switches Market Outlook
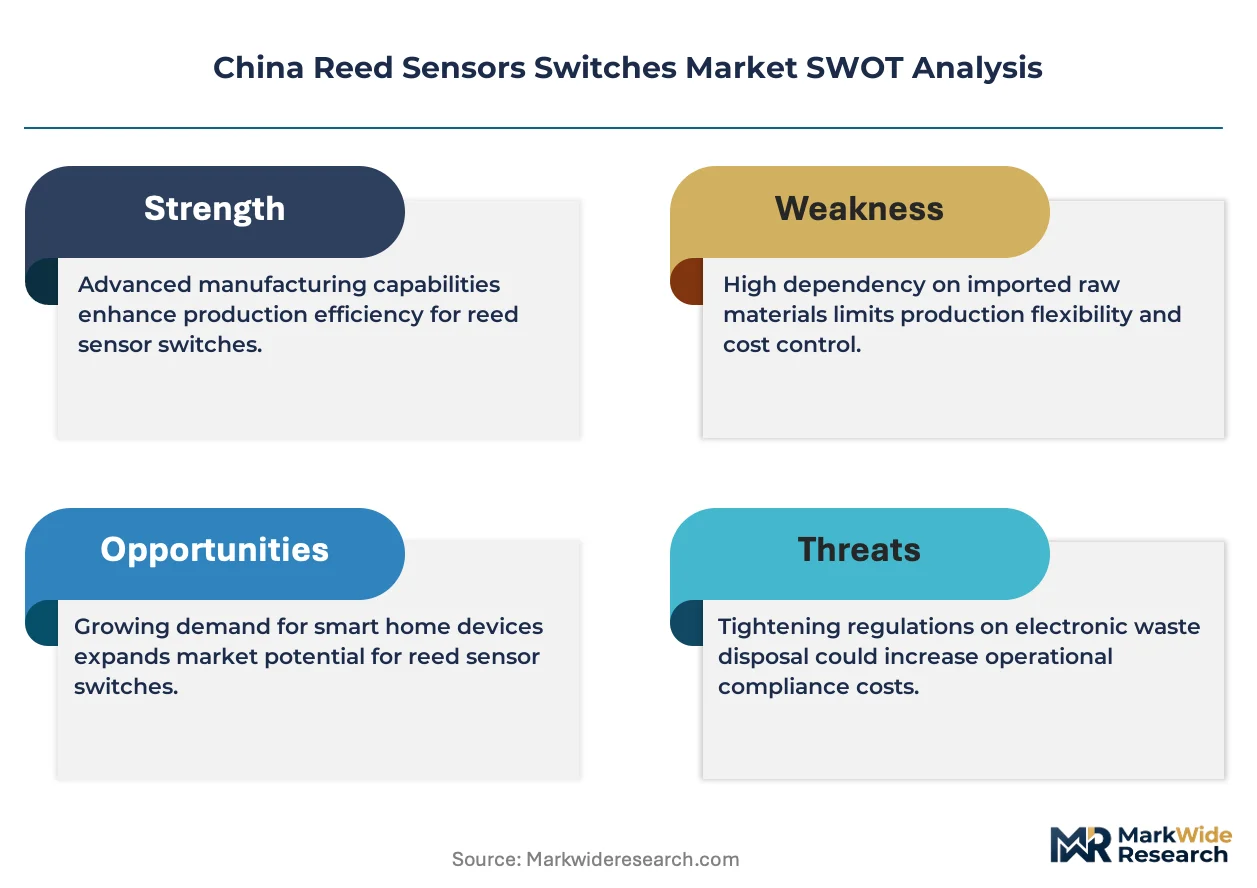
Rare-earth magnet alternatives in reed switch assemblies is realigning cost structures for Chinese manufacturers. Littelfuse Inc. leverages its automotive certification depth to anchor premium positioning in EV battery management systems. Standex Electronics sustains manufacturing scale through dedicated facilities serving industrial automation clients. Zhejiang Xurui Electronic competes on proximity to downstream electronics clusters in Zhejiang province.
Reed sensors switches are electromechanical devices hermetically sealed in glass envelopes containing ferromagnetic reeds that close under magnetic field influence, typically rated for switching voltages from millivolts to hundreds of volts. They serve as contactless position detectors, level sensors, and safety interlocks across industrial and consumer applications. Magnetic reed switch products occupy the largest volume share given their penetration in household appliances and HVAC controls, while automotive reed switch variants command margin premiums due to AEC-Q200 qualification requirements. Specialty reed switch applications in medical and aerospace equipment represent the fastest structural expansion within the technology portfolio.
China's SAMR enforces GB standards compliance for electromagnetic compatibility and product safety labeling, directly conditioning market access for domestic and imported reed switch products. MIIT industrial policy incentives under the dual carbon goals are accelerating replacement of electromechanical switches with lower-power alternatives in smart grid infrastructure. NMPA medical device regulations create additional certification layers for reed relays deployed in patient-contact equipment. Stakeholders must monitor evolving GB standard revisions and provincial green manufacturing audits to anticipate compliance cost shifts and qualification timeline changes.
Market Dynamics
China's GB standards for electromagnetic compatibility are tightening certification timelines, forcing reed sensor manufacturers to restructure qualification workflows and consolidate testing partnerships with SAMR-accredited laboratories.
Growth Catalysts
- Dual carbon policy mandates:MIIT incentives under China's dual carbon goals are accelerating replacement of electromechanical switches with lower-power reed alternatives in smart grid infrastructure.
- Yangtze River Delta concentration:Demand clusters in the manufacturing corridor spanning Shanghai, Jiangsu, and Zhejiang provinces, creating dense supplier ecosystems and shortened logistics loops.
- Electric vehicle sensor integration:Automotive battery management systems require AEC-Q200 qualified reed switches for contactless current sensing and thermal runaway detection.
Market Restraints
- Rare-earth magnet cost volatility:Neodymium and samarium-cobalt price swings compress margins for reed switch assemblies dependent on permanent magnet actuation.
- GB standards compliance friction:SAMR electromagnetic compatibility testing creates 4-6 month certification bottlenecks for new product introductions.
- Solid-state magnetic sensor substitution:Hall-effect and magnetoresistive devices displace reed switches in high-frequency switching applications above 10kHz.
Strategic Opportunities
- Medical device certification white space:NMPA regulations for patient-contact equipment create premium positioning for hermetically sealed reed relays in diagnostic imaging systems.
- Western China industrial automation:Sichuan and Chongqing manufacturing bases remain underpenetrated for industrial reed sensor deployment versus coastal saturation.
- Silicon carbide convergence:Integration of reed switches with SiC power modules enables new protection architectures in high-voltage EV charging infrastructure.
Industry Challenges
- AEC-Q200 qualification timelines:Automotive-grade reed switch certification requires 18-24 month validation cycles that strain working capital for mid-tier suppliers.
- Hermetic sealing skill scarcity:Glass-to-metal seal engineering expertise concentrates among aging technician cohorts in legacy manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Reed Sensors Switches Market |
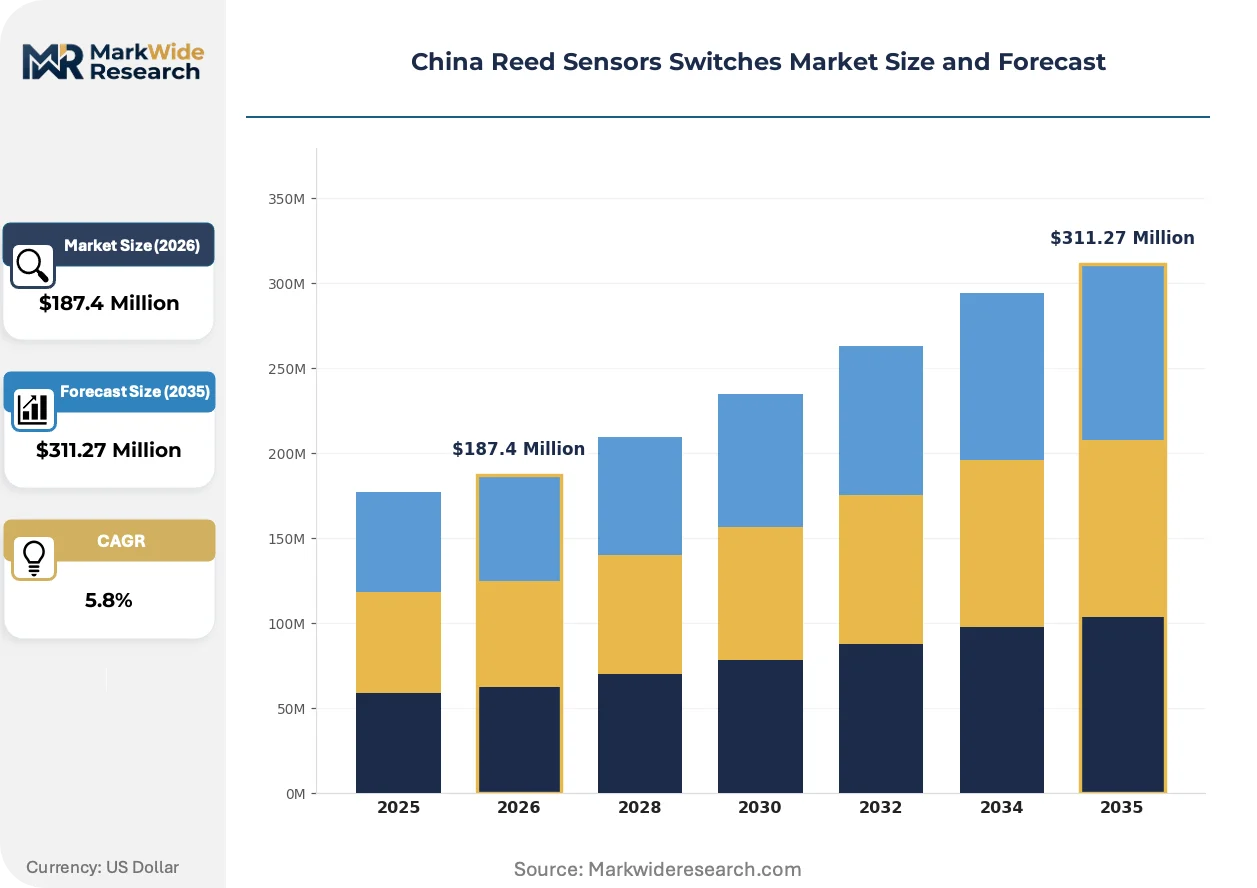
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Reed Switch, Reed Relay, Specialty Reed Switch, Automotive Reed Switch Application: Industrial Automation, Consumer Electronics, Automotive Systems, Security Systems End User: Manufacturers, OEMs, Distributors, Retailers Technology: Solid-state, Analog, Digital, Hybrid |
| Companies Covered | Littelfuse Inc., Standex Electronics, Coto Technology, PIC GmbH, Honeywell International Inc., Zhejiang Xurui Electronic, HSI Sensing, Aleph America, Meder Electronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Reed Sensors Switches Market Strategic Shifts
Magnetic reed switch technology is bifurcating into commodity household appliance segments and premium automotive-medical tiers, with innovation concentrating on contact material science and miniaturization for space-constrained applications.
Surface-mount device reed switches are expanding into wearable health monitoring equipment. Medical OEMs in Shenzhen and Suzhou are adopting 2.5mm pitch SMD variants for glucose monitor lid-detection functions. This form factor is expanding into consumer wellness devices previously served by mechanical microswitches.
China's GB/T 17626 electromagnetic immunity standards are tightening surge withstand requirements for industrial reed relays. SAMR enforcement of updated immunity test levels is forcing redesign of contact alloys and internal magnetic shielding. Factory automation suppliers in Jiangsu province are pre-qualifying products to the 2024 draft standard to avoid retrospective compliance costs.
Buyers in the Yangtze River Delta are consolidating supplier relationships around vertically integrated reed switch manufacturers offering in-house magnet production. Electronics assemblers in Hangzhou and Ningbo now favor single-source contracts covering both sensor and actuator components. This consolidation pattern is most visible among tier-two HVAC control panel manufacturers seeking simplified procurement workflows.
China Reed Sensors Switches Market Segmentation
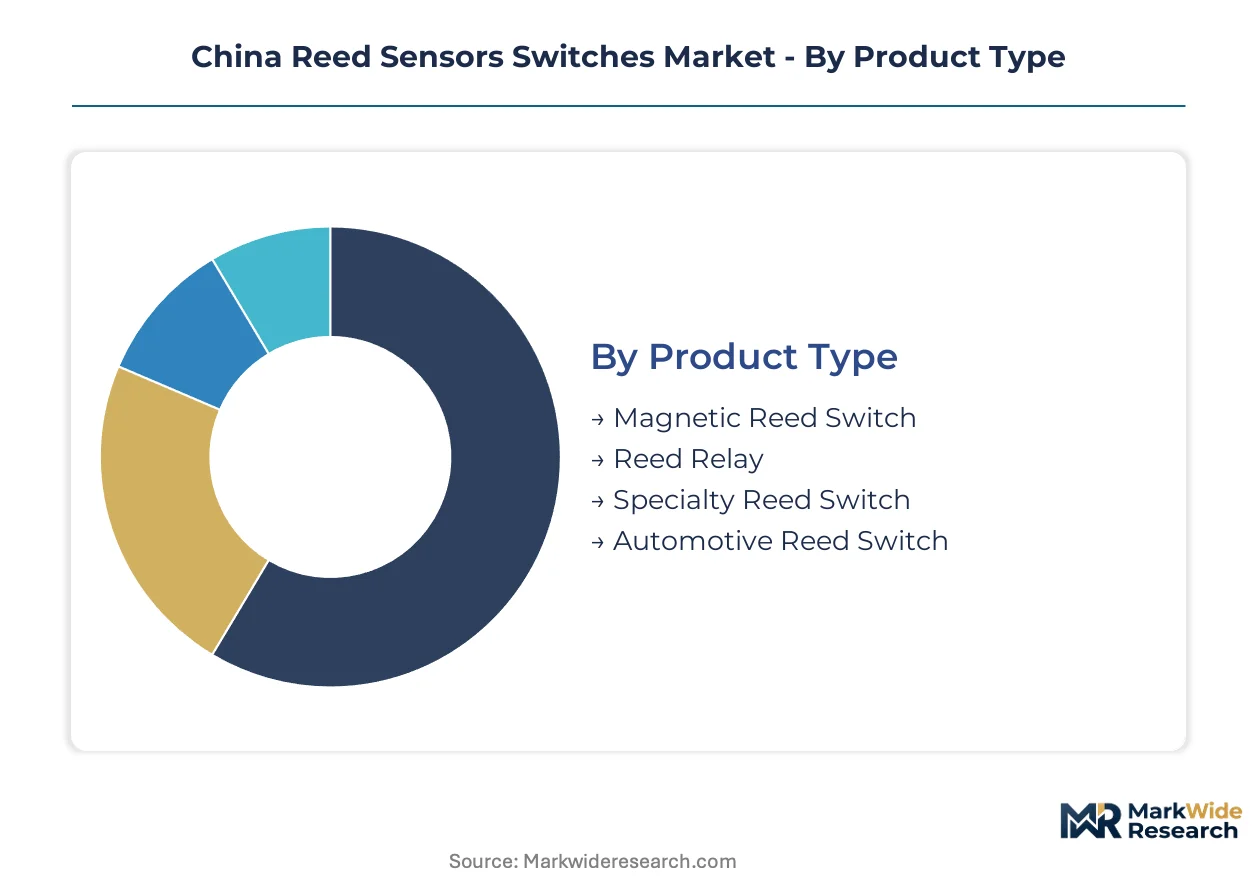
Reed sensor switch segmentation in China reflects divergent commercial logics across product tiers and application environments. Understanding these divides enables suppliers to align certification investments with margin profiles and procurement concentration patterns.
Product Type:
Volume concentration clusters in household appliance and HVAC applications, while premium capture depends on automotive qualification depth.
- Magnetic Reed Switch:Hermetically sealed glass envelopes containing ferromagnetic reeds activate under magnetic field influence, switching voltages from millivolts to hundreds of volts. Demand concentrates in Yangtze River Delta manufacturing corridors for household appliance and HVAC control panel integration, where procurement favors single-source contracts covering both sensor and actuator components.
- Automotive Reed Switch:AEC-Q200 qualified variants withstand thermal cycling and vibration profiles specific to electric vehicle battery management systems. Shenzhen and Suzhou automotive electronics assemblers drive procurement for contactless current sensing and thermal runaway detection functions, though 18-24 month validation cycles strain working capital for tier-two suppliers.
- Reed Relay:Coil-actuated reed switches offering higher current handling for industrial and medical applications. NMPA regulations create additional certification layers for patient-contact equipment deployment.
- Specialty Reed Switch:Miniaturized or radiation-hardened variants for aerospace and diagnostic imaging systems. Medical OEMs in Shenzhen adopt surface-mount device form factors for glucose monitor lid-detection functions.
Mature deployment sits with magnetic reed switches. Newer deployment is concentrated in automotive reed switches.
Application:
Procurement patterns split between coastal saturation and interior expansion opportunities, with certification requirements varying sharply by end-use environment.
- Industrial Automation:Factory automation suppliers in Jiangsu province pre-qualify reed relays to GB/T 17626 electromagnetic immunity standards, redesigning contact alloys and internal magnetic shielding to meet tightened surge withstand requirements. Western China manufacturing bases in Sichuan and Chongqing remain underpenetrated versus coastal corridors.
- Automotive Systems:Electric vehicle manufacturers expand sensor integration for battery management, driving AEC-Q200 qualified demand. MIIT dual carbon policy incentives accelerate replacement of electromechanical switches with lower-power reed alternatives.
- Consumer Electronics:Wearable health monitoring equipment adopts 2.5mm pitch surface-mount device variants, expanding into wellness devices previously served by mechanical microswitches.
- Security Systems:Contactless position detectors and safety interlocks for access control and intrusion detection applications. GB standards compliance creates 4-6 month certification bottlenecks for new product introductions.
Procurement maturity clusters in industrial automation. Steepest expansion trajectory appears in automotive systems.
End User:
Channel structure reflects consolidation around vertically integrated manufacturers versus fragmented distribution networks serving smaller assemblers.
- Manufacturers:In-house production of reed switch assemblies for captive consumption in appliance and automotive control systems. Rare-earth magnet cost volatility compresses margins for assemblies dependent on permanent magnet actuation.
- OEMs:Original equipment manufacturers in Hangzhou and Ningbo consolidate supplier relationships around single-source contracts covering both sensor and actuator components. Electronics assemblers favor simplified procurement workflows from vertically integrated suppliers.
- Distributors:Inventory and technical support functions for mid-tier industrial clients lacking direct supplier relationships. SAMR electromagnetic compatibility testing requirements extend qualification timelines.
- Retailers:Small-volume sales of replacement and hobbyist-grade reed switch products through electronics component channels.
Supply chain control concentrates with manufacturers. Channel expansion is gaining share fastest among OEMs pursuing supplier consolidation.
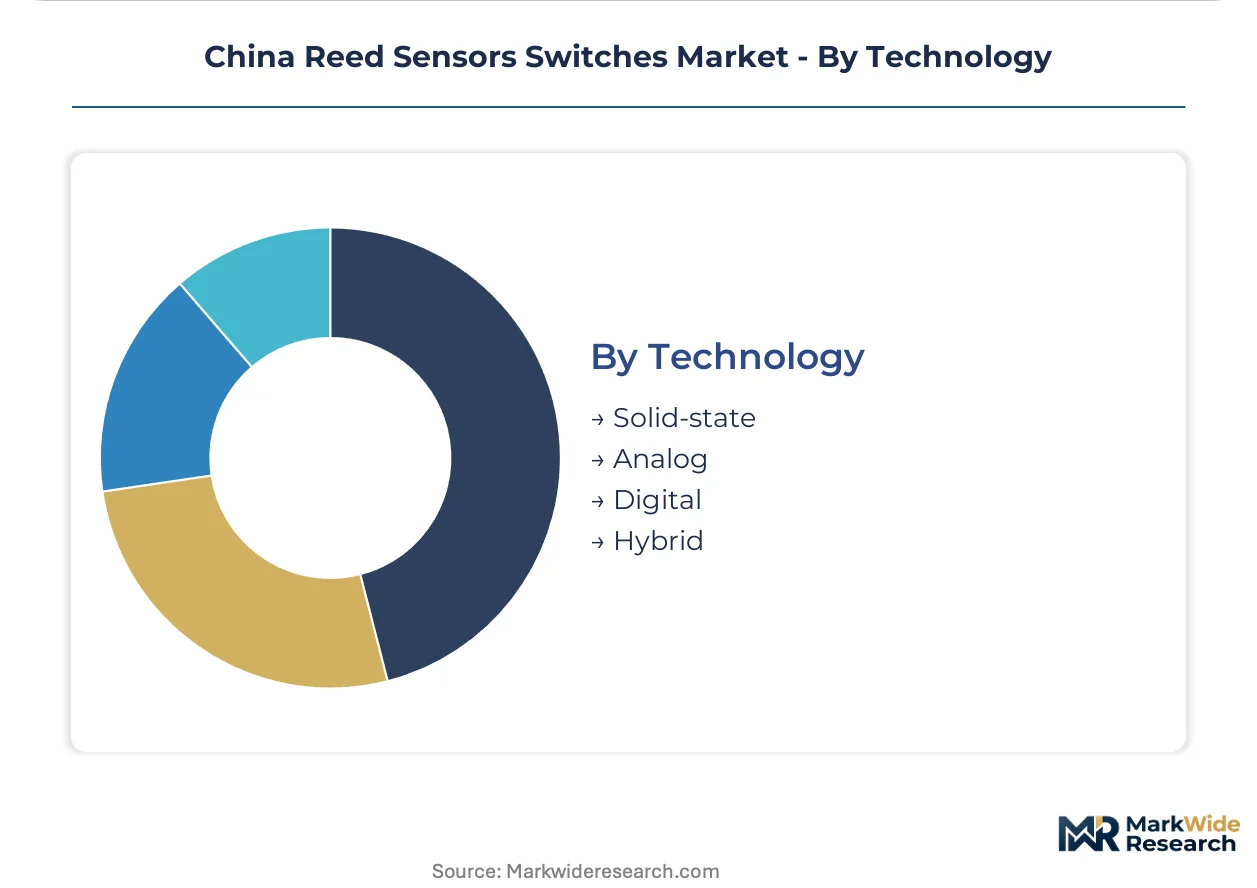
Technology:
Performance requirements and frequency response characteristics determine technology selection, with solid-state alternatives displacing electromechanical solutions in specific switching regimes.
- Solid-state:Hall-effect and magnetoresistive devices displace reed switches in high-frequency switching applications above 10kHz, offering faster response times and longer operational life. Silicon carbide convergence enables new protection architectures in high-voltage EV charging infrastructure.
- Analog:Continuous signal reed switch outputs for position sensing applications requiring proportional response. Industrial automation clients in Jiangsu province specify analog variants for precision level detection.
- Digital:Binary on/off switching outputs for discrete control functions in security and appliance applications. Digital reed switches integrate with microcontroller-based control systems.
- Hybrid:Combined electromechanical and solid-state architectures leveraging reed switch hermetic sealing with semiconductor signal conditioning. Medical device applications in diagnostic imaging systems require hybrid approaches for patient-contact equipment.
Established deployment dominates analog implementations. Technology transition is accelerating most quickly in solid-state substitution for high-frequency applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for reed sensors switches concentrates in China's coastal manufacturing belts, where electronics clusters and automotive assembly plants drive procurement volumes. Provincial industrial policies and GB standards compliance requirements shape supplier access across sub-regional markets.
Yangtze River Delta
Shanghai, Jiangsu, and Zhejiang provinces anchor procurement for household appliance and HVAC control panel integration. SAMR electromagnetic compatibility testing creates 4-6 month certification bottlenecks for new product introductions in this corridor. Electronics assemblers in Hangzhou and Ningbo consolidate supplier relationships around single-source contracts covering both sensor and actuator components.
Pearl River Delta
Guangdong province drives demand for surface-mount device reed switches in wearable health monitoring equipment. Shenzhen medical OEMs adopt 2.5mm pitch SMD variants for glucose monitor lid-detection functions. Factory automation suppliers in Dongguan pre-qualify products to GB/T 17626 electromagnetic immunity standards to avoid retrospective compliance costs.
Beijing-Tianjin-Hebei
Automotive battery management systems procurement expands for AEC-Q200 qualified reed switches in electric vehicle manufacturing. MIIT dual carbon policy incentives accelerate replacement of electromechanical switches with lower-power alternatives. Beijing-based automotive electronics assemblers specify contactless current sensing and thermal runaway detection functions.
Sichuan-Chongqing
Western China manufacturing bases remain underpenetrated for industrial reed sensor deployment versus coastal saturation. Chongqing's growing automotive sector creates emerging demand for automotive-grade variants. Provincial green manufacturing audits under MEE oversight condition supplier qualification timelines.
Shandong Peninsula
Industrial automation clients in Qingdao and Yantai specify analog reed switch variants for precision level detection. Rare-earth magnet cost volatility compresses margins for assemblies dependent on permanent magnet actuation. Local manufacturers face GB standards compliance friction extending product introduction cycles.
China Reed Sensors Switches Market Competitive Environment
Supplier consolidation dominates the current landscape as buyers favor vertically integrated manufacturers offering in-house magnet production. The vendor base fragments across three tiers: multinational component houses with automotive certification depth, mid-scale specialists serving industrial automation, and regional fabricators competing on proximity to downstream electronics clusters. Two strategic archetypes have emerged: premium-positioned players leveraging AEC-Q200 qualification and cost-optimized suppliers capturing household appliance volume. Competitive moves concentrate on backward integration into magnet supply and consolidation of testing partnerships with SAMR-accredited laboratories.
Among multinational component houses, Littelfuse Inc. and Standex Electronics occupy positions defined by certification breadth and manufacturing scale. Littelfuse Inc. exemplifies the premium-tier archetype through its automotive qualification depth. Standex Electronics anchors the scale-driven segment with dedicated facility structures. Zhejiang Xurui Electronic represents the regional specialist tier, competing on proximity to Zhejiang province electronics clusters. These three players illustrate the competitive spectrum: global certification leverage, manufacturing scale, and geographic adjacency to demand.
| Leading Market Players |
|---|
| Littelfuse Inc. |
| Standex Electronics |
| Coto Technology |
| PIC GmbH |
| Honeywell International Inc. |
| Zhejiang Xurui Electronic |
| HSI Sensing |
| Aleph America |
| Meder Electronic |
| Others |
Value Chain & Pricing Dynamics
Backward integration into rare-earth magnet production anchors supply position and pricing power for reed switch manufacturers serving Yangtze River Delta electronics clusters. SAMR electromagnetic compatibility certification costs create fixed compliance burdens that favor scaled players with captive testing partnerships, compressing margin flexibility for smaller fabricators competing on proximity rather than vertical control.
Pricing Analysis
Volume-margin splits separate household appliance commodity tiers from automotive-medical premium capture. Three-tier pricing structure across AEC-Q200 certified, industrial-grade, and economy appliance levels reflects certification depth and hermetic sealing precision. Pricing pressure stems from neodymium and samarium-cobalt magnet cost volatility feeding raw material uncertainty into assembly quotes. Tier-two HVAC control panel manufacturers exhibit highest price sensitivity, while Shenzhen medical OEMs accepting NMPA-qualified hermetic relays show lowest elasticity.
Supply Chain Analysis
Returns and refurbishment flows remain minimal for hermetically sealed reed switches given glass envelope fragility and contamination risks in medical applications. Manufacturing concentrates in China, Japan, and Germany with Zhejiang province hosting dense downstream electronics assembly ecosystems. Raw material dependencies center on borosilicate glass tubing, rhodium-plated ferromagnetic reeds, and rare-earth permanent magnets. Single-source vulnerability sits with aging glass-to-metal seal technician cohorts in legacy manufacturing regions. Distribution runs through vertically integrated manufacturers offering bundled sensor-actuator contracts to Yangtze River Delta OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's reed sensors switches market operates as a cost-of-compliance arena where SAMR electromagnetic compatibility testing creates 4-6 month certification bottlenecks that moat qualified incumbents against unvalidated entrants.
For Market Incumbents: Extend AEC-Q200 qualification depth into emerging silicon carbide power module integration for EV charging infrastructure protection architectures. Consolidate testing partnerships with SAMR-accredited laboratories to compress validation timelines. Solid-state magnetic sensor substitution above 10kHz switching frequencies threatens commodity reed switch volume; defend position through captive magnet production and single-source contract structures with Hangzhou and Ningbo electronics assemblers. For New Entrants and Emerging Players: The premium-economy price-point gap in automotive reed switches creates entry space for mid-tier specialists. Western China industrial automation in Sichuan and Chongqing manufacturing bases remains underpenetrated versus coastal saturation. Target medical device certification white space for hermetically sealed reed relays in diagnostic imaging systems. Go-to-market leverage rests on proximity to Shenzhen and Suzhou medical OEM clusters with NMPA regulatory navigation capabilities. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational component houses seeking automotive certification breadth and Yangtze River Delta manufacturing footprint. Long-term viability favors vertically integrated manufacturers with in-house magnet production and SAMR testing partnerships over pure-play fabricators. Acquisition target archetype: mid-scale Jiangsu province suppliers with GB/T 17626 pre-qualification capabilities and established OEM relationships. Monitor GB standard revision drafts and provincial green manufacturing audit schedules as inflection indicators for compliance cost shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Production | Captive rare-earth supply insulates margin compression from neodymium price volatility. |
| SAMR-Accredited Testing Partnership Consolidation | Compressed 4-6 month certification timelines accelerate new product introduction velocity. |
| AEC-Q200 Qualification Depth Expansion | Premium positioning in EV battery management systems commands margin over household appliance tiers. |
| Surface-Mount Device Form Factor Development | 2.5mm pitch variants penetrate Shenzhen wearable health monitoring equipment procurement. |
| Western China Geographic Expansion | Sichuan and Chongqing manufacturing bases offer industrial automation white space versus coastal saturation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with reed switch manufacturing plant managers, automotive Tier 1 supplier procurement leads, SAMR-accredited laboratory technical directors, and medical device OEM sourcing executives combined with MIIT policy documents, GB standards revision drafts, and NMPA medical device registration databases. Bottom-up demand modeling triangulated against top-down industrial output metrics to validate segment-level estimates.
Data-stream reconciliation across shipment volumes, certification timelines, and raw material price indices informed projection construction. Segmentation dimensions modeled include product type, application environment, end-user channel structure, and technology architecture across the analysis window. CAGRs derived from regression analysis against industrial automation capital expenditure cycles, electric vehicle production trajectories, and smart grid infrastructure deployment schedules. Industry-specific forecast inputs incorporated glass-to-metal seal technician cohort demographics and rare-earth magnet price volatility bands.
Inputs from SAMR enforcement bulletins and MIIT dual carbon policy guidance were available through the study window; gaps in real-time Western China manufacturing base penetration metrics introduce uncertainty bands for Sichuan-Chongqing expansion trajectories. Forecasts reflect documented assumptions regarding GB standards implementation timelines and AEC-Q200 validation cycle stability. Practitioners should monitor draft GB/T 17626 electromagnetic immunity standard revisions and provincial MEE green manufacturing audit announcements for early signals of compliance cost inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
DC Circuit Breaker Market
Switches
Canada Switch Gear Market
Switches
Matrix Switches Market
Switches
Europe Push Buttons and Signaling Devices Market
Switches
Surface Mount Switch Market
Switches
Optical Cross Connect (OXC) Switches Market
Switches
APAC Push Buttons and Signaling Devices Market
Switches
Contactor-based Transfer Switch Market
Switches
Paralleling Switchgear Market
Switches
Australia Switchgear Market
Switches
Haptic Feedback Switch and Button Platforms Market
Switches
Optical Switches Market
Switches
Miniature-Circuit Breaker Market
Switches
Global High Voltage Switchgear Market
Switches
High-Voltage Disconnect Switch Market
Switches
Global Float Level Switches Market