
 North America Low Voltage Switchgear Market | 2026-2036
North America Low Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Low Voltage Switchgear Market Insights
Multi-source procurement among utilities and large industrials is expanding as buyers diversify supply risk across North American manufacturing footprints. Schneider Electric leverages its integrated digitized solutions portfolio to anchor premium positions in data center switchgear. Siemens competes through deep manufacturing scale across circuit breaker and motor control center lines. Eaton sustains channel control via extensive distributor networks serving commercial and infrastructure end users.
North America low voltage switchgear encompasses electrical distribution apparatus rated up to 1,000 volts AC or 1,500 volts DC, comprising molded-case and air circuit breakers, busbar assemblies, protective relays, and arc-flash containment enclosures fabricated from cold-rolled steel with powder-coat insulation. These systems isolate fault currents, enable load switching, and protect downstream equipment across commercial buildings, manufacturing plants, and critical infrastructure. Circuit breakers command the largest product type position due to replacement cycles in aging commercial stock, while smart switchgear represents the fastest-growing technology segment as remote monitoring and predictive maintenance capabilities displace traditional electromechanical platforms. Panelboards retain mature margin pools in renovation-driven commercial construction, though data center end users are shifting specification priority toward integrated control architectures.
The National Electrical Manufacturers Association coordinates voluntary standards with OSHA electrical safety mandates to shape arc-flash and short-circuit withstand requirements across U.S. installations. Health Canada and the Canadian Standards Association enforce parallel certification pathways that condition market access for cross-border suppliers. Stakeholders must monitor how NEMA and CSA alignment on digitized product standards evolves, as divergence would fragment certification costs for vendors serving both markets.
Market Dynamics
Data center operators across the United States and Canada are accelerating procurement of smart switchgear systems as EPA energy efficiency mandates and IoT-enabled monitoring platforms reshape product specifications. Utility-scale renewable interconnection projects in Texas and hyperscale campus expansions are concentrating breaker and switchboard orders.
Growth Catalysts
- EPA energy efficiency mandates:Evolving federal standards are forcing commercial building operators to replace aging electromechanical distribution equipment with intelligent load management systems.
- Hyperscale data center construction:Cloud infrastructure operators in Texas and Virginia are specifying integrated switchgear architectures with remote monitoring capabilities for campus expansions.
- Utility-scale renewable interconnection:Solar and wind projects across the ERCOT grid require low voltage switchgear capable of bidirectional power flow and rapid fault isolation.
Market Restraints
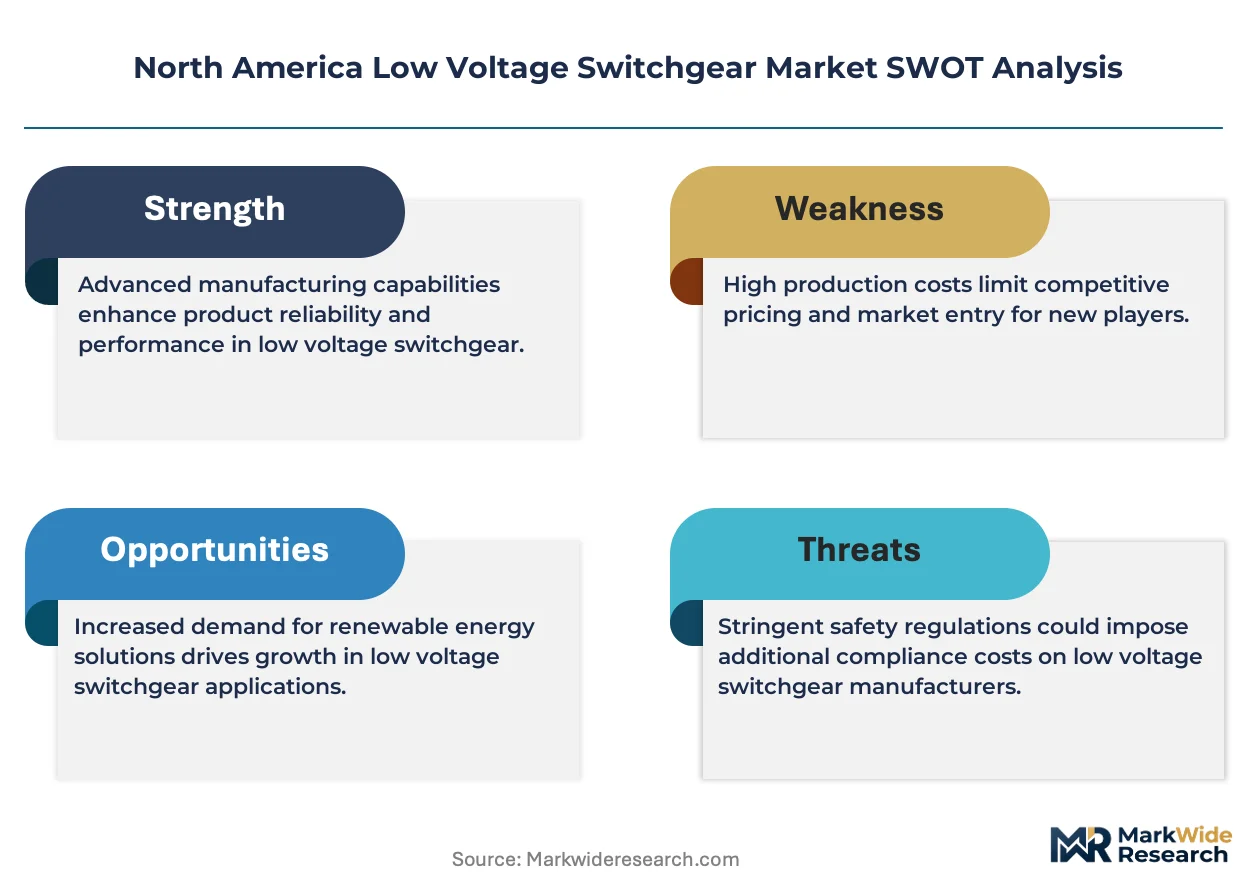
- Copper and cold-rolled steel price volatility:Raw material input costs for busbar assemblies and enclosures fluctuate with commodity markets, compressing fabrication margins.
- Concentrated domestic manufacturing:Circuit breaker production clusters in the Midwest create geographic supply risk during regional logistics disruptions.
- NEMA-CSA standard divergence risk:Misalignment between U.S. and Canadian certification pathways would fragment compliance costs for cross-border vendors.
Strategic Opportunities
- Canadian smart grid modernization:Hydro-Québec and Ontario's IESO are deploying advanced distribution management systems requiring digitized switchgear with embedded sensors.
- Edge computing facility buildout:Micro data centers in secondary U.S. markets need compact, pre-integrated switchgear skids with factory-installed monitoring.
- OSHA arc-flash safety mandates:Stricter enforcement of NFPA 70E workplace standards is accelerating replacement of legacy panelboards with arc-resistant enclosures.
Industry Challenges
- Electrical engineering talent scarcity:Shortages of power systems specialists with arc-flash coordination expertise delay project commissioning timelines.
- Legacy electromechanical integration:Retrofitting smart monitoring into existing MCC lineups without disrupting continuous operations requires complex phased cutover planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Low Voltage Switchgear Market |
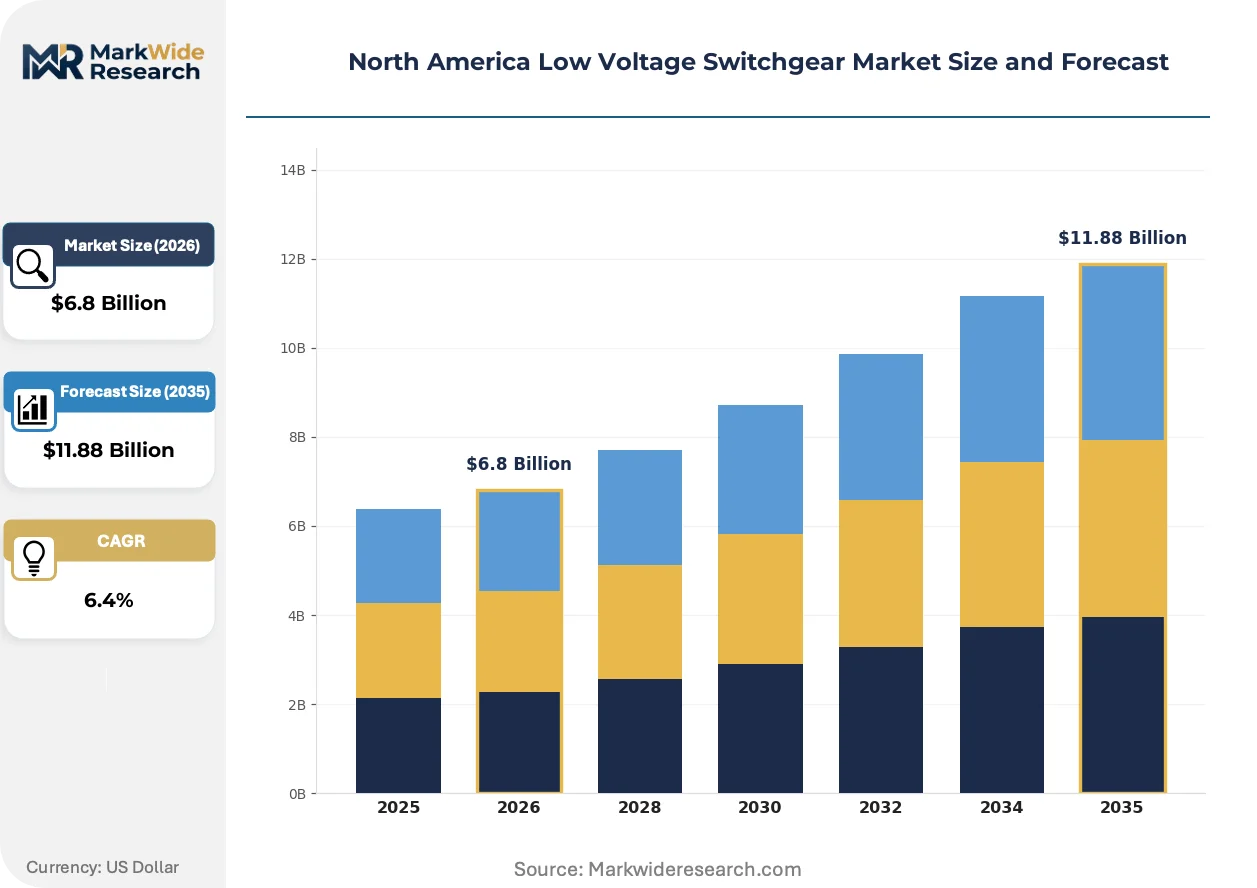
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panelboards, Motor Control Centers, Circuit Breakers, Switchboards End User: Commercial, Industrial, Infrastructure, Data Centers Technology: Smart Switchgear, Traditional Switchgear, Digitized Solutions, Integrated Control Installation Type: Indoor, Outdoor, Modular, Custom Solutions |
| Companies Covered | General Electric, Rockwell Automation, Schneider Electric, Hitachi, Mitsubishi Electric Corporation, Siemens, Eaton, Fuji Electric, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Low Voltage Switchgear Market Trends and Innovations
Digitalization is actively reshaping competitive positioning across North American low voltage switchgear as embedded sensors and edge computing displace traditional maintenance models. Specification priorities are pivoting toward predictive capabilities and remote operability.
IoT-enabled thermal monitoring and partial discharge detection is expanding into mission-critical infrastructure applications. Data center operators in Northern Virginia and Dallas-Fort Worth are mandating these capabilities in new construction specifications. The technology is expanding into service contract structures as OEMs bundle continuous diagnostics with hardware sales.
OSHA's intensified enforcement of NFPA 70E arc-flash protection standards is compelling facility managers to upgrade protective relay coordination. Industrial plants in the Midwest are accelerating MCC replacement cycles to comply with incident energy reduction mandates. Food processing and automotive assembly facilities are responding fastest due to high personnel density on production floors.
Buyers are consolidating vendor relationships around full-lifecycle service agreements rather than transactional equipment procurement. Large industrials in the Texas Gulf Coast petrochemical corridor are unbundling maintenance from capital budgets and contracting directly with OEM service arms. This pattern is most visible in continuous-process industries where unplanned outages carry seven-figure revenue impacts.
North America Low Voltage Switchgear Market Segmentation
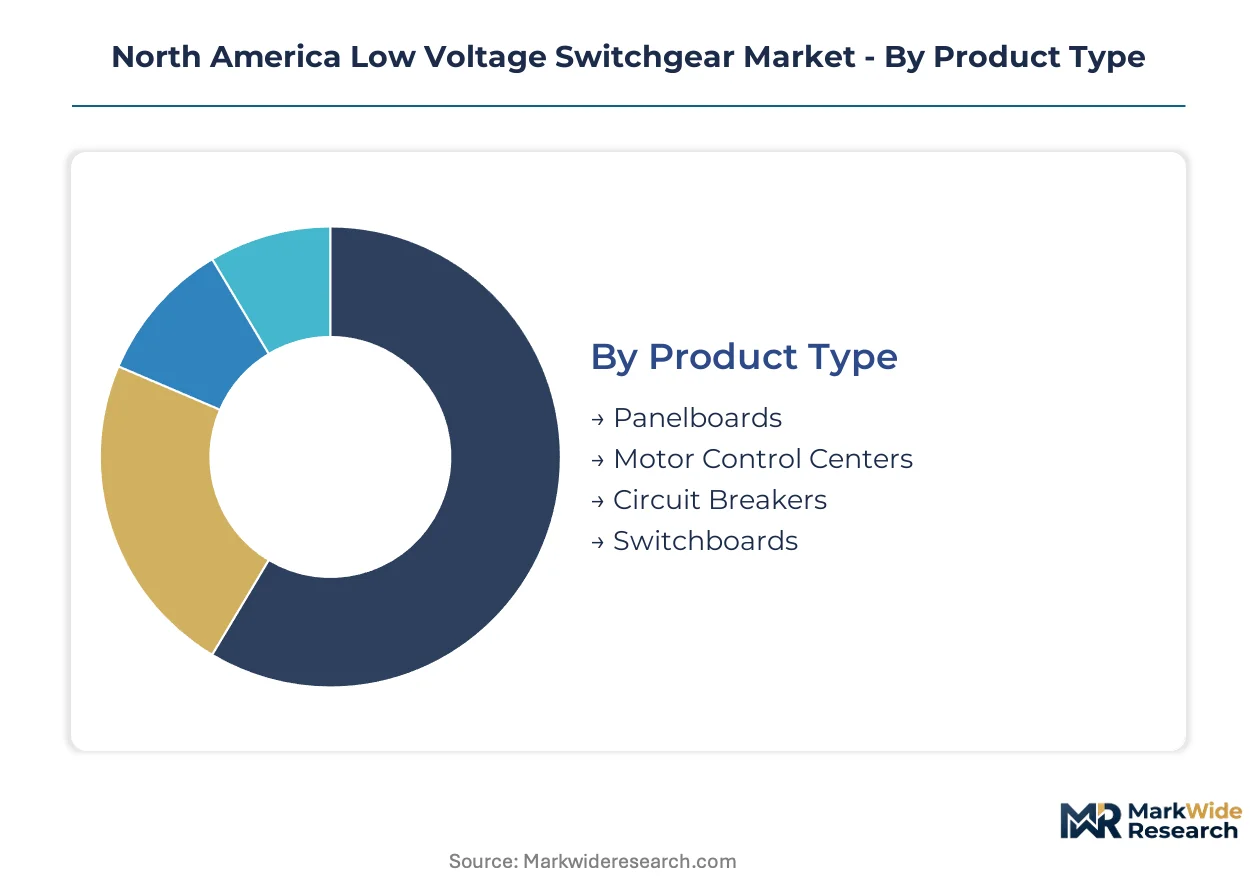
Segmentation in low voltage switchgear reveals distinct capital deployment patterns across product architectures, end-use applications, and installation methodologies. Procurement specifications diverge sharply between mission-critical data center operators seeking integrated intelligence and commercial building owners prioritizing replacement cost minimization.
Product Type:
Circuit breakers and switchboards command the highest upfront capital intensity due to raw material content in copper busbar assemblies and arc-flash containment engineering.
- Circuit Breakers:Molded-case and air circuit breakers rated up to 1,000V AC incorporate thermal-magnetic or electronic trip units with adjustable instantaneous and long-time protection curves. Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth is concentrating procurement of intelligent breakers with embedded power quality monitoring and remote racking capabilities.
- Switchboards:Freestanding or wall-mounted assemblies integrate main and distribution breakers with busbar systems fabricated from cold-rolled steel enclosures. ERCOT utility-scale renewable interconnection projects in Texas are driving orders for switchboards capable of bidirectional power flow and rapid fault isolation in solar and wind farm collector substations.
- Panelboards:Compact distribution assemblies serve branch circuit protection in commercial renovation projects where space constraints limit equipment footprint.
- Motor Control Centers:Enclosed assemblies of motor starters, variable frequency drives, and protective devices serve industrial process automation with standardized vertical sections.
Circuit breakers absorb the bulk of installed capacity; switchboards are expanding most quickly.
End User:
Application requirements stratify across customer types, with data center operators accepting premium pricing for predictive maintenance architectures unavailable to commercial building portfolios.
- Data Centers:Hyperscale and colocation operators specify integrated switchgear with IoT-enabled thermal monitoring, partial discharge detection, and digital twin compatibility for campus-wide energy management. Northern Virginia's Ashburn-Dulles corridor and Dallas-Fort Worth's Irving-Lewisville cluster anchor procurement volume.
- Industrial:Petrochemical facilities along the Texas Gulf Coast and automotive assembly plants in Michigan and Ohio prioritize arc-resistant enclosures and NFPA 70E compliance for personnel protection in high-density production environments.
- Commercial:Office buildings, retail centers, and hospitality properties drive replacement cycles in aging electrical infrastructure with cost-optimized panelboard and breaker specifications.
- Infrastructure:Airports, hospitals, and water treatment facilities require seismic-rated and emergency power-compatible switchgear with extended temperature operating ranges.
Industrial end users maintain the largest installed base; data centers show the steepest expansion trajectory.
Technology:
Technology selection determines lifecycle service revenue potential, with digitized platforms enabling multi-year diagnostic contracts absent from electromechanical alternatives.
- Smart Switchgear:Embedded sensors, edge computing nodes, and cloud-connected analytics platforms enable predictive maintenance and remote operability. Data center operators are mandating these capabilities in new construction specifications across the United States and Canada.
- Digitized Solutions:Retrofit sensor packages and communication modules upgrade legacy breaker lineups without full equipment replacement, serving industrial facilities with continuous-process constraints.
- Integrated Control:Factory-preconfigured switchgear skids with pre-installed monitoring, power distribution units, and busway connections reduce field commissioning time for edge computing facilities.
- Traditional Switchgear:Electromechanical protection and manual operation persist in cost-sensitive commercial applications with limited maintenance staffing.
Traditional switchgear retains the largest installed footprint; smart switchgear is gaining share fastest.
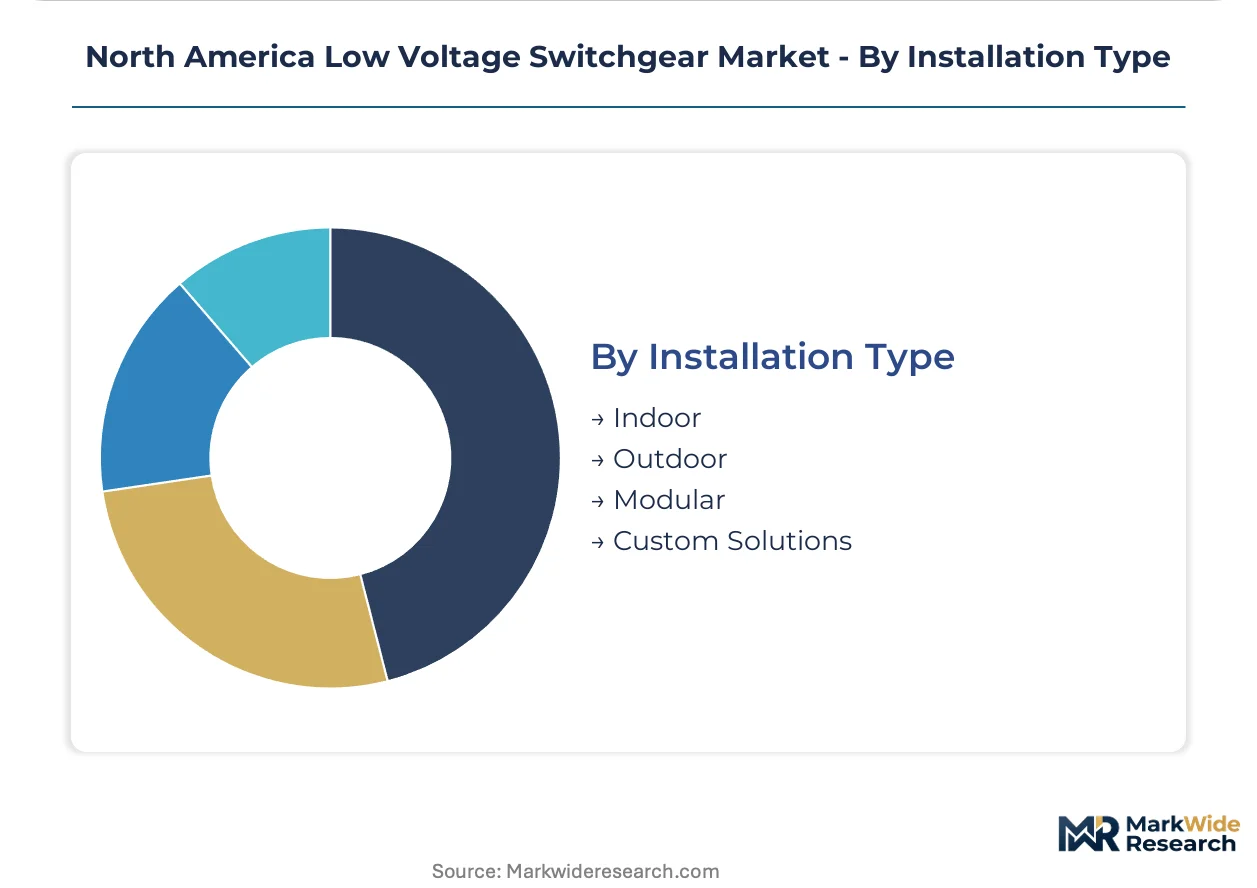
Installation Type:
Installation methodology shapes project delivery economics, with modular and factory-integrated approaches compressing field labor hours in tight construction windows.
- Indoor:Climate-controlled electrical rooms and switchgear vaults in commercial buildings and data centers house standard NEMA 1 or NEMA 12 enclosures with standard ventilation.
- Outdoor:NEMA 3R and 4X rated enclosures with space heating and thermostatic cooling serve renewable energy collector substations and remote infrastructure applications.
- Modular:Pre-engineered electrical houses and e-houses with integrated HVAC, fire suppression, and switchgear reduce site construction duration for industrial expansions.
- Custom Solutions:Application-specific enclosures, busbar configurations, and control interfaces address non-standard voltage requirements or severe service environments.
Indoor installations dominate current capacity; modular solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining corridors in Arizona and Utah anchor raw material security for North American busbar fabrication, while cold-rolled steel supply from Indiana and Ohio mills underpins enclosure manufacturing across the continent.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth concentrates intelligent breaker procurement with embedded power quality monitoring. EPA energy efficiency mandates under the Clean Air Act drive commercial building operators toward intelligent load management retrofits. ERCOT grid expansion across Texas utility-scale solar and wind projects demands switchgear capable of bidirectional power flow and rapid fault isolation.
Canada
Hydro-Québec and Ontario's IESO deploy advanced distribution management systems requiring digitized switchgear with embedded thermal sensors. Health Canada and CSA certification pathways condition cross-border market access for U.S. suppliers serving provincial utilities. Toronto-Waterloo corridor data center buildouts specify factory-integrated switchgear skids with pre-installed monitoring for edge computing facilities.
Mexico
Nearshoring of automotive and electronics manufacturing to Nuevo León and Baja California drives motor control center demand for plant automation. CFE grid modernization programs require low voltage distribution equipment compatible with renewable interconnection standards. Tijuana-Mexicali industrial parks anchor contract manufacturing demand for cost-optimized panelboard specifications.
North America Low Voltage Switchgear Market Competitive Landscape
Capacity expansion dominates the current landscape as incumbent suppliers scale manufacturing footprints to serve data center and renewable energy procurement waves. The vendor base stratifies across three tiers: integrated multinational OEMs with full digitized portfolios, regional specialists with deep distributor channel control, and modular system integrators serving rapid-deployment industrial projects. Strategic archetypes include full-lifecycle service providers bundling predictive maintenance contracts, premium-positioned smart switchgear specialists, and cost-optimized fabricators serving commercial renovation cycles. M&A activity and strategic partnerships represent the dominant competitive moves, with players acquiring sensor technology capabilities and forming alliances with cloud infrastructure operators.
Among integrated multinational OEMs, Schneider Electric SE and Siemens AG exemplify the premium-tier archetype through digitized solutions portfolios, while Eaton Corporation plc anchors the extensive distributor network model serving commercial and infrastructure end users. These three entities occupy positions spanning the full technology spectrum from traditional electromechanical platforms to IoT-enabled predictive maintenance architectures, representing the competitive template against which regional specialists and modular integrators define differentiation.
| Leading Market Players |
|---|
| General Electric |
| Rockwell Automation |
| Schneider Electric |
| Hitachi |
| Mitsubishi Electric Corporation |
| Siemens |
| Eaton |
| Fuji Electric |
| ABB |
| Others |
Pricing and Supply Chain Analysis
Smart-electromechanical capability divergence between intelligent switchgear with embedded IoT architectures and traditional breaker platforms manifests in both pricing power and supply chain sourcing patterns. Premium-tier vendors bundle predictive maintenance subscriptions with hardware sales, while commodity fabricators compete on copper busbar weight and cold-rolled steel gauge alone.
Pricing Analysis
Warranty and service-bundling arrangements separate full-lifecycle contracts from transactional equipment sales across the North American market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and embedded sensor density. Price differentiation stems from UL 489 arc-flash testing compliance and remote monitoring capability integration. Cost compression in economy-tier panelboard segments is intensifying because of raw material spot market volatility. Commercial building renovators exhibit highest price sensitivity, while hyperscale data center operators accept premium positioning for predictive maintenance architectures.
Supply Chain Analysis
NEMA and CSA certification gating restricts qualified supplier pools to manufacturers with dual-standards testing infrastructure. Circuit breaker production concentrates in the United States, Mexico, and Canada, with busbar fabrication anchored in Arizona and Indiana copper corridors. Raw material dependencies center on copper cathode, cold-rolled steel coil, and epoxy resin powder coatings. Single-source vulnerability in Midwest breaker manufacturing clusters creates geographic concentration risk during regional logistics disruptions. Distribution runs through electrical wholesale distributors serving contractor and industrial maintenance channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as copper price volatility and certification compliance costs force sub-scale fabricators toward strategic exits. EPA efficiency mandates and IoT specification requirements raise capital barriers beyond smaller regional players.
For Market Incumbents: Acquire sensor technology capabilities and cloud analytics platforms to anchor full-lifecycle service contracts. Backward integration into copper busbar fabrication secures margin control against commodity volatility. Channel control through exclusive distributor relationships defends position against modular system integrators entering rapid-deployment industrial segments.
For New Entrants and Emerging Players: The price-point gap between premium smart switchgear and economy panelboard tiers opens white-space targeting opportunities. Unbundled retrofit sensor packages for legacy motor control centers in continuous-process industries offer the most penetrable entry vector. Direct contracting with OEM service arms bypasses established distributor networks.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated multinational OEMs seeking regional manufacturing footprints. Long-term viability favors targets with established CSA certification pathways and data center customer relationships. Monitor EPA enforcement intensity on Clean Air Act efficiency mandates as the critical inflection signal for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Platform Acquisition | Embedded thermal monitoring capabilities anchor multi-year predictive maintenance contracts with hyperscale operators. |
| CSA Certification Investment | Dual NEMA-CSA testing infrastructure unlocks cross-border procurement from Hydro-Québec and Ontario IESO modernization programs. |
| Copper Busbar Backward Integration | In-house fabrication of cold-rolled copper assemblies insulates margins from LME price volatility in construction cycles. |
| Modular E-House Manufacturing Scale-Up | Pre-engineered electrical houses with integrated HVAC compress field commissioning windows for ERCOT renewable interconnection projects. |
| Edge Computing Facility Partnership | Factory-integrated switchgear skids with pre-installed monitoring capture micro data center buildouts in secondary U.S. markets. |
Research Methodology
NEMA technical standards filings, EIA electricity consumption surveys, and SEC 10-K equipment supplier disclosures formed the secondary backbone for market sizing and competitive positioning. Primary interviews with data center engineering directors, electrical contractor procurement managers, utility interconnection planners, and industrial maintenance supervisors validated specification trends and replacement cycle timing. Bottom-up and top-down triangulation cross-checked shipment volumes against capital expenditure disclosures from hyperscale operators and renewable project developers.
Bottom-up modeling of circuit breaker, switchboard, and panelboard unit shipments across product architectures anchored volume estimates, while top-down macroeconomic drivers shaped price trajectory assumptions across the projection horizon. Segmentation dimensions included product type, end-use application, technology tier, and installation methodology. CAGRs were derived from regression analysis against historical utility capital expenditure patterns and data center construction permit data. Forecast inputs incorporated EPA regulatory enforcement schedules and copper futures curve expectations.
Inputs from NEMA shipment databases and utility interconnection queues were available through the study window; gaps in real-time project cancellation data introduce uncertainty bands around near-term order flow estimates. Forecasts reflect assumptions regarding sustained hyperscale data center construction intensity and continued ERCOT renewable interconnection queue advancement. A model refresh is warranted upon material change in EPA Clean Air Act enforcement priorities or copper price volatility exceeding historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Global Safety Switches Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
Fixed Switch Cabinet Market
Switches
Smart Circuit Breaker Market
Switches
Differential Pressure Switches Market
Switches
Argentina Automotive Reed Sensors Switches Market
Switches
Paralleling Switchgear Market
Switches
Global High Voltage Switchgear Market
Switches
DC Switchgear Market
Switches
Ethernet Switch Market
Switches
Matrix Switches Market
Switches
South America Low Voltage Switchgear Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Hazardous Location Limit Switches Market
Switches
Intelligent Power Switches Market
Switches
Europe Low Voltage Switchgear Market