
 Cross Point Switch Market | 2026-2036
Cross Point Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Cross Point Switch Market Analysis
Software-defined configuration layers are broadening what cross point switch vendors monetize beyond hardware shipments. Analog Devices Inc. leverages its mixed-signal portfolio to anchor premium positions in precision routing applications. Lattice Semiconductor Corporation specializes in low-power programmable matrices for edge-computing environments. Texas Instruments Inc. dominates industrial-grade switch segments through captive foundry capacity and temperature-hardened designs.
A cross point switch is an integrated circuit that establishes programmable electrical pathways between multiple input and output ports, typically achieving switching speeds below 10 nanoseconds with crosstalk isolation exceeding 60 dB in high-performance variants. Its primary purpose is enabling dynamic signal routing in systems where physical rewiring is impractical, from broadcast video infrastructure to military communications backplanes. Digital switches command the largest revenue pool due to compatibility with modern serialized data protocols, while matrix switches capture expanding share in test-and-measurement environments requiring non-blocking full-connectivity architectures. Fiber optics technology segments attract premium pricing as coherent optical interfaces displace copper backplanes in hyperscale data centers.
FCC equipment authorization requirements shape electromagnetic compatibility benchmarks for switches deployed in US telecommunications infrastructure, while REACH substance restrictions in Europe constrain plating chemistries and flame-retardant formulations used in PCB assemblies. China's GB standards and MIIT certification protocols create parallel compliance tracks for vendors serving state-backed 5G buildouts. Stakeholders must monitor divergence between regional semiconductor subsidy regimes as these determine where captive fabrication capacity gets allocated across competing switch architectures.
Market Dynamics
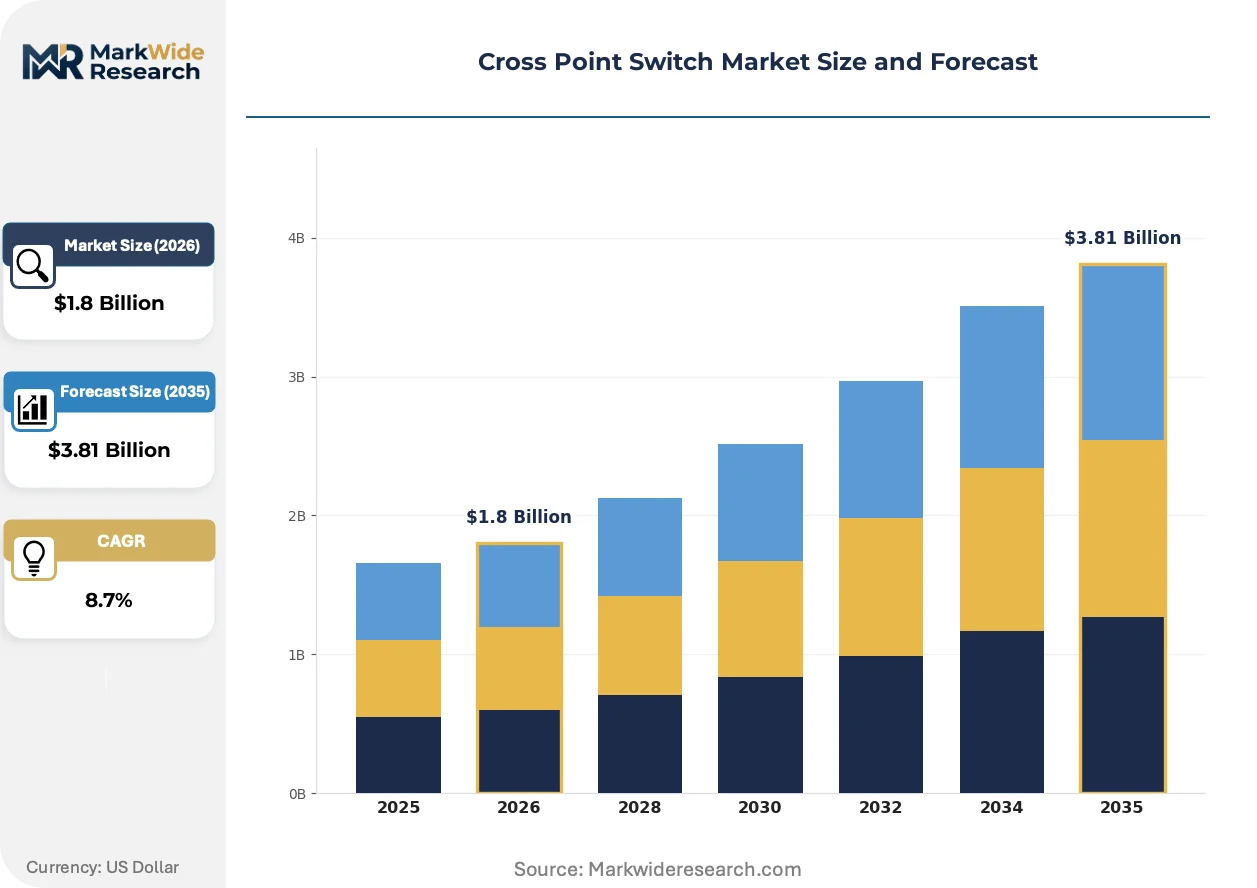
Hyperscale data center operators are consolidating procurement around high-density switching matrices, forcing vendors to reconfigure foundry allocation toward 400G+ coherent optical interfaces while navigating divergent semiconductor subsidy regimes across major economies.
Growth Catalysts
- MIIT Domestic Sourcing Mandates:China's Ministry of Industry and Information Technology procurement rules for state-backed 5G infrastructure are redirecting supply chain configurations toward captive domestic fabrication capacity.
- Coherent Optical Displacement:Fiber optics technology segments attract premium pricing as optical interfaces replace copper backplanes in hyperscale data center buildouts.
- Edge Computing Density Requirements:Low-power programmable matrix demand from distributed inference clusters is expanding addressable volume beyond traditional broadcast and military backplane applications.
Market Restraints
- Plating Chemistry Constraints:REACH substance restrictions in Europe constrain flame-retardant formulations and plating chemistries used in PCB assemblies, elevating compliance costs for non-EU vendors.
- Foundry Concentration Risk:Advanced node capacity for precision routing applications concentrates in Taiwan and South Korea, exposing supply security to geopolitical friction.
- Signal Integrity Limitations:Crosstalk isolation above 60 dB in high-port-count matrices requires exotic substrate materials that inflate bill-of-materials costs disproportionately.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentive schemes for electronics manufacturing are attracting switch module assembly investments to serve domestic 5G and data center buildouts.
- Software-Defined Monetization:Configuration layer licensing creates recurring revenue streams beyond hardware shipment economics, particularly in broadcast infrastructure refresh cycles.
- Automotive Ethernet Convergence:Zonal architecture adoption in electric vehicles is opening new demand for automotive-grade switching matrices with temperature-hardened specifications.
Industry Challenges
- Multi-Standard Certification Burden:Parallel compliance tracks for FCC equipment authorization, GB standards, and REACH create elongated qualification timelines that compress product refresh windows.
- Mixed-Signal Talent Scarcity:Design of precision routing applications requires rare expertise spanning RF, digital, and analog domains, constraining R&D velocity at mid-tier vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross Point Switch Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Switches, Digital Switches, Matrix Switches, Video Switches Application: Broadcasting, Data Centers, Telecommunications, Military Technology: Fiber Optics, Electric, Hybrid, Wireless End User: Telecom Operators, Content Providers, Government Agencies, Enterprises |
| Companies Covered | Analog Devices Inc., Lattice Semiconductor Corporation, Texas Instruments Inc., MACOM Technology Solutions, Broadcom Inc., ON Semiconductor, Arrow Electronics, Inc, Avnet, Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross Point Switch Market Emerging Trajectories
Silicon photonics integration and software-defined configuration layers are compressing traditional hardware-centric business models while regulatory divergence across major economies fragments certification pathways.
Silicon photonics-based switching matrices combine optical and electronic functions on monolithic substrates, eliminating discrete transceiver modules. Hyperscale cloud operators in the United States are deploying these at 800G lane rates for intra-campus interconnects. This convergence is overtaking legacy pluggable optics architectures in data center spine layers, collapsing supplier margins on standalone transceiver products.
China's GB standards and MIIT certification protocols for telecommunications equipment have tightened electromagnetic compatibility benchmarks specifically for 5G base station backplanes. Domestic vendors with captive testing facilities are accelerating qualification cycles. State-backed carrier procurement is tilting toward suppliers with parallel GB and international certification capabilities, disadvantaging pure-export manufacturers.
Hyperscale buyers are consolidating vendor relationships around full-stack switching partners capable of delivering configuration software, thermal management, and field service as unified contracts. Traditional component distributors serving mid-market test-and-measurement customers are losing attach rates to direct vendor engagement models. This consolidation is most visible in North American cloud campus deployments where procurement teams centralize spend across compute, storage, and networking fabrics.
Cross Point Switch Market Segmentation
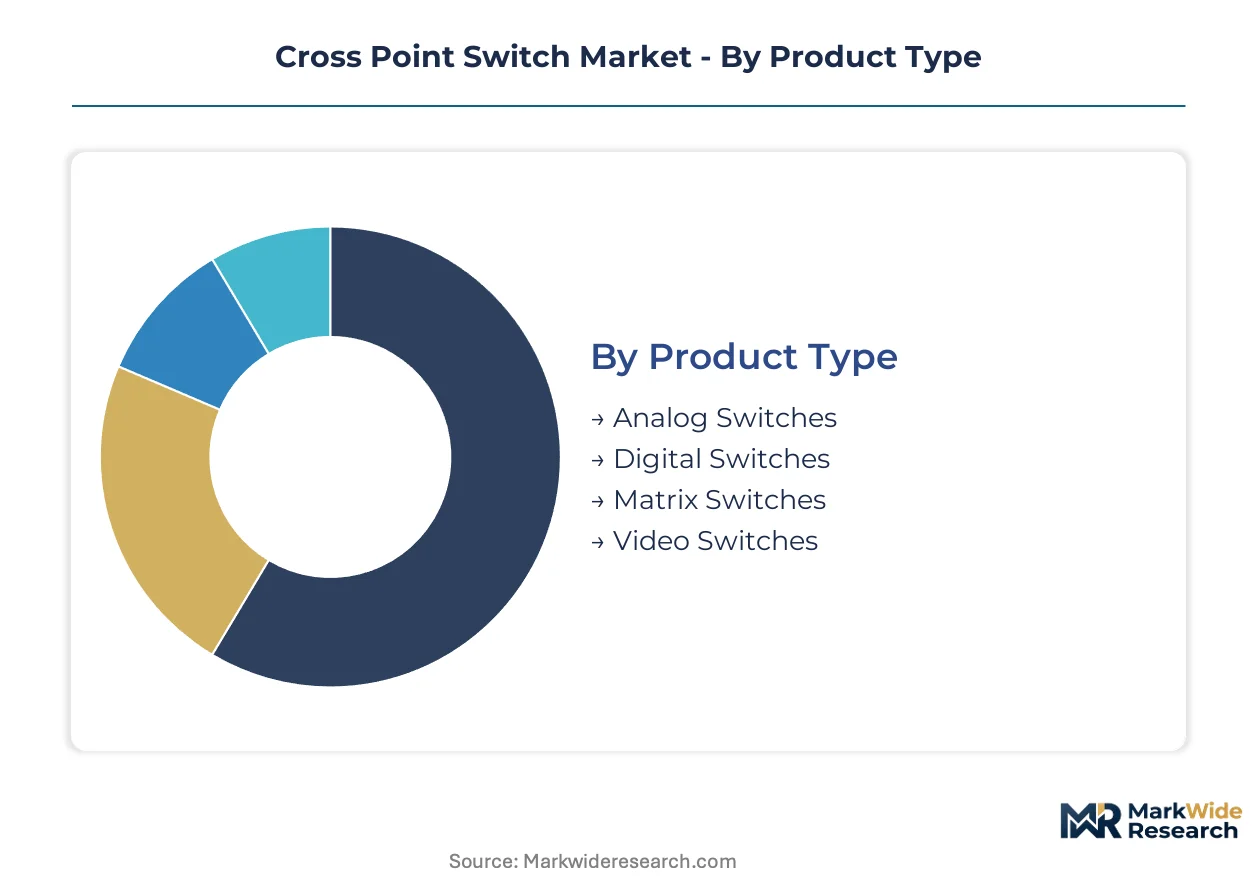
Cross point switch procurement patterns diverge sharply across deployment contexts, from hyperscale data center spine layers requiring 800G coherent optical matrices to military backplanes demanding radiation-hardened analog precision. Upgrade cycles in each segment reflect distinct reliability mandates, port density trajectories, and regulatory qualification burdens that reshape vendor R&D allocation.
Product Type:
Replacement cycles in broadcast infrastructure and data center spine layers are compressing as 400G+ coherent optical interfaces displace legacy copper backplanes, forcing vendors to synchronize foundry roadmaps with divergent customer refresh timelines.
- Digital Switches:These devices route serialized data protocols through CMOS-based switching fabrics with nanosecond-scale propagation delays. Hyperscale cloud campuses in the United States drive procurement concentration here, as port density requirements above 256×256 force abandonment of legacy analog architectures. FCC equipment authorization mandates for electromagnetic compatibility extend qualification timelines, compressing product refresh windows.
- Matrix Switches:Non-blocking full-connectivity architectures enable simultaneous routing between any input-output pair without signal degradation. Test-and-measurement environments in Germany and Japan concentrate demand, where REACH substance restrictions on plating chemistries elevate compliance costs for non-EU vendors serving precision instrumentation OEMs.
- Analog Switches:Continuous signal paths preserve waveform integrity for RF and video applications requiring minimal insertion loss.
- Video Switches:Specialized routing matrices handle uncompressed 4K/8K SDI streams with sub-frame latency requirements.
Digital switches sit at the top of the volume ranking, with matrix switches climbing the fastest as test-and-measurement refresh cycles accelerate.
Application:
Cost tier differentiation separates capital-intensive hyperscale deployments from maintenance-driven military retrofits, with procurement authority fragmenting across engineering teams with incompatible specification priorities.
- Data Centers:Spine-layer switching matrices at 800G lane rates demand silicon photonics integration to eliminate discrete transceiver modules. United States-based cloud operators consolidate procurement around full-stack partners capable of unified software, thermal management, and field service contracts.
- Military:Temperature-hardened designs with crosstalk isolation exceeding 60 dB operate across -55°C to 125°C ranges for avionics and communications backplanes. Domestic sourcing requirements in China's MIIT procurement rules redirect supply chain configurations toward captive fabrication capacity for state-backed programs.
- Broadcasting:SDI router refresh cycles in live production facilities prioritize deterministic latency over raw bandwidth.
- Telecommunications:5G base station backplanes require GB standards compliance alongside international certification for export markets.
Data centers command the largest absolute spend, with military applications expanding most quickly as geopolitical friction accelerates sovereign supply chain investments.
Technology:
Customer type stratification separates hyperscale self-builders from telecom operator procurement consortiums, with divergent technical staffing levels dictating preference for integrated versus modular solutions.
- Fiber Optics:Coherent optical interfaces on monolithic silicon photonics substrates collapse supplier margins on standalone transceiver products. China's state-backed carrier procurement tilts toward vendors with parallel GB and international certification capabilities.
- Electric:Copper backplane solutions retain cost advantage in edge computing deployments with moderate port counts and shorter reach requirements.
- Hybrid:Mixed electrical-optical architectures bridge legacy infrastructure during phased migration to full optical fabrics.
- Wireless:Emerging millimeter-wave switching matrices for 5G mmWave beamforming applications.
Fiber optics sits at the top of the volume ranking, with hybrid solutions gaining share fastest as brownfield data centers pursue incremental upgrade paths.
End User:
Supply concentration in Taiwan and South Korean foundry capacity exposes each end user category to divergent geopolitical risk profiles, with procurement teams adjusting dual-sourcing strategies accordingly.
- Telecom Operators:State-backed 5G buildouts in China concentrate demand for GB-certified switching matrices with domestic semiconductor content mandates. MIIT procurement rules redirect supply chain configurations toward captive fabrication capacity.
- Content Providers:Streaming infrastructure operators in the United States prioritize software-defined configuration layers for broadcast infrastructure refresh cycles, creating recurring revenue streams beyond hardware shipment economics.
- Government Agencies:Defense and intelligence applications require ITAR-controlled supply chains with provenance documentation.
- Enterprises:Private data center operators in India align with PLI scheme incentives for domestic electronics manufacturing.
Telecom operators sit at the top of the volume ranking, with content providers climbing the fastest as streaming bitrate wars force continuous spine-layer expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns in cross point switch manufacturing increasingly track divergent semiconductor subsidy regimes and certification cost structures. Vendors relocate assembly operations to jurisdictions offering production-linked incentives while maintaining design centers near hyperscale customer clusters.
United States
Hyperscale cloud campuses in Northern Virginia and the Pacific Northwest drive procurement concentration for 800G coherent optical matrices. FCC equipment authorization requirements for electromagnetic compatibility extend qualification timelines for spine-layer deployments. Austin and Phoenix host expanding design centers where vendors co-locate thermal management engineering teams with major cloud operators.
China
State-backed 5G infrastructure buildouts concentrate demand for GB-certified switching matrices with domestic semiconductor content mandates. MIIT procurement rules redirect supply chain configurations toward captive fabrication capacity for telecommunications backplanes. Shenzhen and Shanghai anchor domestic vendor ecosystems serving state carrier procurement consortiums with parallel certification capabilities.
Germany
Test-and-measurement OEMs in Munich and Stuttgart sustain demand for non-blocking matrix switches requiring REACH-compliant plating chemistries. ECHA substance restrictions on flame-retardant formulations elevate compliance costs for non-EU component vendors. Dresden's silicon photonics research clusters attract co-development partnerships for precision routing applications.
India
Production-linked incentive schemes for electronics manufacturing attract switch module assembly investments serving domestic 5G and data center buildouts. TRAI spectrum allocation policies accelerate telecommunications infrastructure deployment timelines. Bangalore and Hyderabad host design centers where vendors localize firmware development for tropical climate specifications.
Japan
Precision instrumentation manufacturers in Tokyo and Osaka sustain procurement of low-crosstalk analog switches for RF test environments. METI semiconductor revitalization policies subsidize domestic foundry capacity for mixed-signal devices. Yokohama clusters host specialist distributors serving broadcast infrastructure refresh cycles with deterministic latency requirements.
Cross Point Switch Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-stack vendors capturing hyperscale data center contracts while distributors retain attach rates in mid-market test-and-measurement channels. The vendor base concentrates around three strategic archetypes: captive foundry operators with temperature-hardened design legacies, fabless programmable logic specialists, and mixed-signal portfolio diversifiers. Dominant competitive moves include vertical integration into silicon photonics fabrication and strategic licensing of software-defined configuration layers.
Among North American diversified semiconductor manufacturers, Analog Devices Inc., Texas Instruments Inc., and Broadcom Inc. exemplify contrasting approaches to the precision routing segment. Analog Devices Inc. occupies a position anchored in mixed-signal portfolio breadth. Texas Instruments Inc. represents the captive foundry model with industrial-grade temperature specifications. Broadcom Inc. sits within the scale-driven tier serving hyperscale cloud operator procurement consolidation.
| Leading Market Players |
|---|
| Analog Devices Inc. |
| Lattice Semiconductor Corporation |
| Texas Instruments Inc. |
| MACOM Technology Solutions |
| Broadcom Inc. |
| ON Semiconductor |
| Arrow Electronics, Inc |
| Avnet, Inc. |
| Renesas Electronics Corporation |
| Others |
Supply Flow & Price Mechanics
REACH substance restrictions on plating chemistries and flame-retardant formulations in Europe gate qualified supply for premium-tier switching matrices, elevating compliance costs for non-EU vendors while creating pricing power for certified domestic manufacturers serving precision instrumentation OEMs in Germany and Japan.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for advanced node switching matrices as foundry competition intensifies for 400G+ coherent optical interfaces. Three-tier pricing structure across premium, standard, and economy levels separates silicon photonics-integrated spine-layer solutions from copper backplane alternatives and legacy analog architectures. Cost compression in standard-tier digital switches is intensifying because hyperscale buyers consolidate procurement around full-stack vendors bundling software configuration layers. Telecom operators in China exhibit highest price sensitivity due to MIIT domestic sourcing mandates, while US cloud campuses demonstrate lowest sensitivity given unified contract structures covering thermal management and field service.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand while specialist distributors retain attach rates in mid-market test-and-measurement segments. Taiwan, South Korea, and the United States anchor advanced node fabrication for precision routing applications. Silicon substrates, III-V compound semiconductors, and specialized plating chemicals constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan foundry capacity for mixed-signal devices, exposing supply security to geopolitical friction. Distribution runs through consolidated vendor relationships for North American cloud campuses and fragmented channel partnerships serving European precision instrumentation OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cross point switch market functions as a stable compounder underpinned by inexorable port density expansion in hyperscale data center buildouts, with refresh cycles compressing as 800G lane rates displace legacy architectures.
For Market Incumbents: Lock in captive foundry allocation for temperature-hardened designs by securing long-term capacity reservations at Taiwan and South Korean facilities before emerging fabless entrants capture share in edge-computing programmable matrices. Prioritize parallel GB standards and FCC certification investment to defend against domestic Chinese vendors accelerating qualification cycles through state-backed testing facilities. Channel control through direct engagement models with hyperscale procurement teams represents the critical defensive lever against component distributor disintermediation. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for switch module assembly investments serving domestic 5G and data center buildouts with localized firmware development for tropical climate specifications. Target brownfield data center hybrid upgrade paths as the most penetrable segment, where mixed electrical-optical architectures bridge legacy infrastructure during phased migration. Pursue software-defined configuration layer licensing as the primary go-to-market angle, creating recurring revenue streams that decouple from hardware shipment economics. For Investors and Strategic Acquirers: Roll-up economics work for mixed-signal portfolio diversifiers because precision routing applications require rare expertise spanning RF, digital, and analog domains that constrains R&D velocity at mid-tier vendors. Over a multi-year horizon, consolidation around full-stack switching partners capable of delivering unified software, thermal management, and field service contracts will reward platform players over point-product specialists. Watch hyperscale cloud operator capex disclosure patterns as the primary inflection indicator for spine-layer procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Monolithic optical-electronic substrates eliminate discrete transceiver modules at 800G lane rates. |
| Software-Defined Configuration Layer Licensing | Recurring revenue streams decouple vendor economics from hardware refresh cycles in broadcast infrastructure. |
| Parallel Certification Investment | GB standards and FCC authorization capabilities accelerate qualification for China's state-backed 5G procurement. |
| Captive Foundry Capacity Reservation | Long-term allocation agreements secure supply for industrial-grade temperature-hardened designs. |
| Direct Hyperscale Engagement Model | Unified contracts covering compute, storage, and networking fabrics displace traditional component distributors. |
Methodological Framework
Direct dialogue with data center procurement directors, semiconductor foundry planning officers, telecommunications equipment engineers, and broadcast infrastructure technical directors anchored qualitative assessment, combined with triangulation against SEC filings from major diversified manufacturers, MIIT procurement disclosure databases, hyperscaler capex reports, and ECHA REACH substance restriction updates. Bottom-up build-up from segment-level port density requirements and top-down cross-check against foundry capacity allocation announcements validated volume estimates.
Bottom-up modeling of port shipment volumes by application layer and top-down reconciliation against foundry revenue disclosures structured analytical approach across the projection horizon. Segmentation dimensions included product type, deployment context, interface technology, and end-user procurement authority. CAGRs were derived from weighted average of customer refresh cycle compression rates and foundry roadmap acceleration. Industry-specific inputs incorporated coherent optical displacement trajectories and domestic sourcing mandate compliance timelines.
Revisions become necessary when geopolitical friction disrupts Taiwan foundry operations, when REACH substance restrictions expand to additional chemical categories, or when hyperscale cloud operators accelerate lane rate migration beyond silicon photonics readiness. Forecasts reflect documented assumptions regarding customer consolidation behavior and certification timeline elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Molded Case Circuit Breaker Market
Switches
Pad-Mounted Switchgear Market
Switches
Campus Switches Market
Switches
Residual Current Circuit Breaker Market
Switches
Outdoor Boundary Vacuum Load Switch Market
Switches
Carrier Router Switch Market
Switches
Digital Crosspoint Switches Market
Switches
Brazil Switchgear Market
Switches
United States X by Wire Systems Market
Switches
DC Circuit Breaker Market
Switches
Pressure Switch Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
Transfer Switch Market
Switches
North America Switchgear Market
Switches
Electromechanical Microwave Switch Market
Switches
Reed Switches Sensors Market