
 Autonomous Technology Market | 2026-2036
Autonomous Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Technology Market Analysis
Modular sensor suites is broadening buyer choice as fleet operators mix-and-match lidar, radar, and camera stacks rather than accepting bundled OEM packages. Waymo leverages its captive data infrastructure to sustain mapping precision across operating domains. Tesla anchors consumer awareness through vertically integrated hardware-software stacks. NVIDIA Corporation dominates AI compute supply for training and inference workloads across the ecosystem.
Autonomous technology encompasses systems capable of perceiving environments, processing sensory inputs through algorithmic decision-making, and executing physical actions without continuous human intervention, typically operating across SAE automation levels 0 through 5. These systems integrate perception hardware, edge computing platforms, and control actuators to perform navigation, manipulation, or monitoring tasks in dynamic real-world conditions. Self-driving cars occupy the largest value pool today, though autonomous robots in manufacturing are capturing margin as deployment complexity declines. Machine learning underpins most functional advances, while sensor fusion architectures are becoming the critical differentiator for safety certification. Logistics applications lead commercial traction, whereas healthcare represents an emerging frontier with distinct regulatory pathways.
The National Highway Traffic Safety Administration shapes vehicle safety standards and crash investigation protocols in the United States, while the EU AI Act imposes risk-based conformity obligations on autonomous systems deployed in European markets. The Federal Aviation Administration governs beyond-visual-line-of-sight drone operations, constraining aerial autonomy scale until type certification frameworks mature. Stakeholders must monitor how fragmented national approval pathways affect cross-border platform economics and partnership structures.
Market Dynamics
Logistics operators are consolidating procurement around modular perception stacks, forcing hardware suppliers to unbundle sensor suites and compete on individual component performance rather than integrated platform dominance.
Growth Catalysts
- EU AI Act conformity pathways:The regulation's risk-based classification provides clarity for high-risk autonomous system deployment, accelerating vendor investment in certification-ready architectures for European markets.
- Edge computing silicon maturation:Inference-optimized chips are reducing latency-critical decision costs, enabling real-time processing without cloud dependency for mobile robotics and vehicular platforms.
- Arizona and California testing corridors:Permissive regulatory environments and dedicated infrastructure in these states are concentrating validation mileage and operational data collection for SAE Level 4 systems.
Market Restraints
- Lidar component supply concentration:Specialist foundries in select East Asian manufacturing clusters control critical MEMS and solid-state emitter production, creating input bottlenecks during demand surges.
- FAA beyond-visual-line-of-sight constraints:Aerial autonomy scale remains capped pending type certification framework maturation, limiting drone logistics to visual-range operations.
- Functional safety validation costs:ISO 26262 ASIL-D compliance for automotive platforms requires extensive fault analysis and redundant system architecture, elevating development expenditure for new entrants.
Strategic Opportunities
- Healthcare facility automation:Surgical robotics and sterile logistics bots face distinct regulatory pathways through FDA and EMA, creating first-mover advantages for platforms achieving dual-market clearance.
- India manufacturing automation:PLI scheme incentives for electronics and automotive production are driving autonomous robot demand for assembly and quality inspection in Gujarat and Tamil Nadu facilities.
- Sensor fusion algorithm licensing:Specialized perception software vendors can monetize safety-critical fusion architectures separately from hardware, opening recurring revenue streams in fragmented fleet operator markets.
Industry Challenges
- Systems safety engineering talent scarcity:Functional safety expertise for autonomous platforms requires combined competencies in control theory, probabilistic risk assessment, and regulatory documentation that outpace academic program output.
- Multi-jurisdiction homologation complexity:Divergent national approval frameworks for autonomous vehicles force redundant testing protocols, compressing platform economics for scaled deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Technology Market |
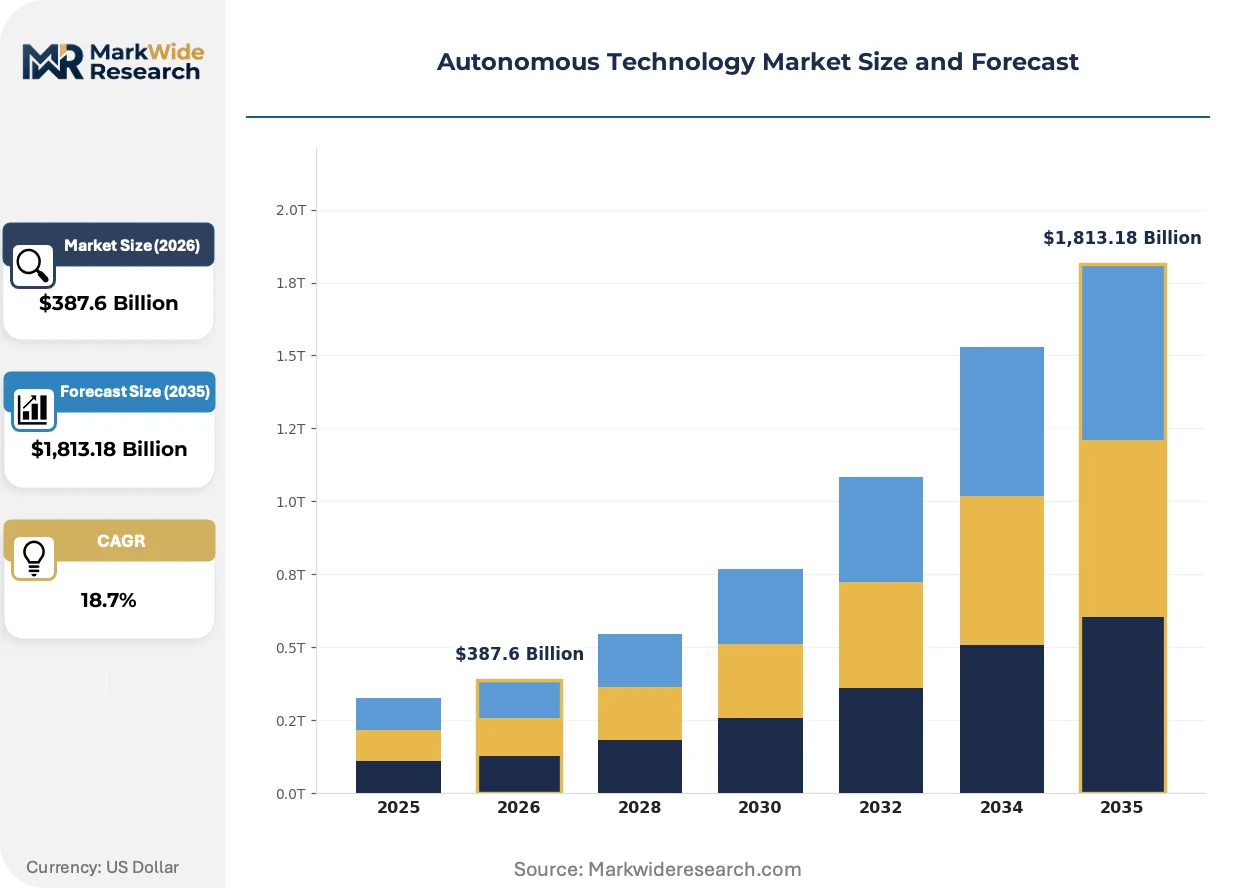
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,813.18 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Driving Cars, Drones, Autonomous Robots, Autonomous Vehicles Technology: Machine Learning, Computer Vision, Lidar, Sensor Fusion Application: Logistics, Agriculture, Healthcare, Security End User: Military, Retail, Manufacturing, Transportation |
| Companies Covered | Waymo, Tesla, NVIDIA Corporation, Mobileye, Cruise, Aurora Innovation, Zoox, Aptiv, Nuro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Technology Market Emerging Trajectories
Foundation models trained on diverse operational data are compressing development timelines for perception and prediction modules, while regulatory sandboxes in multiple jurisdictions are accelerating real-world validation cycles.
Transformer-based architectures for sensor fusion are rewriting how autonomous systems integrate camera, lidar, and radar inputs into unified environmental representations. Tier 1 automotive suppliers and robotics OEMs are adopting these models for next-generation platforms launching 2024-2026. The shift is compressing the traditional multi-year algorithm development cycle and enabling cross-domain transfer from simulation to physical deployment.
The EU AI Act's risk-based conformity framework is imposing documentation and human-oversight requirements on high-risk autonomous systems entering European markets. Industrial consequence includes mandatory algorithmic impact assessments and post-market monitoring obligations for safety-critical applications. Logistics and automotive segments are responding by embedding compliance engineering earlier in product development and pre-positioning technical documentation for notified body review.
Fleet operators are consolidating vendor relationships around platforms offering open sensor interfaces and API-accessible perception outputs. Traditional bundled OEM packages are losing ground to mix-and-match procurement that prioritizes component upgradeability and interoperability. This pattern is most visible in North American logistics networks where operators maintain heterogeneous vehicle pools and demand flexible integration with existing fleet management systems.
Autonomous Technology Market Segmentation
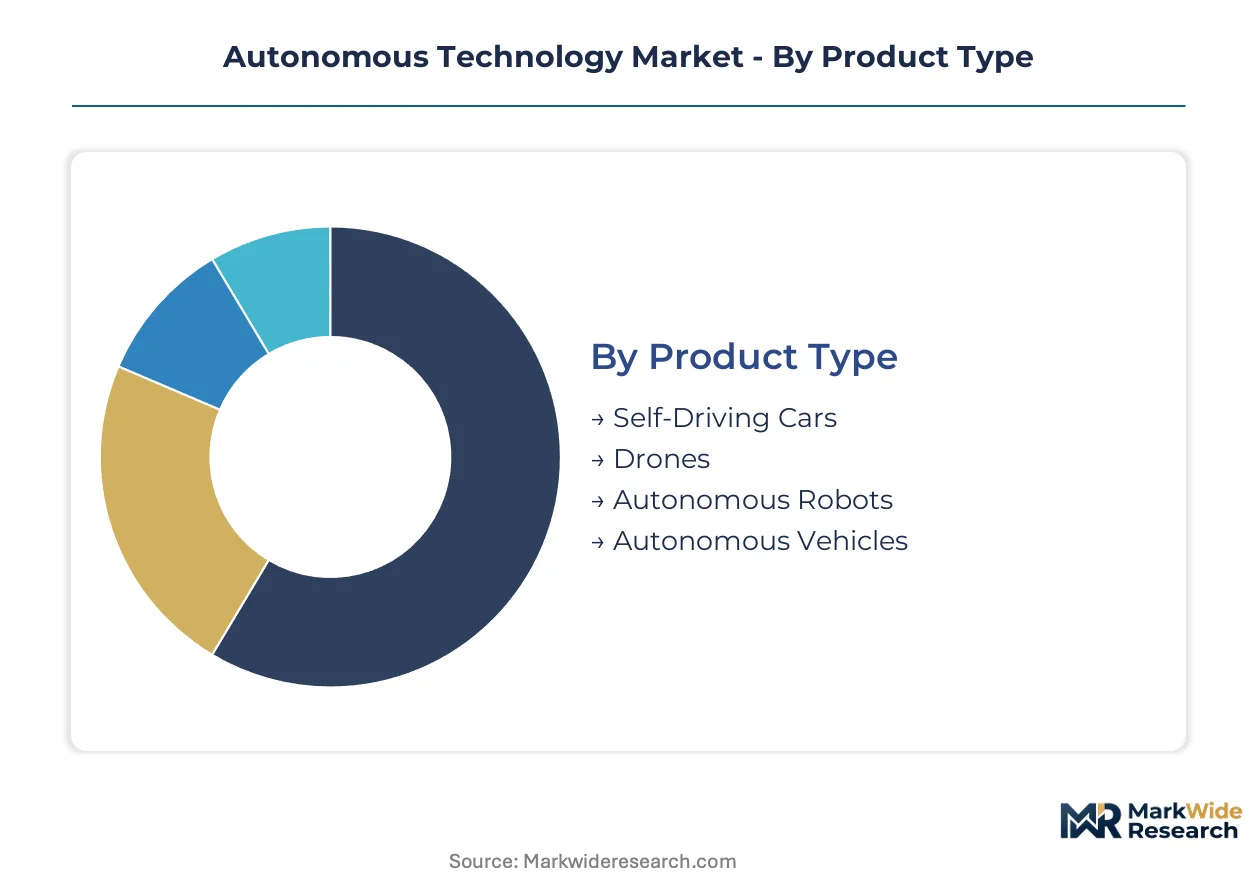
Segmentation in autonomous technology reveals divergent commercialization timelines across product architectures and deployment contexts. Buyers prioritize validated safety records and regulatory pathway clarity when allocating capital across these categories.
Product Type:
Fleet operators select platforms based on operational domain complexity and infrastructure dependency.
- Self-Driving Cars:SAE Level 4-capable passenger vehicles integrate redundant perception stacks and geofenced operational design domains. Arizona and California testing corridors concentrate validation investment as operators accumulate real-world mileage for regulatory submission.
- Drones:Beyond-visual-line-of-sight aerial platforms face FAA operational constraints pending type certification maturation. Logistics networks in the United States currently limit deployment to visual-range corridors while awaiting regulatory framework expansion.
- Autonomous Robots:Ground-based mobile manipulators serve manufacturing and warehouse environments with structured navigation requirements.
- Autonomous Vehicles:Heavy-duty freight platforms target hub-to-hub logistics routes with simplified environmental complexity relative to urban passenger service.
Self-Driving Cars lead on scale; Drones lead on momentum once FAA frameworks mature.
Technology:
Procurement patterns track inference cost reduction and safety certification readiness.
- Machine Learning:Foundation models trained on diverse operational data compress perception and prediction development timelines. Transformer architectures enable cross-domain transfer from simulation to physical deployment across automotive and robotics platforms.
- Sensor Fusion:Algorithmic integration of heterogeneous inputs—camera, lidar, radar—into unified environmental representations represents the critical differentiator for ISO 26262 ASIL-D compliance. Tier 1 suppliers license specialized fusion architectures separately from hardware bundles.
- Computer Vision:Edge-optimized neural networks process visual inputs for object detection and lane keeping with reduced silicon cost.
- Lidar:Solid-state and MEMS emitter technologies face supply concentration in East Asian manufacturing clusters, creating procurement bottlenecks during demand surges.
Sensor Fusion commands premium positioning; Machine Learning shows steepest expansion trajectory.
Application:
End-use selection depends on regulatory pathway clarity and labor substitution economics.
- Logistics:Warehouse automation and last-mile delivery networks drive commercial traction with quantifiable throughput gains. North American fleet operators consolidate procurement around modular perception stacks with API-accessible outputs.
- Healthcare:Surgical robotics and sterile logistics bots face distinct FDA and EMA regulatory pathways, creating first-mover advantages for dual-market clearance holders.
- Agriculture:Autonomous tractors and crop monitoring drones address seasonal labor scarcity in large-scale farming operations.
- Security:Perimeter patrol and facility monitoring applications leverage reduced sensor cost for persistent autonomous presence.
Logistics dominates current deployment; Healthcare offers premium margin expansion.
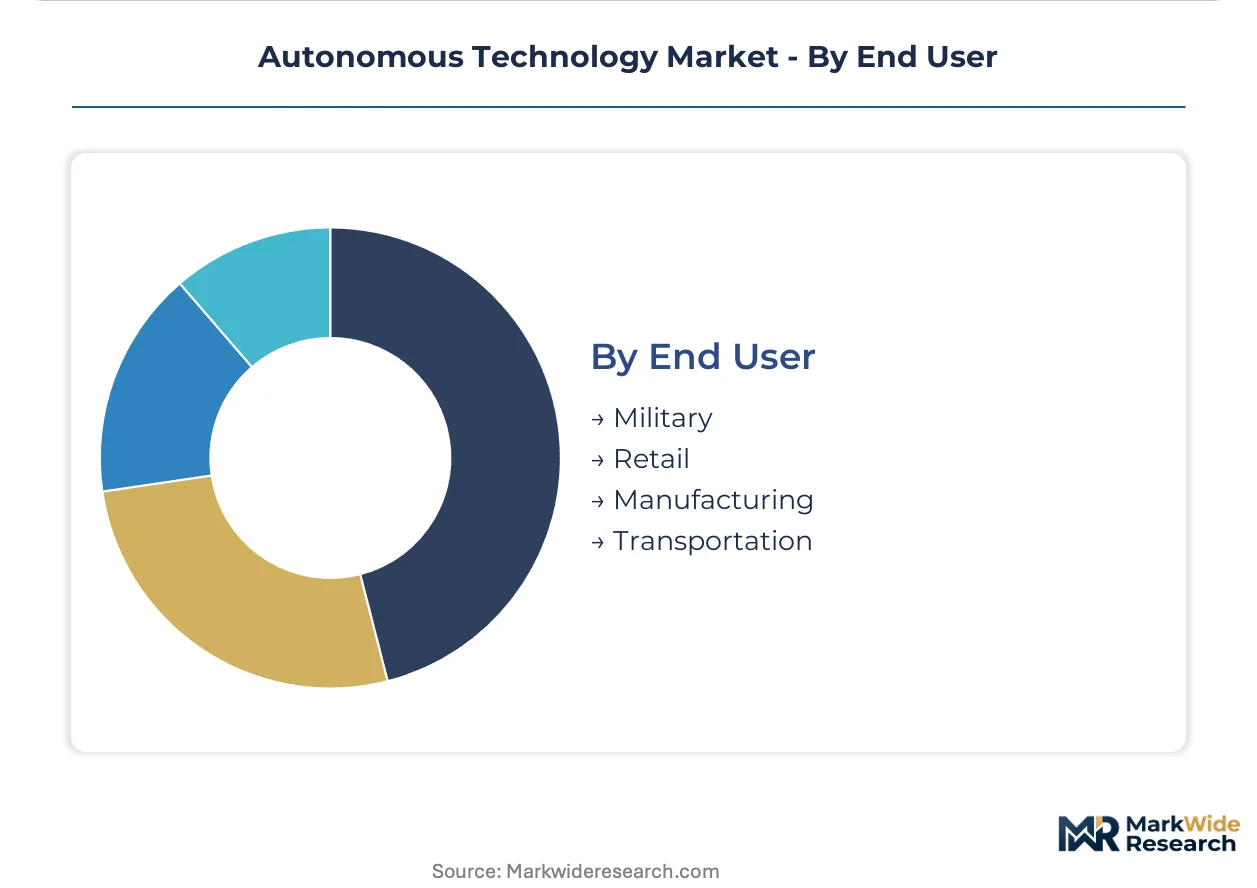
End User:
Contract structures vary by procurement authority centralization and operational risk tolerance.
- Transportation:Ride-hail networks and freight operators demand validated safety records and geoflexibility for heterogeneous fleet integration. Open sensor interfaces enable mix-and-match procurement across vehicle generations.
- Manufacturing:PLI scheme incentives in India drive autonomous robot demand for electronics and automotive assembly in Gujarat and Tamil Nadu facilities.
- Military:Defense procurement prioritizes jam-resistant navigation and cyber-hardened command chains with extended operational range requirements.
- Retail:Inventory management and customer-facing service robots target labor cost reduction in high-turnover environments.
Transportation leads on contract value; Manufacturing shows fastest volume scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The autonomous technology industry traces its commercial roots to California's Silicon Valley, where DARPA-funded research programs spawned the first generation of self-driving vehicle startups during the mid-2000s. This foundational concentration established the technical standards and talent pipelines that now diffuse across three continents. Regulatory permissiveness and capital availability in specific jurisdictions continue to determine where validation mileage accumulates and where commercial deployment scales first.
United States
Arizona and California testing corridors concentrate SAE Level 4 validation investment as operators accumulate real-world mileage for NHTSA regulatory submission. The FAA governs beyond-visual-line-of-sight drone operations, constraining aerial autonomy scale until type certification frameworks mature. Pittsburgh and Detroit clusters host robotics and automotive integration facilities serving freight and manufacturing applications.
China
MIIT standards for intelligent connected vehicles accelerate domestic OEM autonomous platform development across the Yangtze River Delta. GB standards for functional safety create compliance baselines for lidar and sensor fusion suppliers targeting passenger and logistics vehicle markets. Beijing and Shenzhen municipal governments operate designated autonomous vehicle testing zones with expanded operational design domains.
Germany
KBA homologation requirements for automated driving functions drive Tier 1 supplier investment in ISO 26262 ASIL-D certification capabilities. The EU AI Act imposes risk-based conformity obligations on high-risk autonomous systems entering European markets. Stuttgart and Munich automotive clusters integrate sensor fusion development with legacy powertrain engineering competencies.
India
PLI scheme incentives for electronics and automotive production drive autonomous robot demand for assembly and quality inspection in Gujarat and Tamil Nadu facilities. BIS standards for industrial automation equipment create procurement specifications for manufacturing end-users. Bangalore and Hyderabad technology corridors host machine learning engineering talent pools serving domestic and export markets.
Japan
METI funding programs for Society 5.0 implementation accelerate autonomous logistics robot deployment in aging workforce environments. JIS standards for mobile robots establish safety benchmarks for warehouse and healthcare facility applications. Nagoya and Osaka manufacturing belts integrate autonomous ground vehicles with just-in-time production systems.
Autonomous Technology Market Vendor Landscape
Premium-margin players sit above commodity-margin players across sensor fusion algorithm licensing and safety certification capabilities. The vendor base organizes into three tiers: integrated platform providers controlling captive data infrastructure, modular hardware suppliers competing on component performance metrics, and specialized perception software vendors monetizing recurring licensing revenue. Strategic moves concentrate on unbundling historically integrated sensor suites and securing dual-market regulatory clearance for healthcare and logistics applications.
Within the integrated platform tier, Waymo and Tesla occupy positions as archetypes of divergent technical approaches to market development. NVIDIA Corporation anchors the AI compute supply layer across training and inference workloads. These three entities exemplify how vertical control over data generation, silicon architecture, or consumer distribution creates defensive positioning against modular competitors.
| Leading Market Players |
|---|
| Waymo |
| Tesla |
| NVIDIA Corporation |
| Mobileye |
| Cruise |
| Aurora Innovation |
| Zoox |
| Aptiv |
| Nuro |
| Others |
Supply Flow & Price Mechanics
Fleet operator consolidation around modular perception stacks is forcing hardware suppliers to unbundle sensor suites and compete on individual component performance, compressing margins on bundled OEM packages while elevating pricing power for specialized fusion algorithm vendors. This procurement shift is reshaping how Tier 1 suppliers structure contracts and where foundry capacity investments flow.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the autonomous technology landscape, with differentiation driven by ISO 26262 ASIL-D certification grade and inference-optimized silicon architecture. Cost compression in standard-tier sensor modules is intensifying because logistics operators demand API-accessible outputs without captive hardware bundles. Manufacturing end-users in India exhibit the highest price sensitivity due to PLI scheme margin constraints, whereas healthcare facility buyers accept premium positioning for dual-market FDA and EMA clearance holders.
Supply Chain Analysis
Lidar emitter supply rests on specialist foundries concentrated in Taiwan, South Korea, and select Japanese manufacturing clusters, creating dependency on MEMS and solid-state component production for perception hardware stacks. Edge computing silicon draws from NVIDIA's AI compute supply layer and emerging inference-optimized chip vendors, while sensor fusion software licenses feed from specialized perception vendors. Single-source vulnerability in East Asian emitter manufacturing poses structural risk during demand surges. Distribution runs through Tier 1 automotive suppliers and direct OEM procurement channels serving heterogeneous fleet operator markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous technology market reads as a late-cycle quality story where procurement is concentrating around validated safety records and regulatory pathway clarity, with fleet operators prioritizing ASIL-D certification and dual-market clearance as non-negotiable specifications.
For Market Incumbents: Lock in sensor fusion algorithm licensing revenue through recurring contracts with fragmented logistics operators, and deepen backward integration into captive data infrastructure to defend against modular hardware competitors eroding platform margins. Waymo's mapping precision advantage and NVIDIA's AI compute dominance illustrate how vertical control creates defensive moats. For New Entrants and Emerging Players: The gap between premium-tier healthcare robotics and economy-tier warehouse automation creates white-space opportunity for mid-market surgical logistics platforms targeting sterile facility applications. India's PLI scheme manufacturing automation demand in Gujarat and Tamil Nadu represents the most penetrable geography. A go-to-market angle anchored in BIS standards compliance for industrial automation equipment bypasses incumbent certification timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized perception software vendors monetizing safety-critical fusion architectures separately from hardware bundles. Long-term viability across a 5-10 year window favors platforms achieving dual-market regulatory clearance in healthcare and logistics. The signal to watch is FAA beyond-visual-line-of-sight framework maturation unlocking aerial autonomy scale.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Algorithm Licensing | Recurring revenue streams from fragmented fleet operators reduce hardware margin dependence. |
| Dual-Market Regulatory Clearance | FDA and EMA pathway completion creates first-mover advantage in healthcare robotics deployment. |
| Backward Integration into Data Infrastructure | Captive mapping and training data sustains perception precision across operating domains. |
| Modular Sensor Interface Standardization | API-accessible outputs align with logistics operator mix-and-match procurement preferences. |
| Edge Computing Silicon Partnership | Inference-optimized chip supply secures latency-critical decision capability without cloud dependency. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with autonomous vehicle platform engineers, Tier 1 supplier procurement leads, logistics fleet operators, and regulatory affairs specialists with secondary validation against SEC filings, NHTSA safety databases, EU AI Act documentation, and MIIT intelligent connected vehicle standards. Bottom-up component demand modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Segment-weighting approaches modeled SAE automation levels, application categories spanning logistics and healthcare, technology types including sensor fusion and machine learning, and regional regulatory clusters. CAGRs were derived from installation base growth trajectories and content-per-vehicle expansion across automotive and robotics platforms. Forecast inputs incorporated PLI scheme incentive timelines, FAA certification pathway milestones, and EU AI Act conformity assessment requirements.
Caveats apply where FAA beyond-visual-line-of-sight framework delays, lidar supply bottlenecks, or EU AI Act enforcement variations could materially shift the outlook. Forecasts reflect assumptions about regulatory sandbox expansions and silicon cost reduction curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Global Ground Control Station Market
Unmanned Systems
High Altitude Aeronautical Platform Stations Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Global Unmanned Aerial Vehicle Landing Gears Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
North America Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Autonomous Aircraft Sensors Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
US Autonomous Navigation Market