
 Pepperoni Foods Market | 2026-2036
Pepperoni Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Pepperoni Foods Market Analysis
Branded retail pack revenue is fragmenting across food service bulk contracts and private-label supermarket channels. Hormel Foods Corporation leverages its vertically integrated pork supply chain to control raw material costs across production cycles. Tyson Foods sustains national distribution scale through its refrigerated logistics network. Johnsonville, LLC anchors regional brand loyalty in the Midwest with differentiated spice formulations.
Pepperoni denotes a cured, fermented, and dried salami variant traditionally manufactured from pork and beef, seasoned with paprika or chili pepper, with a moisture-to-protein ratio typically below 1.6:1 to achieve shelf stability. The product serves primarily as a pizza topping and charcuterie component across commercial and retail food channels. Traditional pepperoni occupies the mature volume position, while organic variants command premium shelf positioning in supermarket refrigerated sections. Food service distribution channels capture the largest margin pool through direct-to-restaurant contracts with national pizza chains.
USDA FSIS enforces pathogen reduction and labeling standards for ready-to-eat meat products, while FDA oversees sodium content claims and nutritional disclosure requirements. The EU F-Gas Regulation and EFSA processed meat guidelines shape export compliance costs for manufacturers targeting European food manufacturers. Stakeholders must monitor evolving clean-label certification requirements and alternative protein ingredient approvals to anticipate reformulation investments.
Market Dynamics
USDA FSIS sodium reduction mandates are forcing reformulation across cured meat portfolios, compressing moisture-to-protein ratios while preserving shelf stability and flavor profiles in processed pork products.
Growth Catalysts
- Quick-service pizza procurement:National pizza chains are expanding direct-supply contracts for pepperoni as a core menu staple, locking in volume commitments through multi-year agreements.
- Clean-label certification tailwinds:USDA Organic and Non-GMO Project Verified standards are opening premium shelf positioning in supermarket refrigerated sections for differentiated pepperoni variants.
- Charcuterie board expansion:Retail demand for sliced pepperoni as a standalone snacking component is accelerating through club store and specialty grocer channels.
Market Restraints
- Feed grain cost volatility:Corn and soybean price swings in the US Midwest directly squeeze pork producer margins, transmitting upstream into cured meat input costs.
- Pathogen testing burdens:USDA FSIS Listeria monocytogenes sampling protocols impose holding-period delays and disposal costs for small-batch fermentation operations.
- Plant-based substitution:Pea-protein and mycelium-based pepperoni analogs are capturing trial purchases from flexitarian households in coastal metropolitan markets.
Strategic Opportunities
- EU export compliance:EFSA processed meat guidelines and F-Gas Regulation adherence create a certification moat for US manufacturers willing to absorb reformulation costs for European food manufacturers.
- E-commerce direct-to-consumer:Refrigerated last-mile logistics partnerships with specialty fulfillment providers are enabling subscription-based artisan pepperoni delivery.
- Dual-species blending innovation:Beef-pork ratio optimization combined with smoked paprika and fermented chili pepper profiles is unlocking flavor differentiation for food service private-label programs.
Industry Challenges
- Fermentation science talent scarcity:Master salumieri with expertise in controlled humidity drying chambers command premium wages, constraining small-producer scale-up timelines.
- Legacy equipment retrofit costs:Converting existing smokehouses to meet EPA air-quality standards for particulate emissions requires capital outlays that strain regional processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pepperoni Foods Market |
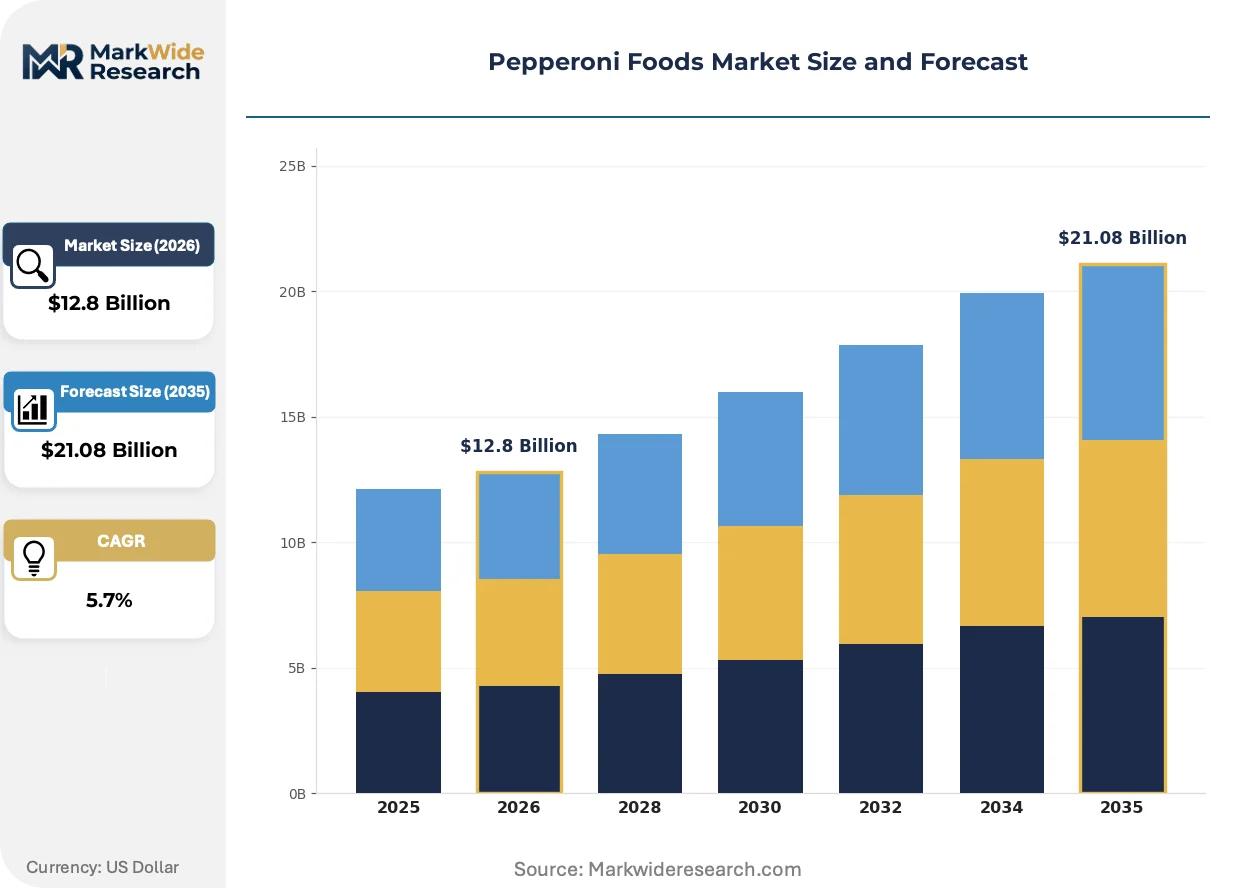
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Vegetarian, Organic, Spicy Packaging Type: Vacuum Packs, Slices, Whole, Bulk Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Food Service End User: Restaurants, Households, Catering Services, Food Manufacturers |
| Companies Covered | Bridgford Foods, Johnsonville, LLC, Hormel Foods Corporation, Performance Food Group, Ezzo Sausage Company, Tyson Foods, Boar’s Head Provisions Co., Inc., US Foods Holding, Smithfield Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pepperoni Foods Market Emerging Trajectories
Digital traceability systems and precision fermentation are converging with regulatory pressure on sodium and pathogen control, reshaping how pepperoni moves from pork sourcing to pizza topping.
Blockchain-enabled lot tracking is digitizing supply chain transparency from farm to slicer. Major quick-service restaurant procurement teams are mandating immutable provenance records for pathogen accountability. This technology is compressing recall response windows while elevating supplier qualification barriers for mid-tier processors.
USDA FSIS is tightening ready-to-eat meat labeling standards around sodium disclosure and allergen cross-contamination warnings. Manufacturers face reformulation investments or risk delisting from school nutrition and healthcare food service contracts. The prepared foods segment is responding with reduced-sodium fermentation protocols that maintain flavor intensity through extended curing cycles.
Food service buyers are consolidating pepperoni procurement through group purchasing organizations rather than direct distributor relationships. National pizza chains are leveraging volume concentration to extract price concessions and exclusive spice-blend formulations. This shift is most visible in the US Southeast, where multi-brand franchise operators are centralizing protein sourcing across their portfolios.
Pepperoni Foods Market Segmentation
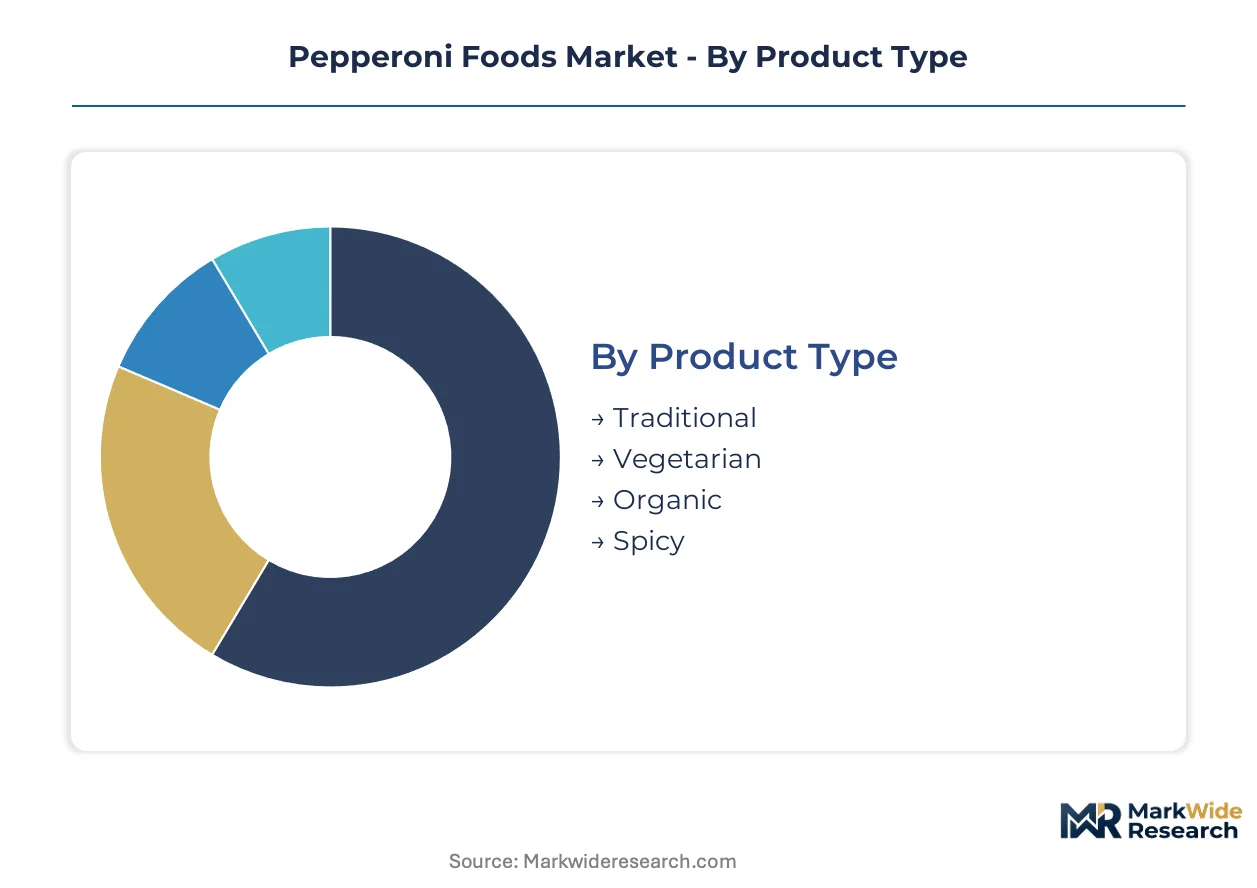
Pepperoni segmentation reveals divergent velocity profiles across product lifecycles. Traditional formats rotate through food service pipelines in weeks, while organic variants sit in retail cold cases for months. Understanding these turnover differentials shapes inventory financing and margin capture strategies for processors and distributors alike.
Product Type:
Traditional pepperoni turns fastest through pizza chain procurement, while organic and vegetarian variants exhibit extended shelf residency due to premium positioning and narrower buyer pools.
- Traditional:Pork-beef blends with paprika and chili seasoning achieve moisture-to-protein ratios below 1.6:1 for shelf stability. Quick-service pizza chains in the United States lock in multi-year volume contracts, compressing procurement cycles and squeezing mid-tier processor margins.
- Organic:USDA Organic certification mandates antibiotic-free pork sourcing and restricted nitrate curing protocols. Premium shelf positioning in supermarket refrigerated sections attracts flexitarian households in coastal metropolitan markets willing to absorb price premiums.
- Vegetarian:Pea-protein and mycelium-based analogs replicate fat crystallization and fermentation notes through precision fermentation. Trial purchases concentrate in health-focused retail clusters where clean-label positioning overrides taste parity concerns.
- Spicy:Fermented chili pepper and smoked paprika formulations target charcuterie board expansion and standalone snacking channels.
Traditional pepperoni dominates installed base. Organic is where expansion concentrates.
Packaging Type:
Cost tier stratification separates high-touch artisan formats from commodity bulk throughput, with packaging labor intensity directly mapping to price realization.
- Bulk:Unsliced chubs and food service totes move through direct-to-restaurant contracts with minimal handling overhead. National pizza chains leverage volume concentration to extract price concessions and exclusive spice-blend formulations.
- Slices:Pre-portioned rounds optimize labor efficiency in high-throughput pizzeria kitchens. Club store and specialty grocer channels in the US Southeast are accelerating retail demand for this format as a charcuterie board component.
- Vacuum Packs:Modified atmosphere packaging extends refrigerated shelf life for supermarket distribution.
- Whole:Intact sticks serve artisan delis and specialty food service accounts requiring custom thickness control.
Bulk packaging commands the largest revenue pool. Sliced formats are climbing the fastest.
Distribution Channel:
Customer type fragmentation splits procurement behavior between consolidated institutional buyers and dispersed household purchasers with divergent price elasticity profiles.
- Food Service:Direct contracts with quick-service restaurant chains and group purchasing organizations capture margin through volume commitments and exclusive formulations. USDA FSIS pathogen testing protocols impose holding-period delays that favor large-scale processors with dedicated quality laboratories.
- Supermarkets:Private-label and branded retail packs compete for refrigerated case placement through slotting fee negotiations. Clean-label certification tailwinds are opening premium positioning for differentiated pepperoni variants.
- Online Retail:Refrigerated last-mile logistics partnerships enable subscription-based artisan delivery to specialty households.
- Convenience Stores:Grab-and-go snacking formats target impulse purchase occasions with smaller pack sizes.
Food service channels dominate installed base. Online retail is where expansion concentrates.
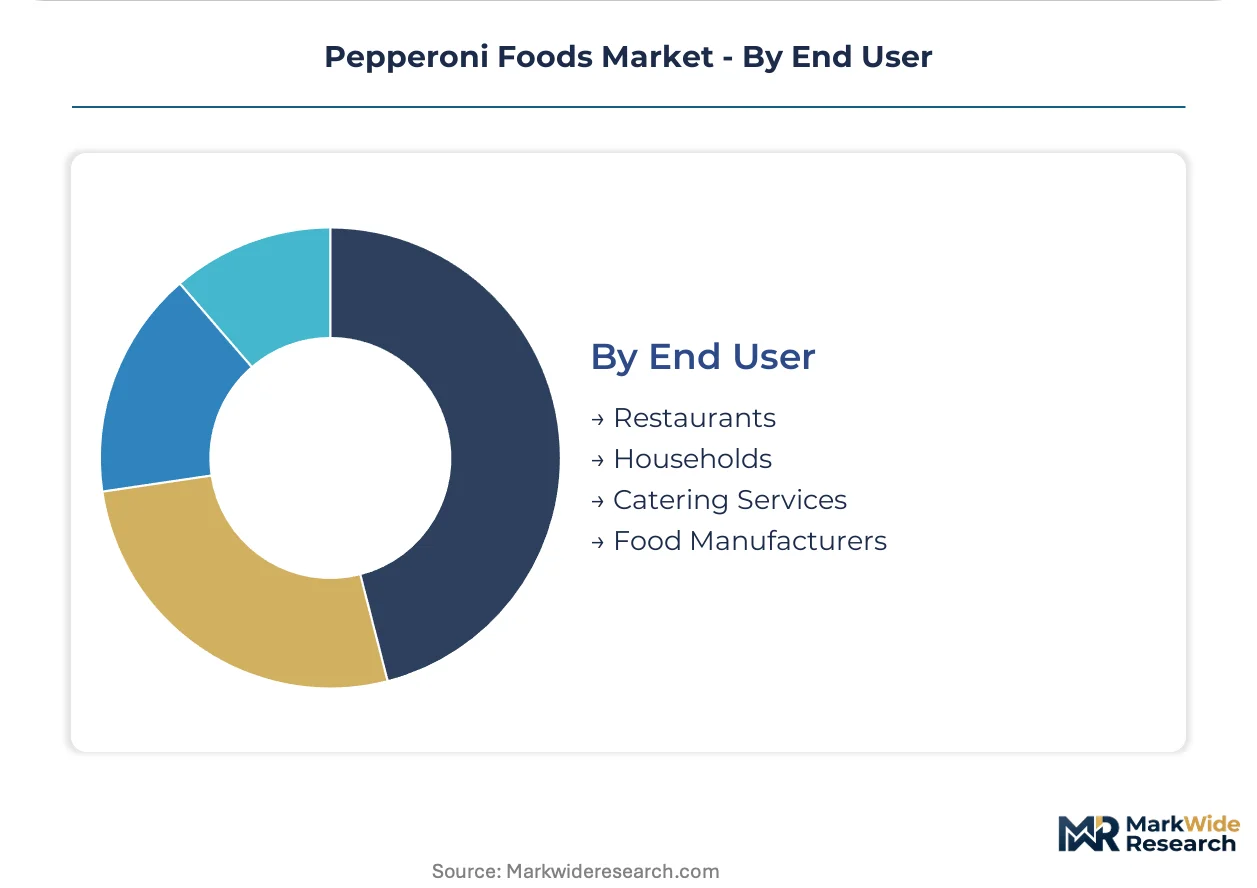
End User:
Application maturity varies sharply between established pizza topping demand and emerging charcuterie snacking occasions with divergent growth trajectories.
- Restaurants:Quick-service pizza chains and independent pizzerias constitute the core volume sink, with procurement consolidating through multi-brand franchise operators. Sodium reduction mandates are forcing reformulation investments to maintain school nutrition and healthcare food service contract eligibility.
- Households:Retail sliced pepperoni for home pizza assembly and charcuterie boards is accelerating through club store channels. Flexitarian households in coastal metropolitan markets are driving trial of plant-based analogs.
- Catering Services:Event-scale protein procurement favors bulk formats with consistent slice yield predictability.
- Food Manufacturers:Ingredient-grade pepperoni supplies frozen pizza and prepared sandwich production lines.
Restaurant channels dominate installed base. Household consumption is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States show the lowest price elasticity, absorbing premiums for branded formulations, while emerging markets in Asia-Pacific exhibit acute sensitivity to commodity pork input costs.
United States
Quick-service pizza chains in the Southeast and Midwest lock in multi-year pepperoni procurement contracts, insulating volume from spot price swings. USDA FSIS enforces pathogen reduction standards and sodium disclosure mandates that force reformulation investments. Chicago and Milwaukee anchor regional processing clusters where Johnsonville maintains differentiated spice formulations for food service accounts.
Germany
Charcuterie board expansion in premium retail channels drives demand for artisan whole-stick formats with extended curing cycles. EFSA processed meat guidelines and EU F-Gas Regulation compliance requirements create certification barriers for US exporters targeting European food manufacturers. Bavaria's meat processing corridor concentrates small-batch fermentation operations serving specialty grocer channels.
China
Western-style pizza penetration in tier-one cities accelerates pepperoni import demand despite domestic processed pork dominance. SAMR oversees nutritional labeling and food safety standards for imported cured meat products. Shanghai and Beijing metropolitan clusters host cold-chain distribution hubs for quick-service restaurant supply contracts.
Italy
Traditional salami culture constrains pepperoni adoption in independent pizzerias, though tourist corridor restaurants in Rome and Milan absorb imported US formulations for American-style offerings. EU food safety regulations align with EFSA guidelines on processed meat additives and labeling. Emilia-Romagna's cured meat heritage clusters preserve artisan production methods that compete with industrial imports.
Canada
Cross-border supply integration with US processors maintains price parity for food service buyers in Ontario and Quebec. Health Canada and PMRA regulate sodium content claims and antimicrobial use in processed pork products. Toronto's food service distribution hub consolidates procurement for multi-brand pizza franchise operators across the Prairie Provinces.
Pepperoni Foods Market Vendor Landscape
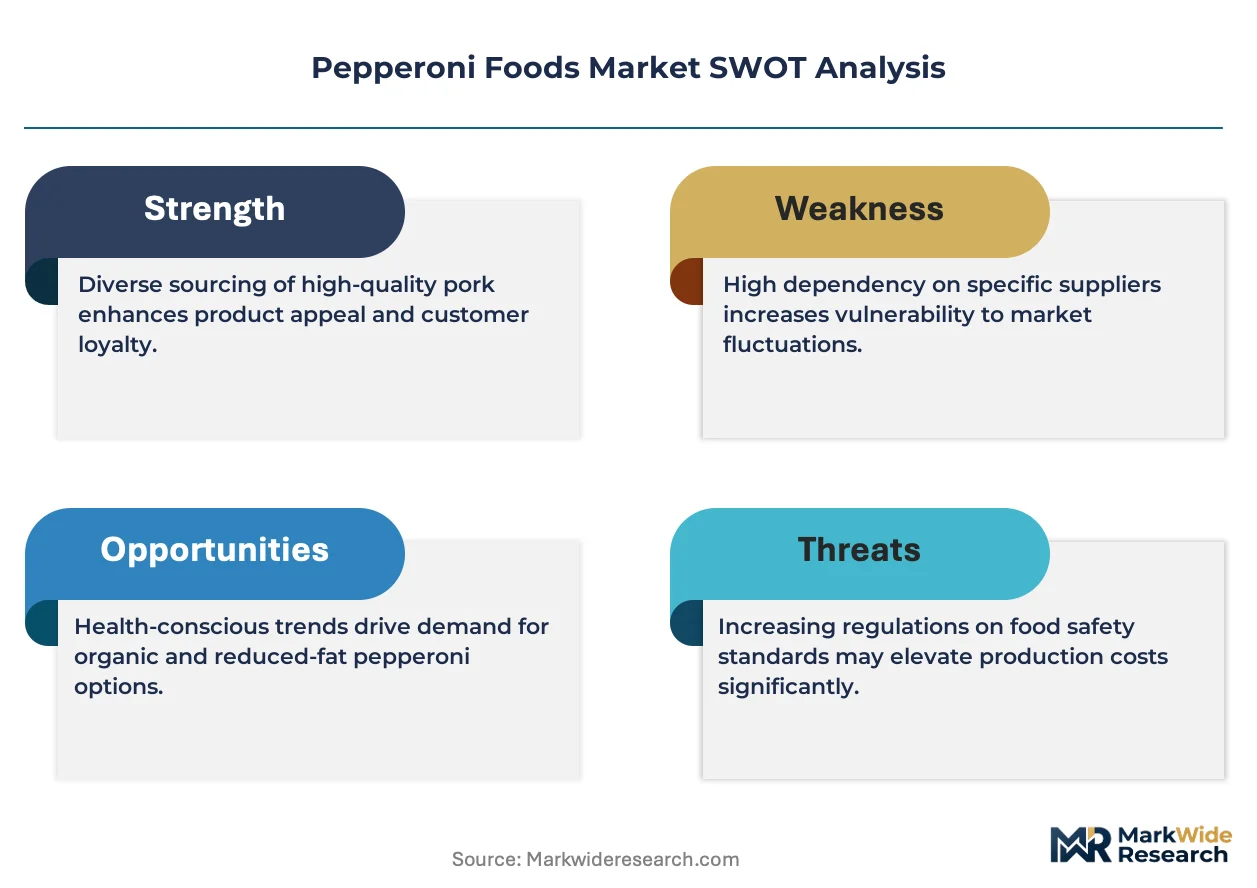
Capability concentration sits with regional specialists commanding fermentation science expertise; scale advantage sits with diversified protein conglomerates leveraging refrigerated logistics networks. The market structures around three tiers: national distributors with direct chain restaurant relationships, mid-size processors with private-label flexibility, and artisan producers with certified organic positioning. Dominant competitive moves include backward integration into pork supply chains and exclusive spice-blend formulation partnerships with quick-service buyers.
Among US-based protein conglomerates, Hormel Foods Corporation, Tyson Foods, and Johnsonville exemplify divergent strategic archetypes. Hormel anchors the vertically integrated tier with captive pork supply control across production cycles. Tyson occupies the national distribution scale position through refrigerated logistics infrastructure. Johnsonville represents regional brand loyalty concentration in Midwest markets with differentiated product positioning.
| Leading Market Players |
|---|
| Bridgford Foods |
| Johnsonville, LLC |
| Hormel Foods Corporation |
| Performance Food Group |
| Ezzo Sausage Company |
| Tyson Foods |
| Boar's Head Provisions Co., Inc. |
| US Foods Holding |
| Smithfield Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Midwest pork processing capacity utilization running above 85 percent compresses supplier pricing flexibility while amplifying buyer negotiating leverage across multi-year food service contracts. USDA FSIS sodium reduction mandates force reformulation investments that transmit upstream into raw material specifications and curing cycle economics.
Pricing Analysis
Food service contract renewals drive lifetime value through multi-year volume commitments and exclusive spice-blend formulations. Three-tier pricing structure across USDA Organic certified, traditional, and private-label economy tiers separates premium shelf positioning from commodity bulk throughput. Pricing pressure stems from corn and soybean feed cost volatility transmitting into pork producer margins. Quick-service pizza chains show lowest price sensitivity through locked procurement cycles, while independent pizzerias absorb spot market swings.
Supply Chain Analysis
EU F-Gas Regulation and EFSA processed meat guidelines restrict technology flows for US exporters targeting European food manufacturers. Geographic supply concentration centers on the United States, Germany, and China as dominant processing clusters. Raw material dependencies draw from Midwest feed grain corridors, Brazilian soybean imports, and domestic pork production networks. Single-source vulnerability runs through concentrated fermentation science talent pools. Distribution runs through refrigerated logistics partnerships with national cold-chain operators and direct-to-restaurant contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cyclical recovery anchored to quick-service pizza chain expansion cycles and protein procurement consolidation waves.
For Market Incumbents: Harden supply chain resilience through backward integration into antibiotic-free pork sourcing to preempt USDA Organic certification bottlenecks. Lock in multi-year fermentation science talent contracts before wage inflation accelerates small-producer scale-up timelines. For New Entrants and Emerging Players: Coastal metropolitan flexitarian households represent the most penetrable entry point for plant-based analog trials with clean-label positioning. Subscription-based artisan pepperoni delivery through refrigerated last-mile logistics partnerships offers a defensible go-to-market angle against incumbent distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because food service procurement concentration favors scaled processors with dedicated quality laboratories over fragmented regional operators. Target mid-tier processors with private-label flexibility and existing USDA FSIS compliance infrastructure. Watch quick-service pizza chain same-store sales velocity as the inflection signal for protein procurement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pork Supply | Hormel Foods Corporation's captive sourcing model controls raw material cost volatility across production cycles. |
| Clean-Label Certification Investment | USDA Organic and Non-GMO Project Verified standards unlock premium shelf positioning in supermarket refrigerated sections. |
| Direct-to-Restaurant Contract Expansion | National pizza chains leverage volume concentration to extract exclusive spice-blend formulations and price concessions. |
| Refrigerated E-Commerce Infrastructure | Specialty fulfillment partnerships enable subscription-based artisan delivery bypassing traditional distributor markups. |
| Fermentation Science Talent Acquisition | Master salumieri expertise in controlled humidity drying chambers constrains small-producer scale-up timelines and commands premium wages. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with quick-service restaurant procurement directors, meat processing plant managers, and USDA FSIS compliance officers; and secondary validation through FDA nutritional labeling databases, USDA livestock and grain reports, and SEC protein conglomerate filings. Bottom-up volume modeling triangulated against top-down value estimates anchored the forecast calibration.
Forecast inputs span product type segmentation across traditional, organic, and vegetarian formats; packaging tier differentiation between bulk food service and retail sliced configurations; and distribution channel splits between direct restaurant contracts and supermarket private-label placements. CAGRs derive from historical procurement cycle analysis and forward-looking protein demand elasticity assumptions. Industry-specific inputs include feed grain price correlation models and fermentation capacity expansion pipelines.
Macroeconomic conditions sit as an overlay; deviation in feed grain commodity indices and quick-service restaurant capital expenditure cycles would shift the trajectory. Material shifts in USDA FSIS sodium reduction enforcement timelines or EU F-Gas Regulation compliance stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Animal Protein Market
Meat Products
Beef Bouillon Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Beef Fat Powder Market
Meat Products
Pork Flavors Market
Meat Products
Smokehouse Market
Meat Products
Kosher Beef Market
Meat Products
Pork Belly Meat Market
Meat Products
Shark Meat Market
Meat Products
North America Canned Meat Market
Meat Products
Pork Meat Market
Meat Products
3D Printed Meat Market
Meat Products
Meat Flavors Market
Meat Products
Brisket Market
Meat Products
Canned Pork Market
Meat Products
Bahrain Poultry Meat Market