
 United Kingdom Energy Bar Market | 2026-2036
United Kingdom Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Energy Bar Market Analytics
Aftermarket subscription revenue from direct-to-consumer replenishment programs is narrowing the margin advantage that traditional supermarket listings once held. Glanbia PLC leverages its dairy protein supply chain to control input costs for sports-focused formulations. Oatein Limited anchors its position through bakery-inspired texture profiles that differentiate from chalky competitors. Fulfil Nutrition competes aggressively on impulse placement in convenience retail.
Energy bars are shelf-stable, nutrient-dense food products typically formulated with protein isolates, carbohydrate syrups, and binding agents, manufactured through cold-press extrusion or baked slab-and-cut processes, designed to deliver sustained energy release for active consumers. Protein bars dominate absolute volume due to entrenched gym culture penetration, while meal replacement bars capture the fastest expansion as time-compressed professionals substitute breakfast and lunch occasions. Snack bars occupy a mature, price-sensitive tier where private label pressure constrains branded margin pools.
The Food Standards Agency enforces allergen labeling and nutrition claims verification, while the Competition and Markets Authority monitors pricing transparency in online retail channels, and Advertising Standards Authority rules restrict health benefit assertions in influencer marketing. These frameworks elevate compliance costs for entrants but fortify incumbent positions through established quality systems. Stakeholders must monitor evolving HFSS placement restrictions and reformulation thresholds as these will determine which product architectures retain retail access.
Market Dynamics
The Food Standards Agency's updated nutrition labeling requirements are compressing formulation flexibility while simultaneously raising compliance barriers that favor established quality systems over new entrants.
Growth Catalysts
- Gym culture penetration:Fitness enthusiasts in Greater London and the South East corridor are normalizing pre-workout and post-workout bar consumption, creating habitual purchase patterns that stabilize volume baselines.
- HFSS placement restrictions:The UK's evolving high-fat-sugar-salt retail placement rules are forcing reformulation toward protein-dense architectures that qualify for prominent checkout positioning.
- Cold-press extrusion:This manufacturing process preserves heat-sensitive micronutrients and enables cleaner-label claims that command shelf price premiums in health-specialist retail.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings tied to New Zealand and EU milk powder auctions compress margin predictability for sports-focused formulations.
- Supermarket listing fees:Tesco, Sainsbury's, and Asda demand six-figure slotting allowances that exhaust working capital for sub-£5 million revenue brands.
- Sugar alcohol tolerance thresholds:Maltitol and sorbitol digestive discomfort limits their inclusion rates, constraining low-sugar formulation degrees of freedom.
Strategic Opportunities
- Direct-to-consumer replenishment:Subscription models bypass supermarket margin extraction and capture first-party consumption data for flavor development pipelines.
- Meal replacement occasion expansion:Time-compressed professionals in Manchester and Birmingham are substituting breakfast and lunch with fortified bars, opening weekday volume increments.
- Advertising Standards Authority clarity:Updated guidance on permissible health benefit assertions creates compliant creative territory for influencer marketing that previously operated in legal gray zones.
Industry Challenges
- Food technologist scarcity:Formulation chemists capable of balancing protein solubility, shelf stability, and clean-label demands command salaries 40% above general food science benchmarks.
- Allergen cross-contamination protocols:FSA-mandated verification systems require dedicated production lines or lengthy changeover sanitation that reduces asset utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Energy Bar Market |
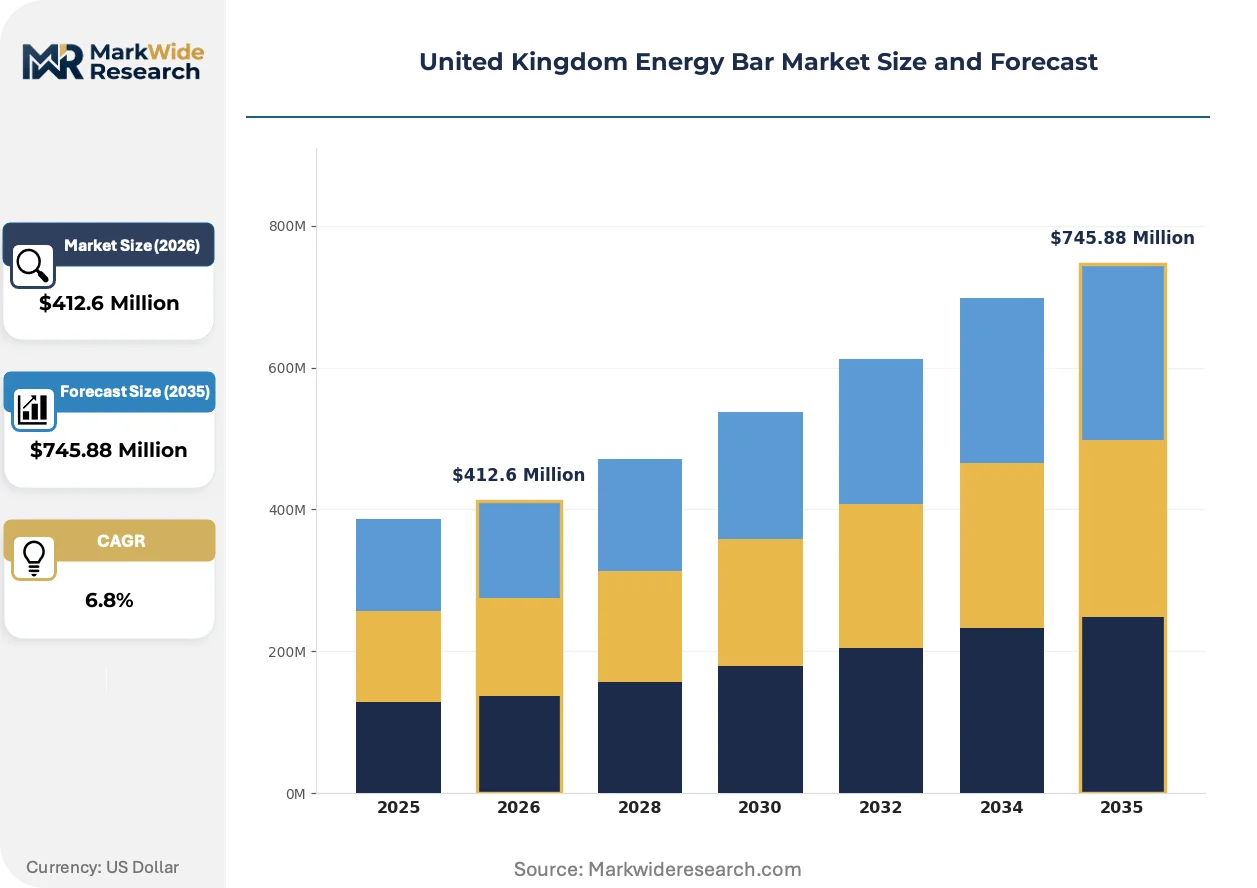
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Meal Replacement Bars, Snack Bars, Nut Bars End User: Athletes, Fitness Enthusiasts, Busy Professionals, Students Distribution Channel: Supermarkets, Online Retail, Health Stores, Fitness Centers Flavor Type: Chocolate, Vanilla, Berry, Peanut Butter |
| Companies Covered | Glanbia PLC, Unilever PLC, Mondelez International, Inc., Oatein Limited, Fulfil Nutrition, Kellogg Company, Post Holdings, Inc., HNC Healthy Nutrition Company Ltd., General Mills, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Energy Bar Market Evolving Landscape
Texture engineering and regulatory positioning are displacing flavor novelty as the primary competitive battleground, with mouthfeel patents and placement compliance now determining shelf survival.
Plant protein texturization via extruded pea and fava bean isolates is rendering obsolete the chalky, gritty mouthfeel that previously limited vegan bar repeat purchase rates. Premium health retailers in Brighton and Bristol are accelerating adoption of these reformulated SKUs. The technology is compressing the sensory gap between dairy and plant architectures, forcing incumbent whey-dependent brands into defensive R&D cycles.
The Food Standards Agency's updated nutrition claims verification framework is tightening permissible protein content assertions and mandating substantiation dossiers for glycemic response marketing. This elevates compliance costs disproportionately for sub-scale entrants lacking in-house regulatory affairs functions. Sports-focused formulations targeting gym-based consumption are most affected, with several brands withdrawing "slow release energy" claims pending dossier assembly.
Impulse placement economics are reshaping channel strategy, with convenience retail now commanding higher trade investment than traditional grocery despite lower absolute volume. Fulfil Nutrition and similar competitors are securing Premier League and Travelodge checkout slots that capture unplanned purchase occasions. This rotation is most visible in Greater London transport hubs, where commuter grab-and-go behavior concentrates morning and evening velocity spikes.
United Kingdom Energy Bar Market Segmentation
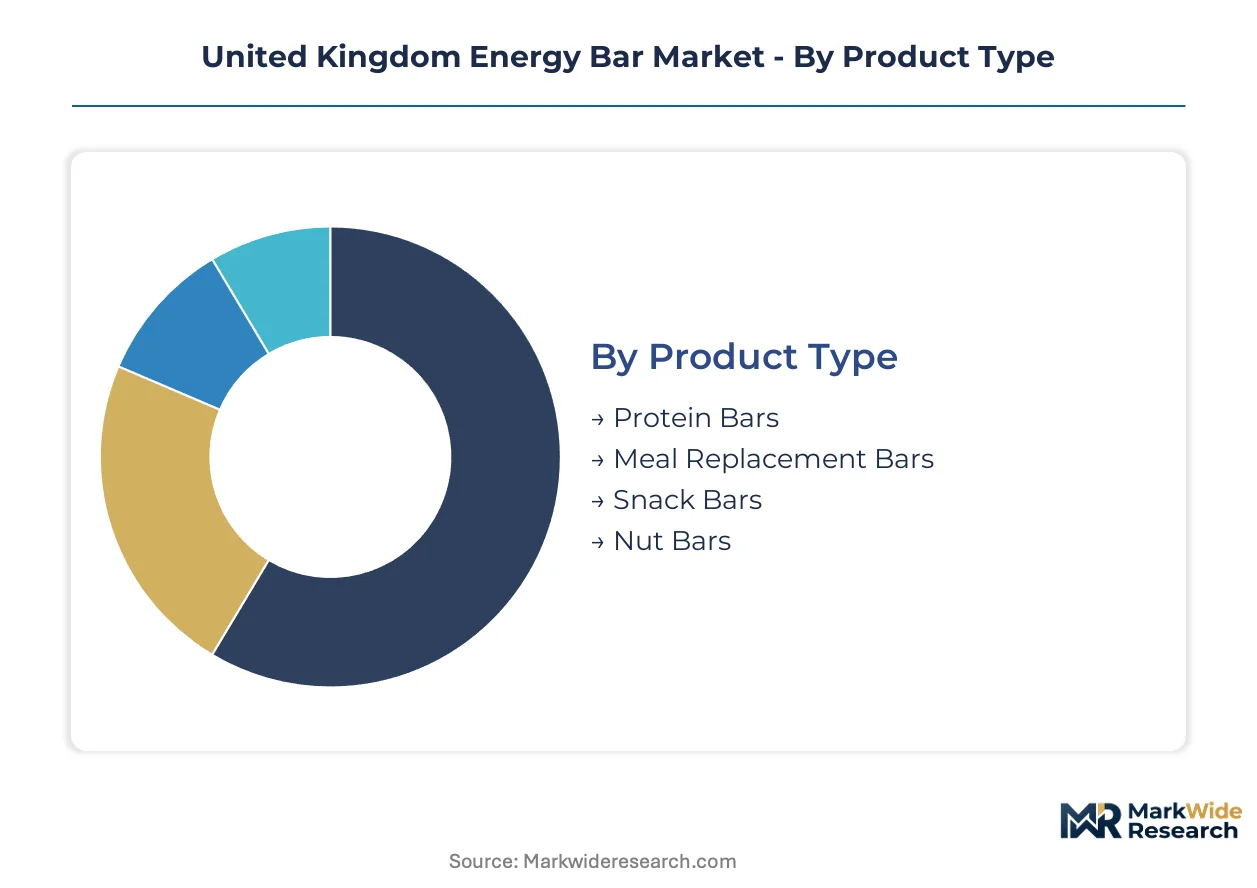
Segmentation in the United Kingdom energy bar market determines formulation priorities, channel investment, and pricing architecture. Product type dictates manufacturing equipment and protein sourcing strategies. End user profiles shape marketing claims and packaging formats. Distribution channel selection controls margin extraction and brand positioning.
Product Type:
After-sales-service intensity varies sharply across product architectures, with meal replacement bars demanding nutritional consultation support and protein bars requiring batch-traceability systems for athlete safety.
- Protein Bars:Formulated with whey isolates or plant concentrates delivering 15-25g protein per serving through cold-press extrusion or baked slab processes. Demand concentrates among gym members in Greater London and the South East corridor where pre-workout and post-workout consumption has normalized into habitual purchase patterns.
- Meal Replacement Bars:Fortified with complete micronutrient profiles and higher caloric density to substitute breakfast or lunch occasions. Time-compressed professionals in Manchester and Birmingham are accelerating adoption for weekday convenience, opening volume increments outside traditional fitness demographics.
- Snack Bars:Lower protein, carbohydrate-forward formulations positioned for impulse consumption between meals.
- Nut Bars:Whole-food architectures emphasizing visible nut inclusions and minimal processing for clean-label positioning.
By volume, protein bars lead. By growth pace, meal replacement bars are expanding most quickly.
End User:
Cost tier stratification separates premium formulations targeting competitive athletes from value-positioned SKUs capturing student budgets.
- Athletes:Competitive and semi-professional sports participants requiring batch-tested formulations with substantiated performance claims. Demand clusters around specialized health stores and direct-to-consumer subscription channels where verification documentation is accessible.
- Fitness Enthusiasts:Recreational gym-goers normalizing bar consumption as part of structured training regimens. This cohort drives volume baselines in Greater London fitness centers and commands the broadest flavor variety.
- Busy Professionals:Time-constrained workers substituting traditional meals with fortified bars during commutes and office hours.
- Students:Price-sensitive consumers prioritizing convenience and portability over premium protein content or specialized formulations.
Athletes command the highest per-unit spend. Busy professionals are gaining share fastest as meal replacement occasions expand beyond fitness contexts.
Distribution Channel:
Geography determines channel viability, with urban density supporting convenience retail while suburban and rural markets rely on supermarket penetration.
- Supermarkets:Tesco, Sainsbury's, and Asda dominate absolute volume through extensive shelf space and promotional mechanics. Listing fees and slotting allowances create barriers for sub-scale brands, compressing margin pools for entrants lacking established trade relationships.
- Online Retail:Direct-to-consumer replenishment programs capture first-party consumption data and bypass supermarket margin extraction. Subscription models are narrowing the advantage that traditional retail listings once held.
- Health Stores:Specialist retailers in Brighton and Bristol accelerate adoption of clean-label and plant-protein innovations.
- Fitness Centers:On-site vending and retail capture pre-workout and post-workout purchase occasions with minimal competitive interference.
Supermarkets retain volume leadership. Online retail is climbing the fastest as subscription mechanics lock in recurring revenue.
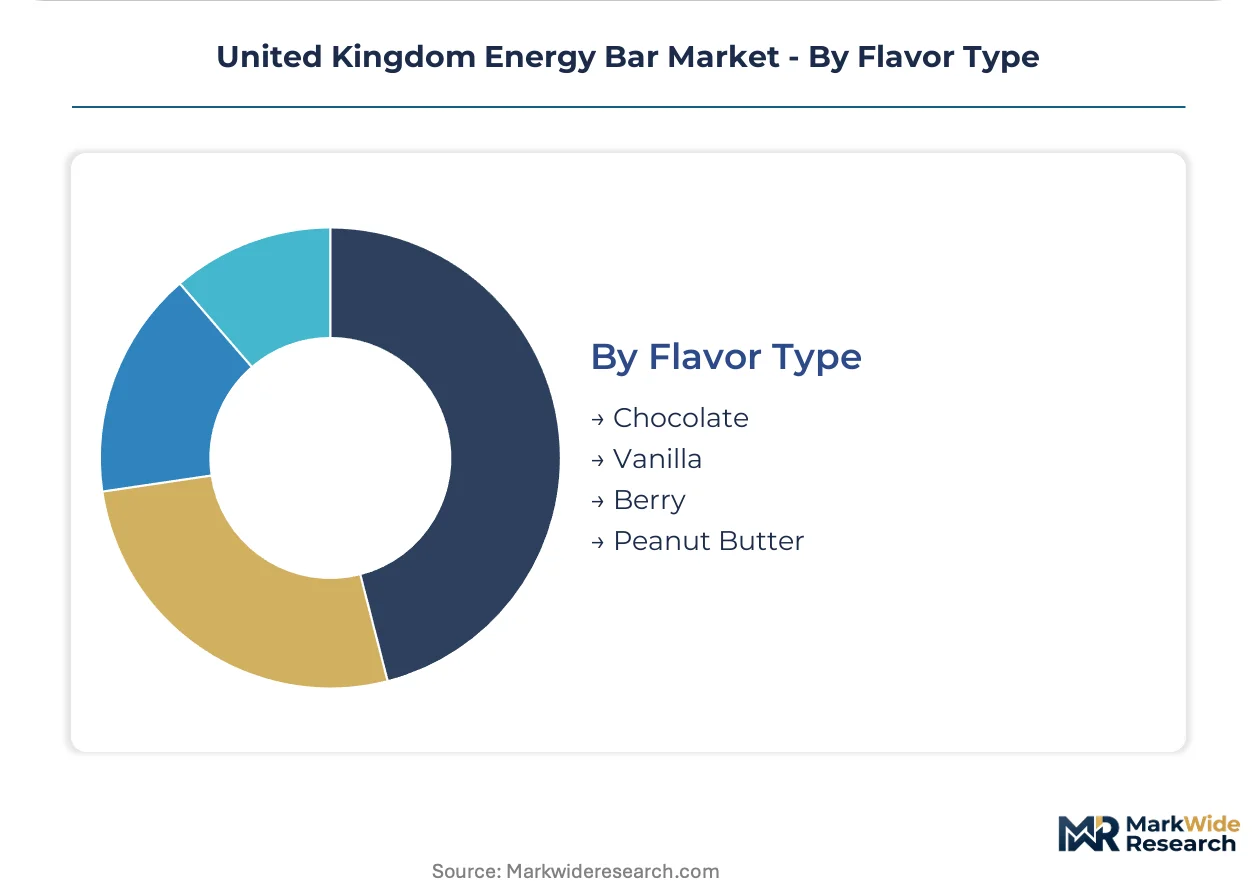
Flavor Type:
Maturity curves separate established profiles with proven manufacturing scalability from emerging variants requiring formulation R&D investment.
- Chocolate:Dominant flavor architecture leveraging cocoa powder and chocolate coatings for mass-market acceptance. Manufacturing processes are standardized across contract manufacturers, enabling rapid SKU proliferation.
- Peanut Butter:High-protein compatibility and texture binding properties make this a staple in sports-focused formulations. Allergen labeling requirements under Food Standards Agency mandates elevate compliance costs for this segment specifically.
- Vanilla:Neutral base supporting protein-forward positioning without competing flavor masking.
- Berry:Fruit-infused variants targeting clean-label and natural-positioned consumers in health-specialist retail.
Chocolate dominates absolute volume. Berry is gaining share fastest as plant-protein texturization advances reduce flavor-masking challenges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater London consumes energy bars primarily as gym-adjacent sports nutrition, while the Midlands and North England increasingly adopt meal replacement formats for workplace convenience. This geographic divergence in usage patterns shapes distinct channel investments and formulation priorities across UK sub-regions.
Greater London and South East
Fitness center density and commuter rail traffic drive pre-workout and grab-and-go consumption. The Food Standards Agency's HFSS placement restrictions force reformulation toward protein-dense architectures qualifying for prominent retail positioning. Specialist health retailers in Brighton accelerate clean-label adoption.
Midlands
Time-compressed professionals in Birmingham and Manchester substitute traditional meals with fortified bars during weekday commutes. The Competition and Markets Authority monitors pricing transparency in online retail channels serving this cohort. Manufacturing clusters around Nottingham supply private-label formulations.
North England
Price-sensitive student populations in Leeds and Sheffield prioritize value-positioned SKUs over premium protein content. The Advertising Standards Authority restricts health benefit assertions in influencer marketing targeting younger demographics. Regional supermarket chains dominate distribution.
Scotland
Outdoor recreation culture in Edinburgh and Glasgow sustains demand for shelf-stable nutrition during hiking and cycling activities. The Food Standards Agency enforces allergen labeling requirements that elevate compliance costs for nut-forward formulations popular in this market.
Wales
Smaller urban centers concentrate consumption in convenience retail rather than fitness-specialist channels. The Welsh Government's food and drink strategy supports local ingredient sourcing for clean-label positioning. Cardiff-based startups test plant-protein texturization innovations.
United Kingdom Energy Bar Market Competitive Landscape
Capability concentration sits with dairy-protein supply chain controllers; scale advantage sits with multinational CPG conglomerates. The market structures around three tiers: global food majors with supermarket leverage, sports-nutrition specialists with gym-channel expertise, and insurgent direct-to-consumer brands with subscription mechanics. Dominant competitive moves include backward integration into protein sourcing and impulse-placement investment in convenience retail.
Within the sports-nutrition specialist tier, Glanbia PLC and Oatein Limited exemplify contrasting strategic positions. Glanbia represents supply-chain-integrated capability concentration, leveraging captive dairy protein access to control input costs. Oatein occupies a differentiation-focused position through texture-engineering expertise. Fulfil Nutrition anchors the convenience-retail impulse strategy, securing high-velocity placement in transport hubs and travel locations.
| Leading Market Players |
|---|
| Glanbia PLC |
| Unilever PLC |
| Mondelez International, Inc. |
| Oatein Limited |
| Fulfil Nutrition |
| Kellogg Company |
| Post Holdings, Inc. |
| HNC Healthy Nutrition Company Ltd. |
| General Mills, Inc. |
| Others |
Value Network & Pricing Analysis
New Zealand and EU dairy auction volatility concentrates upstream protein sourcing power, compressing margin predictability for UK formulators while rewarding Glanbia PLC's captive whey concentrate supply with downstream pricing flexibility against spot-market competitors.
Pricing Analysis
Long-term offtake contracts dominate whey protein concentrate procurement, insulating scaled manufacturers from spot-market dairy commodity swings while smaller brands absorb price volatility through quarterly renegotiation cycles. Price differentiation hinges on clean-label certification tier and gym-channel brand premium versus supermarket private-label compression. Pricing pressure stems from Tesco and Sainsbury's slotting allowance demands that exhaust sub-£5 million revenue brand working capital. Students in Leeds and Sheffield exhibit highest price sensitivity; competitive athletes tolerate premium positioning for batch-tested formulations.
Supply Chain Analysis
Whey protein isolates feed from New Zealand and Irish dairy processing clusters, while extruded pea and fava bean isolates draw from Netherlands and French plant-protein texturization facilities. Raw material dependencies include dairy commodity auctions, binding agent syrups, and chocolate coating inputs. Single-source vulnerability concentrates in whey concentrate supply chains exposed to Oceania drought cycles. Distribution runs through three-tier structure: direct-to-consumer subscription bypasses retail margin extraction, health-specialist channels capture premium positioning, and convenience retail secures impulse velocity in Greater London transport hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Meal replacement occasion expansion among time-compressed professionals signals early-cycle penetration beyond legacy fitness demographics, positioning the market for sustained volume baseline growth as weekday substitution habits normalize.
For Market Incumbents: Build regulatory affairs capability moats through in-house Food Standards Agency substantiation dossier assembly, defending against sub-scale entrants lacking compliance infrastructure. Deepen backward integration into captive dairy protein sourcing to neutralize New Zealand auction volatility. Secure Premier League and Travelodge checkout slots ahead of HFSS placement restriction enforcement to lock impulse channel access against insurgent convenience retail competitors.
For New Entrants and Emerging Players: Build out direct-to-consumer replenishment programs targeting Manchester and Birmingham professionals with subscription mechanics that capture first-party consumption data for flavor pipeline development. White-space opportunity concentrates in plant-protein texturization innovations where extruded pea and fava bean isolates compress the sensory gap with dairy architectures. Health-specialist retail in Brighton and Bristol offers lowest competitive density for clean-label positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer brands possessing subscription revenue bases and first-party data infrastructure but lacking supermarket trade relationships. Five-to-ten year viability hinges on omnichannel execution capability bridging DTC economics with convenience retail velocity. Watch Food Standards Agency HFSS threshold adjustments as inflection signal determining which product architectures retain prominent retail access.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses Tesco and Sainsbury's slotting allowances while capturing recurring revenue and consumption data. |
| Plant-Protein Texturization R&D Investment | Reduces sensory gap with whey formulations, unlocking Brighton and Bristol health-specialist retail placement. |
| Convenience Retail Impulse Placement | Secures Premier League and Travelodge checkout slots capturing unplanned commuter purchase occasions. |
| Food Standards Agency Compliance Dossier Assembly | Enables substantiated "slow release energy" claims that competitors withdraw pending verification. |
| Backward Integration into Dairy Protein Sourcing | Neutralizes New Zealand auction volatility, replicating Glanbia PLC's margin insulation advantage. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with formulation chemists, category buyers at Tesco and Sainsbury's, gym retail managers, and Food Standards Agency regulatory leads; and secondary validation through Nielsen retail audit data, UK customs import records for whey protein concentrates, and Advertising Standards Authority guidance documentation. Bottom-up SKU-level volume aggregation triangulated against top-down category expenditure estimates from consumer panel data.
Forecast inputs spanned protein bar, meal replacement bar, and snack bar architectures across the projection horizon, with flavor type and distribution channel dimensions layered for granularity. CAGRs derived from trend extrapolation adjusted for HFSS placement restriction timing and gym culture penetration saturation curves. Whey protein commodity auction trajectories and cold-press extrusion equipment capacity expansion schedules fed industry-specific forecast sensitivity.
Stress conditions across dairy commodity volatility bands, Food Standards Agency reformulation threshold scenarios, and convenience retail slotting cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about gym membership growth and meal substitution habit formation. Cross-checking against Circana retail velocity benchmarks and Nielsen consumer panel expenditure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Low Calorie Dip Market
Snacks
Middle East and Africa Snack Pellets Market
Snacks
Low Calorie Granola Market
Snacks
Low Calorie Cookies Market
Snacks
Granola Bars Market
Snacks
China Snack Bar Market
Snacks
North America Baked Savory Snacks Market
Snacks
Duck Neck (Chinese Snack) Market
Snacks
North America Cereal Bar Market
Snacks
Fiber Bars Market
Snacks
Healthy Fat-Free Snacks Market
Snacks
Latin America Extruded Snack Food Market
Snacks
Low-Calorie Savoury Snacks Market
Snacks
South America Cereal Bar Market
Snacks
Fat Free Snacks Market
Snacks
Poland Snack Bar Market