
 Cheese Shreds Market | 2026-2036
Cheese Shreds Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Shreds Market Analytics
Buyer concentration among quick-service restaurant chains is hardening as national pizza and Tex-Mex brands consolidate procurement around fewer approved suppliers. Lactalis leverages its European dairy network to supply shredded mozzarella to foodservice operators across multiple continents. Kraft Heinz Company anchors North American retail shelves with branded shred lines in bag and shaker formats. Leprino Foods Company dominates pizza cheese supply through its specialized low-moisture mozzarella production systems.
Cheese shreds consist of pre-cut cheese strands, typically 1.5 to 3 millimeters in width, produced through mechanical cutting or shredding of blocks followed by anti-caking treatment with cellulose or starch to prevent clumping during distribution and storage. Vegetarian rennet-based shreds capture expanding share as enzyme labeling transparency influences consumer selection, while bulk packaging for foodservice channels sustains higher margin pools through volume contracts and direct delivery logistics. Online distribution channels represent the fastest-growing route as cold-chain fulfillment capabilities mature.
FDA enforces standards of identity for cheese products that define moisture content, milkfat thresholds, and permitted ingredients, directly constraining formulation flexibility for shredded cheese marketed in the United States. USDA organic certification and state-level dairy quality programs create tiered compliance burdens that favor processors with dedicated organic shredding lines and traceability systems. Stakeholders must monitor evolving plant-based labeling disputes and precision fermentation alternatives that threaten conventional dairy shred positioning.
Market Dynamics
Quick-service restaurant procurement consolidation is compressing supplier margins while simultaneously demanding extended anti-caking performance guarantees and cold-chain reliability standards that reshape capital allocation across shredding operations.
Growth Catalysts
- USDA organic certification protocols:Certified organic shred lines command shelf-space premiums in US retail channels as private-label buyers enforce traceability mandates. Dedicated organic shredding infrastructure creates defensible supplier positions.
- Vegetarian rennet labeling transparency:Enzyme-origin disclosure requirements in multiple jurisdictions are redirecting formulation decisions toward microbial and fermentation-derived coagulants. Clean-label positioning accelerates category switching.
- Pizza chain volume aggregation:National pizza operators are consolidating mozzarella shred procurement around approved supplier lists with direct-distribution logistics. Foodservice volume contracts sustain margin pools unavailable in fragmented retail.
Market Restraints
- Milk price volatility:Fluid milk and block cheese input costs fluctuate with feed grain markets and dairy herd cycles, compressing shred processor margins during commodity spikes. Hedging instruments add administrative burden without full protection.
- FDA standards of identity constraints:Moisture content and milkfat thresholds for cheese products limit formulation flexibility for reduced-fat or extended-moisture shred variants. Innovation scope narrows within defined identity parameters.
- Precision fermentation dairy proteins:Lab-cultured casein and whey alternatives threaten conventional dairy shred positioning as production scales and cost curves improve. Brand equity in traditional dairy offers temporary insulation.
Strategic Opportunities
- India foodservice penetration:Quick-service pizza and burger chains are expanding store networks in Indian metropolitan markets with limited local shred supply infrastructure. Import partnerships or greenfield shredding facilities capture first-mover advantage.
- Cold-chain e-commerce fulfillment:Direct-to-consumer cheese shred subscription and specialty retail delivery channels mature with insulated packaging and same-day logistics. Premium positioning offsets higher last-mile costs.
- EU Green Deal agricultural transition:Farm-to-fork sustainability mandates and methane reduction incentives favor processors with verified low-carbon milk sourcing and renewable energy shredding operations. Carbon labeling creates differentiation vectors.
Industry Challenges
- Anti-caking agent reformulation timelines:Cellulose and starch alternatives with equivalent clump-prevention performance require extended stability testing across temperature and humidity ranges. FDA GRAS notification or self-affirmation processes add months to product launches.
- Shred length consistency automation:Mechanical cutting systems demand skilled maintenance technicians for blade calibration and optical sorting integration. Labor scarcity in dairy equipment mechanics constrains throughput optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Shreds Market |
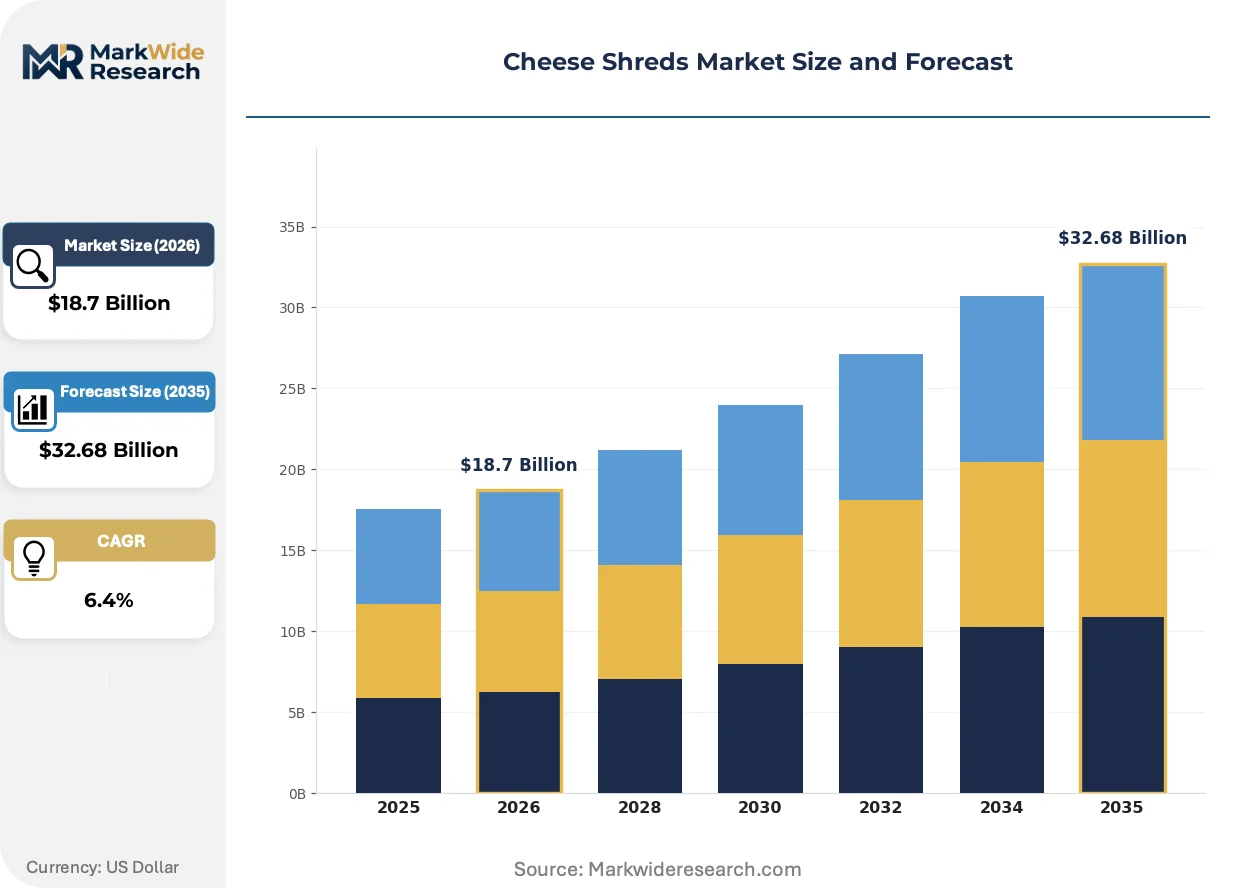
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Non-Vegetarian, Reduced Fat, Organic Packaging Type: Bags, Shakers, Cups, Bulk End User: Households, Restaurants, Cafes, Food Service Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesalers |
| Companies Covered | Lactalis, Kraft Heinz Company, Dairy Farmers of America, Schreiber Foods, Leprino Foods Company, Arla Foods, Saputo Inc., Sargento Foods Inc., Bel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Shreds Market Evolving Landscape
Mechanical shredding and anti-caking treatment technologies are converging with digital traceability systems to transform how cheese shreds move from block processing to final consumption, compressing quality assurance timelines while expanding origin transparency.
Precision fermentation-derived casein is absorbing formulation trials across premium shred lines as microbial protein production achieves functional parity with traditional dairy proteins. Specialty pizza chains in Northern Europe and coastal US metros are piloting these alternatives in blended products. The technology is absorbing R&D budgets that previously targeted only processing efficiency gains, redirecting innovation resources toward ingredient substitution.
EU F-Gas Regulation phase-down schedules are accelerating refrigeration system retrofits in shredding and cold-storage facilities across member states. Processors face capital decisions between compliant synthetic refrigerants and natural alternative systems with higher upfront costs. Central and Eastern European shredding operations with aging infrastructure encounter compressed compliance timelines relative to Western European facilities with recent capital cycles.
Foodservice operators are unbundling shred specification from bundled dairy procurement contracts, creating direct supplier relationships that bypass traditional broadline distributors. Pizza chains with 500-plus unit counts negotiate moisture content, shred dimensions, and anti-caking protocols separately from block cheese purchases. This pattern concentrates most visibly in US Sun Belt markets where chain store density supports dedicated distribution routes.
Cheese Shreds Market Segmentation
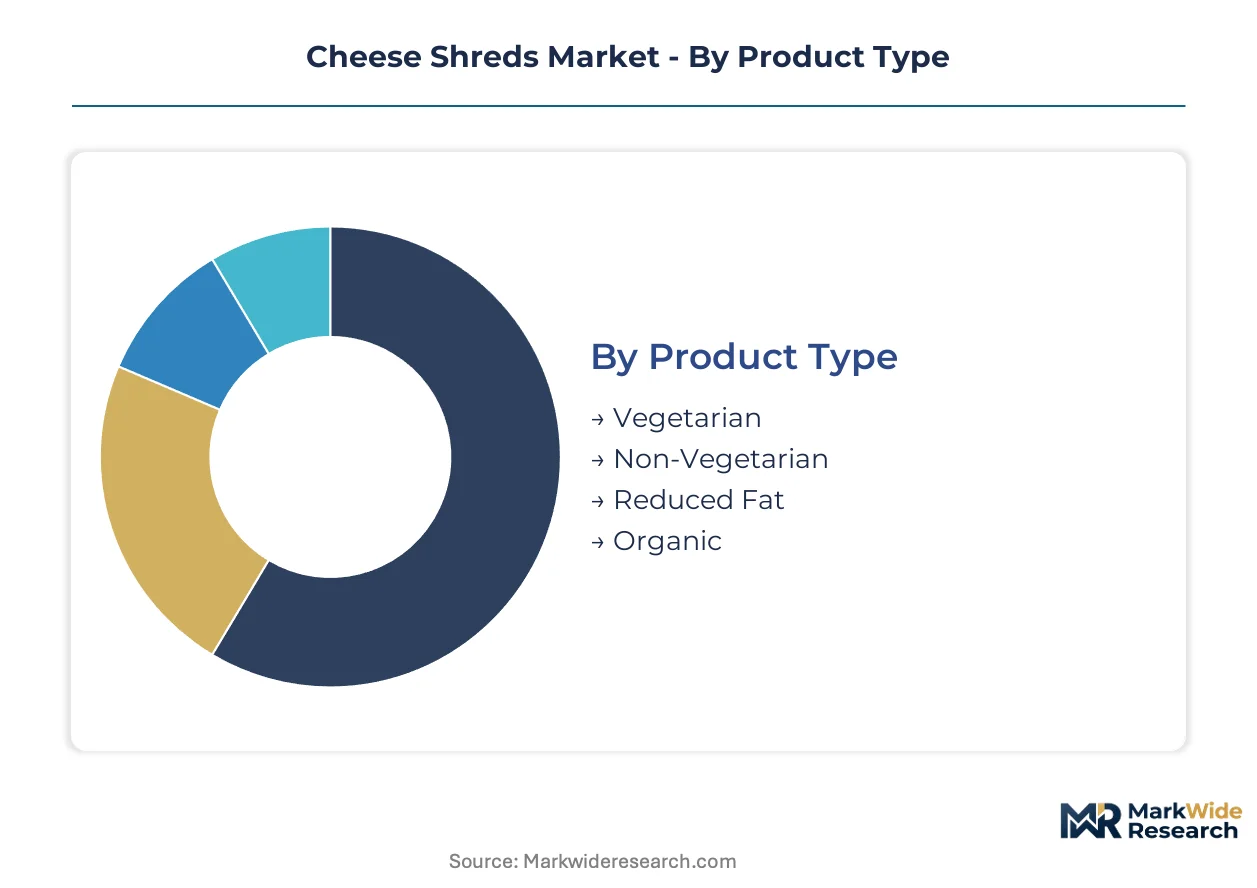
Cheese shred segmentation reveals divergent margin structures across product formulation, packaging format, and channel economics. Procurement patterns in foodservice and retail channels pull suppliers toward incompatible operational footprints, forcing strategic choices on equipment specialization and cold-chain configuration.
Product Type:
Volume leadership rests with conventional formulations, while premium tiers extract margin through certification premiums and ingredient transparency mandates.
- Vegetarian:Microbial and fermentation-derived rennet formulations meet enzyme-origin disclosure requirements across multiple jurisdictions. Pizza chains in Northern Europe and coastal US metros specify vegetarian rennet for menu transparency, with suppliers capturing shelf-space premiums in retail channels where clean-label positioning accelerates category switching.
- Reduced Fat:Moisture content and milkfat thresholds constrained by FDA standards of identity limit formulation flexibility. School nutrition programs and health-system foodservice operators drive procurement volume, though texture degradation in melt applications restricts pizza chain adoption compared to full-fat alternatives.
- Non-Vegetarian:Traditional animal-derived rennet persists in commodity mozzarella supply to price-sensitive foodservice operators. Italian heritage brands and aged cheese shred lines maintain this specification for flavor profile consistency.
- Organic:USDA certification and state-level dairy quality programs create tiered compliance burdens. Dedicated organic shredding infrastructure with traceability systems commands shelf-space premiums as private-label buyers enforce origin mandates.
Today's leader: Vegetarian. Tomorrow's challenger: Organic.
Packaging Type:
Foodservice procurement scale favors bulk configurations, while retail channel fragmentation drives format diversification and anti-caking performance guarantees.
- Bulk:Direct-distribution logistics for quick-service restaurant chains sustain margin pools unavailable in fragmented retail. National pizza operators negotiate moisture content, shred dimensions, and anti-caking protocols under volume contracts with dedicated cold-chain reliability standards.
- Bags:Zip-seal and resealable configurations dominate retail private-label and branded shred lines. Anti-caking treatment with cellulose or starch prevents clumping during distribution and storage, with optical sorting integration ensuring shred length consistency.
- Shakers:Fine-cut parmesan and hard cheese varieties target pasta and salad applications. Shelf-stable formulations with modified atmosphere packaging extend retail distribution reach.
- Cups:Single-serve portions capture convenience-oriented household demand and institutional feeding programs. Portion control specifications align with school nutrition and healthcare foodservice procurement.
Bulk configurations anchor foodservice profitability. Bags drive retail volume expansion.
End User:
Restaurant procurement consolidation concentrates supplier relationships, while household demand fragments across retail channels with divergent quality expectations.
- Restaurants:National pizza and Tex-Mex brands consolidate procurement around approved supplier lists with direct-distribution logistics. Foodservice volume contracts demand extended anti-caking performance guarantees and shred specification unbundled from block cheese purchases.
- Food Service:Broadline distributor bypass accelerates as chains with 500-plus unit counts negotiate direct supplier relationships. Institutional feeding, healthcare systems, and contract catering drive specification standardization.
- Households:Retail private-label penetration concentrates in US supermarkets where price sensitivity dominates purchase decisions. Online subscription and specialty delivery channels mature with insulated packaging and same-day logistics.
- Cafes:Limited-service coffee and sandwich chains drive smaller-format shred procurement with menu localization requirements. Regional supplier relationships predominate given fragmented store networks.
Restaurants command supplier attention today. Food service direct procurement climbs fastest.
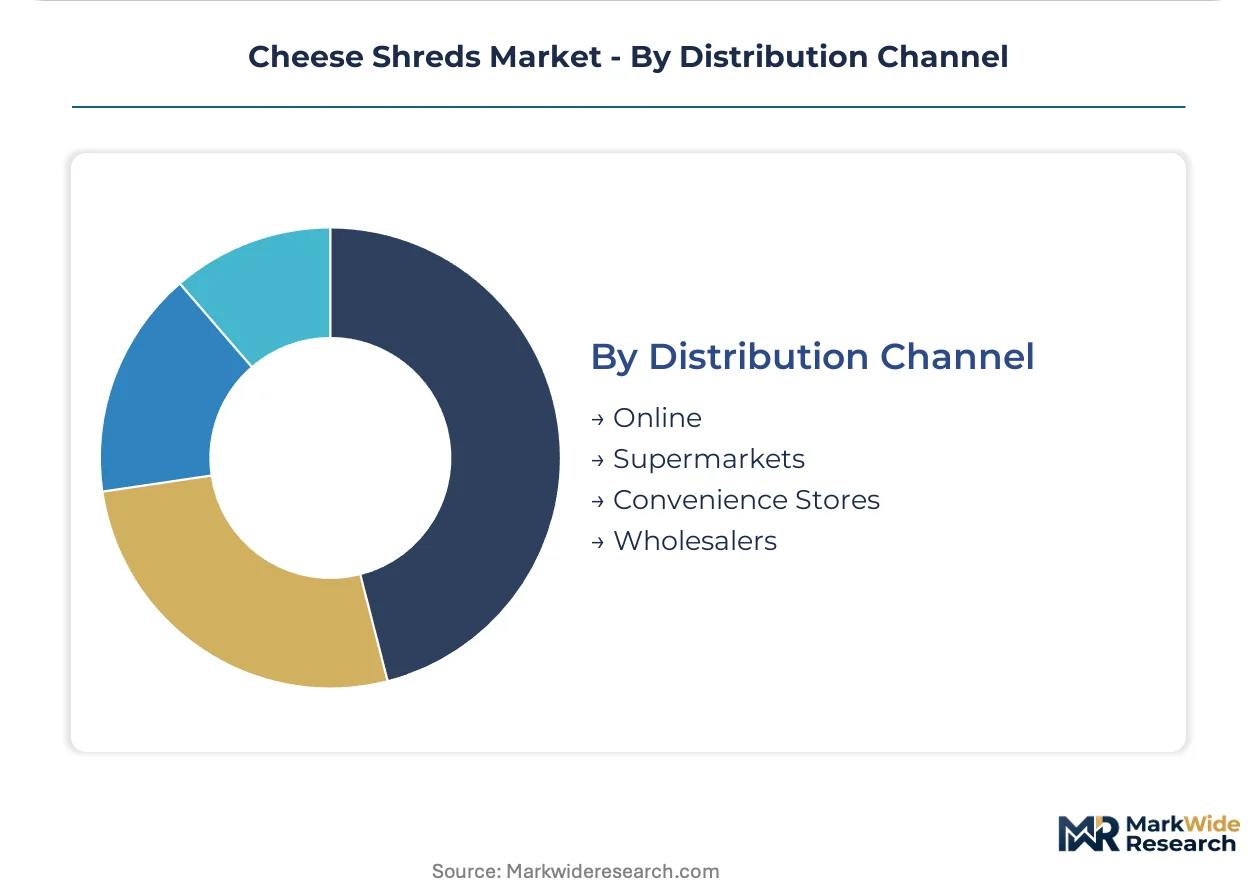
Distribution Channel:
Cold-chain maturity determines channel viability, with digital fulfillment infrastructure expanding addressable market for temperature-sensitive shred products.
- Online:Direct-to-consumer subscription and specialty retail delivery channels represent the steepest expansion trajectory as insulated packaging and same-day logistics mature. Premium positioning offsets higher last-mile costs in metropolitan markets.
- Supermarkets:Private-label buyers enforce traceability mandates and dedicated organic shredding line requirements. Shelf-space allocation battles between branded and store-brand shred lines intensify with category margin compression.
- Wholesalers:Traditional broadline distribution faces unbundling pressure as large foodservice operators negotiate direct supplier relationships. Remaining volume concentrates in fragmented independent restaurant supply.
- Convenience Stores:Grab-and-go prepared food programs drive shredded cheese procurement for hot case and made-to-order applications. Limited cold-storage capacity restricts SKU breadth.
Supermarkets maintain volume dominance. Online channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dairy processing expertise clusters around traditional cheese-making regions with established cold-chain infrastructure and foodservice density. Workforce concentrations in Wisconsin, Lombardy, and Jutland anchor production capacity.
United States
Pizza chain procurement consolidation drives volume concentration in the Upper Midwest and Southwest. FDA standards of identity constrain moisture content and milkfat thresholds for shredded cheese formulations. Wisconsin's Fox River Valley hosts specialized low-moisture mozzarella shredding operations supplying national foodservice contracts.
Germany
EU Green Deal farm-to-fork mandates accelerate methane reduction investments across Bavarian and Lower Saxony dairy cooperatives. EFSA labeling requirements and national organic certification programs shape product formulation decisions. The Allgäu alpine dairy cluster maintains traditional shredding capacity while retrofitting refrigeration systems for F-Gas Regulation compliance.
Italy
Protected designation of origin enforcement preserves premium positioning for Parmigiano-Reggiano and Grana Padano shred lines. Ministry of Agricultural, Food and Forestry Policies (MIPAAF) traceability protocols favor processors with integrated farm-to-shred documentation. Emilia-Romagna's Parma and Reggio Emilia provinces concentrate heritage shredding infrastructure for export markets.
India
Quick-service restaurant expansion in Mumbai, Delhi-NCR, and Bangalore outpaces domestic shred supply infrastructure. FSSAI dairy safety standards and state-level milk quality programs create compliance entry barriers. Maharashtra's Pune-Nashik corridor attracts greenfield shredding investment from international dairy processors seeking foodservice partnerships.
France
ANSM and DGCCRF enforcement of enzyme-origin labeling redirects formulation toward microbial rennet alternatives. CAP reform decoupling payments reshape dairy farm economics in Normandy and Brittany. The Loire Valley and Franche-Comté regions sustain artisanal shredding capacity for specialty retail channels.
Cheese Shreds Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidation patterns concentrate around three structural layers: multinational dairy groups with integrated shredding operations, regional cooperatives with foodservice specialization, and private-label converters serving retail channels. Dominant competitive moves include direct-distribution logistics investments for quick-service restaurant procurement and dedicated organic shredding line construction for traceability premiums.
Within the multinational tier, Lactalis leverages its European dairy network across multiple continents while Kraft Heinz Company anchors North American retail shelf presence. Leprino Foods Company exemplifies foodservice specialization through its pizza cheese supply focus. These three occupy positions reflecting distinct strategic archetypes: geographic diversification, retail brand equity, and operational scale concentration respectively.
| Leading Market Players |
|---|
| Lactalis |
| Kraft Heinz Company |
| Dairy Farmers of America |
| Schreiber Foods |
| Leprino Foods Company |
| Arla Foods |
| Saputo Inc. |
| Sargento Foods Inc. |
| Bel Group |
| Others |
Value Network & Pricing Analysis
Quick-service restaurant procurement consolidation around direct-distribution logistics is forcing shred processors to absorb cold-chain reliability costs while negotiating volume contracts that compress per-unit margins. This buyer-driven restructuring concentrates pricing power among national pizza chains with 500-plus unit counts, leaving suppliers to recover value through anti-caking performance guarantees and specification unbundling.
Pricing Analysis
Capacity additions in India and Central Europe are reshaping price floors for commodity mozzarella shreds as greenfield facilities compete for foodservice volume contracts. Pricing stratifies across premium, standard, and economy tiers based on USDA organic certification status and vegetarian rennet labeling transparency. Cost compression in standard-tier supply is intensifying because milk price volatility and precision fermentation alternatives squeeze processor margins. Quick-service restaurant chains exhibit highest price sensitivity through consolidated procurement, while specialty retail channels and direct-to-consumer subscriptions show lowest sensitivity due to clean-label premiums.
Supply Chain Analysis
USDA organic certification and FDA standards of identity create qualification gating that fragments supplier tiers and extends product launch timelines through GRAS notification requirements. Milk supply draws from the United States, Germany, and Italy as dominant sourcing regions, with block cheese inputs, anti-caking agents, and cold-chain logistics forming critical dependencies. Single-source vulnerability concentrates in specialized low-moisture mozzarella production systems where Leprino Foods maintains operational scale advantages. Distribution runs through direct-supplier relationships for foodservice chains and supermarket private-label networks for retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA standards of identity and USDA organic certification protocols compound competitive advantage for processors with dedicated compliance infrastructure, turning regulatory burden into demand-generation machinery. The report frames this market as a regulatory compounder where traceability mandates and enzyme-origin disclosure requirements continuously reshape procurement criteria.
For Market Incumbents: Lock in foodservice volume contracts through extended anti-caking performance guarantees and direct-distribution logistics investments that bypass traditional broadline distributors. Precision fermentation alternatives threaten conventional dairy shred positioning as production scales, making backward integration into low-carbon milk sourcing and renewable energy shredding operations the priority defensive lever against carbon labeling differentiation. For New Entrants and Emerging Players: FSSAI dairy safety standards in India open a window for greenfield shredding facilities in the Pune-Nashik corridor as quick-service restaurant expansion outpaces domestic supply infrastructure. Cold-chain e-commerce fulfillment represents the most penetrable white-space target, with direct-to-consumer subscription models offering premium positioning that offsets higher last-mile costs. A certification-first go-to-market angle targeting USDA organic or EU Green Deal compliance captures shelf-space premiums in fragmented retail channels. For Investors and Strategic Acquirers: Asymmetric upside sits with regional cooperatives with foodservice specialization and dedicated organic shredding infrastructure. The five-to-ten year viability window favors processors with verified traceability systems and direct-distribution logistics capabilities rather than commodity converters dependent on broadline distributor relationships. Watch precision fermentation cost curves as the inflection indicator that could displace conventional dairy shred positioning in premium pizza chain procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Distribution Logistics Investment | Bypasses broadline distributors to capture foodservice margin pools unavailable in fragmented retail channels. |
| Dedicated Organic Shredding Line Construction | USDA certification and traceability systems command shelf-space premiums as private-label buyers enforce origin mandates. |
| Precision Fermentation Partnership | Microbial casein production achieves functional parity with traditional dairy proteins in premium shred formulations. |
| Cold-Chain E-Commerce Fulfillment Buildout | Insulated packaging and same-day logistics mature direct-to-consumer subscription channels in metropolitan markets. |
| Renewable Energy Shredding Operations | EU Green Deal methane reduction incentives favor processors with verified low-carbon milk sourcing and carbon labeling. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy procurement managers at quick-service restaurant chains, shredding operations plant managers, retail category buyers, cold-chain logistics coordinators, and regulatory affairs specialists with secondary validation. FDA standards of identity documentation, USDA organic certification records, EU F-Gas Regulation compliance filings, and FSSAI dairy safety standards formed core secondary sources. Bottom-up volume modeling across product type, packaging format, end user, and distribution channel segments triangulated against top-down market sizing.
Historical reference periods anchored the projection horizon through documented procurement consolidation patterns and anti-caking technology adoption curves. Segmentation dimensions modeled included product formulation tier, packaging configuration, channel economics, and regional regulatory cluster. CAGRs derived from compound growth mechanics applied to baseline volume and value estimates. Industry-specific forecast inputs incorporated milk price volatility cycles, precision fermentation production scale trajectories, and cold-chain e-commerce penetration rates.
Revisions become necessary when precision fermentation cost curves achieve parity with conventional dairy proteins, when F-Gas Regulation phase-down schedules accelerate refrigeration system retrofits, or when pizza chain procurement consolidation shifts toward unbundled shred specification. Forecasts reflect assumptions about anti-caking agent stability testing timelines, organic certification traceability system deployment, and direct-distribution logistics network maturation. A model refresh is warranted upon material change in FDA standards of identity enforcement or EU Green Deal agricultural transition incentives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Emmental Cheese Market
Dairy Products
North America Organic Dairy Market
Dairy Products
Colombia Dairy Market
Dairy Products
Donkey Milk Market
Dairy Products
Fluid Milk Market
Dairy Products
Mozzarella Cheese Market
Dairy Products
North America Anhydrous Milk Fat Market
Dairy Products
Global Dairy Market
Dairy Products
Europe Yogurt Market
Dairy Products
North America Sour Cream Market
Dairy Products
Lactic Butter Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
Latin America Cheese Market
Dairy Products
Canada Casein and Caseinate Market
Dairy Products
Flavored Yogurt Market