
 Goldenseal Market | 2026-2036
Goldenseal Market Size, Share, and Industry Trends Forecast 2026-2036
Goldenseal Market Outlook
Appalachian wild-crafting communities is realigning harvest volumes amid sustainability pressures from state conservation agencies. Solaray leverages long-standing relationships with certified organic growers to secure consistent berberine-rich rootstock. Nature's Way anchors its supply chain through cultivated sourcing partnerships that reduce pressure on wild populations. Eclectic Herb specializes in liquid extraction methods that preserve the full spectrum of hydrastine alkaloids.
Goldenseal (Hydrastis canadensis) is a perennial herb native to eastern North American hardwood forests, valued for its roots and rhizomes containing the isoquinoline alkaloids berberine and hydrastine, typically standardized to 5% total alkaloid content for commercial extracts. The plant serves primarily as a botanical ingredient in immune-support and digestive-health formulations across dietary supplement and traditional medicine channels. Capsules and liquid extracts capture the largest volume share among product types, driven by consumer convenience and practitioner dispensing preferences. Online retail and health stores represent the fastest-expanding distribution channels, reflecting a structural shift toward direct-to-consumer botanical purchasing that bypasses conventional pharmacy gatekeepers.
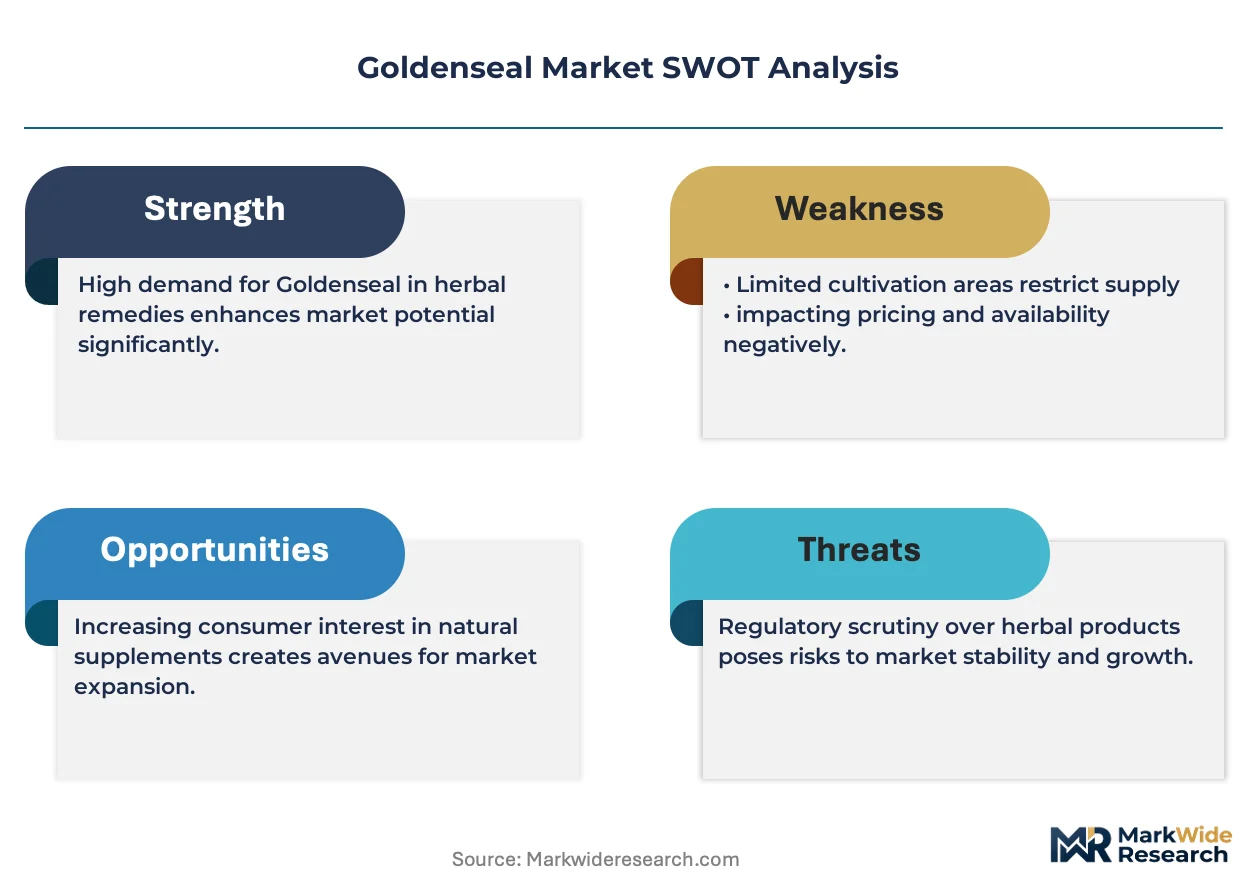
The FDA's DSHEA framework and current Good Manufacturing Practice (cGMP) regulations enforce identity testing and heavy-metal screening for goldenseal raw materials entering interstate commerce. The USDA National Organic Program certifies cultivation operations, while state-level wild-harvest permits in Kentucky, Tennessee, and West Virginia govern collection from public lands. Stakeholders must monitor CITES listing deliberations and state conservation designations that could restrict wild sourcing and trigger accelerated investment in domestic cultivation infrastructure.
Market Dynamics
Appalachian wild-harvesting restrictions and the FDA's cGMP enforcement are compressing raw material availability while forcing dietary supplement manufacturers toward verified cultivation partnerships and identity-tested sourcing protocols.
Growth Catalysts
- DSHEA framework compliance:The FDA's identity testing and heavy-metal screening requirements create competitive separation for suppliers with validated laboratory infrastructure and certified organic operations.
- Botanical immune support demand:Consumer preference for plant-based wellness formulations pulls goldenseal into expanded SKU portfolios across practitioner and direct-to-consumer channels.
- Cultivation infrastructure investment:Kentucky and Tennessee operations are scaling certified organic acreage to replace pressure-depleted wild populations and secure alkaloid-standardized rootstock.
Market Restraints
- Wild population depletion:State conservation agencies in West Virginia and Kentucky have reduced permitted harvest volumes on public lands, constraining raw material inflows from traditional Appalachian sourcing corridors.
- Alkaloid content variability:Hydrastis canadensis exhibits significant berberine and hydrastine concentration variation across harvest sites and cultivation batches, complicating standardization to commercial 5% total alkaloid specifications.
- Substitution pressure from barberry:Berberis species offer chemically similar berberine profiles at lower procurement costs, threatening goldenseal's position in price-sensitive immune-support formulations.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retail platforms bypass conventional pharmacy gatekeepers and capture margin previously allocated to wholesale distribution layers.
- Liquid extraction format growth:Practitioner dispensing preferences and bioavailability claims favor tincture and glycerite formats over encapsulated powders in clinical herbalism channels.
- USDA Organic certification premium:Certified cultivation commands pricing separation from conventional wild-harvested material and satisfies clean-label procurement criteria from major supplement brands.
Industry Challenges
- Multi-year cultivation cycles:Hydrastis canadensis requires four to six years from seed or rhizome division to harvestable rootstock, locking working capital and creating supply-demand timing mismatches.
- Wild-crafting knowledge erosion:Appalachian harvester populations are aging without sufficient generational transfer of sustainable digging practices and population assessment techniques.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Goldenseal Market |
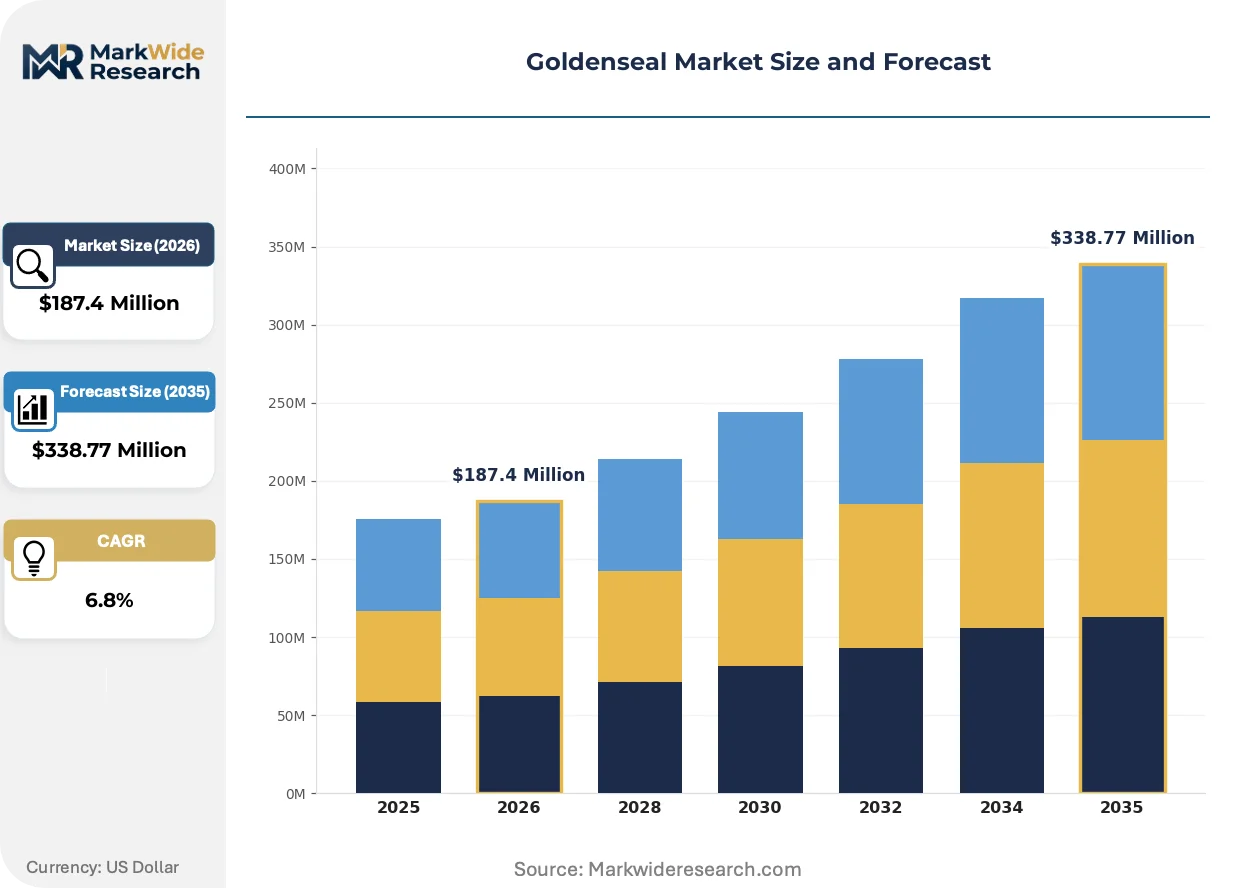
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Extract, Powder, Capsules, Tincture Use Case: Herbal Remedies, Dietary Supplements, Traditional Medicine, Natural Antibiotics Distribution Channel: Online Retail, Health Stores, Pharmacies, Herbal Shops End User: Consumers, Healthcare Practitioners, Herbalists, Nutritionists |
| Companies Covered | Solaray, Enzymedica, Nature's Way, Amazing Formulas, Eclectic Herb, Nutricost, Natural Factors, GlucoVantage, Swanson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Goldenseal Market Strategic Shifts
Near-infrared spectroscopy and DNA barcoding are displacing traditional organoleptic identification methods across goldenseal raw material verification, compressing authentication timelines while raising capital requirements for supplier laboratories.
Spectroscopic analysis is automating alkaloid quantification and adulterant detection at receiving docks, replacing thin-layer chromatography and macroscopic examination protocols that required specialized botanical expertise. Mid-tier supplement manufacturers lacking in-house analytical capabilities are outsourcing verification to third-party laboratories or demanding pre-certified raw materials from cultivation partners. This technology compression is concentrating procurement relationships toward vertically integrated suppliers with captive quality control infrastructure.
The FDA's cGMP regulations for dietary supplements now mandate identity testing for every lot of botanical raw material, with specific documentation requirements for species verification and contamination screening. This enforcement trajectory elevates compliance costs for small-scale wild-harvesting operations while rewarding cultivated supply chains with batch-to-batch consistency and traceable documentation. Appalachian sourcing networks are responding by forming cooperative quality alliances or exiting interstate commerce entirely.
Practitioner channel buyers are consolidating purchasing around single-source cultivation partnerships with transparent alkaloid certificates of analysis, displacing spot-market procurement from aggregated wild-harvested material. This preference shift compresses margins for commodity brokers while rewarding direct grower relationships. The clinical herbalism segment in the Pacific Northwest and New England metropolitan corridors exhibits the most pronounced consolidation toward verified provenance sourcing.
Goldenseal Market Segmentation
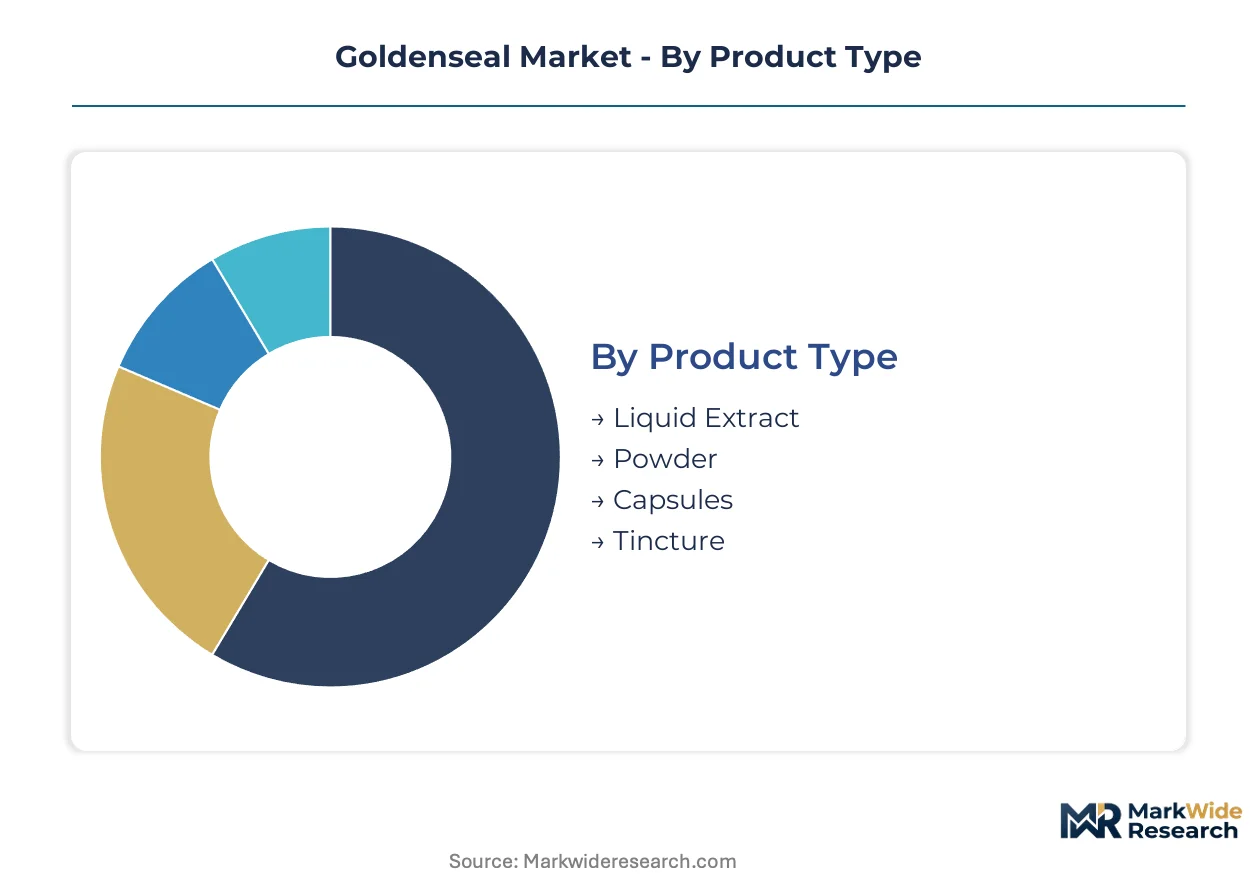
Goldenseal segmentation reveals how formulation chemistry, practitioner dispensing protocols, and alkaloid standardization requirements fragment demand across distinct procurement channels. Each category reflects divergent buyer priorities: bioavailability claims drive liquid formats, while regulatory compliance shapes distribution access.
Product Type:
Buyers in this category separate by consumption context and shelf-stability requirements rather than price sensitivity alone.
- Liquid Extract:Glycerite and ethanol-based preparations preserve the full alkaloid spectrum including heat-sensitive hydrastine fractions. Practitioner channels in the Pacific Northwest and New England metropolitan corridors concentrate demand here, driven by clinical herbalism protocols that prioritize rapid sublingual absorption.
- Capsules:Standardized powdered rootstock in gelatin or vegetable shells dominates direct-to-consumer procurement through online retail platforms. Kentucky and Tennessee cultivation operations supply alkaloid-tested material meeting 5% total alkaloid specifications for this high-volume segment.
- Powder:Bulk raw material serves compounding herbalists and small-scale supplement manufacturers requiring formulation flexibility.
- Tincture:Alcohol-based extractions with defined herb-to-solvent ratios appeal to traditional medicine practitioners and home remedy preparation.
Volume sits with Capsules; growth tilts toward Liquid Extract.
Use Case:
Application context determines alkaloid standardization stringency and documentation requirements for raw material sourcing.
- Dietary Supplements:FDA cGMP compliance mandates identity testing and heavy-metal screening for every production lot. Major brands anchor procurement through certified organic cultivation partnerships in Kentucky that deliver batch-consistent berberine profiles.
- Herbal Remedies:Traditional preparation methods emphasize whole-root integrity over isolated alkaloid standardization. Appalachian wild-harvesting networks supply this segment through state-permitted collection on public lands in West Virginia and Tennessee.
- Traditional Medicine:Indigenous and folk medicine practitioners prioritize sustainable harvesting relationships with documented provenance.
- Natural Antibiotics:Berberine-content claims drive demand for laboratory-verified material in antimicrobial applications.
Revenue concentrates in Dietary Supplements; Herbal Remedies face supply compression from state conservation restrictions.
Distribution Channel:
Channel selection reflects margin capture strategy and regulatory gatekeeper bypass preferences among supplement brands.
- Online Retail:Direct-to-consumer platforms eliminate wholesale distribution markups and enable subscription-based replenishment models. This channel absorbs the steepest expansion trajectory as botanical buyers migrate from brick-and-mortar pharmacy networks.
- Health Stores:Specialty retailers provide educated staff consultation and immediate product access for immune-support purchasing decisions.
- Pharmacies:Conventional drugstore chains represent a contracting channel as pharmacist gatekeeping limits botanical placement.
- Herbal Shops:Independent apothecaries serve practitioner-directed dispensing with custom formulation services.
Transaction volume flows through Health Stores; margin expansion favors Online Retail.
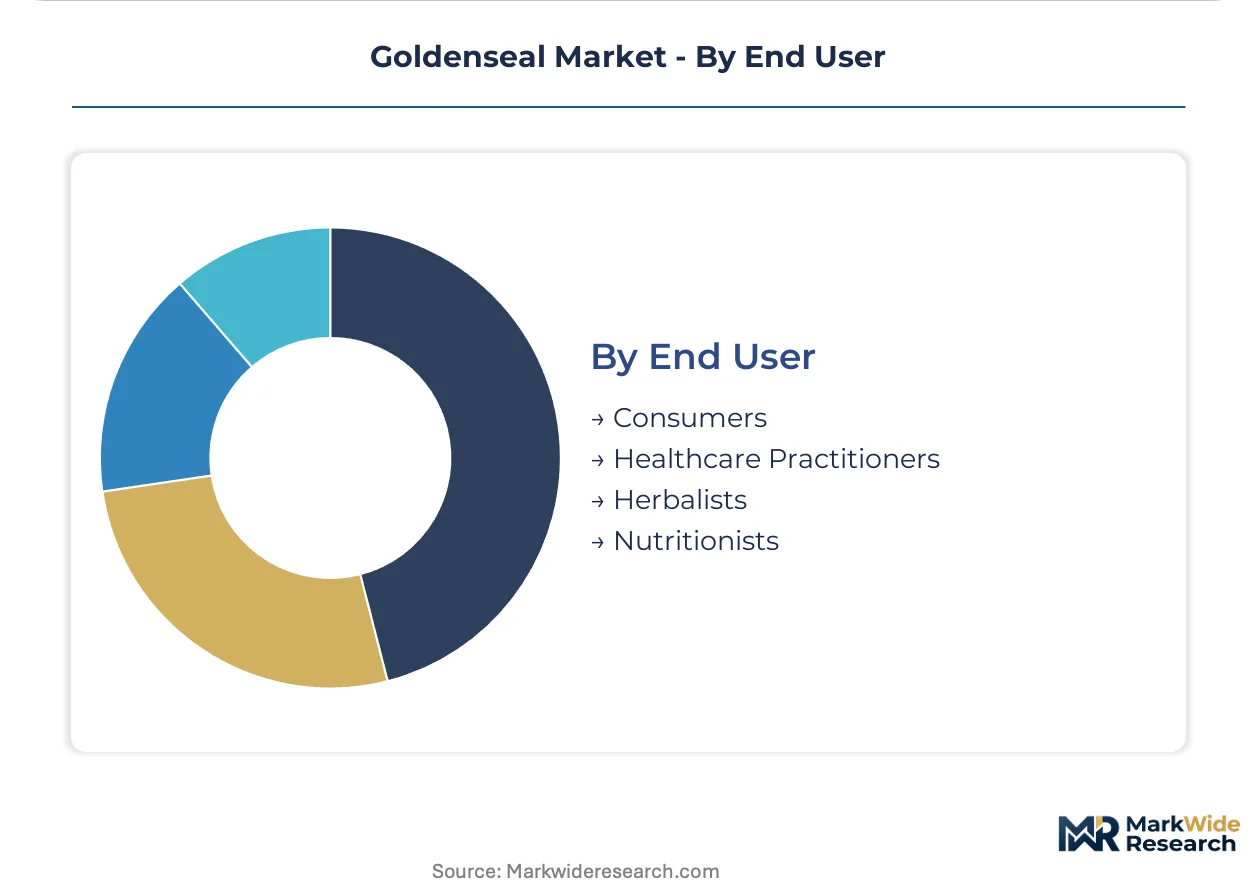
End User:
Professional credentialing separates buyers by analytical sophistication and sourcing documentation requirements.
- Healthcare Practitioners:Naturopathic physicians and integrative medicine clinics demand certificates of analysis with every lot, consolidating procurement around single-source cultivation partnerships with transparent alkaloid verification.
- Herbalists:Clinical and community practitioners blend cultivated and wild-harvested material based on sustainability criteria and therapeutic tradition.
- Consumers:Self-directed buyers rely on brand reputation and USDA Organic certification as quality proxies.
- Nutritionists:Dietary counselors incorporate goldenseal into gut-health protocols with varying emphasis on berberine bioavailability.
Procurement scale clusters with Consumers; certificate-of-analysis requirements concentrate among Healthcare Practitioners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Appalachian hardwood forests anchor goldenseal supply geography, with wild-harvesting traditions and emerging cultivation infrastructure concentrated in eastern North American states. Demand flows through dietary supplement manufacturing clusters and direct-to-consumer distribution hubs.
United States
Kentucky and Tennessee cultivation operations supply alkaloid-standardized rootstock to major supplement brands. The FDA's cGMP regulations enforce identity testing and heavy-metal screening for every production lot entering interstate commerce. Solaray and Nature's Way anchor procurement through certified organic partnerships in these states.
Canada
Health Canada regulates goldenseal as a natural health product under the Natural and Non-prescription Health Products Directorate framework. British Columbia and Ontario host supplement manufacturing and distribution operations serving domestic and export markets. Natural Factors represents Canadian market presence through domestic formulation and retail channels.
Germany
The European Medicines Agency's herbal monograph framework governs Hydrastis canadensis quality specifications for traditional use registrations. Bavaria and Baden-Württemberg concentrate phytopharmaceutical manufacturing and botanical extraction expertise. German consumers access goldenseal through pharmacy and specialized herbal retailer networks.
United Kingdom
The Medicines and Healthcare products Regulatory Agency oversees traditional herbal registration pathways for goldenseal-containing products. London and Southeast England clusters house supplement distribution and e-commerce fulfillment operations. British practitioners source material through importer relationships with North American cultivation partners.
Australia
The Therapeutic Goods Administration lists goldenseal in the Australian Register of Therapeutic Goods for complementary medicine applications. New South Wales and Victoria concentrate naturopathic practitioner networks and specialty health retail. Australian demand pulls through direct import channels and licensed complementary medicine suppliers.
Goldenseal Market Competitive Environment
Global majors compete with regional champions across cultivation partnerships and alkaloid verification capabilities. The vendor base clusters around three tiers: vertically integrated botanical houses with captive laboratory infrastructure, mid-scale organic cultivators serving single-source contracts, and commodity brokers aggregating wild-harvested material. Strategic moves concentrate on certified organic acreage expansion and near-infrared spectroscopy deployment for raw material authentication.
Within the integrated botanical tier, Solaray and Nature's Way exemplify cultivation-backed supply chain architectures. Eclectic Herb occupies a specialist position emphasizing liquid extraction formats. These three anchors represent divergent responses to FDA cGMP pressure: captive organic cultivation, multi-source verified partnerships, and format-specific extraction expertise.
| Leading Market Players |
|---|
| Solaray |
| Enzymedica |
| Nature's Way |
| Amazing Formulas |
| Eclectic Herb |
| Nutricost |
| Natural Factors |
| GlucoVantage |
| Swanson |
| Others |
Value Chain & Pricing Dynamics
Captive cultivation partnerships in Kentucky and Tennessee anchor both supply security and pricing power for alkaloid-standardized goldenseal rootstock. The FDA's cGMP identity-testing mandates create a compliance moat that rewards vertically integrated suppliers with verified laboratory infrastructure while compressing margins for wild-harvesting operations lacking batch documentation.
Pricing Analysis
Certificate-of-analysis bundling separates premium-tier cultivated material from unverified wild-harvested supply. Three-tier pricing structure across certified organic, conventionally cultivated, and state-permitted wild collections reflects alkaloid standardization stringency and traceability depth. Pricing pressure stems from barberry substitution in berberine-focused immune formulations, eroding goldenseal's position in price-sensitive SKUs. Direct-to-consumer channels exhibit lowest price sensitivity due to brand-premium capture, while commodity brokers serving compounding herbalists face acute margin compression.
Supply Chain Analysis
Dual-sourcing requirements from major supplement brands mandate qualification of both Kentucky-Tennessee cultivation networks and Appalachian wild-harvesting cooperatives with state permits. Raw material dependencies center on berberine-rich Hydrastis canadensis rhizomes, organic certification compliance, and laboratory-verified alkaloid certificates. Supply chain risk concentrates in single-source vulnerability from four-to-six-year cultivation cycles that lock working capital and create demand-supply timing mismatches. Distribution runs through certified organic grower partnerships directly to supplement manufacturers, bypassing commodity aggregation layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The goldenseal market functions as a cost-of-compliance story where FDA cGMP regulations erect barrier-to-entry moats favoring players with captive laboratory infrastructure and certified organic acreage.
For Market Incumbents: Acquire near-infrared spectroscopy and DNA barcoding capabilities to automate raw material authentication and displace traditional organoleptic methods. Barberry substitution in berberine applications threatens price-positioning; defend by deepening cultivation partnerships in Kentucky that guarantee hydrastine-preservation for full-spectrum liquid extracts. Certification investment in USDA Organic and state wild-harvest permits secures channel access as conservation restrictions tighten. For New Entrants and Emerging Players: Capture practitioner-directed dispensing channels in Pacific Northwest and New England metropolitan corridors where clinical herbalism protocols prioritize rapid-absorption liquid formats over encapsulated powders. White-space concentrates in glycerite and ethanol-based preparations serving naturopathic physicians demanding transparent alkaloid verification. Go-to-market leverage rests on single-source cultivation partnerships with batch-consistent documentation displacing spot-market procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated botanical houses seeking captive laboratory infrastructure and certified organic acreage. Long-term viability favors cultivation-backed supply chain architectures over commodity brokerage models as FDA enforcement elevates compliance costs. Watch CITES listing deliberations as inflection signal that would trigger accelerated domestic cultivation investment and compress wild-harvesting participation.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Organic Acreage Expansion | Kentucky and Tennessee operations scale to replace pressure-depleted wild Appalachian populations. |
| Laboratory Infrastructure Deployment | Near-infrared spectroscopy automates alkaloid quantification and adulterant detection at receiving docks. |
| Direct-to-Consumer Channel Buildout | Online retail platforms bypass wholesale markups and capture margin previously allocated to distribution layers. |
| Single-Source Cultivation Partnerships | Practitioner buyers consolidate procurement around transparent certificates of analysis with every lot. |
| Liquid Extraction Format Development | Glycerite and ethanol preparations preserve heat-sensitive hydrastine fractions for clinical herbalism channels. |
Study Parameters
USDA National Organic Program certification records, FDA cGMP inspection databases, and state-level wild-harvest permit filings in Kentucky, Tennessee, and West Virginia formed the secondary backbone. Primary interviews with certified organic growers, dietary supplement procurement directors, clinical herbalists, and state conservation agency officials combined with this secondary validation. Bottom-up and top-down triangulation cross-checked cultivation acreage estimates against alkaloid-standardized rootstock demand from major supplement brands.
Bottom-up modeling anchored volume projections to certified organic acreage expansion trajectories and wild-harvest permit volume restrictions across the analysis window. Segmentation dimensions included product type, use case, distribution channel, and end user with alkaloid standardization tier as a cross-cutting variable. CAGRs derived from supply-demand balance modeling that weighted four-to-six-year cultivation cycles against practitioner channel growth and direct-to-consumer platform expansion. Forecast inputs incorporated FDA cGMP enforcement trajectory and CITES listing probability assessments.
The model holds under sustained FDA cGMP enforcement and stable state-level wild-harvest permit allocations; deviation in CITES Appendix II listing or Appalachian conservation designation shifts would compress wild-sourced supply and accelerate cultivation infrastructure investment materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Fermented Black Beans Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Foie Gras Market
Specialty Foods
Super Foods Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Free-From Food Market
Specialty Foods
Space Food Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
North America Hummus Market