
 Dill Juice Market | 2026-2036
Dill Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Dill Juice Market Outlook
Specialty beverage distribution is reshaping how dill juice reaches end consumers, with direct-to-athlete channels and functional drink partnerships gaining priority. The Pickle Juice Company leverages vertical integration from brine sourcing to bottling, sustaining consistent supply for sports teams and gyms. McCormick & Company anchors the ingredient supply tier, competing through flavor science partnerships with beverage co-packers. Mt. Olive Pickle Company dominates retail shelf presence, extending its pickle brand equity into adjacent juice SKUs.
Dill juice is an aqueous extract derived from fermented or fresh dill cucumbers, containing acetic acid, sodium, potassium, and trace lactobacillus cultures, produced through brine fermentation or cold-pressed extraction for use in hydration, mixology, and digestive health applications. Organic dill juice leads volume among product types, though cold-pressed variants command premium positioning in specialty stores where margin pools deepen. Glass bottles remain the preferred packaging for premium positioning, while food service channels drive bulk container demand as restaurants incorporate dill juice into cocktail programs and brining operations.
The FDA governs acidified food safety and labeling requirements for dill juice products, while USDA organic certification shapes premium tier access and pricing power. State-level cottage food laws in Texas, California, and New York create fragmented compliance pathways for small-batch producers entering retail. Stakeholders must monitor regulatory divergence between fermented beverage classifications and sports drink standards as enforcement priorities shift.
Market Dynamics
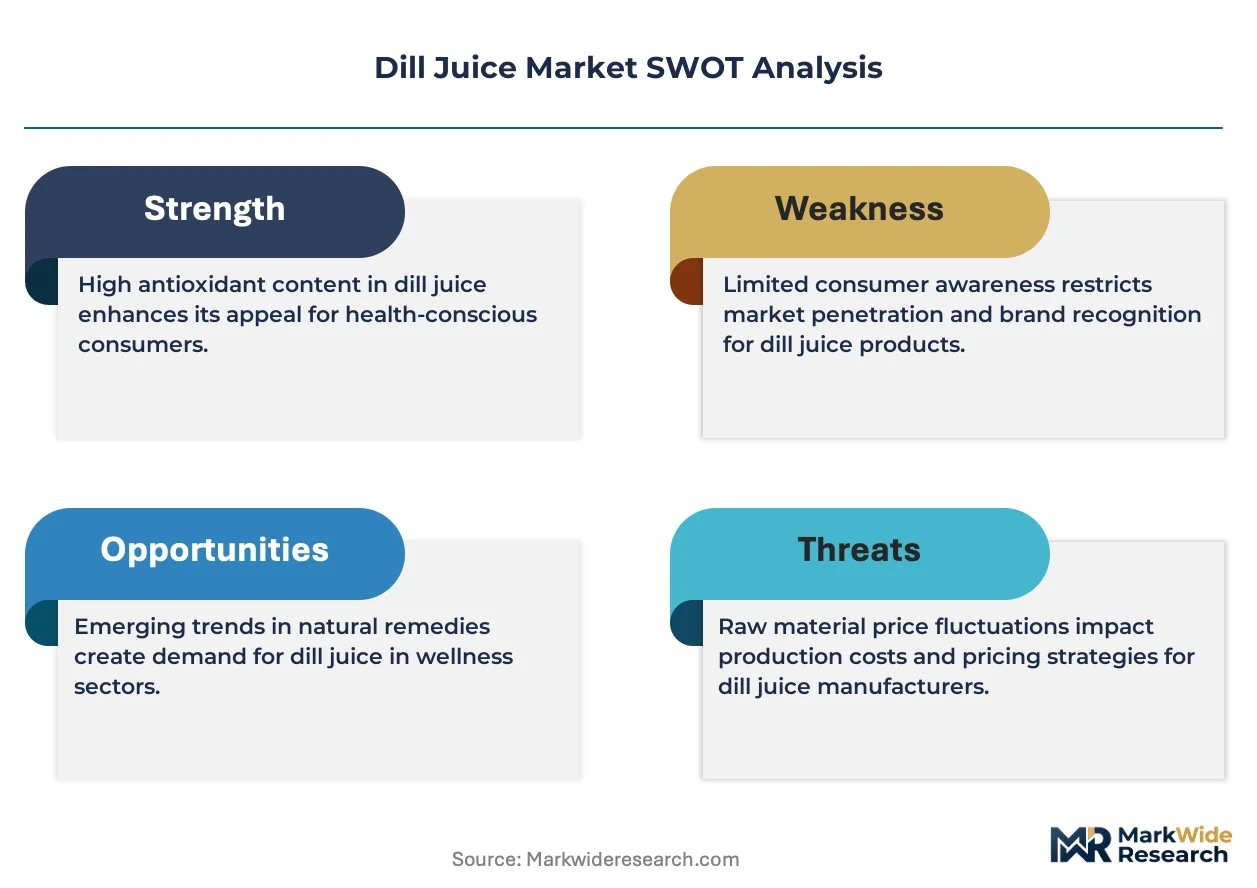
The FDA's evolving acidified food classification rules are forcing beverage manufacturers to restructure fermentation protocols and reformulate dill juice products, creating compliance-driven R&D investment cycles that reshape competitive positioning.
Growth Catalysts
- Pickle-back cocktail culture:Mixology programs in sports bars and craft cocktail venues across the United States are standardizing dill juice as a signature ingredient, expanding food service procurement volumes.
- USDA organic certification:Premium tier pricing power in specialty retail channels depends on organic credentialing, which producers are pursuing to access higher-margin distribution.
- Athlete recovery protocols:Sports teams and training facilities are incorporating dill juice into hydration regimens, driving institutional procurement through direct-to-athlete supply arrangements.
Market Restraints
- Input cost volatility:Cucumber harvest fluctuations and brine salt pricing instability compress margins for fermentation-based producers dependent on agricultural commodity cycles.
- Supply concentration risk:Fermentation capacity clusters in the southeastern United States, creating geographic vulnerability to climate disruptions and logistics bottlenecks.
- Substitution threat:Coconut water and electrolyte tablets compete for sports recovery wallet share, particularly among younger demographics less attached to pickle culture.
Strategic Opportunities
- Gut-health beverage convergence:Kombucha and kefir distribution networks offer ready infrastructure for dill juice probiotic variants targeting digestive wellness consumers.
- Texas cottage food law pathway:Small-batch producers can access retail channels through streamlined state-level compliance, lowering barrier to market entry for artisanal brands.
- Cold-pressed extraction technology:Non-thermal processing preserves volatile compounds for premium positioning, enabling differentiation from heat-pasteurized commodity offerings.
Industry Challenges
- Fermentation science talent scarcity:Qualified food microbiologists command premium salaries, constraining scale-up capacity for mid-tier producers expanding beyond artisanal volumes.
- Dual classification compliance:Products positioned as both sports drinks and acidified foods face overlapping FDA and state-level enforcement, extending time-to-shelf.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dill Juice Market |
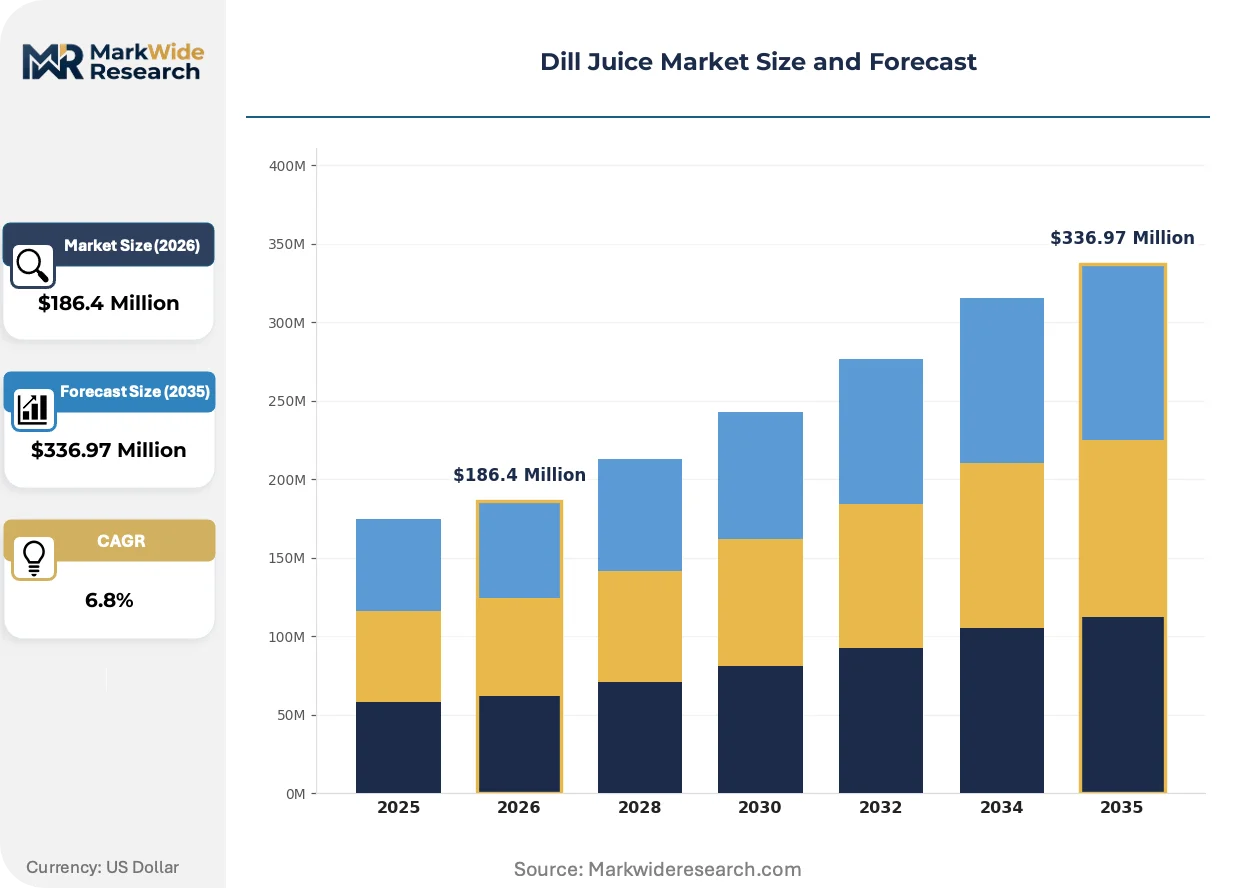
| Market Size in 2026 | $186.4 Million |
| Market Size in 2035 | $336.97 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Dill Juice, Conventional Dill Juice, Cold-Pressed Dill Juice, Dill Juice Concentrate Packaging Type: Glass Bottles, Plastic Bottles, Tetra Packs, Bulk Containers Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Food Service End User: Food Manufacturers, Restaurants, Retail Consumers, Beverage Producers |
| Companies Covered | The Pickle Juice Company, Best Maid Products, McCormick & Company, Mt. Olive Pickle Company, The Real Dill, Van Holten’s Pickles, Suja Life, Evolution Fresh, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dill Juice Market Strategic Shifts
Processing technology and distribution infrastructure are converging to redefine how dill juice reaches end consumers, with fermentation science advances and regulatory clarity emerging as decisive competitive variables.
Cold-pressed extraction equipment is hybridizing traditional brine fermentation with non-thermal stabilization, preserving lactobacillus cultures and volatile aromatics lost in heat pasteurization. Premium beverage co-packers in California and New York are adopting these systems to serve functional drink brands seeking live-culture positioning. The technology is hybridizing supply chain requirements, forcing producers to choose between extended cold-chain distribution or shelf-stable compromise formulations.
The FDA's acidified food guidance revision is compressing formulation timelines as manufacturers await final rulemaking on fermented beverage classification. Uncertainty around whether dill juice falls under sports drink or acidified food standards is driving parallel compliance investments. Small-batch producers in Texas and California are most affected, diverting capital from expansion into regulatory consulting and dual-pathway labeling development.
Athlete procurement patterns are consolidating around direct-to-team supply contracts, bypassing traditional beverage distributors. Sports nutrition departments at collegiate and professional facilities are negotiating volume commitments directly with brine processors, securing consistent electrolyte profiles for hydration protocols. This channel shift is most visible in the southeastern United States, where football program budgets anchor regional demand concentration.
Dill Juice Market Segmentation
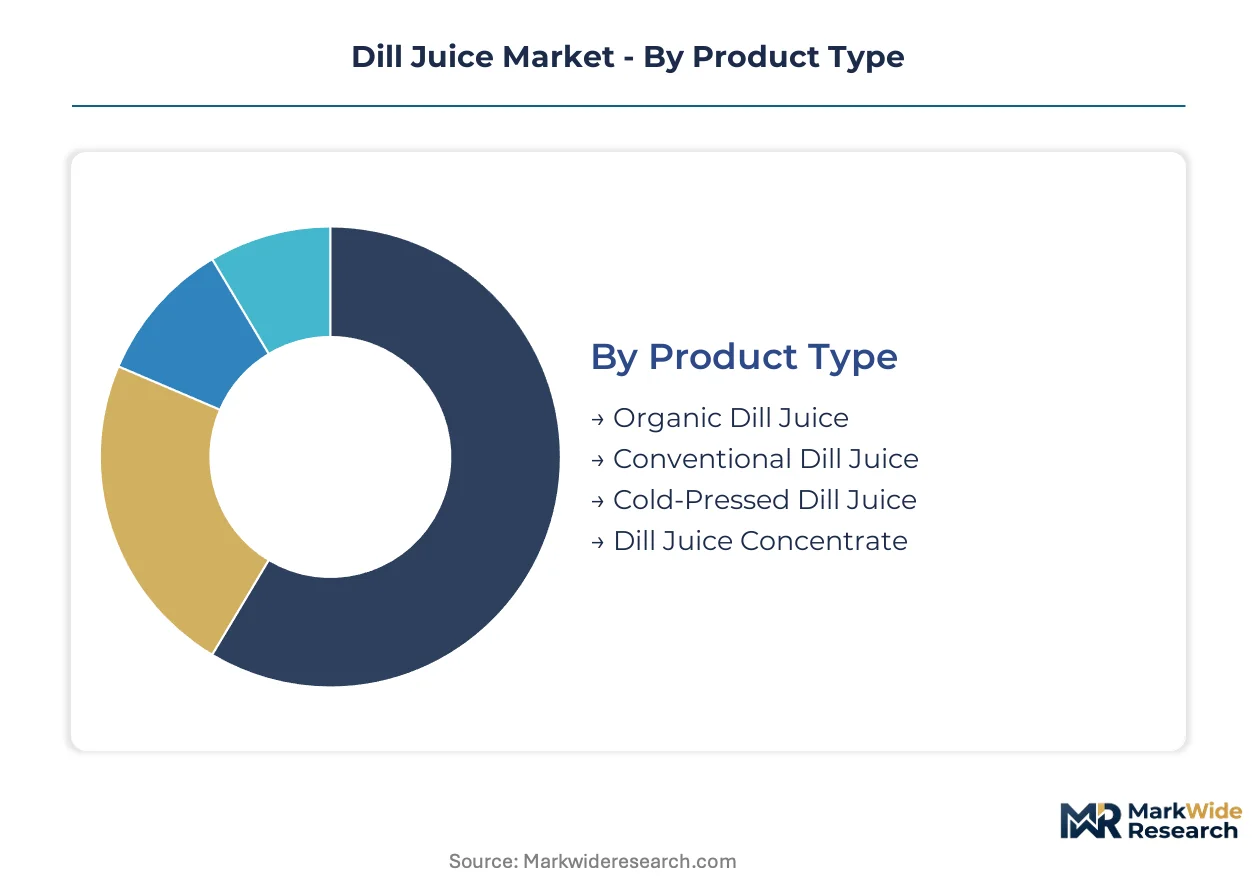
Segmentation in the dill juice market determines access to margin pools and regulatory pathways. Product type dictates USDA certification requirements and shelf positioning, while packaging and channel choices shape cold-chain investments and customer acquisition costs.
Product Type:
After-sales service intensity varies sharply across product types, with live-culture variants demanding cold-chain monitoring and probiotic viability guarantees that conventional heat-treated products avoid.
- Organic Dill Juice:Fermented from certified organic cucumbers with acetic acid, sodium, and trace lactobacillus cultures. Demand concentrates in United States specialty retail where USDA credentialing unlocks premium shelf placement and pricing power.
- Cold-Pressed Dill Juice:Non-thermal extraction preserves volatile aromatics and live cultures for functional positioning. United States beverage co-packers in California and New York are adopting these systems to serve gut-health brands seeking probiotic claims.
- Conventional Dill Juice:Heat-pasteurized commodity product serving mass-market pickle-back cocktail programs and institutional food service accounts with lower unit economics.
- Dill Juice Concentrate:Reduced-moisture format for beverage manufacturing and brining operations, shipped in bulk to food manufacturers seeking consistent electrolyte profiles.
Organic dill juice holds the largest share; momentum sits with cold-pressed variants.
Packaging Type:
Cost tier stratification runs through packaging decisions, with premium glass formats carrying three to five times the per-unit packaging cost of bulk food service containers.
- Glass Bottles:Preferred for premium positioning in United States specialty stores where transparency and perceived purity support higher price points. Cold-pressed producers specify amber or clear glass to signal non-thermal processing.
- Bulk Containers:Drive food service channel economics as restaurants incorporate dill juice into cocktail programs and brining operations, with volume commitments anchoring processor revenue stability.
- Plastic Bottles:Lightweight format for mass retail distribution, balancing shelf visibility with logistics cost reduction in conventional product tiers.
- Tetra Packs:Aseptic cartons for ambient distribution, enabling probiotic juice variants to reach convenience channels without refrigerated infrastructure.
Bulk containers anchor food service procurement volumes; glass bottles command the steepest expansion trajectory in premium retail.
Distribution Channel:
Application concentration shapes channel investment, with sports recovery and mixology use cases fragmenting traditional beverage distribution through direct procurement.
- Food Service:Bars, restaurants, and institutional kitchens standardizing dill juice for pickle-back cocktails and athlete hydration protocols. United States sports nutrition departments negotiate direct supply contracts, bypassing distributors.
- Specialty Stores:Curated retail environments where organic and cold-pressed variants achieve margin premiums through educated consumer self-selection.
- Online Stores:Direct-to-consumer and subscription models for athlete recovery regimens, with refrigerated last-mile logistics constraining serviceable geography.
- Supermarkets:Mass retail placement for conventional and organic SKUs, competing for shelf space against coconut water and electrolyte alternatives.
Food service captures the largest volume commitment; specialty stores are expanding most quickly as gut-health positioning matures.
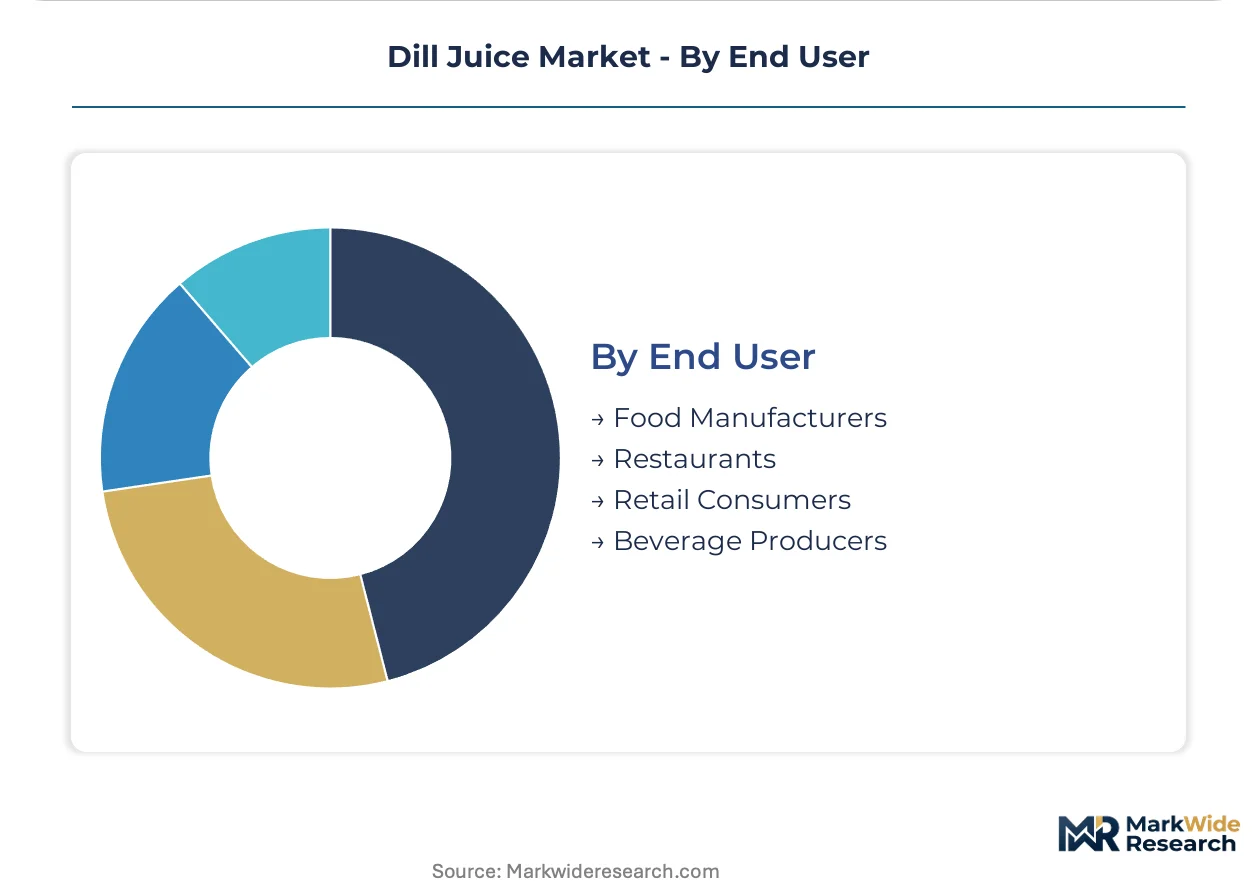
End User:
Customer type determines formulation specificity, with beverage producers demanding consistent electrolyte profiles and restaurants prioritizing batch-to-batch flavor stability for cocktail programs.
- Beverage Producers:Functional drink manufacturers sourcing dill juice as an electrolyte and probiotic ingredient for sports recovery and gut-health SKUs, with FDA acidified food compliance driving supplier qualification.
- Restaurants:Mixology-forward establishments in United States urban markets incorporating dill juice into signature cocktail programs, with bulk procurement reducing per-ounce cost.
- Food Manufacturers:Processors using dill juice concentrate in brining operations and packaged food production, with volume contracts hedging against cucumber harvest volatility.
- Retail Consumers:Individual purchasers through specialty retail and online channels, with athlete recovery trends and pickle culture driving trial and repeat purchase.
Beverage producers hold the largest procurement commitment; restaurants are gaining share fastest as mixology adoption spreads beyond coastal United States markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in United States specialty retail channels, while mass-market volume gravitates toward southeastern fermentation clusters where input costs run lower.
United States
Pickle-back cocktail culture and athlete recovery protocols drive institutional procurement through direct-to-team supply contracts. FDA acidified food classification rules force parallel compliance investments across fermentation-based producers. North Carolina and Georgia fermentation facilities anchor supply concentration for sports nutrition departments.
Canada
Health Canada regulations on probiotic beverage labeling create distinct compliance pathways for live-culture dill juice variants. Cross-border ingredient sourcing from United States brine processors shapes cost structures for Ontario-based beverage manufacturers. Toronto and Vancouver specialty retail channels exhibit strongest demand for organic-certified imports.
Germany
EFSA guidance on fermented food health claims influences formulation decisions for gut-health positioned exports. Traditional cucumber fermentation expertise in Bavaria supports contract manufacturing for private-label dill juice brands. Munich beverage co-packers serve as distribution gateways into broader European markets.
United Kingdom
Mixology adoption in London craft cocktail venues drives food service procurement volumes for premium dill juice SKUs. Post-Brexit import regulations from EU fermentation facilities create supply chain friction for commodity-grade products. Midlands-based food manufacturers utilize dill juice concentrate in packaged savory applications.
Australia
TGA oversight of functional beverage claims constrains sports recovery positioning for imported dill juice products. Domestic cucumber harvest volatility in Victoria and Queensland limits fermentation capacity expansion. Sydney and Melbourne specialty retailers source cold-pressed variants through direct United States import channels.
Dill Juice Market Competitive Environment
Vertically integrated pickle processors and specialty beverage co-packers split the market into distinct capability tiers. Consolidation pressures concentrate around fermentation capacity control and cold-chain distribution infrastructure. Three archetypes dominate: heritage pickle brands extending into adjacent juice SKUs, functional beverage specialists leveraging probiotic positioning, and ingredient suppliers serving co-manufacturing relationships. Competitive moves center on backward integration into cucumber sourcing and technology licensing for non-thermal stabilization systems.
Within the heritage processor tier, The Pickle Juice Company and Mt. Olive Pickle Company exemplify vertical control from agricultural input through retail shelf placement. McCormick & Company occupies a position as the dominant flavor science and ingredient supply anchor, serving beverage co-packers seeking consistent electrolyte profiles. These three entities represent the primary competitive anchors around which mid-tier producers and regional specialists coordinate supply relationships and distribution access.
| Leading Market Players |
|---|
| The Pickle Juice Company |
| Best Maid Products |
| McCormick & Company |
| Mt. Olive Pickle Company |
| The Real Dill |
| Van Holten's Pickles |
| Suja Life |
| Evolution Fresh |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
Cucumber harvest volatility in the southeastern United States compresses margin spreads across all pricing tiers while simultaneously forcing supply chain consolidation around vertically integrated brine processors. This agricultural input risk determines both the premium commanded by cold-pressed variants with supply certainty and the geographic clustering of fermentation capacity.
Pricing Analysis
The customization-premium spread separates configured-to-order cold-pressed SKUs from commodity heat-pasteurized volumes. Pricing stratifies across premium, standard, and economy tiers driven by USDA organic certification and live-culture viability guarantees. Cost compression in conventional segments stems from brine salt pricing instability and seasonal cucumber availability. Institutional food service buyers exhibit highest price sensitivity, while specialty retail consumers absorb premiums for probiotic positioning.
Supply Chain Analysis
Upstream feedstock dependence centers on cucumber cultivation clusters in North Carolina, Georgia, and Michigan, with brine salt sourcing from Ohio Valley deposits. Fermentation capacity draws from captive facilities in the southeastern United States, while cold-pressed extraction equipment concentrates in California and New York beverage co-packer networks. Single-source vulnerability exists in live-culture strain propagation, where qualified food microbiologists anchor regional talent pools. Distribution runs through direct-to-team sports nutrition contracts alongside traditional beverage wholesaler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where probiotic beverage interoperability with kombucha and kefir distribution networks reshapes competitive boundaries. The convergence of gut-health positioning with established functional drink infrastructure creates new ecosystem entry points.
For Market Incumbents: Harden fermentation capacity control through backward integration into cucumber sourcing in North Carolina and Georgia growing regions. Secure exclusive live-culture strain partnerships with university microbiology programs before talent scarcity intensifies. Defend against cold-pressed entrants by locking in multi-year sports team hydration protocol contracts.
For New Entrants and Emerging Players: Build out Texas cottage food law compliance pathways to bypass FDA acidified food bottlenecks for small-batch retail entry. Target the United Kingdom mixology channel where post-Brexit import friction disadvantages commodity European suppliers. Lead with probiotic viability guarantees backed by third-party laboratory certification.
For Investors and Strategic Acquirers: FDA acidified food guidance revision reshapes the acquisition landscape by privileging producers with dual-pathway compliance infrastructure already deployed. Five-to-ten year viability favors vertically integrated pickle processors with captive agricultural supply over pure-play beverage brands. Watch for enforcement priority shifts between sports drink and acidified food classifications as the definitive inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | Enables live-culture dill juice distribution through kombucha retailer networks without spoilage. |
| USDA Organic Certification Investment | Unlocks premium shelf placement in United States specialty retail channels with pricing power. |
| Direct-to-Team Supply Contract | Bypasses beverage distributor margins while anchoring volume commitments from collegiate athletic programs. |
| Non-Thermal Stabilization Technology Licensing | Preserves probiotic claims for gut-health positioning against heat-pasteurized commodity competition. |
| Backward Integration into Cucumber Sourcing | Hedges agricultural input volatility while securing consistent brine quality for fermentation protocols. |
Study Parameters
A spread of perspectives from fermentation science directors, sports nutrition procurement officers, specialty retail category managers, and beverage co-packer operations heads converged on the working assumptions. Primary fieldwork combined with secondary validation from FDA acidified food guidance documents, USDA organic certification databases, and trade flow records from United States customs data. Bottom-up volume modeling triangulated against top-down category spending estimates from food service distribution channels.
Demand-supply-balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, packaging format, distribution channel, and end-user application concentration. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and channel shift velocities. Forecast inputs incorporated cucumber harvest cycle patterns and cold-pressed equipment adoption curves in California and New York co-packer facilities.
Stress conditions across FDA classification rule changes, cucumber yield variance bands, and live-culture strain supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on sports recovery trend durability and mixology adoption rates. Cross-checking against kombucha and kefir category growth benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Global Honey Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Foie Gras Market
Specialty Foods
United States Tofu Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Hot Pot Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Middle East and Africa Free-From Food Market