
 Low Calorie Sweets Market | 2026-2036
Low Calorie Sweets Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Sweets Market Foresight
Multi-sourcing of sweetener inputs is pivoting toward captive stevia and allulose cultivation as ingredient costs fluctuate. Nestlé S.A. leverages its vertical integration into natural sweetener supply chains to secure margin stability. Mondelez International anchors its competitive stance through R&D intensity in reduced-calorie chocolate formulations. Danone S.A. specializes in fiber-based dessert platforms that align with digestive wellness positioning.
Low calorie sweets are confectionery products formulated with reduced caloric density through substitution of sucrose with non-nutritive or reduced-energy sweeteners, typically achieving caloric reductions of 25-50% while maintaining rheological and organoleptic properties comparable to conventional equivalents. The ingredient type dimension shows sugar alcohols occupying mature volume positions in European private label, while natural sweeteners command premium shelf space in North American health food stores. Chocolate segments sustain higher absolute margins despite slower velocity, whereas gummies capture expanding diabetic and pediatric prescription-adjacent demand.
FDA nutrition labeling requirements and the EU's added-sugar disclosure mandates compel manufacturers to reformulate or risk channel exclusion in regulated jurisdictions. Health Canada and FSSAI India are tightening permissible sweetener thresholds, forcing exporters to maintain parallel formulation portfolios. Stakeholders must monitor evolving permissible daily intake recalibrations by WHO and national regulators to anticipate reformulation cycles and preempt supply chain disruption.
Market Dynamics
The Low Calorie Sweets Market pivots on reformulation mandates triggered by sugar-disclosure regulations across major economies, forcing manufacturers to rebuild supply chains around non-nutritive sweeteners while preserving sensory fidelity.
Growth Catalysts
- EU sugar-reduction targets:Mandatory added-sugar caps in processed foods compel confectionery reformulation, expanding contract manufacturing capacity for reduced-calorie variants.
- Diabetic population clusters:Prescription-adjacent positioning of low-glycemic sweets drives pharmacy channel penetration in Germany and the United States.
- Allulose production scale-up:Bioconversion technology advances reduce per-unit sweetener costs, enabling mass-market price parity with conventional sugar confectionery.
Market Restraints
- Stevia leaf supply volatility:Weather-dependent harvests in China and Paraguay create raw material price spikes that compress margins for natural-positioned brands.
- FSSAI India sweetener thresholds:Stringent permissible daily intake limits for polyols force exporters to maintain separate formulation portfolios, raising compliance overhead.
- Aftertaste masking limitations:Reb-A stevia variants and monk fruit extracts retain lingering flavor profiles that limit adoption in premium chocolate applications.
Strategic Opportunities
- Pediatric functional confectionery:Fiber-fortified gummies targeting gut health in school-age children open shelf space in United States mass retail.
- Health Canada front-of-package labeling:Mandatory high-sugar warnings create first-mover advantage for products qualifying as low-calorie alternatives.
- DTC subscription models:Personalized sweetness-level customization bypasses retail slotting fees and builds recurring revenue in urban millennial segments.
Industry Challenges
- Clean-label certification timelines:Non-GMO Project and USDA Organic verification cycles extend 14-18 months, delaying product launches and freezing working capital.
- Sensory scientist scarcity:Specialized expertise in rheology matching for sugar-reduced chocolate and caramel formulations commands premium compensation, constraining R&D throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Sweets Market |
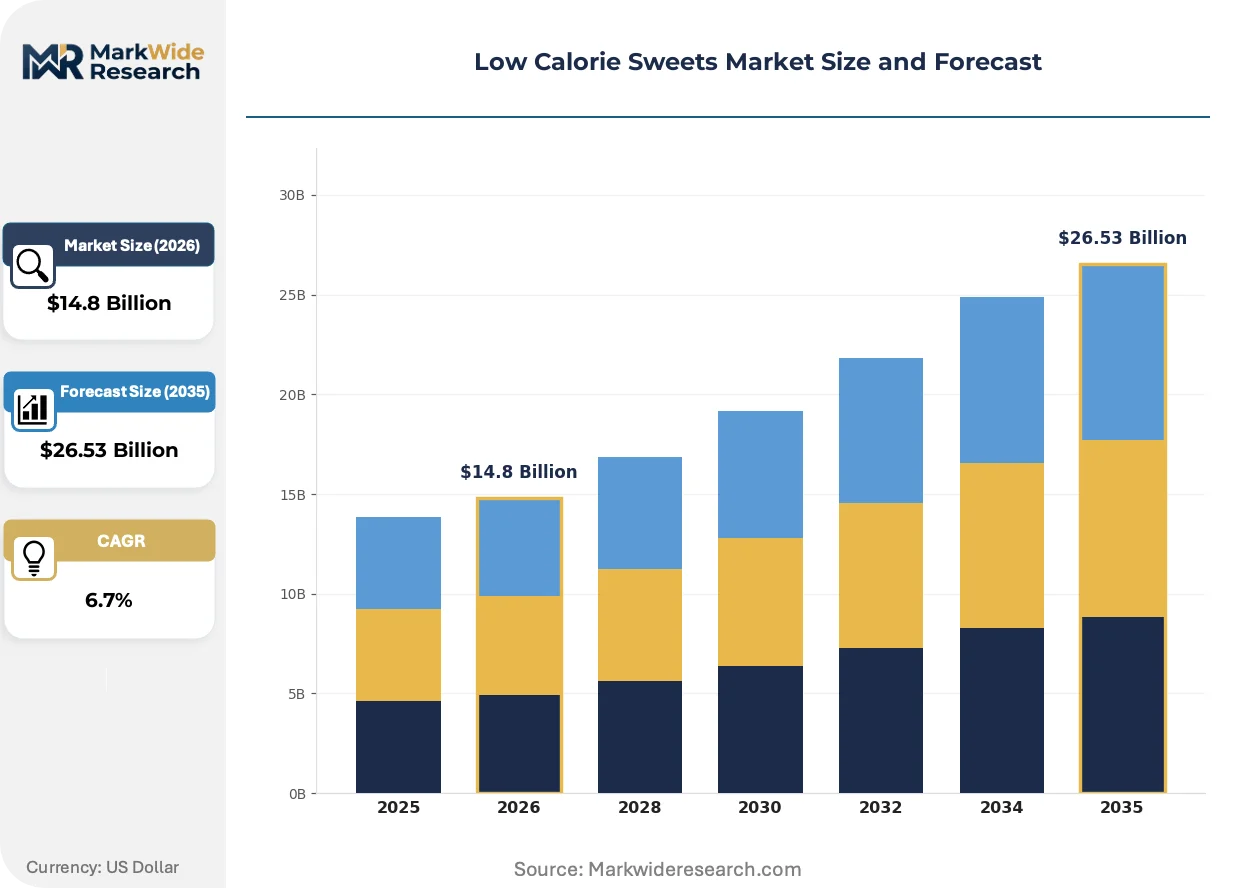
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candies, Chewing Gum Ingredient Type: Natural Sweeteners, Sugar Alcohols, Artificial Sweeteners, Fiber-Based Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Convenience Stores Consumer Type: Health-Conscious, Diabetic Consumers, Weight Watchers, Fitness Enthusiasts |
| Companies Covered | Nestlé S.A., Danone S.A., General Mills, Grupo Bimbo, Del Monte Foods, Bake-N-Serv Inc., Lawler Foods Ltd., Mondelez International, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Sweets Market Shifts & Advancements
Formulation science is compressing the sensory gap between reduced-calorie and conventional sweets, while regulatory disclosure mandates and direct-to-consumer channels rewrite go-to-market economics.
Precision fermentation-derived sweeteners are converging with enzymatic modification techniques to produce rare sugar profiles that replicate sucrose's temporal sweetness curve. Biotech ingredient suppliers in Denmark and California are scaling tank-based production of brazzein and thaumatin proteins. This convergence is collapsing the premium pricing tier that previously separated natural high-intensity sweeteners from synthetic alternatives.
REACH authorization requirements for novel food contact substances are tightening migration limits for packaging used in confectionery with acidic or fat-based matrices. EFSA evaluations of titanium dioxide alternatives are accelerating industry shifts to calcium carbonate and starch-based whitening agents. European private-label manufacturers are responding by consolidating supplier audits and pre-qualifying packaging converters in Poland and Spain.
Subscription-based replenishment models are displacing impulse-driven checkout lane purchases for habitual low-calorie sweet consumption. United States direct-to-consumer brands leverage flavor profiling algorithms to match stevia-masking technologies to individual palate sensitivity. This behavioral pivot concentrates lifetime value capture in coastal metropolitan markets while eroding traditional convenience store velocity.
Low Calorie Sweets Market Segmentation
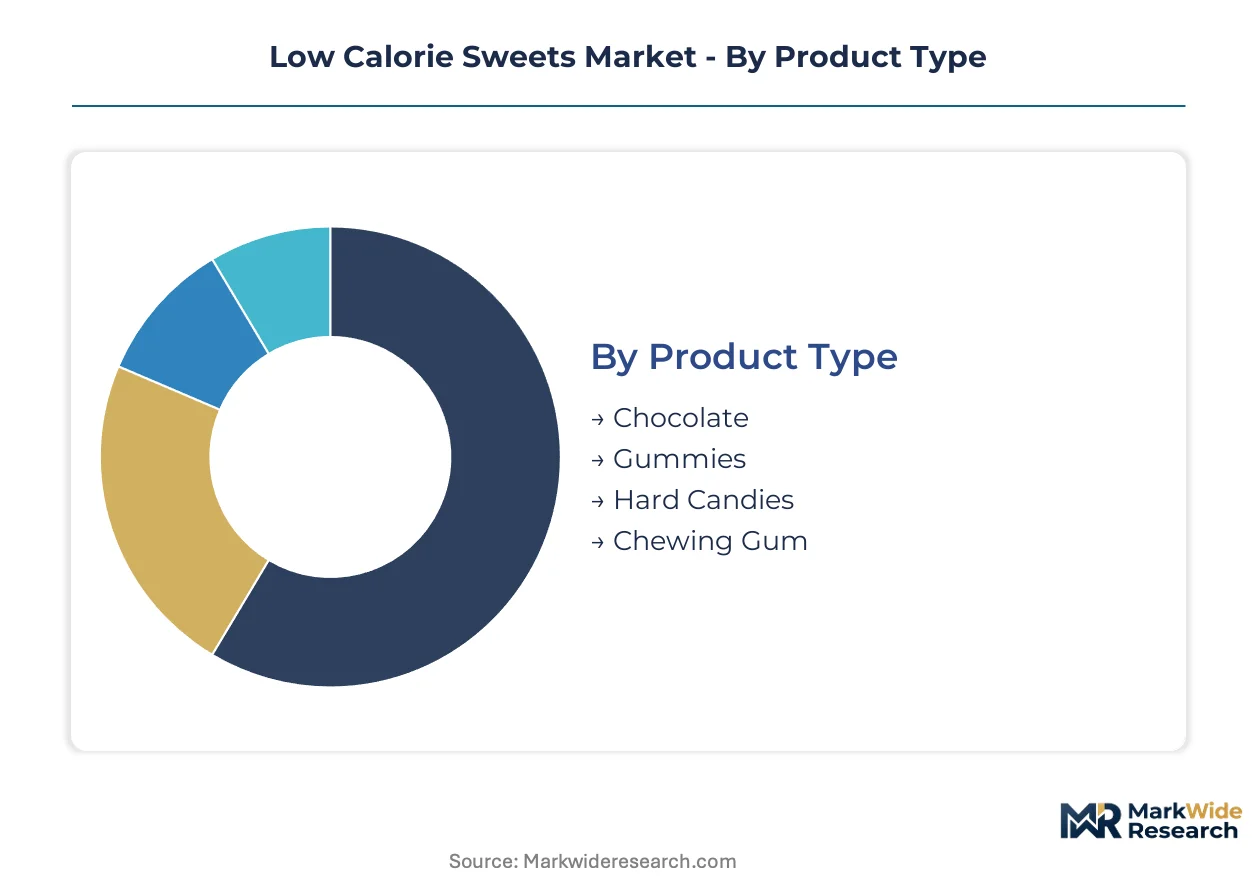
Segmentation in low calorie sweets determines formulation investment priorities and channel allocation. Sweetener chemistry and distribution economics vary sharply across product categories, forcing parallel supply chain configurations.
Product Type:
Production assets for reduced-calorie confectionery cluster around chocolate and gummy manufacturing, with hard candy and chewing gum lines requiring distinct thermal processing equipment.
- Chocolate:Cocoa butter equivalents and fiber-based bulking agents replicate mouthfeel in sugar-reduced formulations. German and Swiss processors dominate capacity for diabetic-positioned chocolate tablets, though slower velocity per SKU demands careful inventory management.
- Gummies:Pectin and starch-based gel matrices accommodate high-intensity sweeteners without crystallization defects. Pharmacy channel penetration in the United States and Germany drives prescription-adjacent positioning for diabetic populations.
- Hard Candies:Isomalt and erythritol blends enable glassy state formation at reduced caloric density. Production concentrates in European private-label facilities serving sugar-free breath freshener demand.
- Chewing Gum:Polyol-based gum bases with encapsulated sweetener release systems dominate functional oral care extensions. Wrigley and Lotte manufacturing footprints in the United States and South Korea anchor global supply.
Chocolate absorbs the bulk of installed capacity; gummies are expanding most quickly.
Ingredient Type:
Cost tier differentiation separates commodity polyols from premium-positioned natural extracts, with regulatory approval status determining geographic deployability.
- Natural Sweeteners:Stevia Reb-A and monk fruit extracts command 3-5x polyol pricing. FDA GRAS status enables United States deployment, though lingering aftertaste limits chocolate application penetration.
- Sugar Alcohols:Mature erythritol and xylitol supply chains serve European private label at commodity economics. Laxative effect thresholds constrain per-serving formulation ceilings under FSSAI India and Health Canada guidelines.
- Artificial Sweeteners:Sucralose and aspartame maintain cost leadership in mass-market chewing gum. Clean-label migration in North American natural food stores erodes shelf space allocation.
- Fiber-Based:Soluble corn fiber and inulin provide bulking with prebiotic positioning. Danone and Kellogg supplier networks prioritize digestive wellness claims in United States pediatric segments.
Sugar alcohols represent the largest volume tier; natural sweeteners show the steepest expansion trajectory.
Distribution Channel:
Channel selection dictates packaging format, margin structure, and promotional intensity, with online retail rewriting traditional velocity economics.
- Supermarkets:Slotting fees and planogram compliance favor established brands with reformulated legacy SKUs. Kroger and Albertsons in the United States dedicate end-cap space to low-calorie seasonal assortments.
- Online Retail:Direct-to-consumer subscriptions bypass retail gatekeepers and enable personalized sweetness-level customization. Coastal United States metropolitan markets concentrate lifetime value capture.
- Health Food Stores:Non-GMO Project and USDA Organic certification requirements filter assortment to premium-positioned entrants. Whole Foods Market's quality standards drive supplier audit consolidation.
- Convenience Stores:Impulse-driven checkout placement favors single-serve chewing gum and hard candy formats. Erosion from subscription models pressures velocity in urban locations.
Supermarkets retain the largest revenue share; online retail is gaining share fastest.
Consumer Type:
Customer motivation determines messaging architecture, with diabetic compliance and weight management requiring distinct clinical versus lifestyle positioning.
- Health-Conscious:Millennial urban professionals prioritize clean-label credentials over absolute caloric reduction. Erewhon and Fresh Thyme customer bases in Chicago and Los Angeles drive natural sweetener adoption.
- Diabetic Consumers:Glycemic index certification and pharmacy channel presence validate clinical utility. German Apotheke and United States CVS Health partnerships require prescription-adjacent marketing compliance.
- Weight Watchers:Points-system compatibility and portion-controlled packaging align with program-specific retail collaborations. Nestlé's portioned chocolate formats target this behavioral segment.
- Fitness Enthusiasts:Protein-fortified and electrolyte-enhanced confectionery bridges sports nutrition and indulgence. CrossFit affiliate retail and REI co-op placement concentrate demand in Denver and Austin.
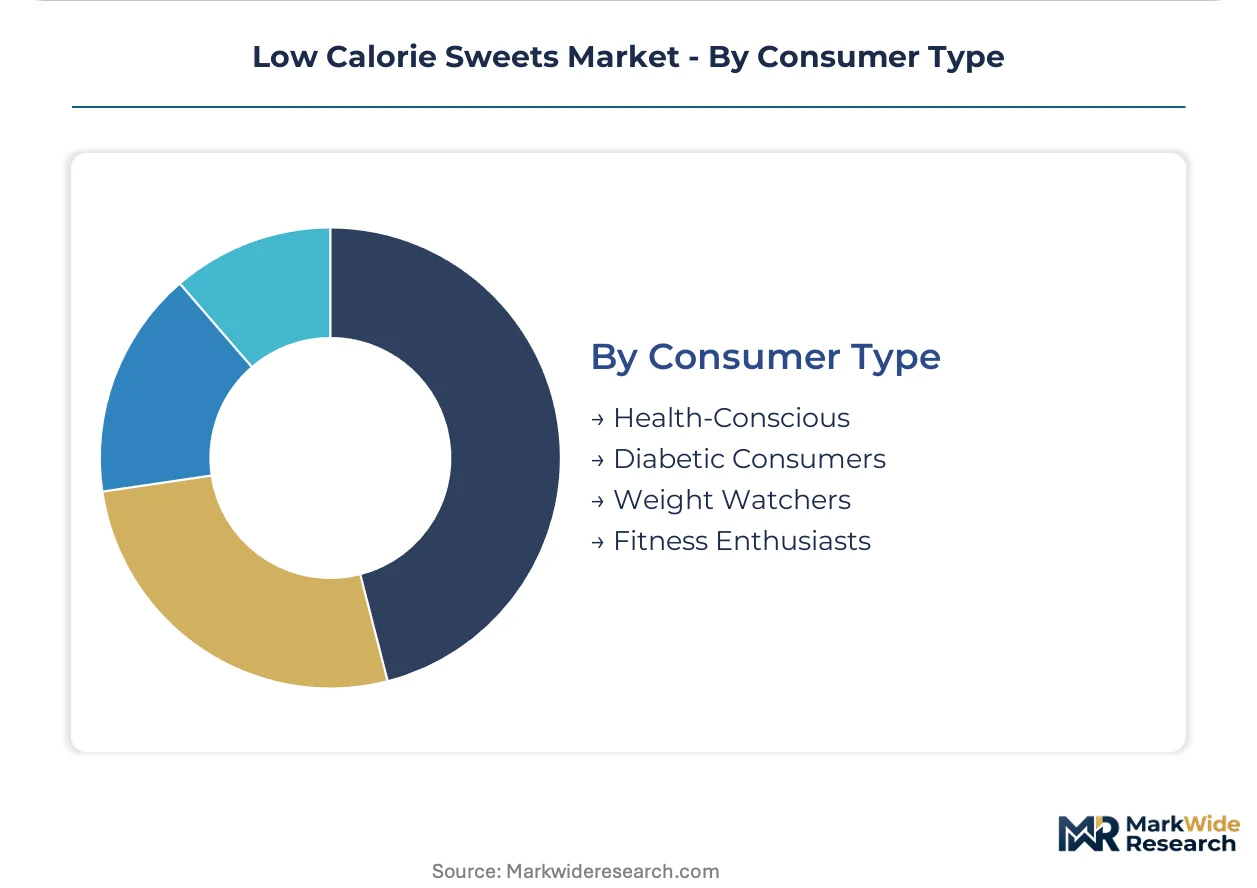
Health-conscious consumers absorb the bulk of marketing investment; diabetic-positioned products are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia leaf cultivation in China's Guangxi Zhuang Autonomous Region anchors raw material flows for natural sweetener supply chains serving formulation facilities worldwide.
United States
Millennial professionals in Chicago and Los Angeles drive clean-label confectionery adoption through premium health food retail channels. FDA nutrition labeling requirements compel reformulation of legacy SKUs to disclose added sugars prominently. Manufacturing clusters in the Chicago metropolitan area concentrate contract capacity for reduced-calorie chocolate and gummy production.
Germany
Pharmacy-channel diabetic positioning sustains demand for low-glycemic chocolate tablets and pectin-based gummies. EU sugar-reduction targets mandate reformulation timelines that expand contract manufacturing capacity for private-label entrants. The functional food retail corridor spanning Cologne, Düsseldorf, and Hamburg concentrates distribution infrastructure for health-positioned sweets.
China
Urban middle-class consumers in Shanghai and Beijing adopt imported low-calorie confectionery as lifestyle wellness indicators. SAMR tightening of food additive standards accelerates domestic stevia extraction capacity expansion. Guangxi and Yunnan provinces host concentrated stevia leaf processing facilities supplying global ingredient networks.
India
Metropolitan health-conscious segments in Mumbai and Bengaluru experiment with sugar-free traditional sweets reformulated for festive gifting. FSSAI permissible daily intake thresholds for polyols force exporters to maintain parallel formulation portfolios distinct from Western markets. Maharashtra and Gujarat house emerging contract manufacturing capacity serving Middle East export demand.
Canada
Front-of-package high-sugar warning mandates create first-mover positioning opportunities for qualifying low-calorie alternatives in Toronto and Vancouver retail. Health Canada sweetener guidelines align closely with FDA frameworks while maintaining distinct labeling disclosure requirements. Ontario-based formulation labs specialize in sensory matching for sugar-reduced chocolate destined for cross-border distribution.
Low Calorie Sweets Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent food conglomerates rebuild around natural sweetener supply chains and reduced-calorie formulation platforms. Market structure tilts toward consolidated multinational control, with three to five diversified nutrition majors commanding supermarket shelf space and pharmacy channel access. Strategic archetypes separate vertically integrated sweetener cultivators, R&D-intensive chocolate specialists, and fiber-based wellness platform builders. Competitive intensity concentrates on captive stevia and allulose supply arrangements alongside precision fermentation partnerships for rare protein sweeteners.
Within the diversified nutrition major tier, Nestlé S.A. and Danone S.A. occupy positions exemplifying vertical integration into natural ingredient sourcing and digestive wellness positioning respectively. Mondelez International anchors the R&D-intensive chocolate reformulation vector. These Switzerland-based, France-based, and United States-based entities collectively represent the scale-driven consolidation pattern reshaping procurement relationships with biotech ingredient suppliers and retail channel gatekeepers.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Danone S.A. |
| General Mills |
| Grupo Bimbo |
| Del Monte Foods |
| Bake-N-Serv Inc. |
| Lawler Foods Ltd. |
| Mondelez International |
| Arla Foods |
| Others |
Supply & Pricing Matrix
Millennial procurement preferences for clean-label certification in North American health food retail force suppliers to absorb 14-18 month USDA Organic verification cycles, compressing working capital and elevating premium tier pricing power for certified entrants. This demand-side pressure cascades through stevia and allulose cultivation networks, where captive supply arrangements now determine margin stability.
Pricing Analysis
Warranty-like certification bundling separates premium natural sweetener formulations from unbundled polyol commodities. Three-tier pricing structure across premium, standard, and economy levels stratifies by USDA Organic status and stevia Reb-A purity grade. Price differentiation stems from certification tier and vertical integration depth. Cost compression in the natural sweetener tier is intensifying because Guangxi stevia leaf harvest volatility feeds raw material spikes. Economy-tier private-label polyols in European retail show highest buyer price sensitivity; premium-positioned DTC subscriptions in coastal United States metros demonstrate lowest.
Supply Chain Analysis
Stevia leaf supply rests on concentrated cultivation in China's Guangxi and Yunnan provinces, with Paraguay anchoring secondary harvest volumes. Allulose bioconversion feeds from corn starch processors in the United States and enzymatic modification facilities in Denmark. Rare protein sweetener inputs draw from precision fermentation tanks in California and Danish biotech clusters. Single-source vulnerability in Guangxi weather-dependent harvests exposes formulation networks to raw material price spikes. Distribution runs through supermarket slotting-fee gatekeepers in Germany and the United States, with DTC subscription models eroding convenience store velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized sensory scientist scarcity constrains R&D throughput for sugar-reduced chocolate formulations, propping pricing for qualified formulation partners and creating acquisition premiums for talent-rich labs.
For Market Incumbents: Deepen captive stevia and allulose cultivation partnerships in Guangxi and Yunnan to offset harvest volatility threatening margin stability. Expand contract manufacturing capacity in Germany's functional food retail corridor ahead of EU sugar-reduction target deadlines. Nestlé-style backward integration into natural sweetener supply chains represents the defensive template; Mondelez-level R&D intensity in reduced-calorie chocolate protects against clean-label entrants. For New Entrants and Emerging Players: The 3-5x price spread between natural sweetener premiums and sugar alcohol commodities opens white-space targeting for mid-tier pectin-based gummies with partial organic certification. Pediatric functional confectionery in United States mass retail offers the most penetrable segment, with fiber-fortified gut health positioning bypassing entrenched chocolate incumbents. Pharmacy-channel diabetic compliance partnerships in Germany provide regulatory-validated go-to-market credibility. For Investors and Strategic Acquirers: The window for entry favors precision fermentation-derived sweetener specialists with scaled thaumatin or brazzein production. Long-term viability hinges on rare protein sweeteners collapsing the premium tier that separated natural from synthetic alternatives. Acquisition targets should demonstrate REACH-compliant packaging migration capabilities and EFSA-ready novel food dossiers. Watch Health Canada front-of-package labeling implementation velocity as inflection indicator for low-calorie alternative shelf space allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Stevia Cultivation Partnerships | Guangxi and Yunnan sourcing agreements insulate margin stability from weather-driven harvest volatility. |
| Precision Fermentation Scale-Up | Danish and Californian biotech partnerships collapse premium pricing tiers separating natural from synthetic sweeteners. |
| Pharmacy Channel Certification | German Apotheke and United States CVS Health partnerships validate clinical utility for diabetic-positioned gummies. |
| DTC Subscription Infrastructure | Coastal metropolitan flavor profiling algorithms bypass retail slotting fees and capture recurring revenue. |
| Clean-Label Certification Investment | Non-GMO Project and USDA Organic verification opens Whole Foods Market placement and freezes competitor launches. |
Research Methodology
Trade databases, EFSA novel food evaluations, and FDA GRAS notifications formed the secondary backbone for supply chain mapping and regulatory trajectory assessment. Primary interviews with formulation scientists at chocolate and gummy manufacturers, procurement leads at natural sweetener extractors, category buyers at Kroger and Albertsons, and regulatory affairs specialists at Health Canada and FSSAI India validated demand-side assumptions. Bottom-up SKU-level velocity data triangulated against top-down category expenditure estimates from customs records and Nielsen retail audit feeds.
Historical trendline analysis of reformulation cycles and sweetener adoption curves informed the projection framework. Segmentation dimensions spanned product type, ingredient chemistry tier, distribution channel economics, and consumer motivation archetype across the modeling period. CAGRs derived from elasticity-adjusted demand curves and capacity expansion pipelines in Guangxi stevia processing and United States allulose bioconversion. WHO permissible daily intake recalibrations and national regulator threshold adjustments fed scenario-weighted forecast bands.
Inputs from EFSA, FDA, and SAMR filings were available through the study window; gaps in real-time stevia leaf harvest yield data introduce uncertainty bands around natural sweetener pricing projections. Forecasts reflect documented assumptions on regulatory timeline adherence and bioconversion technology cost curves. Stevia supply volatility, FSSAI polyol threshold tightening, and REACH packaging migration compliance represent primary revision triggers. A small set of named triggers—Health Canada labeling enforcement velocity, precision fermentation scale-up milestones, and pharmacy channel partnership formation rates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Asia-Pacific Confectionery Market
Confectionery
China Cakes, Pastries, & Sweet Pies Market
Confectionery
Europe Sugar Confectionery Market
Confectionery
UK Confectionery Market
Confectionery
Premium Chocolate Market
Confectionery
Mooncake Market
Confectionery
Gummy Candy Market
Confectionery
Confectionery Fats Market
Confectionery
Japan Chocolate Market
Confectionery
Africa Compound Chocolate Market
Confectionery
South America Chocolate Market
Confectionery
White Chocolate Market
Confectionery
Buttercream Frosting Market
Confectionery
Truffle Chocolate Market
Confectionery
Gummy Market
Confectionery
Sugar Free Lollipops Market