
 Japan Chocolate Market | 2026-2036
Japan Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Chocolate Market Outlook
Buyer concentration among premium department store channels is pivoting toward specialty chocolate boutiques and direct-to-consumer platforms. Meiji Holdings Co., Ltd. leverages its integrated dairy supply chain to control raw material quality from Hokkaido farms. Royce' Confect Co., Ltd. anchors its reputation on nama chocolate freshness protocols that limit distribution radius. Lotte Co., Ltd. competes through Korean-origin product lines adapted to Japanese palate preferences.
Chocolate comprises cocoa solids, cocoa butter, sugar, and emulsifiers processed through conching, tempering, and molding to achieve defined particle size below 30 microns for mouthfeel standards. Its primary commercial purpose spans confectionery, baking ingredient supply, and premium gifting across retail and food service channels. Milk chocolate occupies the largest volume share due to established consumer familiarity, while dark chocolate segments attract margin-rich health-positioned buyers. Specialty shops channel distribution commands premium pricing power through experiential retail formats that online retail cannot replicate.
Japan's Consumer Affairs Agency enforces Food Labeling Standards Act requirements for allergen and origin disclosures, while METI oversees quality benchmarks under Japan Agricultural Standards for processed foods. These frameworks elevate compliance costs for imported products while privileging domestic manufacturers with established laboratory testing infrastructure. Stakeholders must monitor evolving clean-label enforcement intensity and its selective pressure on formulation strategies.
Market Dynamics
Japan's chocolate market is undergoing structural transformation driven by METI's enforcement of the Food Labeling Standards Act, which compels manufacturers to reformulate products and rebuild supply chains around cleaner ingredient declarations and traceable Hokkaido-sourced dairy inputs.
Growth Catalysts
- Clean-label regulation:METI's Food Labeling Standards Act mandates allergen and origin disclosures that favor domestic manufacturers with established laboratory testing infrastructure over importers facing compliance barriers.
- Premium gifting channel:Department store buyers in Tokyo's luxury confectionery corridor are expanding procurement of high-margin nama chocolate and seasonal gift sets, creating concentrated demand pull.
- Direct-to-consumer platforms:Specialty chocolate boutiques are bypassing traditional retail intermediaries, enabling freshness protocols that limit distribution radius while capturing full margin.
Market Restraints
- Cocoa butter cost volatility:Input prices for cocoa butter fluctuate with West African supply disruptions, compressing margins for manufacturers locked into fixed-price department store contracts.
- Freshness protocol constraints:Nama chocolate's limited shelf life and temperature-controlled logistics requirements restrict geographic expansion beyond Tokyo-Osaka corridor.
- Import substitution pressure:Korean-origin product lines adapted to Japanese palate preferences capture price-sensitive segments, constraining domestic premium positioning.
Strategic Opportunities
- Kyushu underpenetration:Fukuoka and regional urban centers outside Kanto lack specialty chocolate boutique density, presenting whitespace for experiential retail formats.
- Health-positioned dark chocolate:Functional ingredient convergence with probiotic and low-glycemic formulations targets aging demographic segments seeking permissive indulgence.
- Confectionery-tourism integration:Factory-direct visitor experiences and Hokkaido dairy farm supply chain tours create channel innovation beyond traditional retail.
Industry Challenges
- Confectionery technologist scarcity:Specialized expertise in particle size reduction below 30 microns and tempering precision is concentrated among aging workforce cohorts in Kobe and Sapporo production clusters.
- Dual certification timelines:Simultaneous Japan Agricultural Standards and Food Labeling Standards Act compliance requires extended laboratory validation cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Chocolate Market |
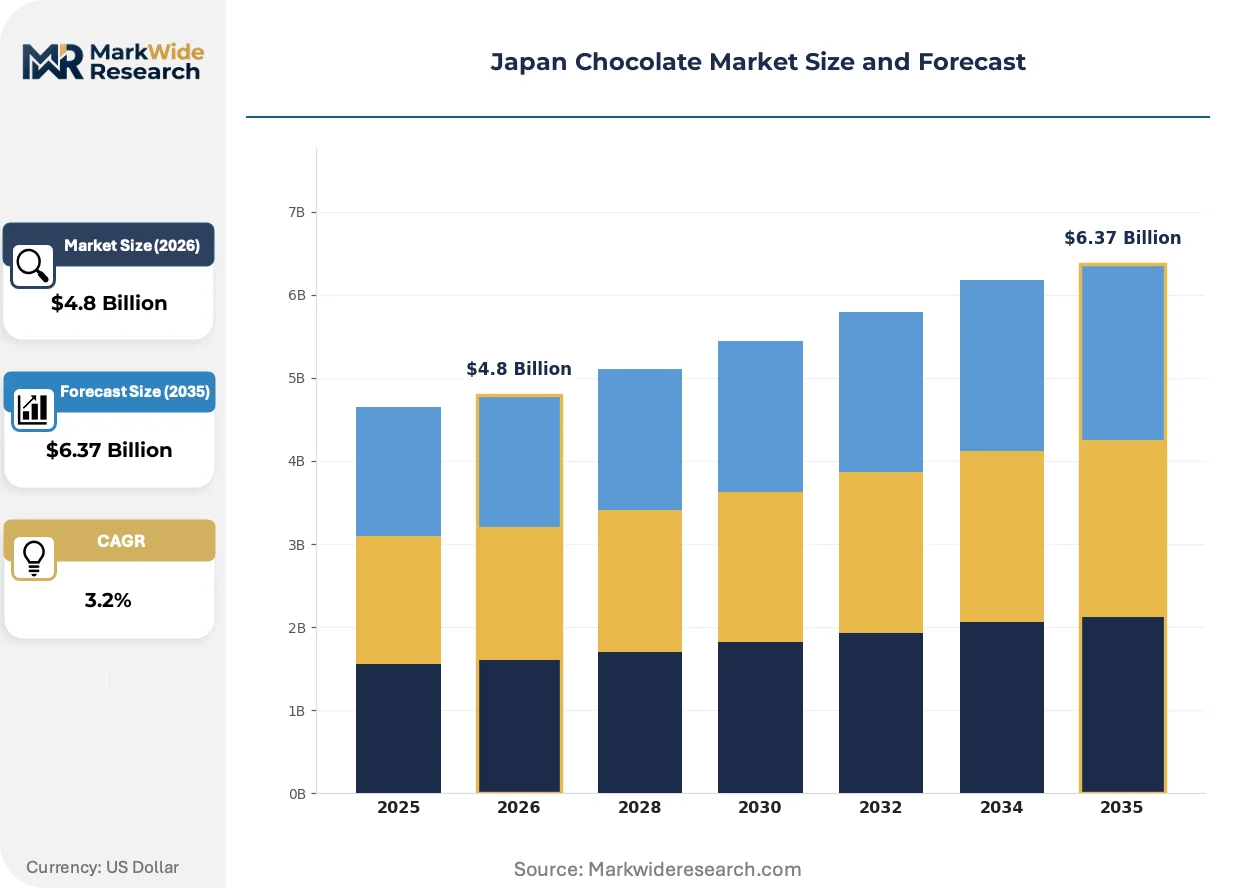
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Bakery Businesses, Food Service, Confectionery Manufacturers Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops Packaging Type: Bags, Boxes, Bars, Individual Wrappers |
| Companies Covered | Meiji Holdings Co., Ltd., Lotte Co., Ltd., Morinaga & Co., Ltd., Nestlé Japan, Ezaki Glico, Royce' Confect Co., Ltd., Mondelez Japan, Mars Inc., Yuraku Confectionery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Chocolate Market Strategic Shifts
Confectionery manufacturers are rebuilding production systems around precision fermentation and localized supply chain control, shifting competitive advantage from scale economies to ingredient provenance transparency and freshness guarantees.
Precision fermentation for cocoa butter alternatives is converging with traditional conching equipment in pilot facilities near Hokkaido dairy operations. Mid-tier manufacturers are adopting these hybrid systems to reduce West African supply dependence while maintaining mouthfeel standards. This technology convergence is compressing the cost gap between bean-to-bar craft producers and industrial-scale competitors.
METI's evolving interpretation of Food Labeling Standards Act requirements is tightening enforcement on "clean" and "natural" marketing claims without standardized definitions. Domestic manufacturers with captive Hokkaido dairy supply chains are accelerating reformulation to preempt regulatory action. Premium gifting segments face the highest compliance exposure as department store buyers demand documented ingredient provenance.
Experiential retail formats in Tokyo's luxury confectionery corridor are displacing traditional department store counter distribution for high-margin seasonal purchases. Specialty boutiques now capture gifting occasions previously served by mass retail, compressing volume through intermediated channels. This channel rotation is most visible among corporate procurement buyers seeking differentiated omiyage options for regional offices.
Japan Chocolate Market Segmentation
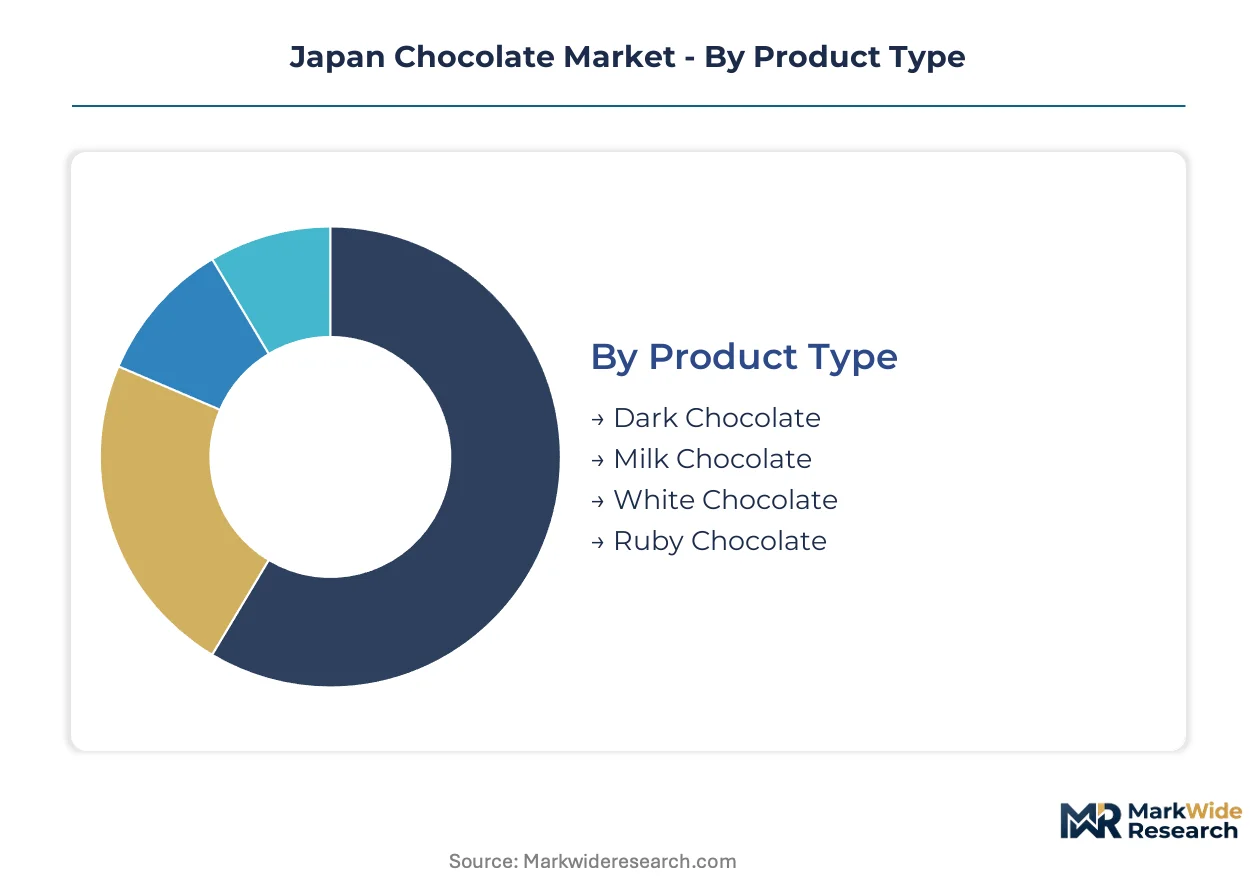
Segmentation in Japan's chocolate market reveals how regulatory pressure from METI and channel evolution in Tokyo's luxury corridor are reshaping where value concentrates. Understanding these divides exposes which buyer configurations command pricing power and which face margin compression from compliance costs.
Product Type:
Buyers differentiate primarily by cocoa content thresholds and permitted ingredient declarations under Food Labeling Standards Act enforcement.
- Milk Chocolate:Formulated with cocoa solids between 10-50% combined with Hokkaido-sourced dairy powders, this segment dominates volume through established palate familiarity across age cohorts. Procurement concentrates in mass retail channels serving suburban Osaka and Nagoya households, though METI's origin disclosure requirements are elevating compliance costs for formulations using imported dairy.
- Dark Chocolate:Cocoa content exceeding 50% enables health-positioned marketing to aging demographics seeking permissive indulgence. Demand clusters in Tokyo's specialty boutiques and department store gifting counters, where premium pricing absorbs higher bean-to-bar production costs and documented provenance requirements.
- White Chocolate:Cocoa butter base without cocoa solids appeals to younger consumers and flavor-infused seasonal variations. Production relies heavily on Hokkaido dairy integration for clean-label compliance.
- Ruby Chocolate:Pink-hued ruby cocoa bean variety offers differentiation in limited artisanal production runs. Scale constraints and patent licensing restrict widespread manufacturing adoption.
Volume sits with milk chocolate formulations; growth tilts toward dark chocolate positioning.
End User:
Application context determines specification rigor, from particle size tolerances in industrial supply to freshness protocols in direct consumption.
- Retail Consumers:Individual purchasers drive seasonal gifting spikes and daily indulgence occasions. Tokyo's luxury confectionery corridor captures premium spend through experiential boutique formats that online retail cannot replicate.
- Confectionery Manufacturers:Industrial buyers demand precise particle size below 30 microns and consistent tempering for downstream processing. Supply relationships concentrate with established Hokkaido-integrated producers capable of laboratory-validated consistency.
- Bakery Businesses:Ingredient procurement prioritizes stable melting profiles and bulk pricing for pastry applications. Regional bakeries outside Kanto face distribution constraints from freshness-sensitive supply chains.
- Food Service:Hotels and restaurants source couverture and decorative elements for plated desserts. Temperature-controlled logistics requirements limit viable supplier radius.
Procurement scale concentrates with confectionery manufacturers; margin expansion favors retail consumer channels.
Distribution Channel:
Physical proximity to production and temperature control capabilities segment channel viability for freshness-limited formats.
- Specialty Shops:Experiential retail formats in Ginza and Omotesando enable full-margin capture and freshness protocols that limit distribution radius. Corporate procurement buyers increasingly source omiyage through these channels for regional office differentiation.
- Supermarkets:Mass retail volume depends on extended shelf-life formulations and promotional pricing. Clean-label reformulation pressures are compressing margins for national brand suppliers.
- Convenience Stores:Grab-and-go single-serve formats target commuter corridors and impulse purchase occasions. Limited refrigeration space constrains premium product placement.
- Online Retail:Direct-to-consumer growth faces temperature-controlled logistics cost barriers for nama chocolate variants. Platforms serve regional buyers outside Tokyo-Osaka corridor with shelf-stable alternatives.
Transaction density clusters in supermarkets; value capture tilts toward specialty shop formats.
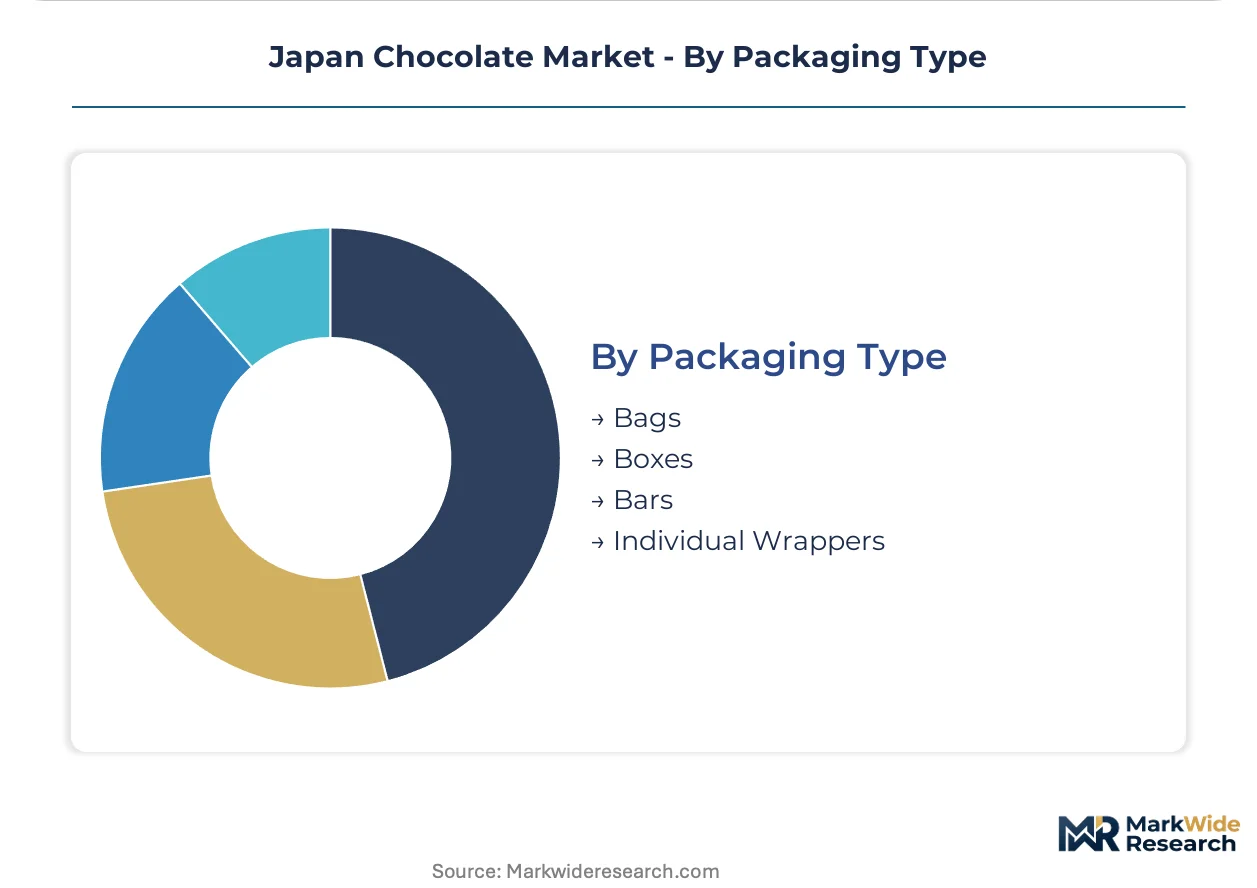
Packaging Type:
Gifting occasion formality and portion control requirements drive packaging selection with regulatory labeling surface implications.
- Boxes:Premium gifting presentations dominate department store seasonal procurement. Surface area accommodates Food Labeling Standards Act disclosure requirements while supporting brand storytelling.
- Bars:Standard retail format balances portion familiarity with production efficiency. Clean-label reformulation visibility is highest in this high-velocity category.
- Bags:Shareable formats target family consumption and value-positioned purchasing. Reclosure features extend shelf life for multi-serve households.
- Individual Wrappers:Single-serve portions enable precise consumption control and food service portioning. Wrapper surface constraints challenge allergen disclosure compliance.
Volume flows through bar formats; premium positioning concentrates in box presentations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hokkaido's dairy pasturelands supply the milk powders that anchor Japan's chocolate production geography, with manufacturing clustering around processing infrastructure in Sapporo and Tomakomai. The island's clean-label compliance advantages stem from integrated farm-to-factory traceability that METI's Food Labeling Standards Act privileges over imported alternatives. Regional output concentrates in white chocolate and milk chocolate formulations where Hokkaido dairy provenance commands premium positioning.
Kanto/Tokyo
Department store buyers in Ginza and Shinjuku drive premium gifting demand for nama chocolate with freshness protocols limiting distribution radius. METI's enforcement of allergen disclosure requirements elevates compliance costs for imported products while privileging domestic boutique operators. Tokyo's luxury confectionery corridor hosts experiential retail formats that capture corporate omiyage procurement previously served by mass retail channels.
Kansai/Osaka
Osaka's mass retail channels serve suburban households with extended shelf-life milk chocolate formulations at promotional price points. The Consumer Affairs Agency monitors labeling compliance across supermarket and convenience store networks with particular scrutiny on origin claims. Production facilities in Sakai and Amagasaki supply volume formulations to western Japan's bakery and food service sectors.
Chubu/Nagoya
Nagoya's industrial confectionery buyers demand precise particle size below 30 microns for downstream processing applications. Japan Agricultural Standards certification requirements concentrate supply relationships with established Hokkaido-integrated producers capable of laboratory-validated consistency. The region's automotive industry concentration supports corporate gifting demand for premium boxed presentations during year-end procurement cycles.
Kyushu
Fukuoka and regional urban centers outside Kanto exhibit underpenetration in specialty chocolate boutique density. METI's clean-label enforcement creates entry barriers for imported products lacking documented Hokkaido dairy provenance. Whitespace exists for experiential retail formats targeting confectionery-tourism integration with local agricultural tourism circuits.
Hokkaido
Sapporo and Tomakomai production clusters leverage captive dairy supply chains for clean-label compliance under Food Labeling Standards Act requirements. Factory-direct visitor experiences and dairy farm supply chain tours create channel innovation beyond traditional retail distribution. The island's aging workforce in confectionery technology expertise presents capability constraints for precision tempering and particle size reduction operations.
Japan Chocolate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty boutique positioning through freshness-limited formats. The market structures around three tiers: integrated dairy conglomerates with Hokkaido supply chain control, Korean-origin competitors adapted to Japanese palate preferences, and artisanal bean-to-bar operators emphasizing provenance transparency. Strategic moves concentrate on backward integration into dairy sourcing, direct-to-consumer platform development, and experiential retail format expansion.
Within the integrated conglomerate tier, Meiji Holdings Co., Ltd. exemplifies supply chain control through Hokkaido dairy integration, while Lotte Co., Ltd. represents Korean-origin competitive pressure on price-sensitive segments. Royce' Confect Co., Ltd. anchors the specialty boutique archetype through freshness protocols that limit geographic expansion. These three occupy distinct competitive positions without direct overlap in procurement channels or consumer occasions.
| Leading Market Players |
|---|
| Meiji Holdings Co., Ltd. |
| Lotte Co., Ltd. |
| Morinaga & Co., Ltd. |
| Nestlé Japan |
| Ezaki Glico |
| Royce' Confect Co., Ltd. |
| Mondelez Japan |
| Mars Inc. |
| Yuraku Confectionery |
| Others |
Value Chain & Pricing Dynamics
Cocoa butter futures volatility on the London International Financial Futures Exchange cascades through Japan's chocolate supply chain into three-tier pricing structure across premium, standard, and economy levels. METI's Food Labeling Standards Act enforcement privileges Hokkaido-integrated manufacturers with captive dairy supply chains, compressing margins for importers facing laboratory validation costs and origin disclosure compliance.
Pricing Analysis
Temperature-controlled logistics warranties separate bundled freshness-guarantee pricing from unbundled shelf-stable alternatives. Premium nama chocolate tiers absorb cold-chain service costs through department store gifting markups, while economy milk chocolate segments compete on promotional price points in Osaka-Nagoya mass retail. Pricing pressure intensifies in mid-tier formulations as Korean-origin competitors capture price-sensitive households. Corporate procurement buyers in Tokyo's luxury corridor demonstrate lowest price sensitivity; suburban family purchasers in Chubu exhibit highest elasticity.
Supply Chain Analysis
Aging confectionery technologist cohorts in Kobe and Sapporo production clusters constrain precision tempering capacity expansion. Manufacturing concentrates in Japan's Hokkaido dairy belt, with secondary processing nodes in Kobe and Sakai. Cocoa butter inputs draw from West African origins; Hokkaido milk powders anchor domestic provenance claims. Single-source vulnerability in West African cocoa supply creates exposure to harvest disruption and quality variance. Distribution runs through temperature-controlled corridors serving Tokyo-Osaka corridor specialty boutiques, with extended shelf-life variants reaching Kyushu through conventional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's chocolate market sits in a formulation-technology transition phase. Precision fermentation for cocoa butter alternatives is displacing conventional bean-to-bar sourcing among mid-tier manufacturers seeking supply security.
For Market Incumbents: Deepen Hokkaido dairy integration through captive farm acquisitions to preempt METI provenance enforcement expansion. Accelerate precision fermentation pilot capacity to reduce West African supply dependence. Defensive consolidation around freshness-protocol expertise counters Korean-origin price competition in standard tiers. For New Entrants and Emerging Players: Launch via experiential retail formats in Fukuoka and Kyushu urban centers where specialty boutique density remains underdeveloped. Target health-positioned dark chocolate segments with probiotic and low-glycemic formulations for aging demographic permissive indulgence. Factory-direct tourism integration with Hokkaido dairy circuits offers differentiated channel access. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision fermentation technology holders with Hokkaido operational footprints in Sapporo-Tomakomai corridor. Long-term viability hinges on clean-label compliance infrastructure and captive supply chain control rather than brand equity alone. Watch METI enforcement intensity on "natural" and "clean" claim standardization as inflection signal for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Reduces West African cocoa butter dependence while maintaining 30-micron mouthfeel standards. |
| Hokkaido Dairy Integration | Secures Food Labeling Standards Act compliance through documented farm-to-factory traceability. |
| Experiential Retail Expansion | Captures corporate omiyage procurement migrating from department store counters to Ginza boutiques. |
| Health-Positioned Formulation | Targets aging demographics with probiotic dark chocolate for permissive indulgence occasions. |
| Confectionery-Tourism Integration | Creates channel innovation through factory-direct visitor experiences and dairy farm supply tours. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with confectionery technologists, department store category buyers, Hokkaido dairy cooperative managers, and METI compliance officers combined with Japan Chocolate and Cocoa Association production statistics, Consumer Affairs Agency enforcement disclosures, and Japan Agricultural Standards certification databases. Bottom-up volume modeling triangulated against top-down expenditure estimates across product type, end user, and distribution channel segments.
Data-stream reconciliation merged production capacity surveys with retail audit movement data across the projection horizon. Segmentation dimensions modeled include cocoa content tier, dairy provenance origin, freshness protocol requirements, and channel temperature-control specifications. CAGRs derived from regression analysis against household expenditure trends and gifting occasion frequency patterns. Forecast inputs incorporated METI regulatory enforcement trajectory assumptions and precision fermentation technology cost curve expectations.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation scale-up would alter the outlook. Forecasts reflect assumptions around Hokkaido dairy supply stability and West African cocoa harvest consistency. Material deviation in METI clean-label enforcement intensity or cocoa butter futures volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Low-Calorie Dark Chocolate Market
Confectionery
South America Confectionery Market
Confectionery
North-American Industrial Chocolate Market
Confectionery
Confectionery Fillings Market
Confectionery
Functional Confectionery Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Confectionery Fats Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Canada Chocolate Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Chocolate Confectionery Market
Confectionery
Asia-Pacific Sugar Free Mints Market
Confectionery
Global Industrial Chocolate Market
Confectionery
China Chocolate Market
Confectionery
South Korea Chocolate Market
Confectionery
Asia Pacific Chocolate Market