
 Oat-Based Snacks Market | 2026-2036
Oat-Based Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Oat-Based Snacks Market Analytics
Canada is fragmenting oat-based snack production across Alberta and Saskatchewan processing corridors. General Mills anchors North American supply through dedicated oat milling infrastructure and long-term grower contracts. Nature's Path Foods differentiates via certified organic sourcing protocols that command premium shelf positioning. Mondelez International extends its distribution leverage from biscuit portfolios into adjacent oat snacking categories.
Oat-based snacks comprise processed oat formulations—typically containing rolled or steel-cut oat flakes at 40-60% by weight, bound with syrups or oils, then baked or extruded into portable formats designed for between-meal consumption. Granola bars occupy the dominant value position within product type segmentation, while baked form variants capture margin pools through extended shelf stability and lower logistics costs. Online retailers represent the fastest-growing distribution channel, though supermarkets retain volume leadership through impulse placement strategies.
FDA nutritional labeling requirements and USDA organic certification standards shape formulation decisions and market access thresholds for domestic manufacturers. Health Canada and PMRA jointly govern oat ingredient safety and pesticide residue limits that affect cross-border trade flows. Stakeholders must monitor evolving clean-label enforcement intensity and regional sourcing compliance costs to sustain margin structures.
Market Dynamics
Clean-label reformulation pressure from FDA nutritional disclosure requirements is compressing legacy formulation margins while forcing accelerated R&D cycles across oat-based snack portfolios.
Growth Catalysts
- Millennial breakfast replacement demand:Urban health-conscious consumers in Germany and Canada treat portable oat formats as meal substitutes, expanding consumption occasions beyond traditional snacking windows.
- USDA organic certification premiums:Certified organic sourcing protocols command shelf price advantages and retailer priority placement in North American natural food channels.
- Extrusion technology advancement:Modern extrusion systems enable protein fortification and texture engineering that differentiates functional oat bars from commodity granola products.
Market Restraints
- Oat input cost volatility:Prairie drought cycles in Alberta and Saskatchewan create supply uncertainty that compresses processor margins during poor harvest years.
- Steel-cut oat processing concentration:Limited North American milling infrastructure creates bottleneck dependency on a handful of regional processors.
- Clean-label compliance friction:FDA added sugar disclosure rules force reformulation of legacy syrup-bound products, eroding familiar taste profiles that drive repeat purchase.
Strategic Opportunities
- German functional snacking white space:Bakery heritage culture creates receptive environment for premium positioned oat formats with added protein or fiber claims.
- Online direct-to-consumer channel expansion:Subscription models bypass supermarket slotting fee structures and capture margin pools previously allocated to retail intermediaries.
- Health Canada organic equivalency recognition:Harmonized certification standards reduce cross-border compliance duplication costs for North American suppliers.
Industry Challenges
- Food technologist talent scarcity:Clean-label formulation expertise combining sensory science with regulatory compliance commands premium compensation that strains mid-tier manufacturer budgets.
- Extrusion equipment capex intensity:Modern high-moisture extrusion lines require seven-figure capital commitments that disadvantage smaller regional players.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat-Based Snacks Market |
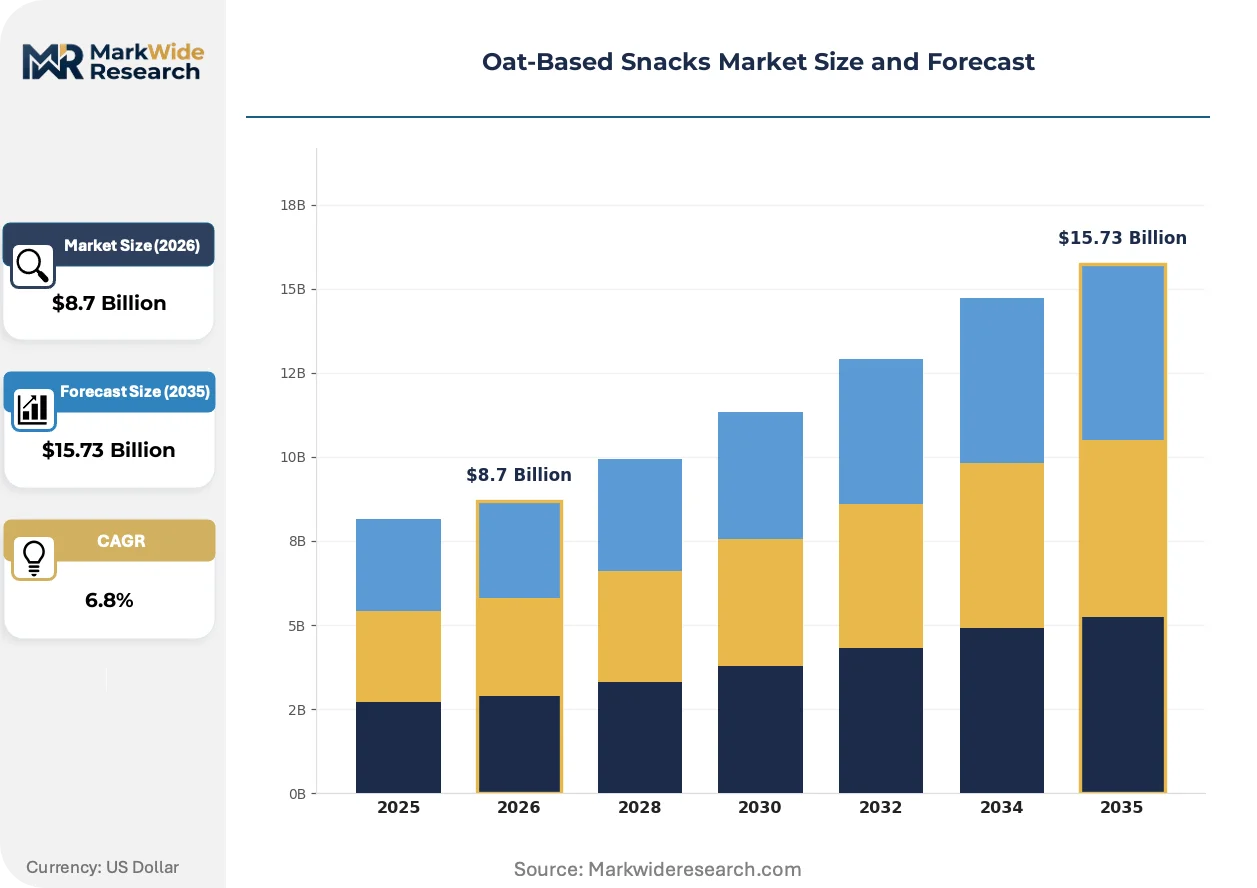
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Oat Cookies, Oatmeal Cups, Oat Clusters Form: Ready-to-Eat, Baked, Chewy, Crunchy Flavor: Chocolate, Berry, Apple Cinnamon, Peanut Butter Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores |
| Companies Covered | Mondelez International, The Hain Celestial Group, General Mills, Clif Bar & Company, Nairn's Oatcakes, Kellogg Company, Abbott Laboratories, Nature's Path Foods, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat-Based Snacks Market Evolving Landscape
Digital traceability infrastructure and accelerated clean-label enforcement are compressing traditional product development timelines while opening premium positioning opportunities for verified supply chains.
Blockchain-enabled ingredient provenance tracking is virtualizing traditional paper-based audit trails. German and Canadian organic oat suppliers deploy distributed ledger systems to verify farm-level sourcing claims. Retail buyers in urban centers now demand real-time traceability dashboards that compress third-party certification timelines and reduce insurance costs for verified clean-label products.
EU F-Gas Regulation phase-down mandates are accelerating refrigeration technology shifts across European oat snack distribution networks. Cold-chain dependent fresh oat bar formats face equipment replacement cycles that favor ambient-stable baked alternatives. German manufacturers respond with modified atmosphere packaging investments that extend shelf life without temperature-controlled logistics.
Subscription-based replenishment models are displacing impulse-driven supermarket purchasing for core oat snack categories. Direct-to-consumer platforms capture recurring revenue from millennial households in Toronto and Vancouver while eroding traditional grocery volume. This channel rotation concentrates most visibly in Canada, where rural distribution gaps make scheduled delivery preferable to sporadic retail access.
Oat-Based Snacks Market Segmentation
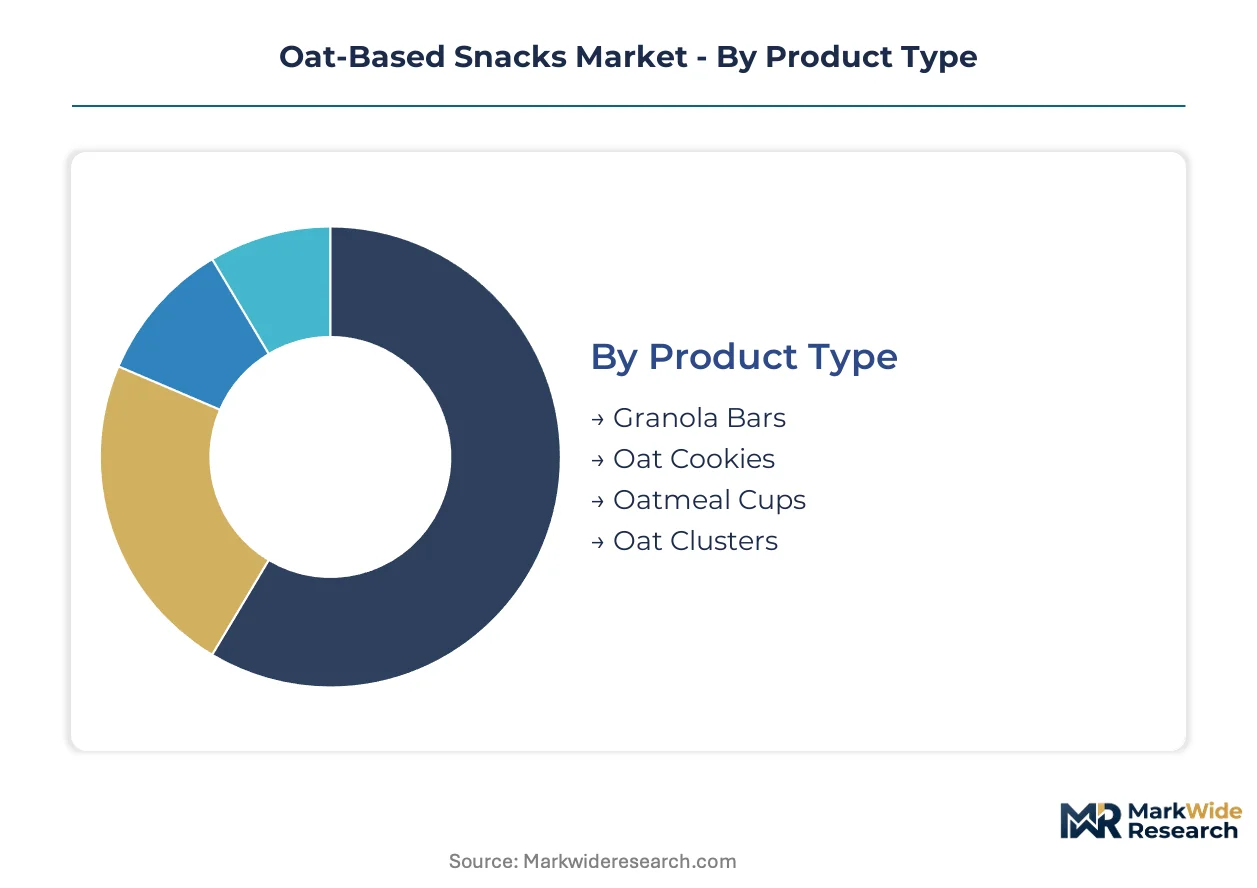
Product differentiation across oat-based snacks hinges on texture engineering, shelf stability, and placement strategy. Manufacturers configure formulations to match specific consumption occasions while navigating channel-specific margin structures.
Product Type:
Cost tier stratification separates commoditized formats from premium-positioned variants with functional ingredient claims.
- Granola Bars:Rolled oat flakes bound with syrup matrices and compressed into portable rectangular formats. German millennial households in Berlin and Munich treat these as breakfast replacements during weekday commutes, driving repeat purchase frequency through convenience positioning.
- Oat Cookies:Higher fat and sugar content than bar formats, leveraging traditional bakery associations for indulgence occasions. Canadian Prairie provinces show concentration of manufacturing capacity for this segment, with Alberta processors supplying North American private-label programs.
- Oatmeal Cups:Single-serve instant oat portions requiring hot water preparation. Office pantry placement in Toronto and Vancouver towers sustains demand.
- Oat Clusters:Loose granola formats targeting yogurt topping and home-baking applications. Health food store distribution dominates.
Granola bars hold installed capacity. Oat clusters are rotating up the share rankings.
Form:
Application context dictates moisture content targets and binding agent selection across manufacturing lines.
- Ready-to-Eat:Pre-portioned formats requiring no preparation beyond package opening. Urban convenience store placement in Canadian metropolitan corridors captures impulse traffic from commuters seeking immediate consumption solutions.
- Baked:Low-moisture extrusion or oven processing delivers extended ambient shelf stability. German retail buyers prioritize this form for reduced logistics costs and minimized cold-chain dependency.
- Chewy:Higher moisture content achieved through syrup retention and fat encapsulation. Texture preference concentrates in younger demographic cohorts.
- Crunchy:Brittle fracture mechanics from extended baking cycles or post-bake toasting. Premium positioning in natural food channels commands shelf price advantages.
Baked forms hold installed capacity. Chewy variants are rotating up the share rankings.
Flavor:
Customer type clustering reveals distinct preference patterns between health-motivated and indulgence-seeking segments.
- Chocolate:Cocoa powder or chip inclusions masking oat base flavors for mass-market acceptance. Dominant velocity in North American supermarket channels.
- Berry:Dried cranberry, blueberry, or raspberry pieces targeting clean-label positioning with natural color and antioxidant associations. German organic certification programs favor this profile.
- Apple Cinnamon:Classic bakery flavor pairing with seasonal demand spikes. Canadian breakfast replacement occasions show above-average adoption.
- Peanut Butter:Protein fortification synergy through nut paste binding. Allergen labeling requirements constrain school-channel placement.
Chocolate holds installed capacity. Berry profiles are rotating up the share rankings.
Distribution Channel:
Geography and volume concentration determine packaging format and promotional investment allocation.
- Supermarkets:High-velocity shelf placement with slotting fee structures and promotional calendar dependency. German REWE and Edeka chains drive continental European volume through end-cap positioning.
- Health Food Stores:Curated assortment with certified organic and non-GMO verification requirements. Canadian independents in British Columbia and Ontario provinces prioritize local sourcing claims.
- Online Retailers:Subscription replenishment models bypass traditional retail margin stacking. Toronto and Vancouver metro areas show steepest expansion trajectory for direct-to-consumer oat snack delivery.
- Convenience Stores:Single-serve impulse formats with compressed shelf life and higher price per ounce. Highway corridor placement captures travel occasion demand.
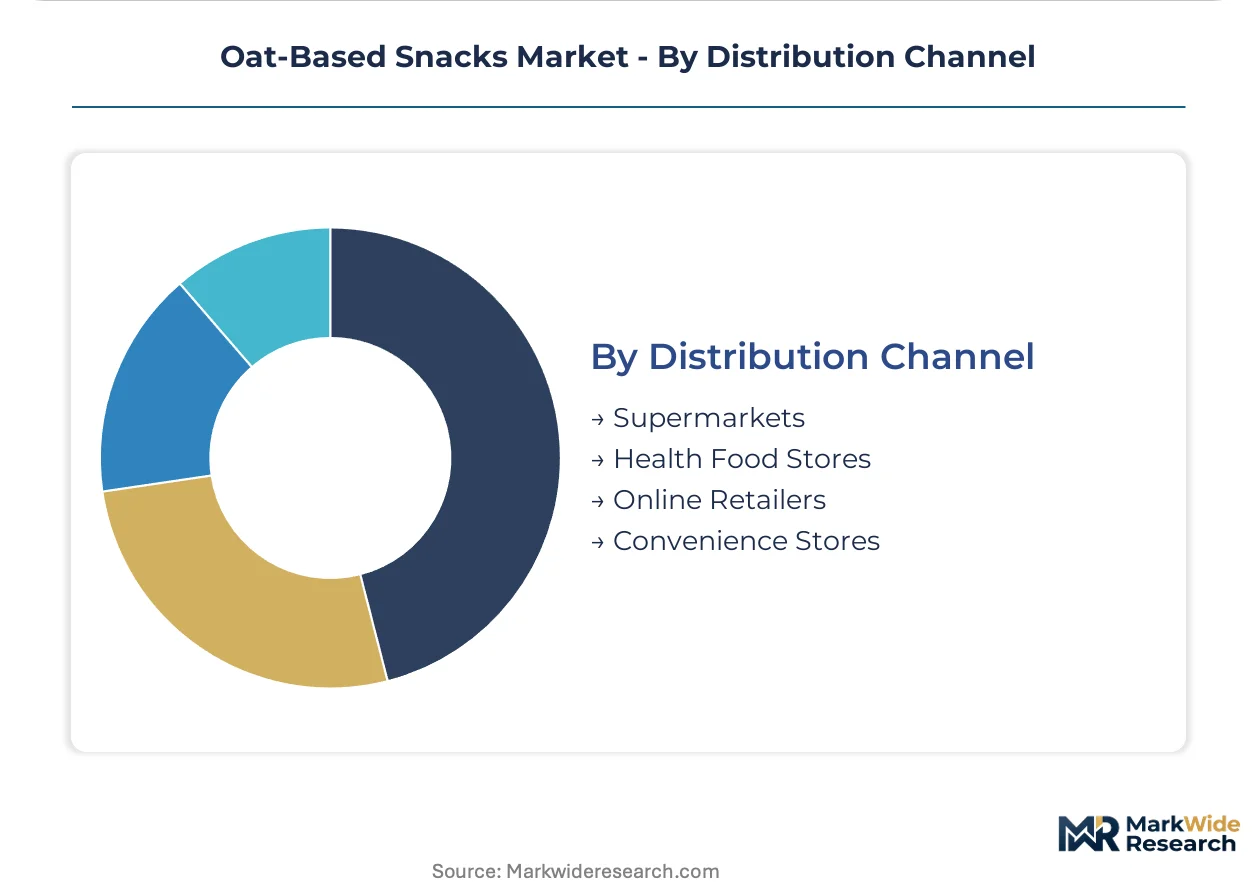
Supermarkets hold installed capacity. Online retailers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutritional disclosure requirements anchor the United States as the dominant regulatory geography, with Health Canada and EFSA frameworks creating parallel compliance corridors in adjacent markets. Urban millennial demand clusters in specific metropolitan corridors drive regional performance variation.
United States
Millennial breakfast replacement demand concentrates in New York Metro and Los Angeles corridors, where portable oat formats capture commuter occasions. FDA added sugar disclosure rules force reformulation of legacy syrup-bound granola bars. Chicago anchors North American oat milling infrastructure through dedicated processing facilities serving branded and private-label programs.
Germany
Bakery heritage culture merges with functional snacking preferences in Berlin and Munich urban centers, creating premium positioning opportunities for protein-fortified oat formats. EU F-Gas Regulation phase-down mandates accelerate refrigeration technology shifts across distribution networks. Bavaria hosts modified atmosphere packaging investments that extend shelf life without cold-chain dependency.
Canada
Subscription-based replenishment models displace impulse-driven supermarket purchasing in Toronto and Vancouver metro areas. Health Canada and PMRA jointly govern oat ingredient safety and pesticide residue limits affecting cross-border trade. Alberta and Saskatchewan processing corridors fragment production across Prairie provinces with grower contract concentration.
United Kingdom
Clean-label enforcement intensity from EFSA guidance creates compliance friction for imported oat snack formulations. London and Southeast England concentrate health food store distribution with certified organic verification requirements. Midlands manufacturing clusters supply private-label programs across European retail channels.
Japan
Functional food positioning aligns with METI-promoted health claims frameworks for fiber and protein fortification. Tokyo and Osaka metropolitan areas drive premium-tier demand for texture-engineered oat formats. Kansai region hosts extrusion technology advancement facilities serving Asia-Pacific export markets.
Oat-Based Snacks Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another, creating a bifurcated structure where organic certification specialists command premium positioning while diversified food conglomerates anchor volume throughput. The vendor base separates into three strategic archetypes: legacy cereal manufacturers extending into adjacent snacking, certified organic pure-plays with sourcing protocol differentiation, and private-label suppliers serving retail channel consolidation. M&A activity targets organic certification capabilities, while capacity expansion focuses on extrusion technology advancement for functional ingredient integration.
Among diversified food conglomerates, Mondelez International and General Mills exemplify scale-driven archetypes with distribution leverage extending from core portfolios into oat snacking adjacencies. Nature's Path Foods occupies a position within the certified organic tier, representing sourcing protocol differentiation that commands premium shelf positioning in North American natural food channels.
| Leading Market Players |
|---|
| Mondelez International |
| The Hain Celestial Group |
| General Mills |
| Clif Bar & Company |
| Nairn's Oatcakes |
| Kellogg Company |
| Abbott Laboratories |
| Nature's Path Foods |
| PepsiCo |
| Others |
Value Network & Pricing Analysis
Undercapacity in Prairie oat milling infrastructure during drought years in Alberta and Saskatchewan compresses processor margins and amplifies spot-price volatility for rolled oat inputs. This utilization squeeze forces manufacturers toward long-term grower contracts that trade pricing certainty for sourcing rigidity.
Pricing Analysis
German organic oat snacks command shelf price premiums 40-60% above North American conventional equivalents, reflecting certification cost absorption and bakery heritage positioning. Three-tier pricing structure across premium, standard, and economy levels separates certified organic SKUs from private-label conventional bars and commodity bulk formats. Pricing pressure stems from FDA added sugar disclosure rules forcing reformulation of legacy syrup-bound products. Price-sensitive mass-market buyers in North American supermarkets resist premium migration, while German urban millennials accept functional ingredient premiums.
Supply Chain Analysis
Health Canada and PMRA pesticide residue limits function as de facto export controls restricting cross-border oat flows from non-equivalent certification regimes. Supply concentrates in Canadian Prairie provinces and German Bavarian processing clusters, with raw material dependencies on Alberta grower contracts, Saskatchewan organic acreage, and European modified atmosphere packaging films. Single-source vulnerability runs through limited North American steel-cut oat milling infrastructure. Distribution runs through supermarket slotting fee structures in Germany and direct-to-consumer subscription platforms in Canadian metro corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oat-based snacking sits in early-cycle expansion as millennial breakfast replacement occasions displace traditional cereal consumption in urban centers. Clean-label enforcement intensity and extrusion technology advancement create asymmetric returns for first movers.
For Market Incumbents: Entrench sourcing control through backward integration into Prairie oat milling capacity and multi-year organic grower contracts. Defend against private-label erosion by accelerating Health Canada organic equivalency recognition to reduce cross-border compliance duplication. Prioritize extrusion equipment capex in Bavaria to capture German functional snacking white space.
For New Entrants and Emerging Players: Establish a beachhead in Canadian online direct-to-consumer subscription models, where rural distribution gaps and millennial replenishment preferences concentrate addressable demand. Target Toronto and Vancouver metro areas with texture-engineered chewy variants. Leverage blockchain-enabled ingredient provenance as a go-to-market differentiator against incumbent paper-based audit trails.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across extrusion technology advancement and modified atmosphere packaging lines, favoring scaled players with balance sheet capacity. Five-to-ten year viability hinges on clean-label formulation expertise scarcity. Acquire certified organic pure-plays with established Health Canada equivalency and Prairie grower relationships. Watch Health Canada-PMRA enforcement intensity as the inflection signal for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | FDA added sugar disclosure rules force legacy product portfolio overhaul to sustain repeat purchase rates. |
| Organic Certification Expansion | USDA and Health Canada equivalency recognition reduces cross-border compliance costs for North American suppliers. |
| Extrusion Technology Advancement | High-moisture extrusion lines enable protein fortification that differentiates functional bars from commodity granola. |
| Direct-to-Consumer Channel Buildout | Subscription models in Toronto and Vancouver bypass supermarket slotting fees and capture recurring revenue pools. |
| Blockchain Traceability Deployment | Distributed ledger systems verify farm-level sourcing claims and compress third-party certification timelines for retail buyers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand managers, category buyers at REWE and Edeka chains, oat procurement leads at Prairie processors, and Health Canada regulatory affairs specialists. Secondary validation drew from FDA nutritional labeling guidance documents, USDA organic certification databases, Nielsen retail audit data, and EFSA clean-label enforcement guidance. Bottom-up volume modeling triangulated against top-down category spend estimates.
Calibration against historical CAGRs and elasticity assumptions anchored projections across the analysis window. Segmentation dimensions modeled include product type, form, flavor profile, distribution channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation moderated by input cost volatility scenarios. Forecast inputs incorporated oat yield variance from Prairie drought cycles and EU F-Gas Regulation phase-down impacts on distribution equipment replacement.
Sensitivities concentrate around Health Canada-PMRA enforcement intensity, FDA added sugar disclosure implementation timing, and extrusion equipment capex availability. Cross-checking against USDA National Agricultural Statistics Service oat production data and IRI retail velocity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Snack Food Packaging Market
Snacks
South America Snack Bar Market
Snacks
Germany Energy Bar Market
Snacks
United Kingdom Energy Bar Market
Snacks
China Snack Bar Market
Snacks
Superfoods-Based Packaged Snacks Market
Snacks
Cheese Snacks Market
Snacks
Spain Energy Bar Market
Snacks
Spain Snack Bar Market
Snacks
Qatar Potato Chips Market
Snacks
United States Energy Bar Market
Snacks
Premium Snacks Market
Snacks
Organic Snacks Market
Snacks
North America Energy Bar Market
Snacks
Asia Pacific Frozen Snacks Market
Snacks
Meat Snacks Market