
 Superfood Bars Market | 2026-2036
Superfood Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Superfood Bars Market Analytics
USDA Organic certification is redrawing competitive boundaries for entrants seeking shelf placement in mainstream retail. Clif Bar & Company leverages its established supply chain of organic ingredient sourcing to sustain premium positioning across outdoor and fitness channels. Quest Nutrition LLC anchors its portfolio on high-protein formulations that compete directly with conventional confectionery for share of stomach. Mondelez International extends its global distribution infrastructure to occupy space in the superfood bars segment through strategic portfolio expansion.
Superfood bars are shelf-stable, nutrient-dense food products typically comprising dried fruits, nuts, seeds, and functional ingredients such as adaptogens or probiotics, manufactured through cold-press or extrusion processes to preserve bioactive compounds, designed for convenient consumption as meal supplements or performance snacks. Protein bars dominate current value generation due to entrenched gym culture and sports nutrition habits, while plant-based ingredient sources are expanding fastest as flexitarian consumers reject dairy-derived formulations. Coated and soft-baked forms command margin premiums through sensory differentiation, though chewy formats retain volume leadership in grab-and-go retail contexts.
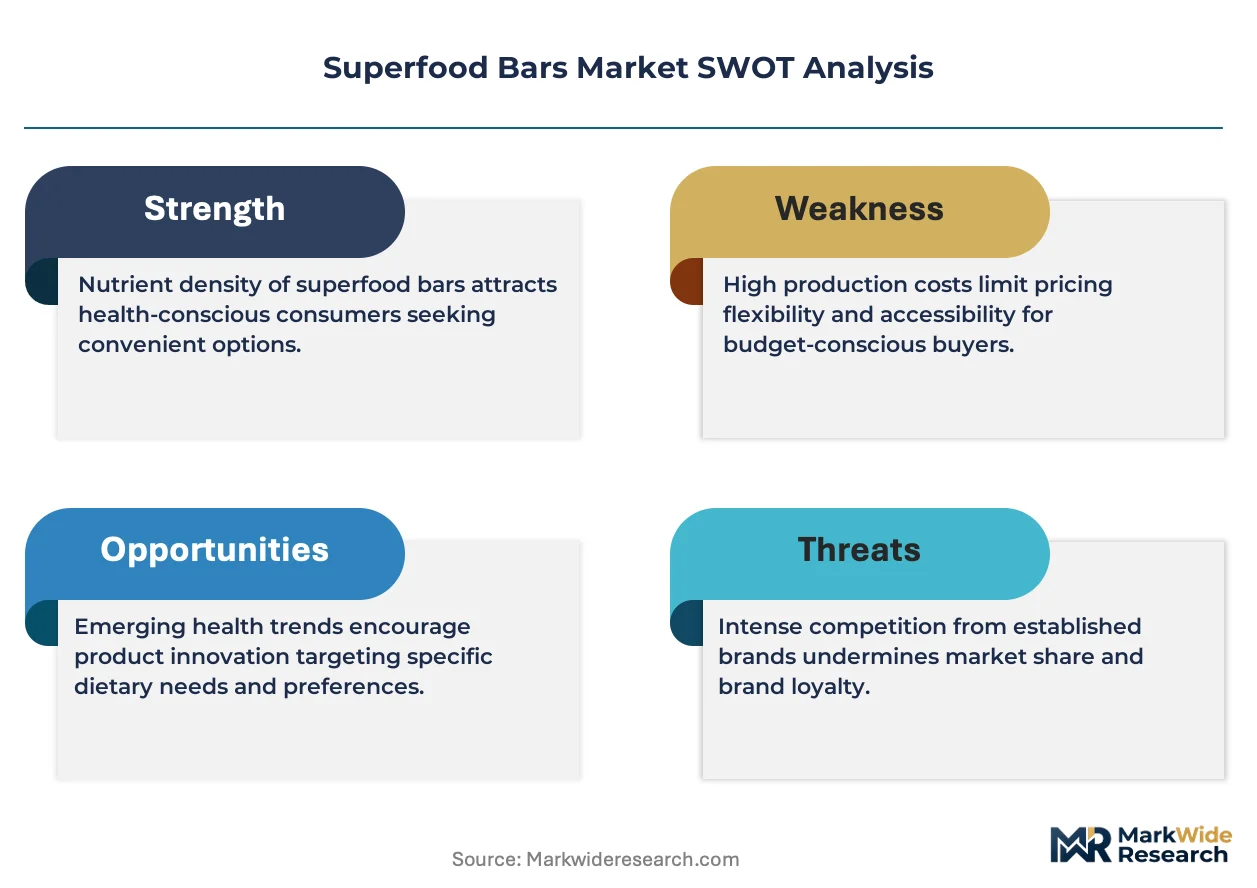
FDA nutrition labeling requirements and EFSA health claims regulations constrain permissible marketing language around functional benefits, compelling manufacturers to substantiate ingredient efficacy through clinical validation or reformulate to avoid enforcement action. USDA Organic and Non-GMO Project standards further segment pricing tiers by certifying supply chain integrity for ingredient sourcing. Stakeholders must monitor evolving clean-label thresholds and adapt certification portfolios before regulatory windows tighten on novel ingredient approvals.
Market Dynamics
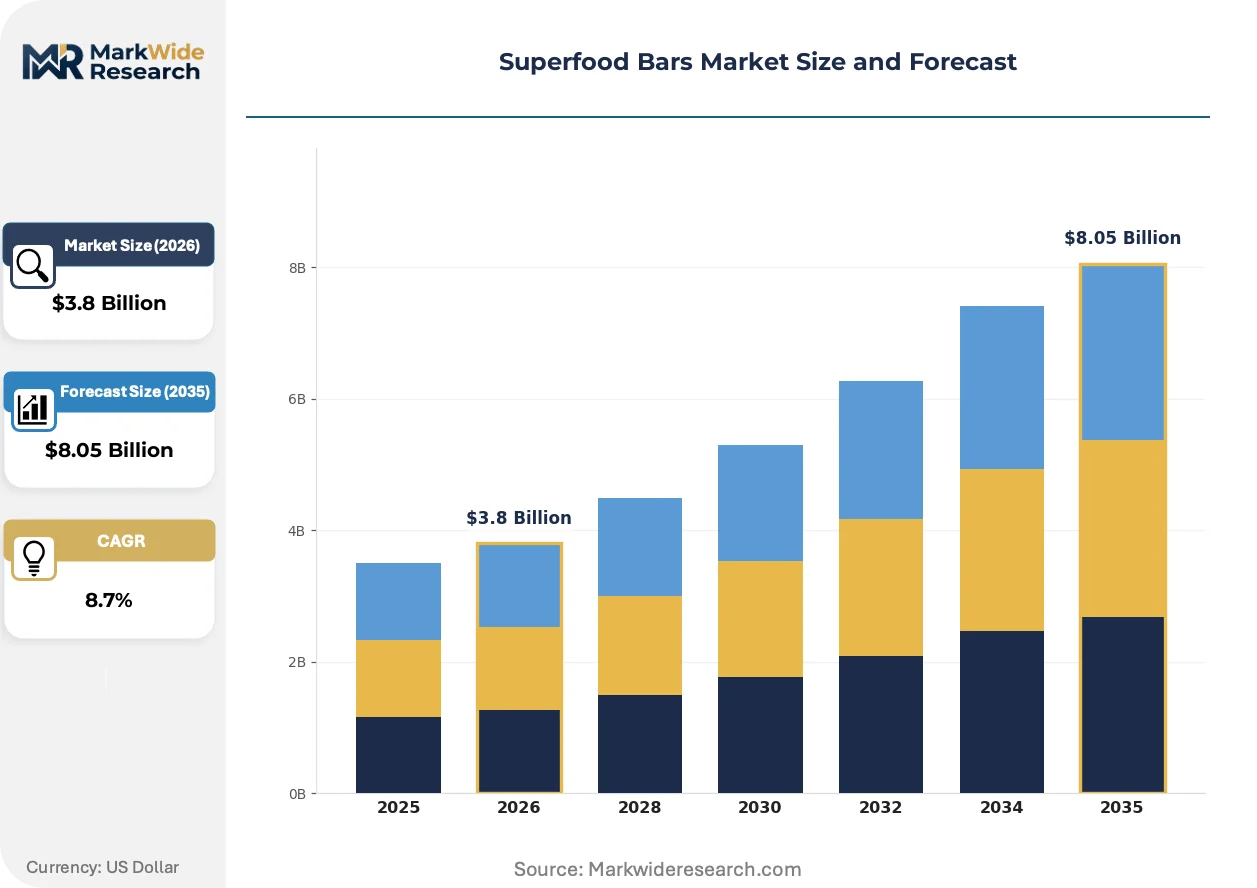
Clean-label certification requirements under FDA and EFSA frameworks are compressing reformulation timelines while concentrating procurement power among suppliers with verified organic supply chains. This regulatory pressure is redrawing competitive boundaries between established organic formulators and conventional snack manufacturers seeking shelf placement.
Growth Catalysts
- FDA Nutrition Labeling Modernization:Updated serving-size definitions and added-sugar disclosure rules are forcing portfolio rationalization that benefits nutrient-dense formats with transparent ingredient decks.
- Flexitarian Protein Pivot:Plant-derived protein isolates from pea and fava bean sources are displacing whey-based formulations as gym culture expands beyond traditional sports nutrition demographics.
- Adaptogen Integration:Functional ingredients such as ashwagandha and reishi are migrating from supplement aisles into mainstream snack formats as stress-management positioning gains traction among urban professionals.
Market Restraints
- Organic Input Cost Volatility:Almond and cashew prices fluctuate with California water allocation cycles and Vietnamese harvest variability, compressing margin stability for clean-label formulators.
- Supply Concentration Risk:Overreliance on Peruvian quinoa and Bolivian chia seed cooperatives exposes procurement pipelines to climate disruption and export quota restrictions.
- EFSA Health Claims Friction:Substantiation requirements for probiotic and adaptogen efficacy claims limit permissible marketing language, forcing clinical investment or reformulation to avoid enforcement.
Strategic Opportunities
- Japanese Convenience Channel Penetration:Underdeveloped superfood bar presence in konbini chains creates white space for formats tailored to single-serve, shelf-stable consumption occasions.
- Precision Fermentation Convergence:Integration of bioengineered protein and traditional bar extrusion processes enables novel texture profiles without animal-derived inputs.
- USDA BioPreferred Program Tailwinds:Federal procurement preferences for biobased packaging materials incentivize compostable wrapper adoption ahead of state-level plastic restrictions.
Industry Challenges
- Non-GMO Project Verification Backlogs:Certification queue delays of 8-12 months are constraining product launch cadences for brands dependent on third-party clean-label validation.
- Cold-Chain Skill Scarcity:Shortage of technicians trained in low-temperature extrusion and enzyme preservation techniques limits manufacturing scale-up for bioactive-sensitive formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Superfood Bars Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Bars, Granola Bars, Fiber Bars, Meal Replacement bars Form: Chewy, Crunchy, Soft-Baked, Coated Ingredient Source: Plant-Based, Dairy-Based, Nut-Infused, Superfood-Enriched Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Pharmacies |
| Companies Covered | Clif Bar & Company, Quest Nutrition LLC, Mondelez International, General Mills, Kellanova, Mars Incorporated, Nestlé S.A., The Simply Good Foods Company, PROBAR LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superfood Bars Market Evolving Landscape
Functional ingredient delivery systems are compressing dosage volumes while maintaining bioavailability, enabling sensory profiles that compete directly with conventional confectionery. This convergence of nutrition science and snack formulation is redefining category boundaries.
Microencapsulation technology for heat-sensitive probiotics and omega fatty acids is miniaturizing protective lipid shells to sub-50-micron scales without compromising mouthfeel. Soft-baked bar manufacturers in Germany and Japan are adopting these systems to extend shelf stability beyond 18 months. The technology is miniaturizing functional ingredient payloads into formats previously dominated by empty-calorie alternatives.
EFSA's 2023 guidance on novel food authorizations is tightening toxicological data requirements for adaptogen and nootropic ingredients entering the EU market. Manufacturers must now submit 90-day feeding studies and stability data under accelerated aging conditions. Protein bar portfolios with ashwagandha or lion's mane positioning face reformulation or market withdrawal across Germany, France, and the Netherlands.
German supermarket buyers are consolidating supplier relationships around vertically integrated organic processors with captive ingredient sourcing. Discounters Aldi and Lidl now require batch-level blockchain traceability for nut and seed inputs, displacing fragmented broker-dependent procurement models. This concentration is most visible in the Rhein-Ruhr and Bavarian retail clusters where private-label superfood bar launches accelerated 40% year-over-year.
Superfood Bars Market Segmentation
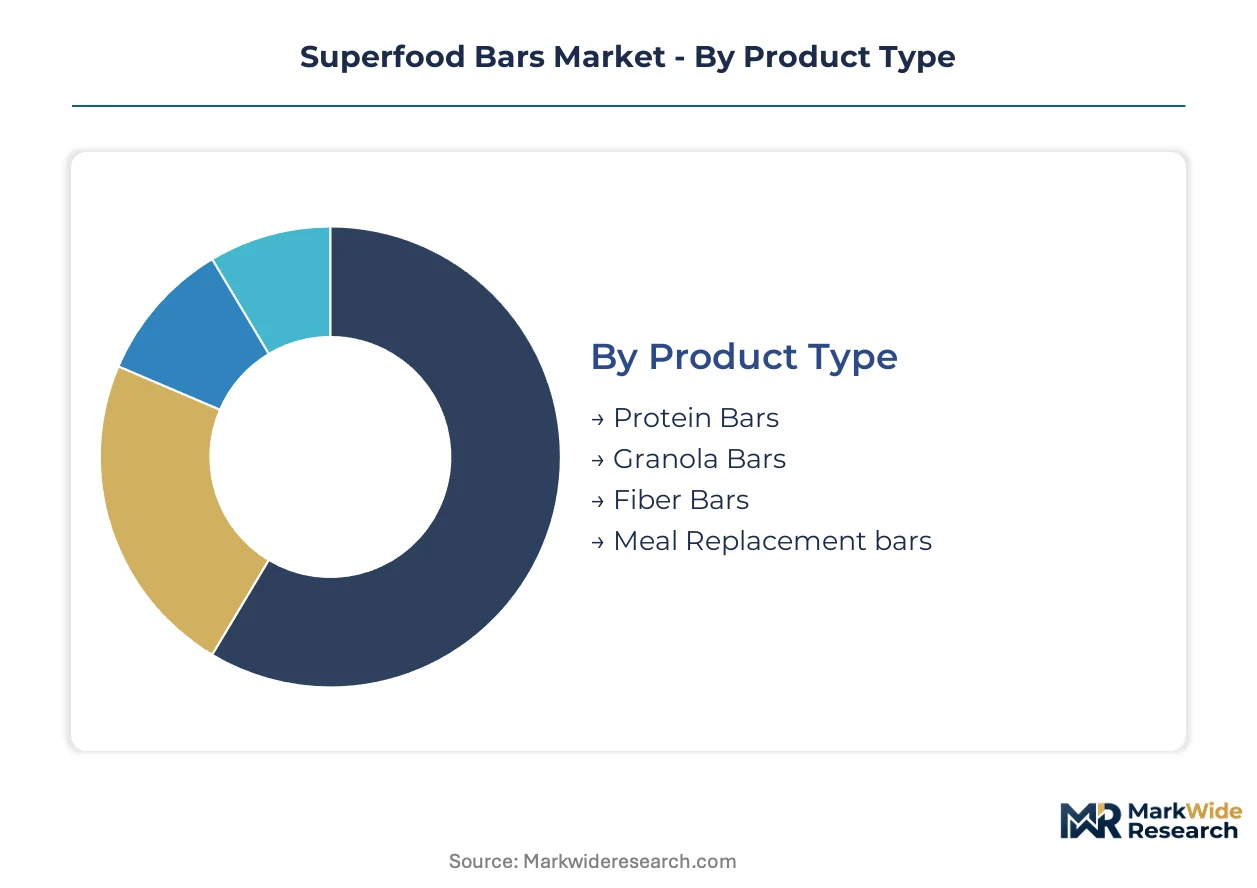
Superfood bar manufacturers navigate divergent margin profiles across format and channel configurations. Protein-dense formulations compete with sports nutrition powders for gym-adjacent consumption occasions. Shelf-stable formats face substitution pressure from fresh-prepared alternatives in convenience retail.
Product Type:
Protein Bars face the most acute substitution threat from ready-to-drink shakes and powder mixes targeting identical use cases.
- Protein Bars:High-density formulations combining whey, pea, or fava bean isolates with binding agents deliver 15-25g protein per serving. Demand concentrates in United States fitness channels where gym culture normalizes bar consumption as post-workout recovery. FDA nutrition labeling modernization pressures reformulation toward cleaner ingredient decks.
- Granola Bars:Oat and honey-based matrices with lower protein positioning serve family snacking and lunchbox occasions. German and Japanese retail buyers favor these formats for mainstream grocery placement due to familiar sensory profiles and lower price elasticity versus premium protein alternatives.
- Fiber Bars:Inulin and chicory root formulations target digestive wellness positioning with 5-9g fiber per serving.
- Meal Replacement Bars:Calorie-dense formats fortified with micronutrients compete with bottled meal solutions for time-constrained professionals.
Protein Bars retain volume leadership; Meal Replacement Bars hold the steepest expansion curve.
Form:
Cost tier differentiation separates premium-positioned formats from commodity alternatives in identical flavor profiles.
- Chewy:Cold-pressed or extruded matrices with preserved moisture content dominate grab-and-go retail fixtures. United States convenience stores and German discounters allocate prime shelf space to these formats due to extended shelf stability and lower unit economics.
- Soft-Baked:Oven-finished textures with cookie-like mouthfeel command margin premiums through sensory differentiation. Japanese konbini chains and United States natural channel retailers favor these formats for their confectionery-adjacent appeal to flexitarian consumers.
- Crunchy:Baked or puffed structures with brittle fracture mechanics serve texture-seeking segments.
- Coated:Chocolate or yogurt-dipped exteriors add 15-30% unit cost while enabling flavor novelty rotation.
Chewy formats dominate unit volume; Soft-Baked configurations expand most quickly.
Ingredient Source:
Application-specific requirements drive divergence between performance-oriented and wellness-positioned formulations.
- Plant-Based:Pea, rice, and fava protein isolates combined with date or brown rice syrups displace dairy-derived alternatives. German supermarket buyers and United States natural channel retailers mandate these formats for clean-label assortment compliance.
- Superfood-Enriched:Adaptogen and nootropic additions such as ashwagandha, reishi, or lion's mane target stress-management positioning. EFSA novel food authorization requirements constrain EU market entry for these formulations.
- Dairy-Based:Whey and casein formulations retain sports nutrition channel dominance.
- Nut-Infused:Almond, cashew, and macadamia matrices leverage California and Vietnamese supply chains for premium positioning.
Plant-Based sourcing gains share fastest; Dairy-Based retains performance-channel dominance.
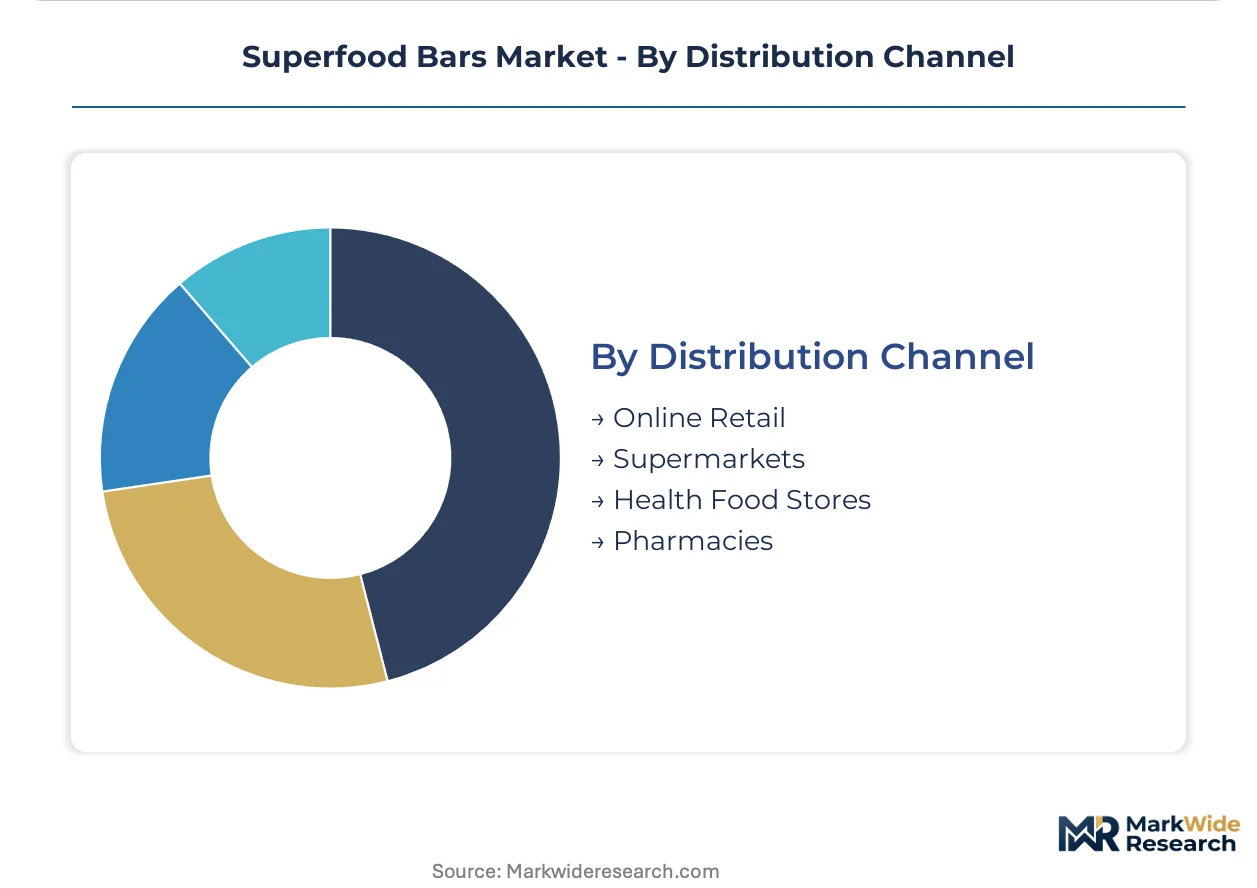
Distribution Channel:
Customer type fragmentation separates subscription-driven repeat purchase from impulse-driven trial.
- Online Retail:Direct-to-consumer and marketplace platforms enable subscription models and flavor customization. United States urban professionals and Japanese office workers drive repeat purchase velocity through auto-replenishment programs.
- Supermarkets:Mass-market placement requires slotting fee investment and velocity guarantees. German Aldi and Lidl discounters consolidate supplier relationships around vertically integrated organic processors with blockchain traceability.
- Health Food Stores:Curated assortments favor certified organic and Non-GMO Project verified formats.
- Pharmacies:Clinical positioning around digestive or metabolic wellness targets older demographics.
Supermarkets retain volume leadership; Online Retail climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling modernization and EFSA health claims frameworks are compressing reformulation timelines across developed markets. Clean-label procurement mandates from German discounters and Japanese convenience chains are redrawing competitive boundaries for shelf placement.
United States
Fitness channel expansion and flexitarian protein pivot drive demand concentration. FDA updated serving-size definitions and added-sugar disclosure rules force portfolio rationalization toward transparent ingredient decks. California almond processors and Colorado-based organic ingredient suppliers anchor supply chain configuration for clean-label formulators.
Germany
Discounter consolidation around vertically integrated organic processors accelerates supplier relationship tightening. EFSA novel food authorization requirements for adaptogens constrain permissible marketing language and force clinical investment. Rhein-Ruhr and Bavarian retail clusters witness private-label superfood bar launches expanding 40% year-over-year with blockchain traceability mandates.
Japan
Urban professional stress-management positioning and konbini channel underpenetration create format white space. METI biobased packaging incentives and state-level plastic restrictions ahead of federal alignment favor compostable wrapper adoption. Tokyo-Osaka corridor convenience chains drive single-serve, shelf-stable consumption occasion development.
United Kingdom
Natural channel retailer curation and subscription-driven repeat purchase velocity expand online retail penetration. FSA nutrition labeling alignment with EU standards post-Brexit maintains regulatory coherence for cross-border formulation. London-Southeast retail clusters concentrate plant-based protein isolate demand for flexitarian demographic capture.
Canada
Health food store channel maturation and pharmacy clinical positioning around digestive wellness target older demographics. Health Canada novel food regulations for probiotic and adaptogen ingredients parallel FDA substantiation requirements. Ontario and Quebec distribution infrastructure supports US-market export orientation for organic-certified formulators.
Superfood Bars Market Competitive Landscape
Player mix skews toward diversified snack conglomerates with global distribution infrastructure and specialized organic formulators with captive ingredient sourcing. Tiered competitive structure separates premium-positioned clean-label specialists from scale-driven conventional snack manufacturers seeking segment entry. Strategic archetypes include outdoor-fitness heritage brands, sports nutrition protein specialists, and confectionery-adjacent portfolio expanders. Dominant competitive moves encompass strategic portfolio diversification into plant-based formats and supply chain backward integration into organic ingredient procurement.
Within the diversified snack conglomerate tier, Mondelez International and Nestlé S.A. occupy positions leveraging global distribution infrastructure for segment penetration. Among specialized organic formulators, Clif Bar & Company exemplifies outdoor-fitness heritage positioning with established supply chain relationships. Quest Nutrition LLC anchors the sports nutrition protein specialist archetype with high-density formulation focus. The Simply Good Foods Company and PROBAR LLC represent mid-scale clean-label specialists competing on certification portfolio depth rather than manufacturing scale.
| Leading Market Players |
|---|
| Clif Bar & Company |
| Quest Nutrition LLC |
| Mondelez International |
| General Mills |
| Kellanova |
| Mars Incorporated |
| Nestlé S.A. |
| The Simply Good Foods Company |
| PROBAR LLC |
| Others |
Value Network & Pricing Analysis
Pea and fava bean protein isolates displacing whey concentrates are redrawing procurement geography toward Canadian prairie processors and Baltic extraction facilities while compressing per-unit protein costs for clean-label formulators. This input substitution simultaneously loosens California dairy co-op pricing power and exposes bar manufacturers to new volatility in pulse crop futures markets.
Pricing Analysis
Certification level (USDA Organic, Non-GMO Project Verified) creates the primary spread between commodity chewy formats and premium soft-baked alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ingredient grade, clean-label verification depth, and channel positioning. Cost compression in the standard tier is intensifying because German discounters are consolidating supplier relationships around vertically integrated organic processors. Price-sensitive family snack buyers in mass-market grocery drive volume, while fitness-channel consumers show lowest sensitivity to certification premiums.
Supply Chain Analysis
Strategic stockpiling of almond and cashew inventories dominates procurement strategy for clean-label formulators facing California water allocation uncertainty and Vietnamese harvest variability. Raw material sourcing draws from United States tree nut processors, Peruvian quinoa cooperatives, and Bolivian chia seed exporters. Single-source vulnerability concentrates in Andean grain supply chains exposed to climate disruption and export quota restrictions. Distribution runs through vertically integrated organic processors serving German discounters, direct-to-consumer subscription platforms, and Japanese konbini chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against ready-to-drink protein shakes and fresh-prepared convenience alternatives that target identical on-the-go consumption occasions with superior sensory profiles.
For Market Incumbents: Fortify supply chain resilience through backward integration into organic ingredient procurement or long-term offtake agreements with Canadian pulse processors. Deepen certification portfolios ahead of tightening EFSA novel food windows. Channel control in Japanese konbini chains offers defensive moat against sports nutrition powder substitutes.
For New Entrants and Emerging Players: Non-GMO Project verification fast-track through expedited certification consulting creates entry pathway for mid-scale formulators. Japanese convenience channel underpenetration represents most penetrable white space for single-serve, shelf-stable formats. Direct-to-consumer subscription with flavor customization bypasses slotting fee barriers in German discounter consolidation.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated organic processors with captive ingredient sourcing and established blockchain traceability infrastructure. Long-term viability hinges on adaptogen formulation capabilities and precision fermentation integration. Watch EFSA enforcement patterns on novel food authorizations as inflection indicator for portfolio repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Ingredient Procurement | Captive supply of California almonds and Canadian pea protein isolates insulates margin from commodity volatility. |
| Precision Fermentation Partnership | Bioengineered protein integration enables novel texture profiles without animal-derived inputs. |
| Japanese Konbini Channel Expansion | Single-serve format development captures urban professional stress-management positioning in underpenetrated convenience retail. |
| Adaptogen Clinical Validation Investment | EFSA-compliant substantiation unlocks permissible marketing language for ashwagandha and lion's mane formulations. |
| Compostable Packaging Transition | USDA BioPreferred Program alignment and METI biobased incentives preempt state-level plastic restrictions. |
Research Methodology
A standing panel of brand managers at organic formulators, category buyers at German discounters, supply planners at tree nut processors, and regulatory affairs leads provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against FDA nutrition labeling guidance, EFSA novel food authorization databases, USDA organic certification records, and Nielsen retail audit data. Bottom-up volume modeling and top-down value triangulation anchored forecast outputs.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, form, ingredient source, and distribution channel, with regional regulatory cluster as cross-cutting variable. CAGRs derived from demand elasticity analysis, substitution rate assumptions, and channel penetration curves. Forecast inputs incorporated flexitarian demographic expansion, clean-label certification adoption rates, and convenience channel format development.
Decision-makers should treat outputs as directional under assumptions of sustained organic certification demand and stable EFSA enforcement posture; material deviation would warrant model refresh. Specific risk factors include almond price spikes from California drought cycles, Peruvian quinoa export restrictions, and accelerated novel food authorization timelines. Revision becomes warranted when adaptogen enforcement intensity or precision fermentation cost curves cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Vegan Dressing Market
Specialty Foods
Cultures Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Silver Food Market
Specialty Foods
Manuka Honey Market
Specialty Foods
Global Pine Pollen Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Poke Food Market
Specialty Foods
Curculin Market
Specialty Foods
Free-From Food Market
Specialty Foods
Acacia Honey Market