
 High Fiber Snack Foods Market | 2026-2036
High Fiber Snack Foods Market Size, Share, and Industry Trends Forecast 2026-2036
High Fiber Snack Foods Market Analytics
Asset-light co-manufacturing partnerships is tilting competitive dynamics toward brands that outsource production while retaining formulation control. General Mills leverages its in-house R&D infrastructure to sustain fiber fortification leadership across multiple snack formats. KIND Snacks competes through premium ingredient sourcing, while Quest Nutrition differentiates via protein-fiber hybrid positioning in performance nutrition channels.
High fiber snack foods contain minimally processed ingredients delivering dietary fiber content typically exceeding three grams per serving, manufactured through extrusion baking, cold-pressing, or oven-toasting methods that preserve structural integrity and nutritional density. These products serve consumers seeking satiety management and digestive health benefits without sacrificing convenience. Bars formulated with whole grains and nuts currently anchor the highest margin pool due to premium price positioning and clean-label premiums, while legume-based chips represent the fastest-expanding segment as savory alternatives displace conventional potato chips. Pouch packaging dominates velocity-driven channels, though box formats sustain stronger household penetration in club retail.
The FDA's updated Nutrition Facts panel and serving-size standards reshape fiber declaration requirements for US market participants, while EFSA health claim frameworks in Europe govern permissible digestive wellness messaging on front-of-pack labels. FSSAI fortification guidelines in India create compliance thresholds for imported and domestically produced fiber-enhanced snacks. Stakeholders must monitor evolving glycemic index disclosure mandates and emerging upcycled fiber ingredient approvals that could redraw cost structures and permitted health claims across priority markets.
Market Dynamics
Clean-label reformulation mandates and front-of-pack fiber disclosure requirements are forcing manufacturers to restructure ingredient sourcing and production workflows across priority markets.
Growth Catalysts
- EFSA Health Claim Frameworks:Permissible digestive wellness messaging on European packaging accelerates consumer trial and premium price realization for fiber-fortified formats.
- Corporate Wellness Program Expansion:Employer-sponsored healthy snacking initiatives in the United States and Germany institutionalize bulk procurement of high-fiber options.
- Extrusion Baking Advancement:Improved processing equipment preserves structural integrity of whole grain matrices, enabling cleaner ingredient decks without sacrificing shelf stability.
Market Restraints
- Input Cost Volatility:Chicory root fiber and resistant starch prices fluctuate with agricultural yield cycles, compressing margin pools for mid-tier producers.
- Supply Concentration Risk:Premium nut and ancient grain sourcing clusters in California and the Mediterranean basin expose brands to climate disruption.
- FSSAI Fortification Thresholds:India's compliance requirements for imported fiber-enhanced snacks create documentation friction and extended clearance timelines.
Strategic Opportunities
- Upcycled Fiber Ingredient Approvals:Emerging regulatory pathways for agricultural byproduct fibers in the European Union and United States unlock cost-advantaged raw material streams.
- Club Retail Box Formats:Household penetration in Costco and Sam's Club channels remains underdeveloped relative to pouch velocity in convenience stores.
- Glycemic Index Disclosure Mandates:Anticipated labeling requirements in key markets create first-mover advantage for brands with validated low-GI formulations.
Industry Challenges
- Clean-Label R&D Talent Scarcity:Formulation chemists skilled in natural fiber integration without synthetic binders command premium compensation and limited availability.
- Multi-Jurisdiction Compliance Parallelism:Simultaneous navigation of FDA serving-size standards, EFSA claim frameworks, and emerging Asian market requirements strains regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Fiber Snack Foods Market |
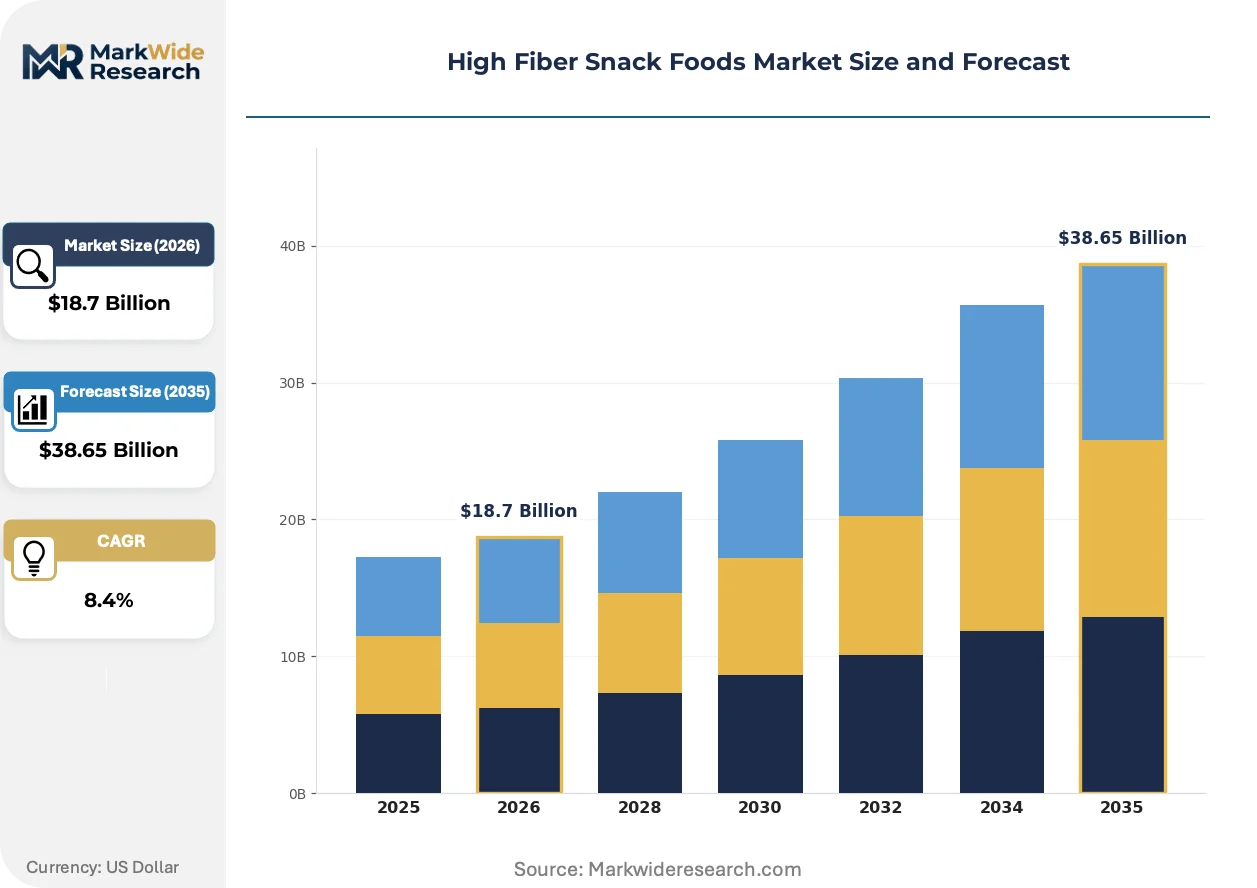
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Bars, Crackers, Cookies Ingredient Type: Whole Grains, Legumes, Nuts, Seeds Flavor Profile: Spicy, Sweet, Savory, Herbal Packaging Type: Bags, Boxes, Pouches, Tubs |
| Companies Covered | General Mills, Kellogg Company, PepsiCo, Nestle, Flowers Foods, Ardent Mills, KIND Snacks, Clif Bar & Company, Quest Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Fiber Snack Foods Market Evolving Landscape
Processing technology convergence and disclosure mandate proliferation are compressing traditional competitive advantages while elevating transparency and traceability as differentiation vectors.
Cold-pressing technology for nut and seed bars is collapsing the cost gap between artisanal small-batch production and scaled manufacturing. Regional craft brands in Germany and the Pacific Northwest adopt this equipment to enter national retail without co-manufacturer dependency. The technology is collapsing minimum efficient scale thresholds, fragmenting volume concentration historically held by extrusion-dominant multinationals.
EU Green Deal packaging requirements and extended producer responsibility frameworks force fiber snack manufacturers to eliminate multi-layer flexible films. Brands serving German and French markets accelerate investment in mono-material pouches and paper-based barriers. The regulation compresses allowable packaging formats, privileging early movers with validated recyclable structures.
Direct-to-subscription models for personalized fiber nutrition are displacing conventional retail trial in urban millennial and Gen Z cohorts. Quarterly replenishment algorithms based on microbiome testing data gain traction in San Francisco, London, and Singapore wellness circles. The channel shift concentrates lifetime value capture with brands that integrate diagnostic hardware partnerships.
High Fiber Snack Foods Market Segmentation
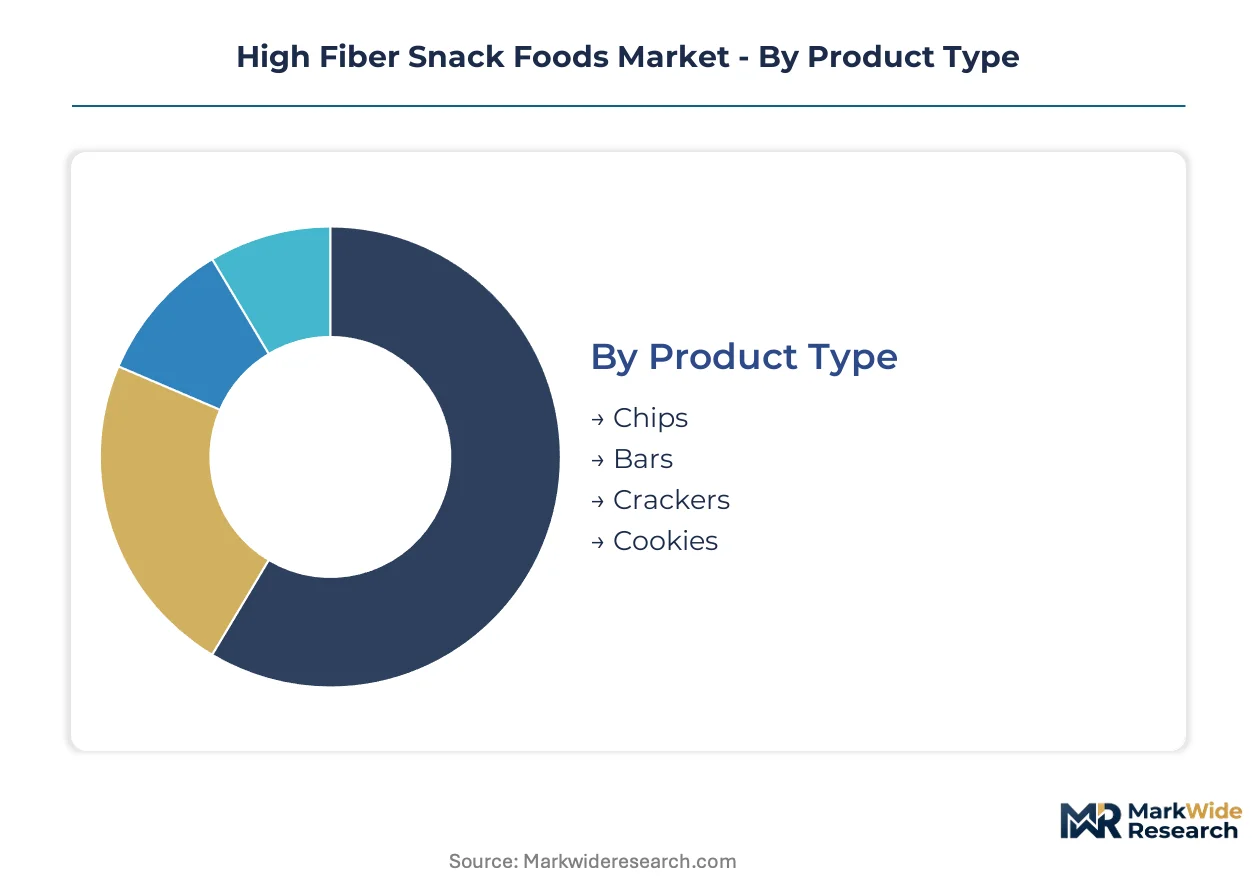
High fiber snack foods demand fragments across distinct consumption occasions, ingredient preferences, and retail formats. Understanding these divides reveals where margin pools concentrate and which technical specifications unlock shelf placement.
Product Type:
Consumption occasions span energy management, savory cravings, and social sharing moments with divergent texture and portability requirements.
- Bars:Dense matrices of whole grains, nuts, and binders deliver sustained satiety for meal replacement and post-workout recovery. Corporate wellness programs in the United States and Germany anchor bulk procurement contracts, though clean-label R&D costs compress mid-tier producer margins.
- Chips:Extruded or baked legume and grain formulations displace conventional potato chips in savory snacking occasions. Urban millennials in China drive velocity through convenience store channels seeking permissible indulgence with digestive benefits.
- Crackers:Oven-toasted whole grain platforms serve cheese pairing and standalone snacking with lower per-unit price points than bars.
- Cookies:Resistant starch and chicory root fiber fortification targets permissible dessert occasions with reduced glycemic impact.
The dominant share belongs to Bars, while Chips is closing the gap fastest.
Ingredient Type:
Raw material selection determines fiber density claims, allergen exposure, and supply chain vulnerability to climate disruption.
- Whole Grains:Oats, quinoa, and ancient wheat varieties provide structural integrity and beta-glucan content for digestive health positioning. Mediterranean basin sourcing clusters expose brands to drought risk, accelerating California and Canadian supplier qualification.
- Legumes:Chickpea, lentil, and pea protein isolates enable savory extrusion with complete amino acid profiles. German and Dutch ingredient technology suppliers dominate processing equipment partnerships for scaled production.
- Nuts:Almond, cashew, and hazelnut inclusions command premium price realization with clean-label appeal.
- Seeds:Chia, flax, and pumpkin seed integration targets omega-3 and lignan co-positioning in functional wellness channels.
Whole Grains retains volume leadership, though Legumes shows the steepest expansion trajectory as savory alternatives gain share.
Flavor Profile:
Taste architecture must reconcile health halo expectations with sensory satisfaction thresholds that drive repeat purchase.
- Savory:Sea salt, cheese, and umami blends dominate chip and cracker formats with lower sugar content than alternatives. Chinese urban retail channels show particular velocity for seaweed and Sichuan peppercorn variants.
- Sweet:Date paste, monk fruit, and stevia formulations balance glycemic management with dessert occasion permissibility. EFSA health claim frameworks restrict permissible sweetness-related messaging on European packaging.
- Spicy:Capsaicin and chili-infused variants target younger cohorts in United States and Southeast Asian markets.
- Herbal:Rosemary, turmeric, and adaptogen inclusions serve premium wellness positioning with anti-inflammatory co-claims.
Savory commands the largest addressable base, while Sweet narrows the gap through permissible indulgence reformulation.
Packaging Type:
Format selection governs shelf stability, portion control signaling, and compliance with EU Green Deal extended producer responsibility mandates.
- Pouches:Multi-layer flexible films dominate convenience store velocity with single-serve portioning, though mono-material alternatives are displacing legacy structures under French and German regulatory pressure.
- Boxes:Rigid formats sustain household penetration in Costco and Sam's Club channels with multi-serve economics and stronger brand billboard presence.
- Bags:Stand-up and pillow configurations serve club retail and grocery perimeter placement with intermediate volume scales.
- Tubs:Rigid containers anchor bulk snacking and foodservice portioning with resealability for extended consumption windows.
Pouches generate the highest channel velocity, yet Boxes is gaining share fastest through club retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serving-size standards and EFSA health claim frameworks are reshaping fiber declaration requirements across priority markets, while corporate wellness programs and clean-label mandates accelerate category expansion in urban retail channels.
United States
Corporate wellness programs in Fortune 500 companies institutionalize bulk procurement of fiber-fortified bars and chips. The FDA's updated Nutrition Facts panel forces reformulation of legacy products to meet revised fiber declaration thresholds. Minneapolis and Chicago anchor co-manufacturing clusters where extrusion baking capacity serves both established brands and emerging private-label entrants.
Germany
EU Green Deal packaging requirements drive mono-material pouch adoption ahead of extended producer responsibility deadlines. EFSA digestive wellness claim frameworks permit specific gut health messaging that accelerates consumer trial and premium price realization. Bavaria and Baden-Württemberg concentrate cold-pressing equipment manufacturing for regional craft brands entering national retail.
China
Urban millennials in Shanghai and Beijing drive velocity for savory legume-based chips through convenience store channels seeking permissible indulgence. SAMR labeling standards govern permitted functional claims on imported fiber-enhanced snacks. The Yangtze River Delta hosts extrusion technology suppliers serving both domestic brands and export-oriented producers.
India
FSSAI fortification guidelines create compliance thresholds for imported and domestically produced fiber-enhanced snacks, extending clearance timelines for foreign entrants. Maharashtra and Gujarat anchor ancient grain sourcing clusters where drought risk accelerates supplier qualification in Punjab and Haryana. Mumbai and Delhi-NCR concentrate direct-to-consumer subscription trials targeting microbiome-conscious professionals.
United Kingdom
Post-Brexit divergence from EU labeling frameworks creates parallel compliance obligations for brands serving both markets. London wellness circles drive adoption of personalized fiber nutrition subscriptions with quarterly replenishment algorithms. The Midlands host oven-toasted cracker manufacturing serving club retail channels across Northern England and Scotland.
High Fiber Snack Foods Market Competitive Landscape
On the supply side, the industry is consolidating around asset-light co-manufacturing partnerships that tilt competitive dynamics toward brands retaining formulation control while outsourcing production. Three strategic archetypes dominate: multinational CPG conglomerates with captive R&D infrastructure, premium ingredient-sourcing specialists, and protein-fiber hybrid positioning players in performance nutrition channels. Dominant competitive moves include vertical integration into ancient grain sourcing and strategic partnerships with microbiome testing platforms for subscription channel capture.
Within the multinational conglomerate tier, General Mills and Kellogg Company exemplify scale-driven players leveraging in-house R&D infrastructure across multiple snack formats. Among premium-positioned specialists, KIND Snacks occupies a position anchored in clean-label ingredient sourcing. These three companies represent distinct competitive vectors: formulation control at scale, premium sourcing credibility, and hybrid functional positioning.
| Leading Market Players |
|---|
| General Mills |
| Kellogg Company |
| PepsiCo |
| Nestle |
| Flowers Foods |
| Ardent Mills |
| KIND Snacks |
| Clif Bar & Company |
| Quest Nutrition |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from California ports to Shanghai anchor cost dynamics for chicory root fiber and resistant starch shipments, compressing margin pools for mid-tier producers while enabling premium price realization for brands with validated low-glycemic formulations and EFSA-compliant packaging.
Pricing Analysis
Certification level (FDA-grade fiber fortification, EFSA health claim validation) creates the primary spread between premium and economy tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by clean-label ingredient density and front-of-pack claim permissibility. Cost compression in the standard tier is intensifying because chicory root fiber spot prices fluctuate with agricultural yield cycles. Corporate wellness procurement managers show lowest price sensitivity, while convenience store distributors exhibit highest elasticity.
Supply Chain Analysis
Export-control regimes on extrusion baking equipment limit technology transfer to Indian and Chinese domestic producers, concentrating advanced processing capacity in German and US manufacturing clusters. Raw material flows draw from Mediterranean basin nut and ancient grain suppliers, California legume processors, and Canadian oat milling operations. Single-source vulnerability clusters in drought-exposed Mediterranean sourcing regions threaten continuity. Distribution runs through club retail box formats and convenience store pouch velocity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates and EU Green Deal packaging requirements are compressing traditional competitive advantages, creating first-mover rewards for brands with validated recyclable structures and microbiome-integrated subscription capabilities.
For Market Incumbents: Build formulation IP moats through captive R&D infrastructure for natural fiber integration without synthetic binders. Deepen backward integration into California and Canadian ancient grain sourcing to mitigate Mediterranean drought exposure. Secure exclusive co-manufacturing partnerships with extrusion baking specialists in Minneapolis and Chicago clusters. For New Entrants and Emerging Players: Build out white-space penetration in India direct-to-consumer subscription channels targeting microbiome-conscious professionals in Mumbai and Delhi-NCR. Exploit underdeveloped club retail box format placement relative to pouch velocity saturation. Lead with personalized fiber nutrition algorithms paired with diagnostic hardware partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cold-pressing equipment manufacturers serving regional craft brands in Germany and the Pacific Northwest. Long-term viability hinges on regulatory navigation capacity across FDA, EFSA, and FSSAI frameworks. Monitor upcycled fiber ingredient approval pathways in the European Union and United States as inflection signals for cost-advantaged raw material streams.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Pouch Transition | EU Green Deal extended producer responsibility deadlines in Germany and France compress allowable packaging formats. |
| Microbiome Testing Platform Partnership | Direct-to-subscription models in San Francisco and London wellness circles concentrate lifetime value capture. |
| Upcycled Fiber Ingredient Sourcing | Agricultural byproduct fiber approvals unlock cost-advantaged raw material streams for premium positioning. |
| Cold-Pressing Equipment Investment | Technology adoption collapses minimum efficient scale thresholds for regional craft brands entering national retail. |
| Corporate Wellness Program Contracting | Fortune 500 bulk procurement in the United States and Germany institutionalizes high-fiber snacking volume. |
Research Methodology
Desk research of FDA guidance documents, EFSA health claim registers, and FSSAI fortification guidelines preceded structured interviews with brand managers, category buyers at club retailers, extrusion equipment manufacturers, and supply chain planners at ingredient suppliers. Secondary validation drew from customs trade data, Nielsen retail audit records, and corporate wellness program procurement disclosures. Bottom-up volume estimates triangulated against top-down category spending analysis.
Assumptions held fixed include prevailing regulatory frameworks across the analysis window, baseline corporate wellness program penetration rates, and established cold-pressing equipment cost curves. Variables stress-tested included agricultural yield volatility for chicory root fiber, drought frequency in Mediterranean sourcing basins, and pace of mono-material packaging adoption. Segmentation modeling spanned product format, ingredient type, flavor architecture, and channel format across geographic clusters.
Stress conditions across input cost volatility, regulatory approval timelines, and channel shift velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and baseline conditions. Material shifts in EFSA health claim framework interpretations or FDA serving-size standard enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Sweet Potato Fries Market
Snacks
Popcorn Market
Snacks
South America Snack Bar Market
Snacks
Energy Bar Market
Snacks
Packaged Rice Snacks Market
Snacks
Fruit and Vegetable Chips Market
Snacks
Saudi Arabia French Fries Market
Snacks
Vegan Snacks Market
Snacks
Super Low Calorie Snacks Market
Snacks
No Fat Snacks Market
Snacks
Germany Energy Bar Market
Snacks
Extruded Cereals Market
Snacks
Asia-Pacific Popcorn Market
Snacks
Snack Subscription Market
Snacks
Protein Bars Market
Snacks
Saudi Arabia Snack Bar Market