
 Low Fat Hummus Market | 2026-2036
Low Fat Hummus Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Hummus Market Analytics
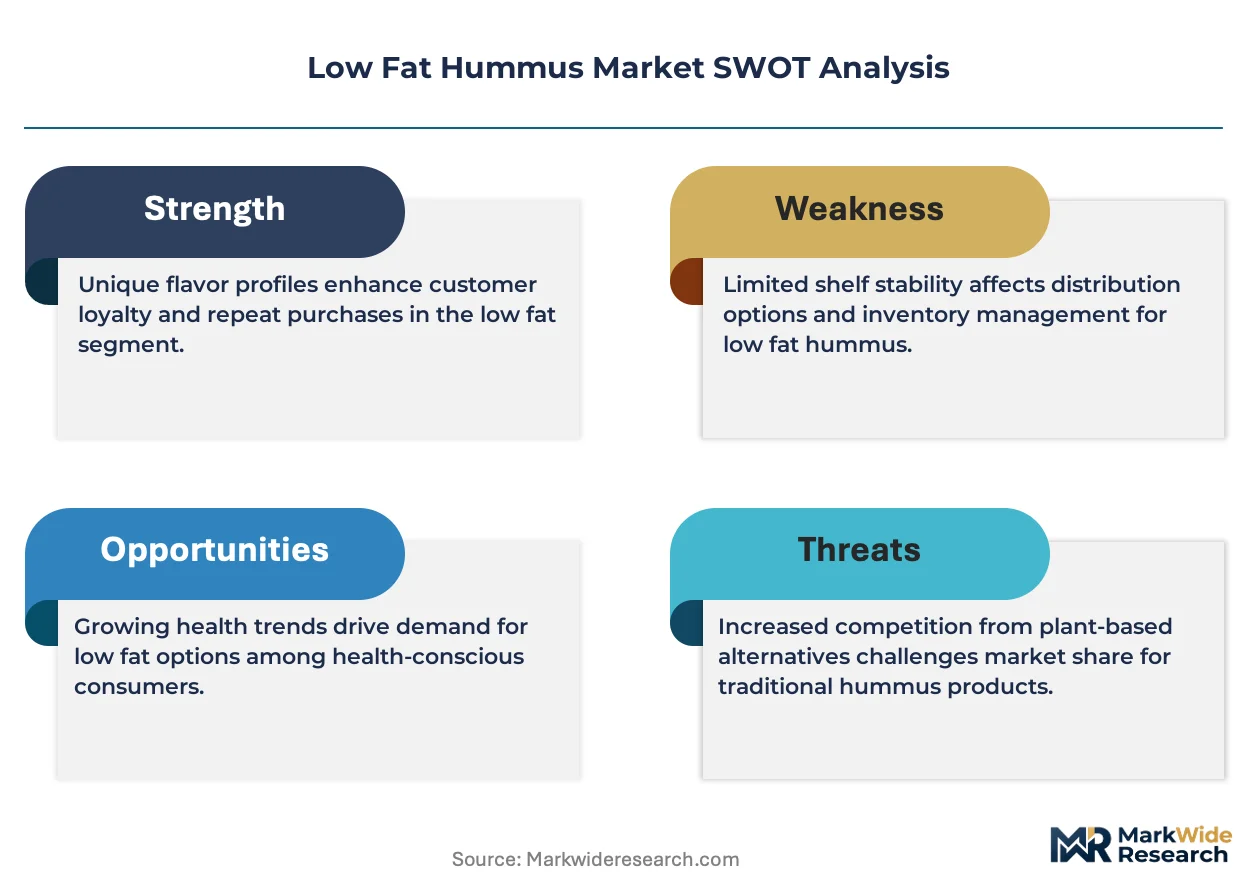
Mediterranean co-manufacturers in Lebanon and Israel is recalibrating tahini sourcing to offset sesame price volatility. PepsiCo, Inc. (Sabra Dipping Company) leverages its refrigerated supply chain dominance across North American club stores. Strauss Group anchors premium positioning through single-serve portfolio depth. Cedar's Mediterranean Foods Inc. specializes in clean-label formulations that command shelf space in US Northeast independents.
Low fat hummus denotes a chickpea-tahini emulsion containing reduced vegetable oil or tahini content, typically achieving under 3 grams of fat per 28-gram serving through modified grind ratios and partial aquafaba substitution; it functions as a refrigerated dip and sandwich spread for calorie-controlled diets. Classic formulations still occupy the largest volume share, though roasted red pepper variants generate disproportionate margin due to ingredient premiumization. Pouch packaging is displacing rigid tubs in European convenience channels, while health stores represent the fastest-growing distribution node for organic-certified SKUs.
The FDA governs nutrition labeling accuracy for low fat claims under 21 CFR 101.62, while the USDA Organic seal shapes premium tier access; in Europe, EFSA health claim restrictions limit fat-reduction messaging on pack. Stakeholders must monitor whether dual-certification requirements for organic and low-fat positioning will consolidate supplier bases or fragment private-label sourcing further.
Market Dynamics
EU Green Deal packaging mandates are compressing rigid tub formats while tahini price volatility forces reformulation strategies across Mediterranean supply chains.
Growth Catalysts
- Clean-label certification:USDA Organic seal access unlocks premium shelf placement in US health stores and Northeast independent grocers.
- Aquafaba substitution technology:Modified grind ratios incorporating chickpea brine reduce fat content without emulsion breakdown.
- German refrigerated channel expansion:Health-conscious households in Berlin and Munich are accelerating chilled dip purchase frequency.
Market Restraints
- Sesame input cost volatility:Lebanese and Israeli tahini suppliers face price instability from climate-impacted sesame harvests.
- EFSA health claim restrictions:European fat-reduction messaging on pack faces strict pre-approval requirements.
- Classic formulation dominance:Traditional high-fat recipes retain volume share due to entrenched consumer taste preferences.
Strategic Opportunities
- Spanish retail corridor penetration:Mediterranean-adjacent convenience channels in Barcelona and Valencia show underdeveloped low-fat SKU presence.
- Recyclable pouch formats:EU Green Deal mandates create first-mover advantage for compliant packaging transitions.
- Single-serve portfolio depth:Portion-controlled packaging aligns with calorie-controlled diet trends in urban French markets.
Industry Challenges
- Dual-certification complexity:Simultaneous organic and low-fat positioning requires fragmented supplier audits and extended compliance timelines.
- Refrigerated supply chain capex:Cold-chain infrastructure investments strain mid-tier manufacturers expanding club store distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Hummus Market |
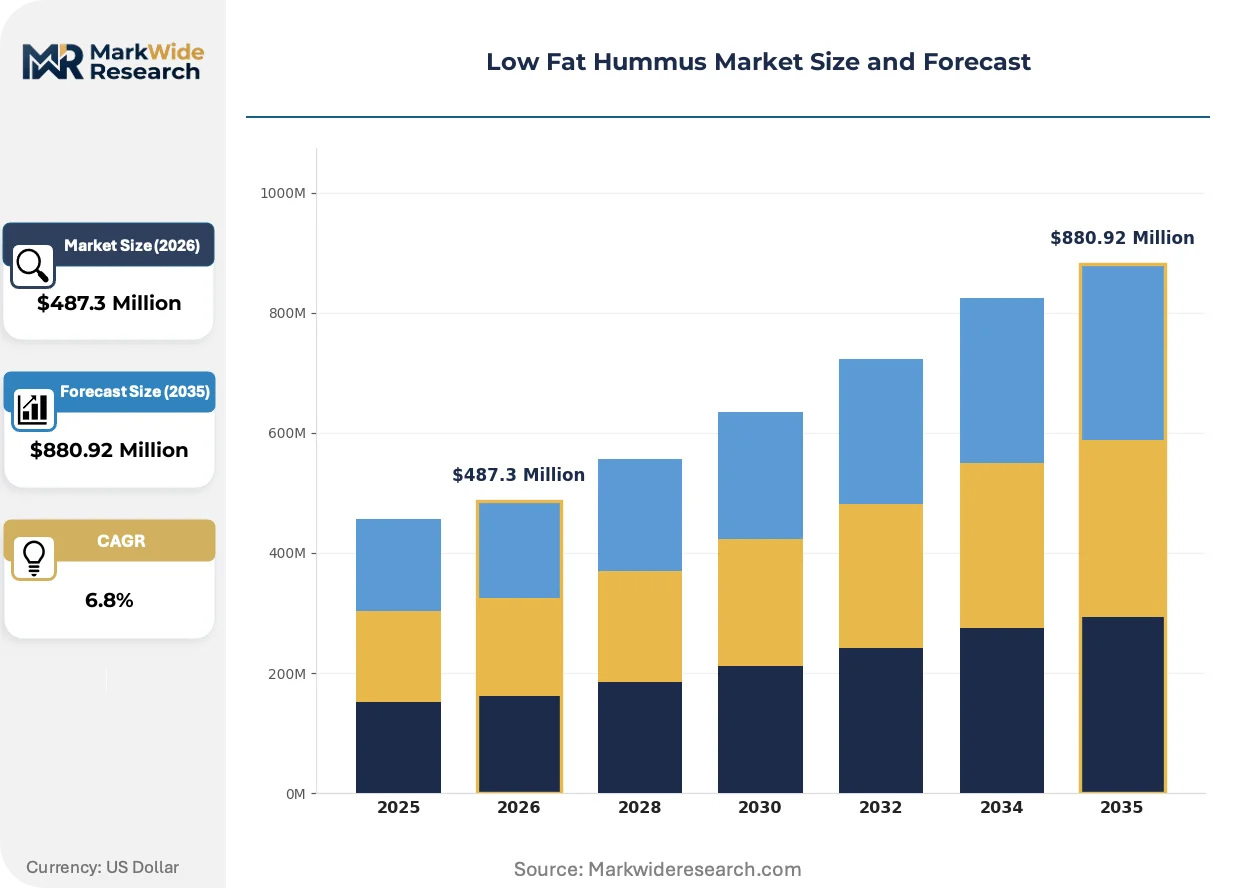
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Classic, Spicy, Garlic, Roasted Red Pepper Packaging Type: Tubs, Sachets, Pouches, Jars Distribution Channel: Supermarkets, Online Retailers, Health Stores, Specialty Shops End User: Restaurants, Caterers, Households, Food Service Operations |
| Companies Covered | PepsiCo, Inc. (Sabra Dipping Company), Groupe Savencia, Lakeview Farms (Tribe Hummus), Cedar's Mediterranean Foods Inc., Boar's Head Provision Co., Inc., Hope Foods, Strauss Group, Bakkavor Group Plc, Haliburton International Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Hummus Market Evolving Landscape
Reformulation science and packaging substrate shifts are redefining competitive advantage while regulatory labeling constraints reshape marketing architecture.
Aquafaba-based emulsion technology is absorbing the functional role of reduced tahini content in fat-controlled formulations. Health-conscious buyers in German and French supermarkets are adopting these reformulated SKUs at accelerated rates. The technology is absorbing margin pressure from sesame price volatility while maintaining mouthfeel parity with traditional recipes.
EFSA health claim pre-approval requirements are tightening fat-reduction messaging permissions across European markets. Manufacturers must submit clinical evidence packages before displaying reduced-fat benefits on pack. Greek and Spanish exporters targeting EU-wide distribution are reformulating labels to emphasize ingredient provenance rather than explicit health claims.
Club store procurement consolidation is compressing supplier negotiation cycles and demanding exclusive SKU configurations. North American refrigerated dip buyers are shifting volume commitments toward vertically integrated manufacturers with captive chickpea sourcing. This concentration is most visible in Northeast US independent grocery networks where shelf space allocation favors multi-certification suppliers.
Low Fat Hummus Market Segmentation
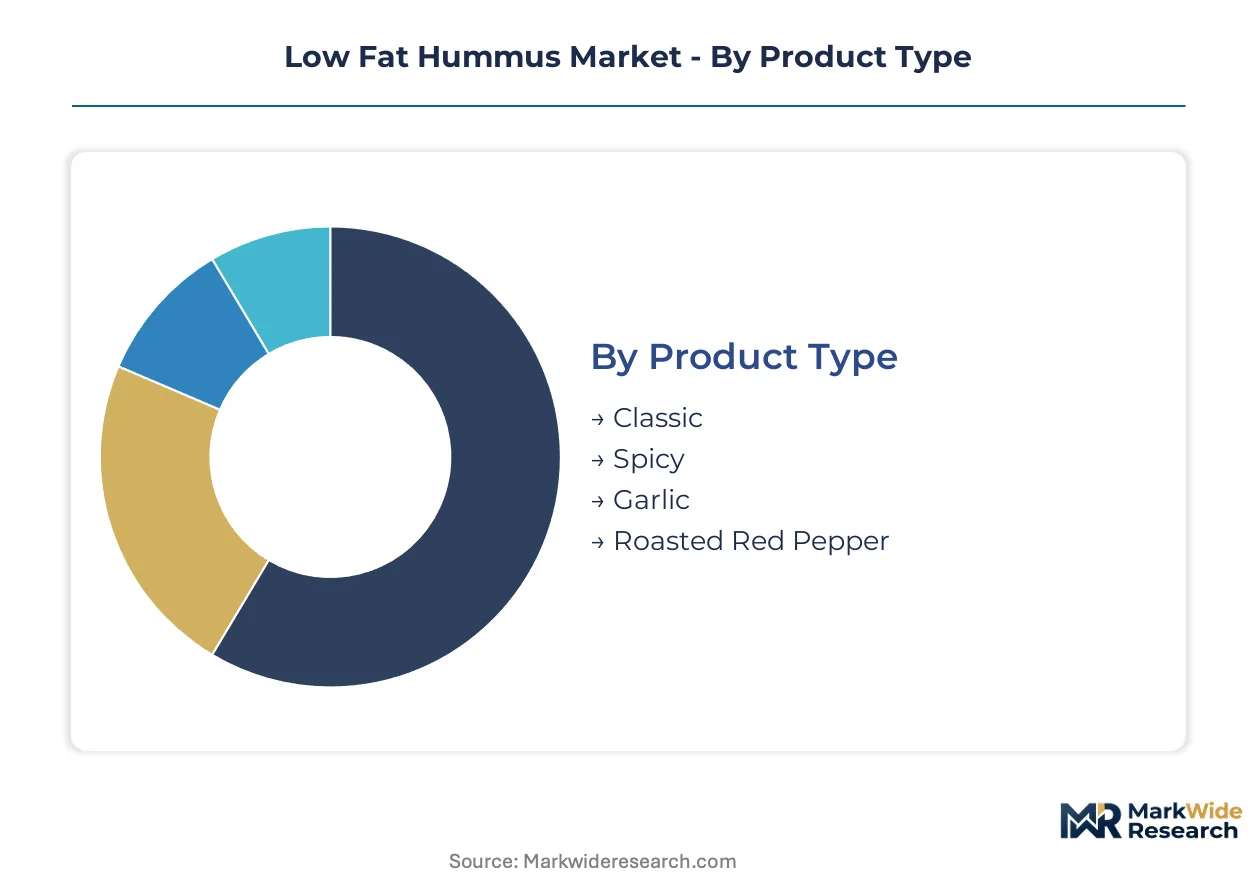
Low fat hummus producers calibrate formulation, packaging, and channel strategies against divergent margin profiles and regulatory exposure. Segmentation reveals where aquafaba substitution technology commands premium pricing versus where classic formulations retain volume dominance through entrenched taste preferences.
Product Type:
Flavor profiles anchor the technical differentiation axis, with grind ratios and ingredient premiums determining fat-reduction feasibility.
- Classic:Traditional chickpea-tahini emulsion with minimal aquafaba substitution maintains mouthfeel parity for conservative palates. Households in Mediterranean-adjacent retail corridors across Spain and Greece drive volume concentration despite higher fat content.
- Roasted Red Pepper:Vegetable puree integration enables partial oil displacement while commanding ingredient premiumization. Health stores represent the fastest-growing distribution node for this SKU due to clean-label positioning and visual differentiation.
- Spicy:Chili or harissa inclusions mask texture modifications from reduced tahini content. Demand concentrates in urban French markets seeking flavor intensity without caloric penalty.
- Garlic:Pungent aromatics offset leaner mouthfeel from aquafaba-heavy formulations. German refrigerated channel expansion favors this variant in Berlin and Munich supermarket sets.
Mature deployment sits with Classic. Newer deployment is concentrated in Roasted Red Pepper.
Packaging Type:
Substrate selection determines cold-chain compatibility and EU Green Deal compliance exposure across convenience versus retail channels.
- Pouches:Flexible films with recyclable laminates meet EU Green Deal mandates while reducing refrigerated freight cube. Barcelona and Valencia convenience channels show underdeveloped presence, creating first-mover openings.
- Tubs:Rigid polypropylene formats face compression from sustainable packaging regulations despite superior shelf stability. Club store procurement consolidation in North America still favors this configuration for bulk SKUs.
- Sachets:Single-serve portions align with calorie-controlled diet trends in urban French markets. Strauss Group anchors premium positioning through portfolio depth in this format.
- Jars:Glass containers retain organic-certified SKU placement in US Northeast independents where clean-label formulations command shelf space. Cedar's Mediterranean Foods Inc. specializes in this packaging tier.
Volume leadership belongs to Tubs. Steepest expansion trajectory is concentrated in Pouches.
Distribution Channel:
Channel selection governs certification requirements and pricing architecture, with organic and low-fat dual-positioning fragmenting supplier bases differently across each node.
- Health Stores:USDA Organic seal access unlocks premium placement for reformulated SKUs with aquafaba substitution technology. This channel absorbs margin pressure from sesame price volatility through consumer willingness to pay for certification.
- Supermarkets:Mainstream refrigerated sets in Germany and France are accelerating chilled dip purchase frequency among health-conscious households. EFSA health claim restrictions limit fat-reduction messaging on pack, forcing ingredient provenance emphasis.
- Online Retailers:Direct-to-consumer fulfillment bypasses shelf space allocation constraints but demands extended cold-chain infrastructure investments. Mid-tier manufacturers face strained capex requirements for this channel.
- Specialty Shops:Mediterranean import-focused independents in US Northeast corridors favor Cedar's Mediterranean Foods Inc. clean-label formulations with multi-certification credentials.
Established presence sits with Supermarkets. Emerging concentration is visible in Health Stores.
End User:
Food service versus retail demand splits on portion control requirements and formulation consistency specifications.
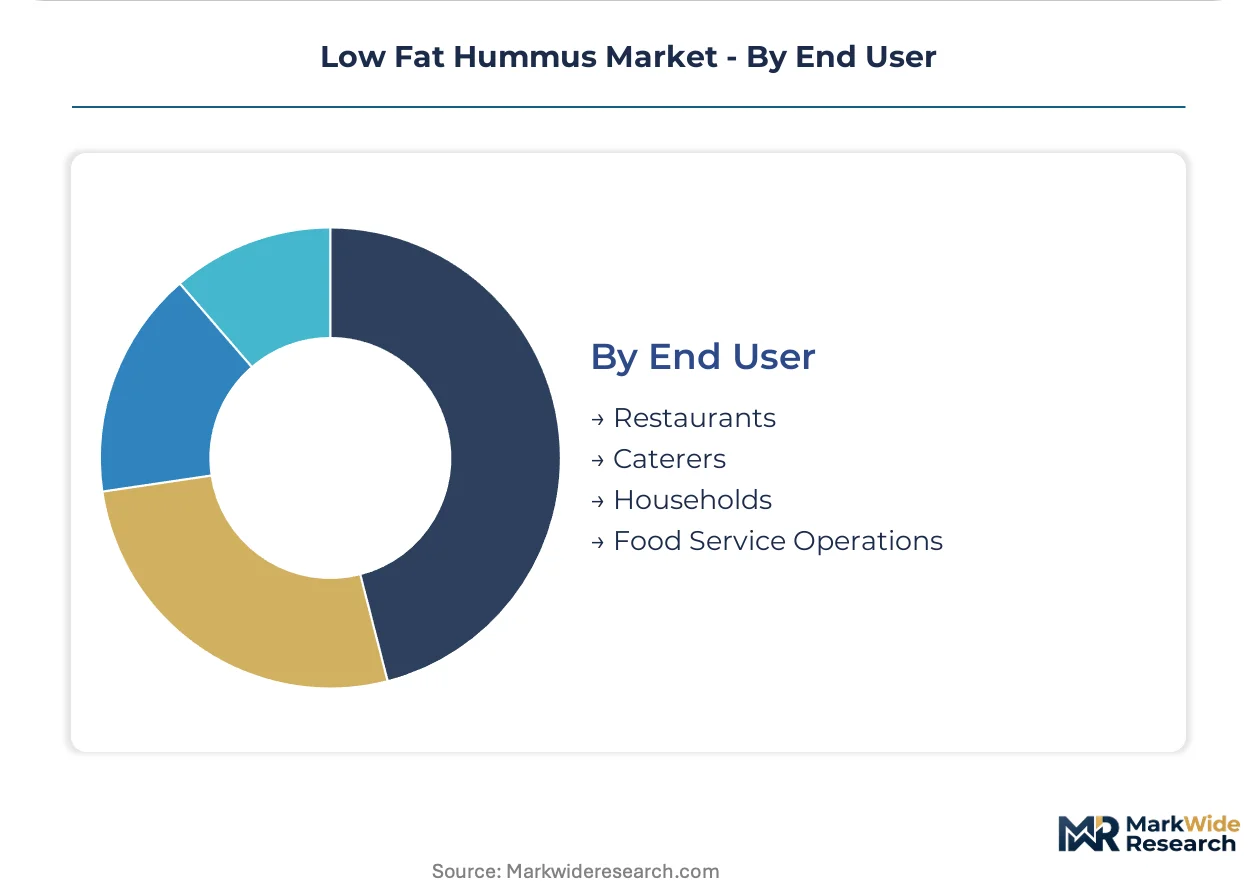
- Households:Calorie-controlled diet trends in urban French and German markets drive refrigerated dip purchase frequency. Single-serve portfolio depth from Strauss Group captures this segment's premium orientation.
- Restaurants:Consistent emulsion stability requirements favor traditional high-fat recipes due to entrenched taste preferences among culinary professionals. Classic formulation dominance persists here.
- Food Service Operations:Bulk procurement contracts demand vertically integrated manufacturers with captive chickpea sourcing. PepsiCo leverages refrigerated supply chain dominance across North American club stores for this end user.
- Caterers:Event-based volume spikes require flexible pouch formats for portion-controlled service. EU Green Deal mandates accelerate transitions away from rigid tub configurations in this segment.
Volume concentration sits with Households. Operational complexity concentrates in Food Service Operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sesame cultivation belts in Ethiopia and Sudan anchor tahini supply chains that feed Mediterranean processing clusters. Refrigerated distribution networks in Western Europe and North America determine market access for finished low-fat hummus products.
United States
Health-conscious households in the Northeast corridor drive refrigerated dip purchase frequency through independent grocers. The FDA enforces nutrition labeling accuracy for low-fat claims under 21 CFR 101.62. Cedar's Mediterranean Foods Inc. commands shelf space in Boston and New York metro independents through clean-label formulations.
Germany
Berlin and Munich supermarkets are accelerating chilled hummus adoption among calorie-controlled diet followers. EU Green Deal packaging mandates compress rigid tub formats in favor of recyclable laminates. Bavarian retail corridors show expanding SKU presence for aquafaba-substituted variants.
France
Urban Parisian markets favor single-serve portion control aligned with premium positioning strategies. EFSA health claim restrictions limit explicit fat-reduction messaging on pack. Strauss Group anchors its European presence through portfolio depth in Île-de-France convenience channels.
Spain
Mediterranean-adjacent retail corridors in Barcelona and Valencia show underdeveloped low-fat SKU penetration relative to classic formulations. Spanish organic certification requirements create dual-compliance complexity for exporters. Andalusian processing clusters supply chickpea inputs to reformulation facilities.
Israel
Lebanese and Israeli tahini suppliers face sesame price volatility from climate-impacted harvests. The country's national food safety regulator enforces strict emulsion stability standards for refrigerated exports. Tel Aviv-area co-manufacturers are recalibrating sourcing strategies to offset input cost pressure.
Low Fat Hummus Market Competitive Landscape
Global majors compete with regional champions across refrigerated supply chain dominance and clean-label certification depth. The vendor base stratifies between vertically integrated conglomerates with captive chickpea sourcing and specialized Mediterranean-formulation independents. Three archetypes dominate: multinational CPG platforms leveraging club store procurement consolidation; regional specialists commanding Northeast US independent grocery networks; and Israeli-based premium-positioned portfolio builders. Competitive moves concentrate on M&A for cold-chain infrastructure and exclusive SKU configurations for club store buyers.
Among multinational CPG platforms, PepsiCo, Inc. (Sabra Dipping Company) occupies a position exemplifying refrigerated supply chain dominance across North American club stores. Strauss Group and Cedar's Mediterranean Foods Inc. represent the specialist tier, with the former anchoring premium single-serve positioning and the latter exemplifying clean-label formulation focus in US Northeast independents. These three entities illustrate how scale, specialization, and regional certification depth create defensible positioning against mid-tier private-label encroachment.
| Leading Market Players |
|---|
| PepsiCo, Inc. (Sabra Dipping Company) |
| Groupe Savencia |
| Lakeview Farms (Tribe Hummus) |
| Cedar's Mediterranean Foods Inc. |
| Boar's Head Provision Co., Inc. |
| Hope Foods |
| Strauss Group |
| Bakkavor Group Plc |
| Haliburton International Foods Inc. |
| Others |
Value Network & Pricing Analysis
Sesame price volatility cascades through tahini-dependent formulation tiers, compressing margins in classic SKUs while aquafaba-substituted variants absorb cost pressure through health-store premium positioning. The EU Green Deal's packaging mandates layer compliance premiums onto pouch formats, fragmenting pricing architecture across rigid-tub legacy buyers and sustainable-substrate adopters.
Pricing Analysis
Warranty-equivalent freshness guarantees differentiate club-store bulk SKUs from unbundled convenience-channel sachets. Three-tier pricing structure across premium organic-certified, standard clean-label, and economy private-label levels anchors the market. Price differentiation stems from dual-certification burden and refrigerated freight cube efficiency. Pricing pressure intensifies in classic formulations as tahini input costs spike, while aquafaba variants show resilience. Food service operations exhibit highest price sensitivity; health stores demonstrate lowest.
Supply Chain Analysis
Direct-to-retail refrigerated channels handle German and French supermarket demand, while club-store procurement consolidates North American volume through vertically integrated suppliers. Chickpea sourcing concentrates in Ethiopia, Turkey, and India; tahini production clusters in Lebanon and Israel. Raw material dependencies include sesame seed, chickpea, and aquafaba brine. Single-source vulnerability in Mediterranean tahini suppliers threatens emulsion stability consistency. Distribution runs through cold-chain logistics networks with temperature-controlled last-mile requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal packaging mandates erect a cost-of-compliance moat that consolidates supplier bases around capitalized format-transition specialists, fragmenting private-label entrants unable to absorb dual-certification audit timelines.
For Market Incumbents: Deepen captive chickpea sourcing through backward integration into Andalusian and Ethiopian cultivation belts to offset tahini price volatility. Expand single-serve portfolio depth in urban French markets before format saturation. The threat of mid-tier private-label encroachment demands preemptive shelf-space lock-in through exclusive SKU configurations for club store buyers. For New Entrants and Emerging Players: Aquafaba emulsion technology offers a technology-first wedge into health-store distribution nodes where organic certification barriers filter legacy competitors. Target Spanish Mediterranean-adjacent retail corridors in Barcelona and Valencia where low-fat SKU penetration lags classic formulation dominance. A direct-to-consumer launch bypasses shelf-space allocation constraints while building brand equity for downstream supermarket expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor Israeli-based co-manufacturers with reformulation capabilities and EU export licenses amid sesame input cost turbulence. Long-term viability centers on cold-chain infrastructure ownership and captive sourcing integration. The signal to watch is club-store procurement consolidation velocity as an inflection indicator for mid-tier manufacturer exit pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Aquafaba Substitution Scale-Up | Reduces tahini dependency while maintaining mouthfeel parity for health-conscious German households. |
| Recyclable Pouch Format Transition | EU Green Deal compliance unlocks first-mover advantage in Barcelona and Valencia convenience channels. |
| Single-Serve Portfolio Expansion | Strauss Group's premium positioning in Île-de-France demonstrates calorie-controlled diet alignment. |
| Captive Chickpea Sourcing Integration | PepsiCo's refrigerated supply chain dominance rests on upstream control over North American club store volume. |
| Dual-Certification Compliance Investment | USDA Organic and low-fat positioning fragments supplier bases around Cedar's Northeast independent network. |
Research Methodology
Trade databases, customs records, and refrigerated food industry filings formed the secondary backbone, supplemented by Nielsen retail audit data and EU regulatory documentation. Primary interviews with category buyers at German and French supermarket chains, R&D directors at Mediterranean co-manufacturers, and supply planners at tahini processors grounded qualitative assessment. Bottom-up SKU-level volume builds and top-down category expenditure trends underwent cross-validation.
Historical trendline analysis of refrigerated dip adoption rates across German and French metropolitan corridors informed baseline assumptions. Segmentation dimensions modeled include flavor profile, packaging substrate, distribution channel certification requirements, and end-user portion control needs. CAGRs derived from elasticity-adjusted projection of health-conscious household penetration and aquafaba substitution technology diffusion curves. Input variables incorporated EFSA health claim restriction enforcement intensity and EU Green Deal implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sesame harvest disruption scenarios or accelerated club-store procurement consolidation. Practitioners should monitor tahini price index movements and recyclable laminate substrate cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
Chamomile Market
Specialty Foods
Dog Food Toppers Market
Specialty Foods
Sofrito Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Global Honey Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Edible Cutlery Market