
 Clay Desiccant Bag Market | 2026-2036
Clay Desiccant Bag Market Size, Share, and Industry Trends Forecast 2026-2036
Clay Desiccant Bag Market Outlook
Asset-light leasing arrangements for humidity-controlled warehousing is reconfiguring competitive dynamics in the clay desiccant supply chain, allowing smaller distributors to challenge incumbent volume players without capital-intensive inventory builds. Clariant AG leverages its integrated bentonite mining operations in southern Europe to sustain cost advantages across pharmaceutical-grade product lines. Stream Peak International anchors its position through specialized custom packaging capabilities for electronics OEMs in Southeast Asia. IMPAK Corporation differentiates via stringent in-house testing protocols that exceed standard military specification requirements for industrial desiccant performance.
Clay desiccant bags are moisture-adsorbent pouches composed primarily of natural bentonite or montmorillonite clay, typically achieving equilibrium moisture capacities of 25-30% by weight at 25°C and 50% relative humidity through physical adsorption rather than chemical reaction. These bags serve to protect packaged goods from humidity-induced degradation during storage and transit across pharmaceutical, electronics, and food supply chains. Industrial desiccants dominate volume flows due to bulk procurement patterns across automotive and heavy machinery export packaging, while pharmaceutical desiccants command premium positioning driven by FDA 21 CFR compliance requirements and validated stability data. Custom packages represent the fastest-growing packaging type as OEMs specify exact dimensions, printing, and insertion automation compatibility to reduce line-integration costs.
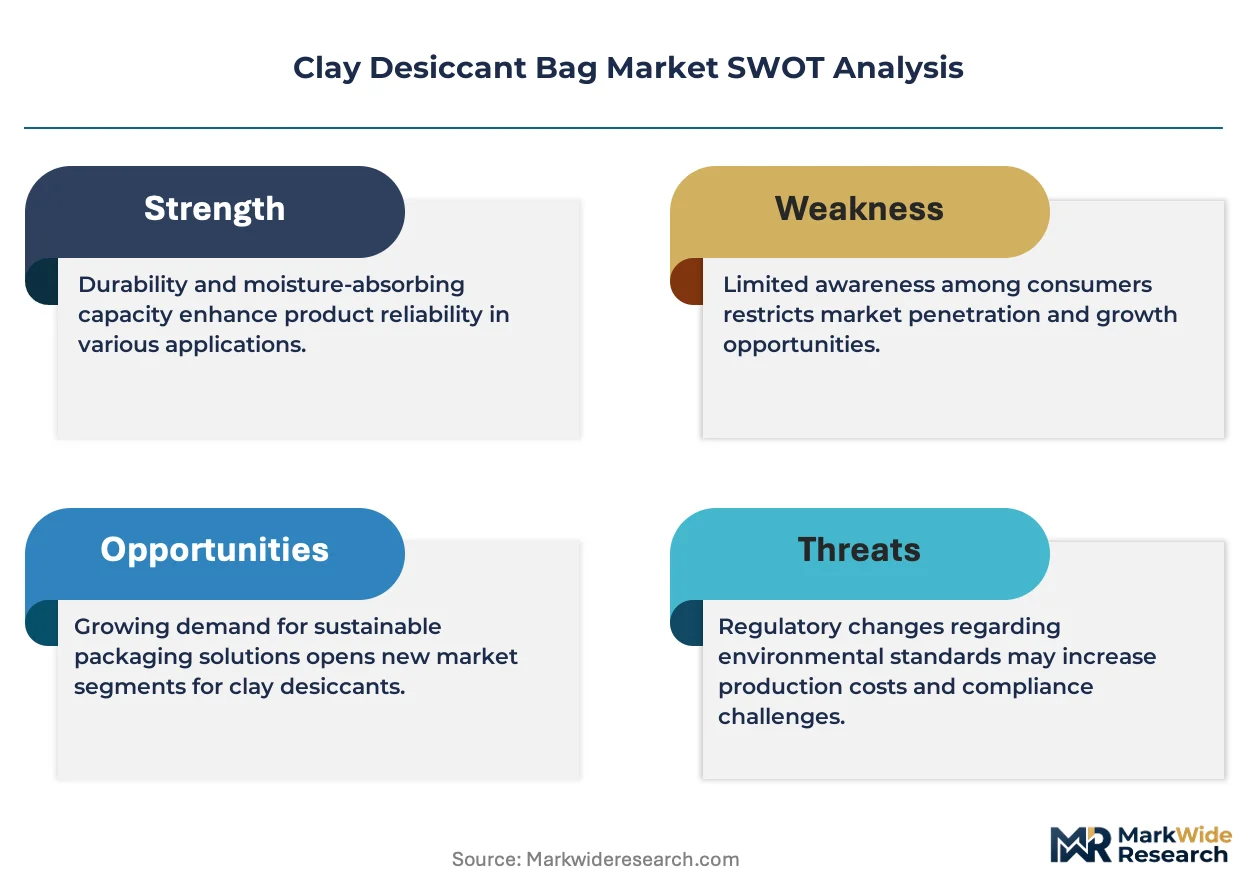
EPA regulations on silica gel disposal classifications are redirecting procurement teams toward clay-based alternatives in US industrial applications, while REACH compliance in Europe mandates full material disclosure for desiccants used in consumer product packaging. China's GB/T standard for packaging desiccants and the FDA's container closure system guidance collectively shape formulation choices, testing protocols, and supplier qualification criteria across major demand centers. Stakeholders must monitor evolving pharmaceutical serialization requirements and their interaction with desiccant insertion automation to anticipate capital allocation priorities.
Market Dynamics
Asset-light leasing models for humidity-controlled warehousing are redistributing bargaining power across the clay desiccant supply chain, allowing regional distributors to challenge volume incumbents without carrying inventory-heavy balance sheets.
Growth Catalysts
- FDA Container Closure System Guidance:Tightened stability testing protocols for moisture-sensitive pharmaceuticals are mandating validated desiccant performance data, pulling clay-based solutions into premium drug packaging applications.
- Electronics Cluster Concentration:Export-oriented manufacturing zones in Guangdong and Jiangsu provinces are driving bulk procurement of industrial-grade montmorillonite bags for semiconductor and component protection during ocean transit.
- EPA Silica Gel Reclassification:Stricter disposal classifications for synthetic desiccants in US industrial applications are redirecting procurement teams toward biodegradable bentonite alternatives with lower environmental compliance burdens.
Market Restraints
- Bentonite Mining Concentration:Captive supply controlled by integrated miners in southern Europe and Wyoming creates input cost volatility for non-vertically integrated bag converters.
- Performance Ceiling at High Humidity:Clay desiccants exhibit diminished adsorption efficiency above 80% relative humidity, limiting deployment in tropical logistics corridors without hybrid system supplementation.
- REACH Material Disclosure Mandates:Full compositional transparency requirements for EU consumer product packaging are extending supplier qualification timelines and raising documentation overhead for Asian exporters.
Strategic Opportunities
- Pharmaceutical Serialization Convergence:Integration of desiccant insertion automation with track-and-trace line equipment creates white space for packaging system vendors in Germany and Switzerland.
- Custom Package Specification:OEM demand for dimensionally precise bags with automated insertion compatibility is opening premium service tiers beyond commodity industrial supply.
- India PLI Scheme for Electronics:Domestic manufacturing incentives are attracting component assembly operations that require humidity protection, building new demand centers outside coastal China.
Industry Challenges
- Validated Stability Data Generation:Pharmaceutical customers require extensive ICH Q1A-compliant testing documentation that stretches R&D timelines and demands specialized analytical capabilities.
- Automation Line Integration Complexity:Desiccant insertion systems must synchronize with high-speed form-fill-seal equipment, requiring joint engineering between bag suppliers and packaging machinery OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clay Desiccant Bag Market |
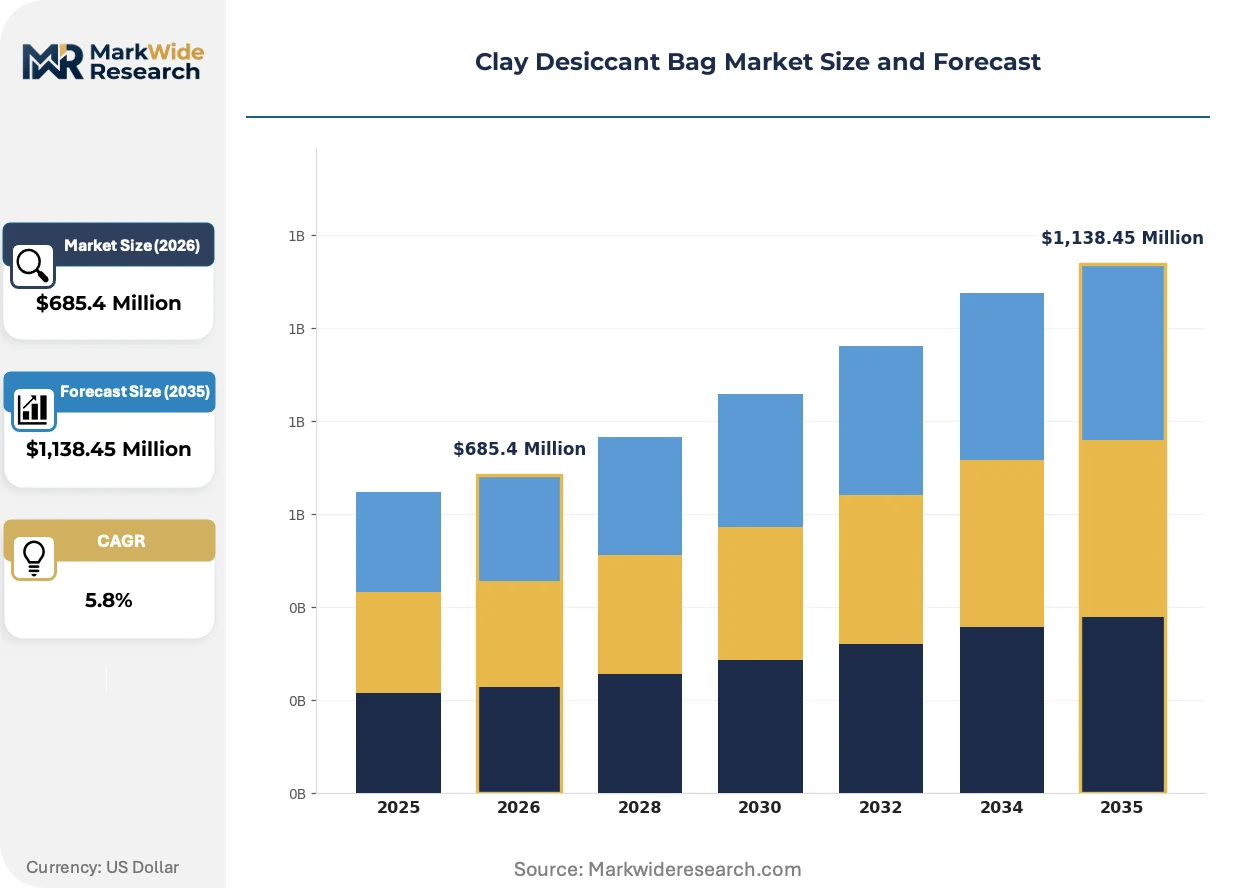
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Industrial Desiccants, Residential Desiccants, Commercial Desiccants, Pharmaceutical Desiccants Packaging Type: Single Use Bags, Bulk Bags, Multi-pack Bags, Custom Packages Application: Food Storage, Electronics Protection, Pharmaceutical Preservation, Industrial Packaging Distribution Channel: Online Retail, Direct Sales, Wholesale Distributors, Specialty Stores |
| Companies Covered | Stream Peak International, Interra Global Corporation, Clariant AG, Solvay, IMPAK Corporation, Desiccare, Inc., GeeJay Chemicals Ltd., AGM Container Controls, Absortech Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clay Desiccant Bag Market Strategic Shifts
Moisture management strategies are converging with automation and sustainability mandates, compressing traditional procurement cycles and collapsing the distinction between commodity supply and engineered solutions.
Indicator dye integration into clay desiccant formulations is collapsing the need for separate humidity monitoring devices in pharmaceutical and electronics packaging. Montmorillonite granules impregnated with cobalt-free color-change chemistry allow visual confirmation of saturation status without electronic sensors. Major drug manufacturers in Germany and medical device exporters in Ireland are specifying these smart desiccants for cold chain shipments where battery-powered loggers face temperature constraints.
REACH compliance deadlines in the European Union are accelerating material substitution away from synthetic silica toward natural bentonite across consumer electronics packaging. ECHA disclosure requirements for substances of very high concern are forcing brand owners to document desiccant composition down to trace additive levels. Electronics OEMs in the Netherlands and Sweden are now requiring full material declarations from bag suppliers, compressing qualification timelines for non-European converters.
Leasing-based warehousing arrangements are fragmenting traditional distributor relationships in the clay desiccant channel. Third-party logistics providers operating humidity-controlled facilities are absorbing procurement decisions previously made by end-use manufacturers. This shift is most visible in the US pharmaceutical distribution network, where regional 3PLs now specify desiccant performance standards for contract packaging operations serving generic drug manufacturers.
Clay Desiccant Bag Market Segmentation
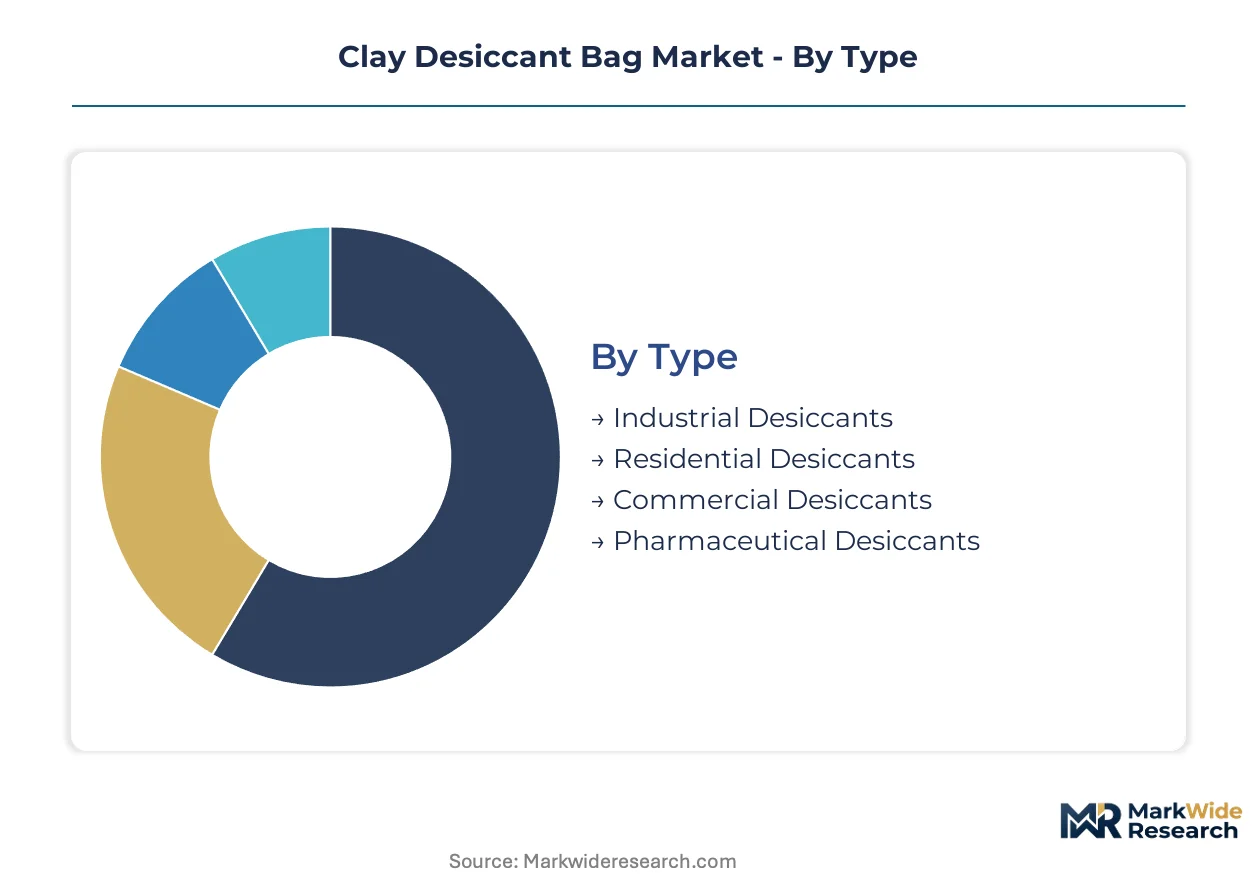
Segmentation in the clay desiccant bag market reveals how moisture protection requirements diverge across regulatory environments, automation readiness, and supply chain scale. Understanding these divides exposes where pricing power concentrates and where commoditization pressures dominate.
Type:
Cost tier separates the four product categories, with regulatory burden and performance validation requirements determining margin structure.
- Pharmaceutical Desiccants:FDA 21 CFR-compliant formulations with validated stability data under ICH Q1A protocols. Demand clusters among generic drug manufacturers in India and Germany facing container closure system guidance deadlines.
- Industrial Desiccants:High-volume bentonite bags for automotive and heavy machinery export packaging. Guangdong and Jiangsu electronics clusters drive bulk procurement through wholesale channels with minimal specification overhead.
- Commercial Desiccants:Mid-tier moisture control for retail distribution and small-scale manufacturing operations. Specifications vary by end-use with moderate documentation requirements.
- Residential Desiccants:Consumer-grade sachets for household storage applications. Price sensitivity dominates with minimal regulatory oversight across all geographies.
Industrial desiccants command the established base. The steepest expansion runs through pharmaceutical desiccants.
Packaging Type:
Application maturity and customer automation readiness shape the four packaging formats, with line integration complexity driving specification divergence.
- Custom Packages:Dimensionally precise bags engineered for automated insertion compatibility. Electronics OEMs in Southeast Asia specify exact tolerances to reduce form-fill-seal line changeover costs.
- Single Use Bags:Standardized sachets for pharmaceutical blister packs and consumer electronics boxes. High-volume, low-margin production with established specifications across all major demand centers.
- Bulk Bags:Large-capacity containers for industrial warehousing and ocean container protection. Procurement concentrates through 3PL arrangements in US pharmaceutical distribution networks.
- Multi-pack Bags:Retail-ready assortments for commercial and residential end-users. Packaging emphasizes shelf presence and consumer convenience over technical performance metrics.
Single use bags anchor current volume. Custom packages are climbing the fastest as OEM automation investments accelerate.
Application:
End-use sector determines regulatory exposure, with FDA, EPA, and REACH compliance requirements fragmenting specification standards.
- Electronics Protection:Montmorillonite-based formulations for semiconductor and component packaging during ocean transit. EPA silica gel reclassification is redirecting US procurement toward bentonite alternatives with equivalent moderate-humidity performance.
- Pharmaceutical Preservation:Validated desiccant systems for moisture-sensitive drug stability. Tightened FDA stability testing protocols mandate performance documentation that stretches supplier qualification timelines.
- Industrial Packaging:Heavy machinery and automotive export protection with minimal regulatory burden. Volume procurement through integrated mining operations in Wyoming and southern Europe sustains cost leadership.
- Food Storage:Compliance-focused applications under FSSAI and FDA food contact regulations. Migration testing requirements limit formulation flexibility compared to industrial segments.
Industrial packaging holds the volume base. Electronics protection shows the steepest expansion trajectory as supply chain regionalization accelerates.
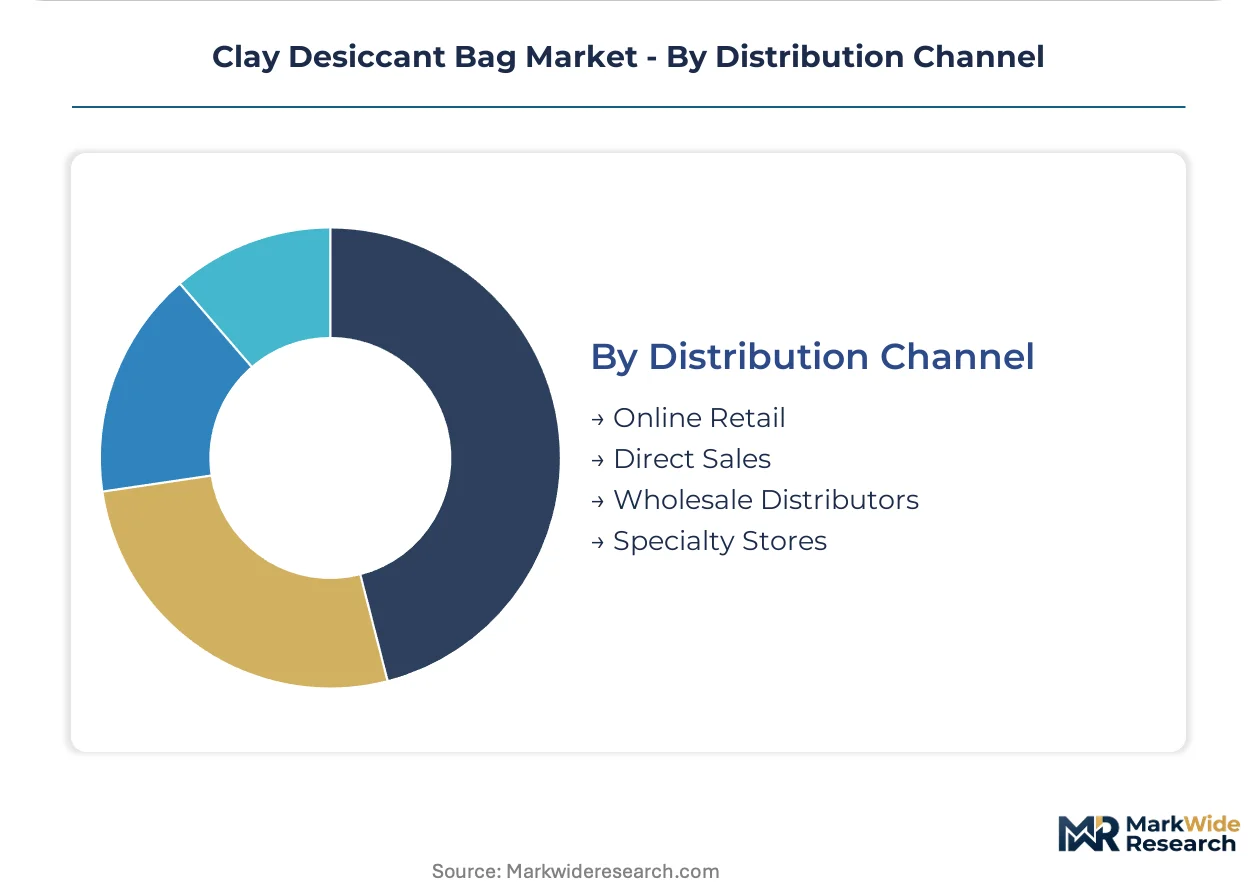
Distribution Channel:
Customer scale and technical specification complexity determine channel selection, with asset-light models disrupting traditional volume relationships.
- Wholesale Distributors:Bulk supply relationships serving industrial and commercial end-users. Humidity-controlled warehousing leasing arrangements are redistributing procurement decisions toward 3PL operators.
- Direct Sales:Engineered solutions for pharmaceutical and electronics OEMs requiring joint development. Technical service intensity sustains margin premiums against commodity alternatives.
- Online Retail:Standardized products for residential and small commercial buyers. Price transparency compresses margins while expanding geographic reach beyond traditional distribution footprints.
- Specialty Stores:Niche supply for restoration, museum, and archival applications. Low volume with high service requirements and extended technical consultation.
Wholesale distributors maintain the established base. Direct sales channels are gaining share fastest as automation integration demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives and tightening environmental regulations are redirecting clay desiccant procurement patterns across major demand centers. Government-backed industrial policies in Asia-Pacific electronics hubs and pharmaceutical clusters in Western Europe are accelerating validated desiccant adoption.
United States
EPA reclassification of silica gel disposal classifications is redirecting industrial procurement teams toward biodegradable bentonite alternatives. FDA container closure system guidance mandates validated stability data for moisture-sensitive pharmaceuticals. Electronics manufacturing corridors in Texas and Arizona are expanding montmorillonite bag specifications for semiconductor packaging during domestic transit.
China
GB/T standards for packaging desiccants shape formulation choices and supplier qualification criteria across export-oriented manufacturing. Dual carbon goals under MEE oversight are pressuring domestic bentonite miners toward cleaner extraction methods. Guangdong and Jiangsu province electronics clusters drive bulk industrial-grade procurement for ocean-bound component protection.
Germany
REACH material disclosure mandates are extending supplier qualification timelines for Asian exporters serving EU consumer electronics markets. EMA pharmaceutical serialization requirements are converging with desiccant insertion automation demands. Generic drug manufacturers in Baden-Württemberg are tightening container closure system specifications ahead of compliance deadlines.
India
PLI scheme incentives for electronics manufacturing are attracting component assembly operations requiring humidity protection outside traditional coastal China supply chains. CDSCO stability testing protocols for moisture-sensitive generics are pulling validated clay desiccants into domestic drug packaging. Maharashtra and Gujarat pharmaceutical clusters are expanding procurement of FDA-compliant bentonite formulations.
Japan
METI industrial standards for moisture-sensitive electronics exports are specifying montmorillonite performance benchmarks for semiconductor protection. PMDA pharmaceutical quality guidelines mandate documented desiccant validation for stability-critical drug shipments. Kanto region medical device exporters are specifying cobalt-free indicator dye integration for cold chain visibility.
Clay Desiccant Bag Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered competitive positions. The vendor base spans integrated bentonite miners, specialized bag converters, and regional distributors leveraging asset-light warehousing models. Three archetypes dominate: mining-integrated formulators with captive raw material access, custom packaging specialists serving automation-intensive OEMs, and testing-intensive validators exceeding military specifications. Capacity expansion and strategic partnerships represent the dominant competitive moves as players position for pharmaceutical serialization convergence.
Within the mining-integrated tier, Clariant AG exemplifies backward control over southern European bentonite deposits. Stream Peak International and IMPAK Corporation occupy positions on opposite specialization vectors—Southeast Asia-focused custom packaging capabilities versus stringent in-house testing protocols. These three anchors illustrate how geographic proximity to electronics clusters, pharmaceutical regulatory hubs, and integrated raw material access stratify competitive positioning without requiring scale-driven consolidation.
| Leading Market Players |
|---|
| Stream Peak International |
| Interra Global Corporation |
| Clariant AG |
| Solvay |
| IMPAK Corporation |
| Desiccare, Inc. |
| GeeJay Chemicals Ltd. |
| AGM Container Controls |
| Absortech Group |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Wyoming and southern European bentonite deposits determines both pricing tier spreads and supply chain shape, with captive mining operations commanding premium positioning while non-integrated converters absorb input cost volatility.
Pricing Analysis
Certification level creates the primary spread across pharmaceutical, industrial, commercial, and residential tiers. FDA 21 CFR-compliant formulations with validated ICH Q1A stability data command substantial premiums over commodity industrial grades, while price differentiation reflects automation compatibility and custom dimensional specifications. Cost compression in standard industrial bags is intensifying because Guangdong electronics clusters negotiate volume offtakes with minimal documentation overhead. Generic drug manufacturers in India exhibit highest price sensitivity due to thin margins, whereas German medical device OEMs prioritize validated performance data over unit economics.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for electronics-bound desiccant flows. Raw material extraction concentrates in Wyoming, Greece, and Turkey, with bag conversion and packaging operations drawing from these captive sources. Montmorillonite ore, Tyvek packaging substrate, and cobalt-free indicator dyes constitute critical input dependencies. Distribution runs through wholesale channels serving industrial clusters, direct sales for pharmaceutical OEMs, and third-party logistics providers absorbing procurement decisions previously made by end-use manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA container closure system guidance convergence with pharmaceutical serialization mandates creates a high-growth disruption window, with automation-ready desiccant suppliers capturing disproportionate value from generic drug manufacturers facing compliance deadlines.
For Market Incumbents: Build regulatory data moats through ICH Q1A-compliant stability testing infrastructure that emerging competitors cannot replicate without multi-year investment. Deepen backward integration into bentonite mining operations to defend against input cost volatility from Wyoming and southern European supply concentration. Channel control through humidity-controlled warehousing leasing arrangements protects against regional distributor fragmentation. For New Entrants and Emerging Players: Pursue custom packaging white space in India PLI scheme electronics manufacturing corridors, where domestic component assembly operations require humidity protection outside established coastal China supply relationships. Target pharmaceutical serialization convergence in Germany and Switzerland, where OEM demand for automated desiccant insertion compatibility outpaces incumbent technical service capacity. Lead with joint engineering capabilities for form-fill-seal line integration rather than commodity price competition. For Investors and Strategic Acquirers: Specialized bag converters with validated testing protocols and pharmaceutical customer relationships represent the most defensible acquisition profile. Long-term viability hinges on exposure to FDA and EMA regulatory compliance spending rather than industrial commodity cycles. Watch for indicator dye integration patents and cobalt-free color-change chemistry capabilities as inflection signals for premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Mining | Captive supply from Wyoming deposits insulates Clariant against input cost volatility. |
| Custom Packaging Capability Expansion | Stream Peak International anchors electronics OEM relationships through dimensional precision engineering. |
| Pharmaceutical Serialization Convergence | Desiccare and AGM Container Controls capture automation integration demand from generic drug manufacturers. |
| Indicator Dye Formulation Development | Cobalt-free color-change chemistry opens cold chain visibility applications for medical device exporters. |
| REACH Compliance Documentation Systems | Full material disclosure capabilities compress Asian exporter qualification timelines for EU electronics markets. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with plant managers at bentonite mining operations, procurement leads at pharmaceutical OEMs, technical R&D directors at bag converters, and distribution channel partners; alongside secondary validation through FDA 21 CFR guidance documents, ECHA REACH substance databases, GB/T packaging standards, customs trade flows, and SEC filings from integrated miners. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down production capacity assessments across Wyoming, Greece, and Turkey.
Forecast inputs considered desiccant grade tier, end-use industry regulatory exposure, packaging format automation compatibility, and regional production hub concentration across the analysis window. Modeled segmentation dimensions included pharmaceutical versus industrial versus commercial versus residential type, custom versus single-use versus bulk versus multi-pack packaging, and electronics protection versus pharmaceutical preservation versus industrial packaging versus food storage application. CAGRs derived from regression analysis against historical bentonite procurement patterns and projected electronics manufacturing cluster expansion.
Macroeconomic conditions sit as an overlay; deviation in ocean freight rates, electronics export demand from Guangdong and Jiangsu provinces, or FDA inspection enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timeline adherence and mining capacity expansion plans. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Packaging Nets Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Carry Bag Market
Bags and Containers
Shrink Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
PE Jumbo Bags Market
Bags and Containers
Centerfold Laminated Bags Market
Bags and Containers
Trash Can Liners Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Twisted Handle Bags Market