
 Logistics Services Software Market | 2026-2036
Logistics Services Software Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Services Software Market Outlook
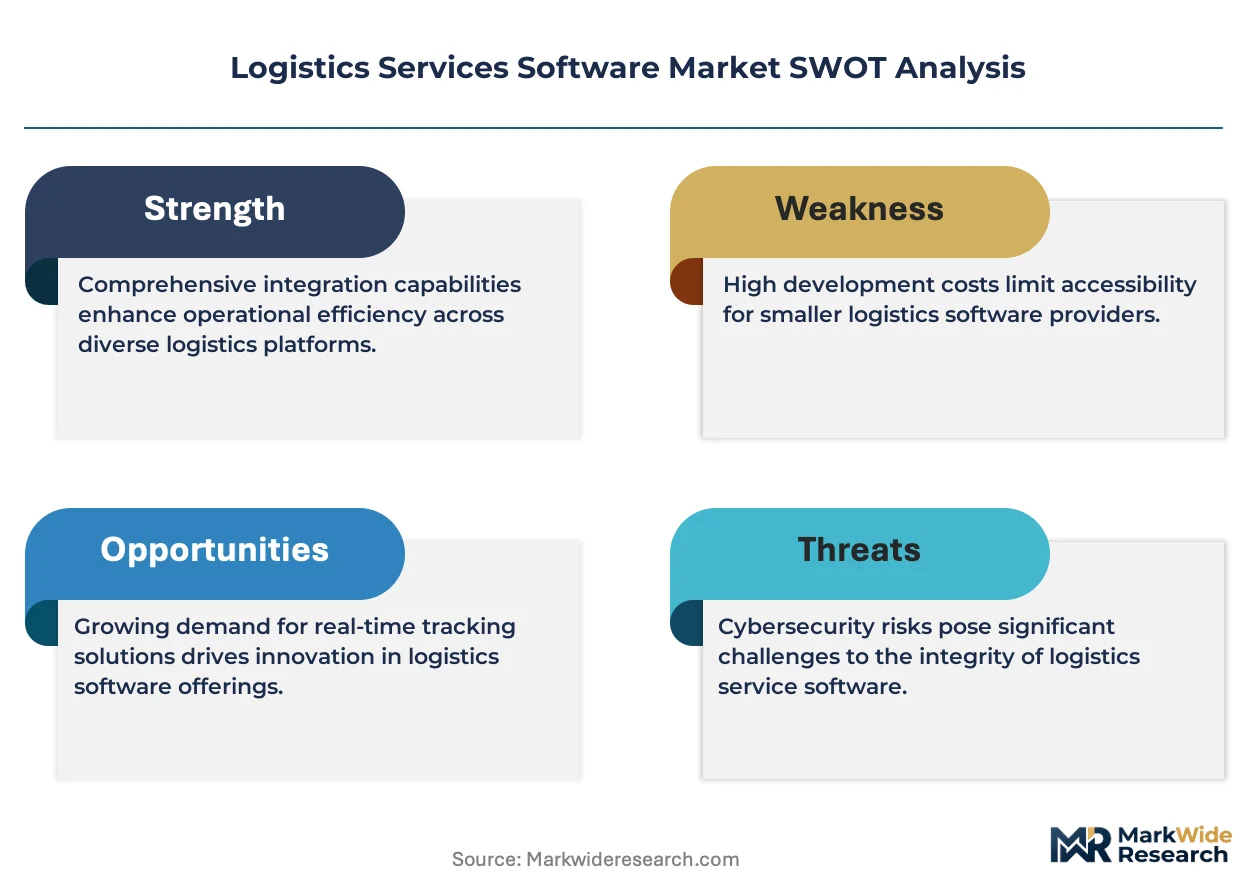
Subscription-based maintenance tiers is restructuring how logistics software vendors monetize their platforms. SAP SE leverages its embedded ERP connectivity to dominate enterprise accounts. Manhattan Associates anchors its position through specialized warehouse management intelligence. Blue Yonder competes on AI-native demand forecasting capabilities.
Logistics services software comprises modular applications that coordinate freight movement, inventory positioning, and delivery sequencing through API-connected cloud architectures, with latency thresholds typically below 200 milliseconds for real-time tracking updates. Route optimization and inventory management modules command the deepest margin pools due to their direct impact on fuel expenditure and carrying costs. Cloud-based and SaaS deployment modes are displacing on-premises installations as shippers prioritize elastic capacity over capital-intensive infrastructure ownership.
The EU AI Act, FDA's oversight of pharmaceutical cold-chain traceability, and China's GB standards for data localization collectively shape product architecture decisions across jurisdictions. Compliance investments now consume substantial R&D bandwidth, particularly for vendors serving cross-border pharmaceutical and food distribution networks. Stakeholders must monitor how divergent data sovereignty requirements fragment platform standardization efforts.
Market Dynamics
Subscription-based maintenance tiers is restructuring how logistics software vendors monetize their platforms, while the EU AI Act imposes algorithmic transparency mandates that consume substantial R&D bandwidth for automated routing systems.
Growth Catalysts
- EU AI Act compliance mandates:Automated routing algorithms now require explainability documentation, forcing vendors to invest in interpretable machine learning architectures that pharmaceutical and food distributors demand for cross-border traceability.
- E-commerce fulfillment network expansion:Platform operators are scaling cloud-native warehouse management investments to handle same-day delivery promises, with API-connected architectures replacing legacy EDI systems.
- Germany's industrial logistics digitization:The country's automotive and machinery clusters are accelerating IoT sensor deployment across freight yards, creating concentrated demand for real-time inventory positioning modules.
Market Restraints
- Cloud infrastructure cost volatility:Elastic compute pricing for sub-200-millisecond latency requirements strains operating margins, particularly for mid-tier vendors serving seasonal freight patterns.
- Data localization fragmentation:China's GB standards, EU GDPR, and emerging Middle Eastern sovereignty rules force redundant platform architectures that fragment development resources.
- Legacy system entrenchment:On-premises ERP installations at major shippers resist API migration, slowing cloud displacement despite SaaS elasticity advantages.
Strategic Opportunities
- Pharmaceutical cold-chain traceability:FDA oversight of temperature-monitored distribution creates premium module demand for sensor integration and audit trail automation.
- AI-native demand forecasting convergence:Machine learning platforms are merging with warehouse robotics orchestration, enabling predictive inventory positioning before purchase orders trigger.
- India's logistics digitization:The country's PLI scheme for warehousing infrastructure and DGFT trade facilitation reforms are opening cloud deployment channels for international vendors.
Industry Challenges
- Embedded ERP integration complexity:SAP and Oracle environments require specialized connector development that consumes 40% of implementation timelines for enterprise accounts.
- Algorithmic audit talent scarcity:The EU AI Act's conformity assessment demands scarce machine learning operations engineers who understand both freight optimization and regulatory documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Services Software Market |
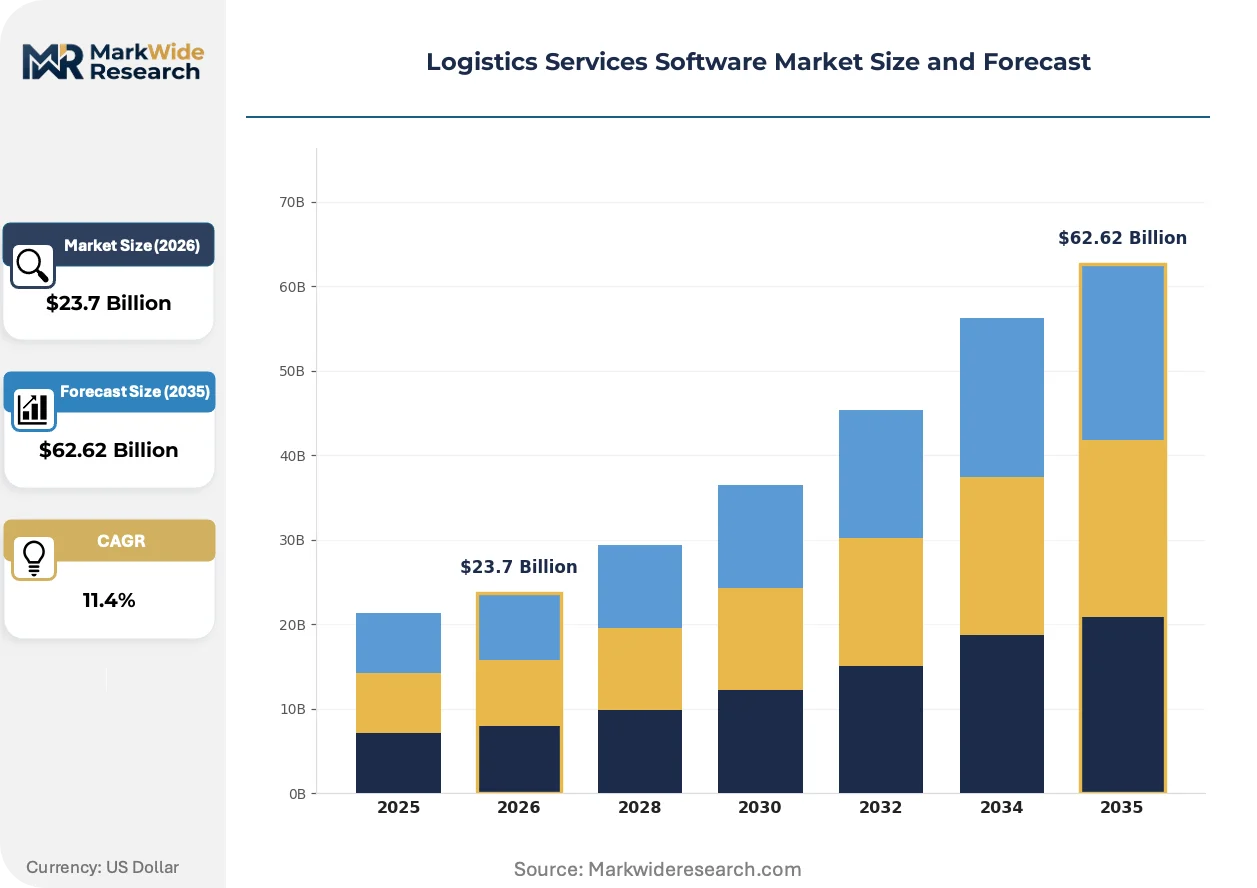
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Route Optimization, Inventory Management, Freight Tracking, Delivery Scheduling End User: Retailers, Manufacturers, Distributors, E-commerce Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | SAP SE, Manhattan Associates, Blue Yonder, Oracle, IBM Corporation, The Descartes Systems Group, Körber AG, Infor, LogiNext Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logistics Services Software Market Strategic Shifts
API-first architectures are displacing monolithic freight management suites, enabling modular procurement where shippers compose best-of-breed routing, inventory, and yard management functions.
Blockchain-enabled documentation is decentralizing bill-of-lading verification across maritime and air freight corridors. Container lines and customs brokers in Rotterdam and Singapore are piloting distributed ledger protocols that eliminate documentary fraud. This technology is decentralizing trust mechanisms previously concentrated in bank-issued letters of credit, compressing settlement cycles from days to hours.
The EU AI Act's risk-based classification system is mandating human-in-the-loop overrides for automated dispatch decisions affecting driver safety. Fleet operators must now maintain algorithmic decision logs that regulators in Brussels and national transport authorities can audit. Pharmaceutical distributors face the steepest compliance burden, as their cold-chain routing algorithms fall under high-risk system designations requiring third-party conformity assessments.
Shippers are unbundling software procurement from managed services contracts, separating platform licensing from implementation support. Third-party logistics providers in Germany and the Netherlands now license warehouse management modules directly while retaining system integrators for configuration. This pattern is most visible among mid-market freight forwarders seeking to avoid long-term vendor lock-in while maintaining operational flexibility.
Logistics Services Software Market Segmentation
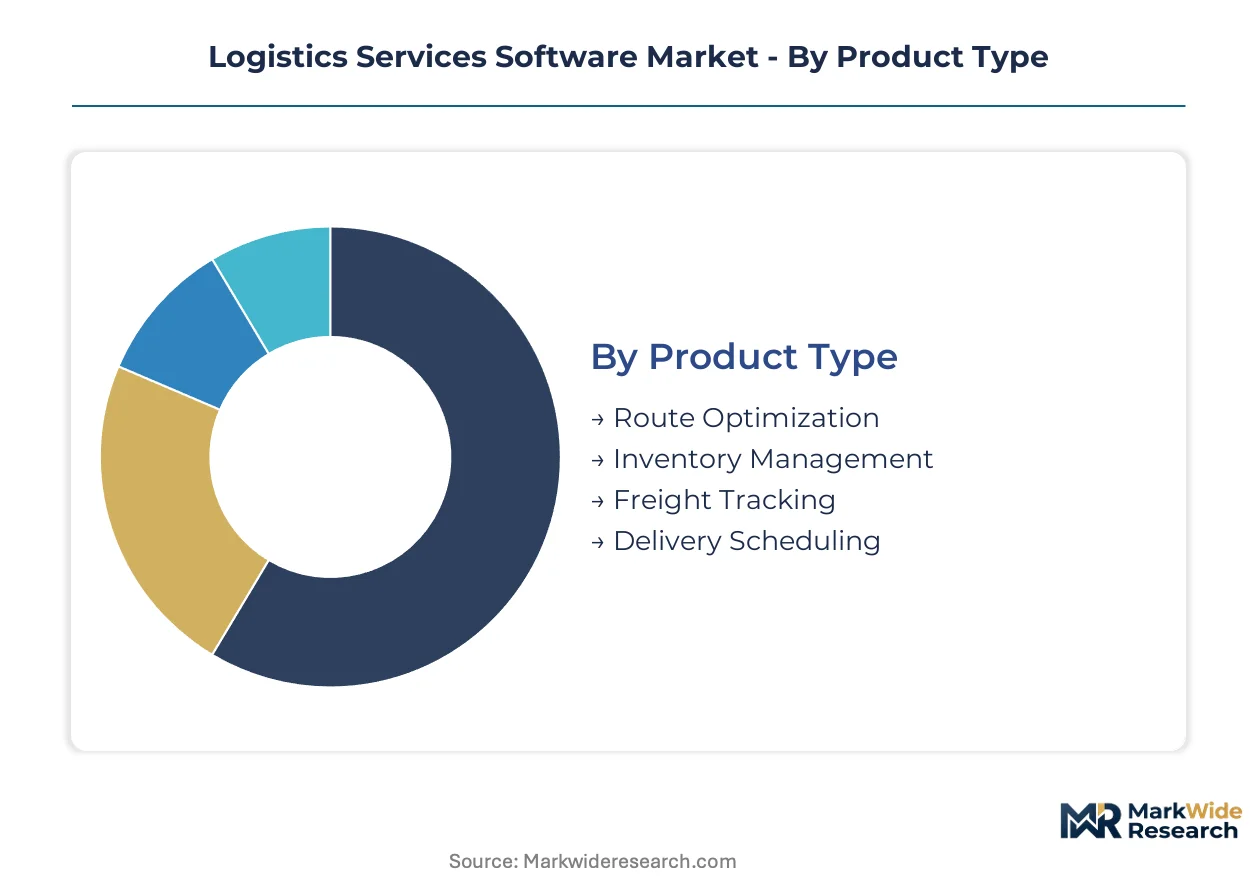
Logistics services software segments reflect divergent buyer priorities across operational complexity, regulatory exposure, and capital constraints. Understanding these fault lines reveals where vendors must configure specialized modules versus standardized platforms.
Product Type:
Buyers in this category differentiate by operational pain point severity and measurable cost reduction potential.
- Route Optimization:Algorithms calculate multi-modal freight paths against fuel costs, toll structures, and driver hour regulations. German automotive clusters and Dutch port operators drive concentrated procurement as they integrate real-time traffic APIs with EU AI Act audit requirements.
- Inventory Management:Systems synchronize warehouse positioning with demand signals through IoT-enabled stock-level monitoring. Pharmaceutical distributors in Basel and Singapore prioritize these modules for FDA and Swissmedic cold-chain compliance documentation.
- Freight Tracking:Sub-200-millisecond latency architectures provide shipment visibility across maritime and air corridors.
- Delivery Scheduling:Last-mile sequencing tools coordinate driver dispatch with customer time-window preferences.
Inventory Management leads volumes today; Route Optimization is gaining share fastest.
End User:
Procurement authority in this category tracks supply chain control points and direct-to-consumer exposure.
- E-commerce:Platforms demand elastic cloud capacity for same-day fulfillment promises, with API-native architectures replacing legacy EDI. Indian marketplace operators and Southeast Asian quick-commerce ventures are expanding warehouse management investments under DGFT trade facilitation reforms.
- Retailers:Omnichannel networks require unified inventory visibility across stores, dark stores, and distribution centers.
- Manufacturers:Industrial clusters in Stuttgart and Nagoya deploy IoT sensor networks for inbound material synchronization.
- Distributors:Third-party logistics providers license modular warehouse systems while outsourcing implementation to system integrators.
E-commerce commands the largest procurement budgets; Retailers are expanding most quickly.
Deployment:
Capital availability and data sovereignty exposure separate buyers across deployment modes.
- Cloud-Based:Elastic compute architectures enable seasonal capacity scaling without infrastructure ownership. Mid-tier freight forwarders in the Netherlands and Belgium prefer this mode to avoid long-term vendor lock-in.
- SaaS:Subscription tiers restructure vendor monetization through usage-based pricing aligned with shipment volumes.
- Hybrid:Configurations maintain sensitive routing data on-premises while leveraging cloud analytics.
- On-Premises:Legacy ERP entrenchment at major shippers resists API migration despite elasticity disadvantages.
Cloud-Based installations dominate new procurement; SaaS is climbing the fastest.
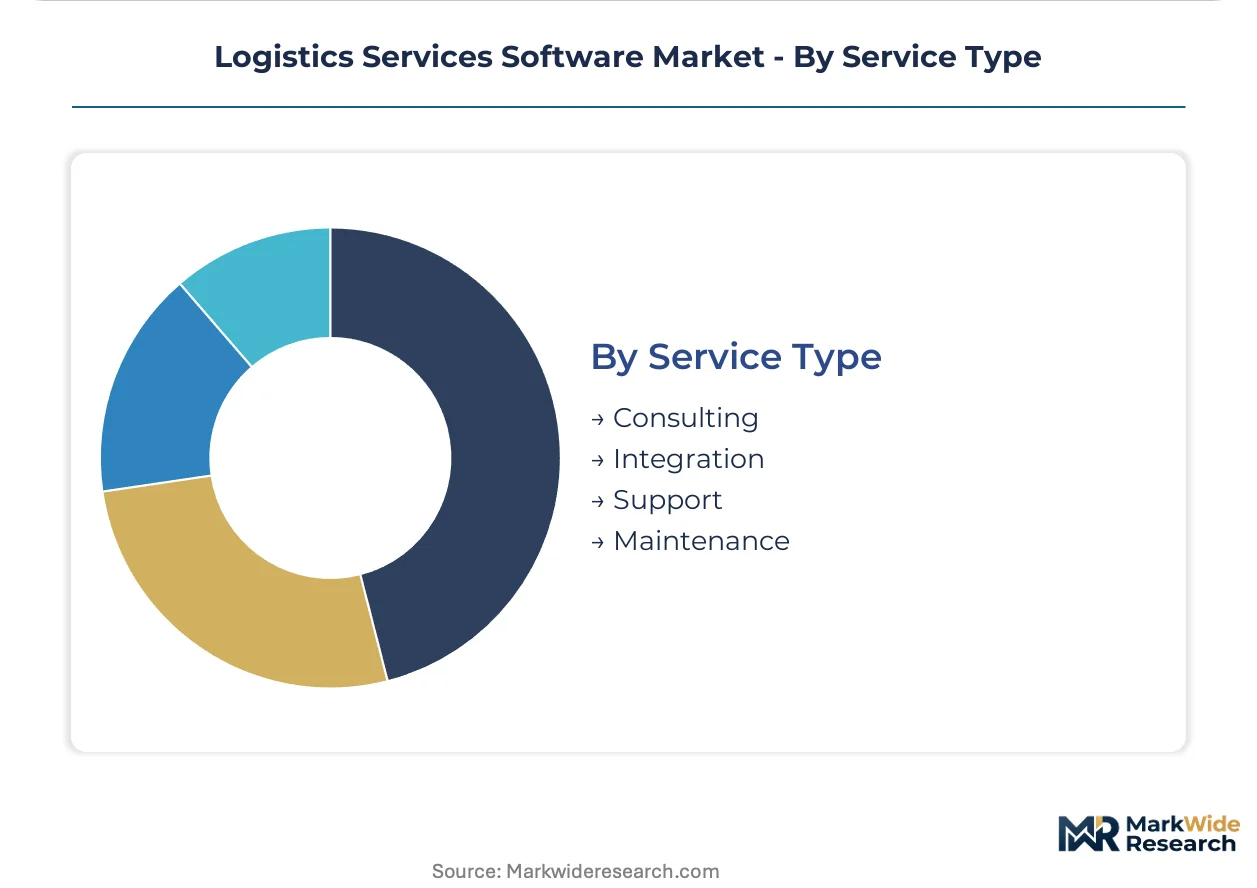
Service Type:
Internal technical capabilities versus external dependency determines service procurement patterns.
- Integration:SAP and Oracle connector development consumes substantial implementation timelines, creating sustained demand for specialized system integrators in enterprise accounts.
- Consulting:EU AI Act compliance documentation and algorithmic audit preparation require scarce machine learning operations expertise.
- Support:24/7 operational assistance for sub-200-millisecond latency threshold maintenance.
- Maintenance:Subscription-based tiers now separate platform licensing from ongoing technical support.
Integration services anchor revenue today; Consulting is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial logistics digitization outpaces France's retail-focused deployments, while India's warehouse automation accelerates under distinct regulatory frameworks than China's data-localization mandates.
Germany
Automotive and machinery clusters in Stuttgart and Munich drive concentrated procurement of IoT-enabled inventory positioning modules. The EU AI Act imposes algorithmic transparency requirements on automated routing systems serving cross-border pharmaceutical networks. KBA transport authorities coordinate with Brussels on conformity assessments for high-risk logistics algorithms.
United States
E-commerce fulfillment networks in Seattle and Los Angeles scale elastic cloud capacity for same-day delivery promises. FDA oversight of pharmaceutical cold-chain traceability creates premium demand for sensor-integrated audit trail modules. Dallas-Fort Worth distribution corridors anchor domestic freight tracking investments.
China
GB standards for data localization force redundant platform architectures for cross-border pharmaceutical distributors. MIIT cloud computing regulations shape deployment decisions for warehouse management systems serving Yangtze River Delta manufacturing clusters. Shenzhen quick-commerce ventures expand API-native fulfillment investments.
India
DGFT trade facilitation reforms open cloud deployment channels for international warehouse management vendors. PLI scheme incentives for warehousing infrastructure accelerate digitization in Maharashtra and Karnataka logistics corridors. Bangalore-based marketplace operators scale real-time inventory positioning for quick-commerce expansion.
Netherlands
Rotterdam port operators pilot blockchain-enabled bill-of-lading verification across maritime freight corridors. GDPR data sovereignty requirements intersect with EU AI Act mandates for automated yard management systems. Amsterdam third-party logistics providers license modular software directly while outsourcing implementation to system integrators.
Logistics Services Software Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise ERP-embedded vendors commanding concentrated accounts while modular best-of-breed players fragment mid-market procurement. The vendor landscape organizes around three strategic archetypes: full-suite platforms leveraging existing enterprise relationships, specialized warehouse intelligence providers, and AI-native demand forecasting specialists. Competitive dynamics center on M&A activity consolidating adjacent supply chain capabilities and API-first architecture investments displacing legacy EDI integrations.
Among enterprise-integrated platform providers, SAP SE and Oracle occupy positions anchoring full-suite logistics modules within broader ERP ecosystems. Manhattan Associates exemplifies the specialized warehouse management archetype, while Blue Yonder sits within the AI-native forecasting tier competing on predictive inventory positioning capabilities.
| Leading Market Players |
|---|
| SAP SE |
| Manhattan Associates |
| Blue Yonder |
| Oracle |
| IBM Corporation |
| The Descartes Systems Group |
| Körber AG |
| Infor |
| LogiNext Solutions |
| Others |
Value Chain & Pricing Dynamics
E-commerce fulfillment networks demanding sub-200-millisecond latency thresholds are forcing cloud infrastructure providers to expand elastic compute capacity across Germany, the United States, and India, compressing margins for mid-tier software vendors unable to achieve hyperscaler-scale procurement leverage.
Pricing Analysis
Capacity additions in Germany's industrial logistics corridors are reshaping price floors for warehouse management modules as SAP SE and Oracle embed connectivity premiums into enterprise ERP bundles. Three-tier pricing structure across premium, standard, and economy levels differentiates by integration complexity and API throughput guarantees, with pharmaceutical cold-chain compliance tiers commanding the widest spreads. Cost compression in mid-market SaaS tiers intensifies because seasonal freight forwarders prioritize usage-based elasticity over fixed licensing. Small third-party logistics providers in the Netherlands and Belgium exhibit the highest price sensitivity, while automotive clusters in Stuttgart accept premium positioning for real-time inventory synchronization.
Supply Chain Analysis
Cloud-native development talent rests on concentrated pools in Bangalore, Berlin, and Seattle, with specialized machine learning operations engineers for EU AI Act documentation scarcer still. Proprietary routing algorithm IP, hyperscaler compute contracts, and embedded ERP connector libraries constitute the critical input stack. Single-source vulnerability runs through NVIDIA's GPU allocation frameworks for AI training workloads, creating bottleneck exposure for demand forecasting module vendors. Distribution runs through direct enterprise sales teams for SAP and Oracle ecosystems, while modular best-of-breed players rely on system integrator channel partnerships in Amsterdam and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's algorithmic transparency mandates impose heavier compliance burdens on vendors serving European pharmaceutical networks than on competitors focused on India's DGFT-facilitated trade corridors, creating a regulatory arbitrage window for capital deployment.
For Market Incumbents: Deepen embedded ERP integration moats by acquiring specialized connector developers serving Oracle and SAP environments, as API migration resistance at major shippers slows cloud displacement. Fortify vertical integration into IoT sensor hardware partnerships to capture cold-chain traceability premiums before FDA oversight tightens pharmaceutical module requirements. For New Entrants and Emerging Players: Launch via modular API-first architectures targeting India's PLI-subsidized warehousing infrastructure, where DGFT reforms have opened cloud deployment channels with lower incumbent saturation. White-space concentration sits with quick-commerce inventory positioning modules for Bangalore marketplace operators, bypassing the EU AI Act compliance overhead that burdens European market entry. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native demand forecasting specialists possessing pre-trained models for automotive and pharmaceutical verticals, as warehouse robotics orchestration convergence accelerates across the analysis window. Long-term viability favors acquisition targets with established EU AI Act conformity assessment documentation and existing KBA transport authority relationships. Watch FDA pharmaceutical cold-chain rulemaking acceleration as the inflection signal for premium module demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures displace EDI systems at Rotterdam port operators and Singapore container lines. |
| Acquisition of Specialist Firm | Machine learning operations talent scarcity in Brussels and Berlin drives consolidation of EU AI Act compliance boutiques. |
| Geographic Expansion | India's PLI warehousing incentives attract cloud-native vendors to Maharashtra logistics corridors. |
| Strategic Partnership | Hyperscaler compute agreements secure sub-200-millisecond latency guarantees for e-commerce fulfillment networks. |
| Product Launch | Blockchain-enabled bill-of-lading modules address documentary fraud compression at maritime freight chokepoints. |
Study Parameters
Bottom-up e-commerce fulfillment modeling reconciled against top-down cloud infrastructure deployment tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers at third-party logistics providers, platform engineers, and system integrators in Amsterdam and Singapore were validated against secondary sources including SEC filings from SAP SE and Oracle, hyperscaler capex disclosures from AWS and Azure, and EU AI Act implementation guidance from Brussels regulatory databases. Triangulation across these vectors ensured segmentation integrity for deployment mode and vertical adoption patterns.
Historical trendline analysis of warehouse management system procurement cycles informed the projection framework across the analysis window. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical industry exposure, integration complexity level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted capacity scaling curves and API adoption velocity indices, with pharmaceutical cold-chain compliance investments and automotive IoT sensor deployment rates serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement acceleration or MIIT data localization expansion in China. The analysis reflects assumptions on cloud displacement velocity and ERP migration resistance documented in stakeholder interviews. A small set of named triggers—FDA pharmaceutical traceability rulemaking, KBA algorithmic audit protocol finalization, and India's DGFT scheme extension—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
E-Invoicing Software Market
Software & Services
Virtual Client Computing Software Market
Software & Services
Courier Software Market
Software & Services
Automated Testing Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Federal Government Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Binary Drivers Market
Software & Services
Global Application Release Automation Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Global Customer Experience Software Market
Software & Services
Global OEE Software Market
Software & Services
Vehicle Embedded Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Global Fixed Asset Management Software Market