
 Airline Route Profitability Software Market | 2026-2036
Airline Route Profitability Software Market Size, Share, and Industry Trends Forecast 2026-2036
Airline Route Profitability Software Market Outlook
North American software vendors is shifting development capacity toward modular cloud architectures for airline operations. Sabre Corporation leverages its global distribution heritage to anchor enterprise-grade revenue management deployments. Amadeus IT Group SA sustains competitive pressure through integrated scheduling and passenger service platforms. PROS Holdings, Inc. differentiates via AI-native pricing science embedded within route planning workflows.
Airline route profitability software comprises algorithmic platforms that calculate per-flight and per-route contribution margins by integrating fuel costs, yield data, passenger demand curves, and operational constraints into unified decision engines. These systems process real-time inventory, competitor pricing, and schedule feasibility to recommend network additions, frequency adjustments, or aircraft gauge changes. Revenue Management solutions dominate current procurement budgets as carriers prioritize dynamic pricing sophistication over legacy scheduling upgrades. Cloud-Based deployment architectures represent the fastest-expanding segment, displacing on-premises installations as airlines seek elastic compute for seasonal demand spikes. SaaS delivery models concentrate margin pools among vendors capable of multi-tenant infrastructure with sub-second query response times.
FAA operational regulations governing slot utilization and on-time performance reporting shape how U.S. carriers configure route profitability dashboards. EASA emissions monitoring requirements under EU Green Deal frameworks are forcing European operators to embed carbon cost allocations into network planning algorithms. India's DGCA and the country's PLI scheme for aviation infrastructure are accelerating domestic airline digitization mandates. Stakeholders must monitor how evolving carbon border adjustment mechanisms and slot allocation reforms will redefine the cost variables that profitability engines must optimize.
Market Dynamics
Cloud migration pressure from full-service carriers in Asia-Pacific is compressing deployment cycles and forcing legacy on-premises vendors to rearchitect their platforms for multi-tenant elasticity.
Growth Catalysts
- EU Green Deal emissions tracking:EASA mandates are embedding carbon cost calculations directly into route planning algorithms, creating mandatory upgrade cycles for European operators.
- Low-cost carrier digitization in India:DGCA modernization directives combined with PLI scheme incentives are accelerating network planning software procurement across domestic airlines.
- Dynamic pricing sophistication:Revenue Management modules are capturing larger procurement budgets as carriers prioritize yield optimization over static scheduling tools.
Market Restraints
- Legacy system integration debt:On-premises PSS and inventory systems create API friction that extends SaaS deployment timelines by 12-18 months.
- Sub-second query requirements:Elastic compute for seasonal demand spikes demands specialized infrastructure expertise that concentrates among three dominant vendors.
- Slot utilization compliance:FAA on-time performance reporting mandates force dashboard customization that fragments standardization efforts.
Strategic Opportunities
- India's aviation infrastructure expansion:PLI scheme beneficiaries are building greenfield digital capabilities without legacy migration burdens.
- AI-native pricing convergence:Machine learning yield engines are merging with operations research solvers to create unified decision platforms.
- Carbon border adjustment preparation:EU Green Deal frameworks are creating export-market compliance requirements that spread emissions-tracking software demand to non-European carriers.
Industry Challenges
- Operations research talent scarcity:Airlines and vendors compete for PhD-level optimization specialists capable of tuning network flow algorithms.
- Multi-tenant latency engineering:SaaS providers must maintain sub-second response times across peak booking windows without overprovisioning base capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airline Route Profitability Software Market |
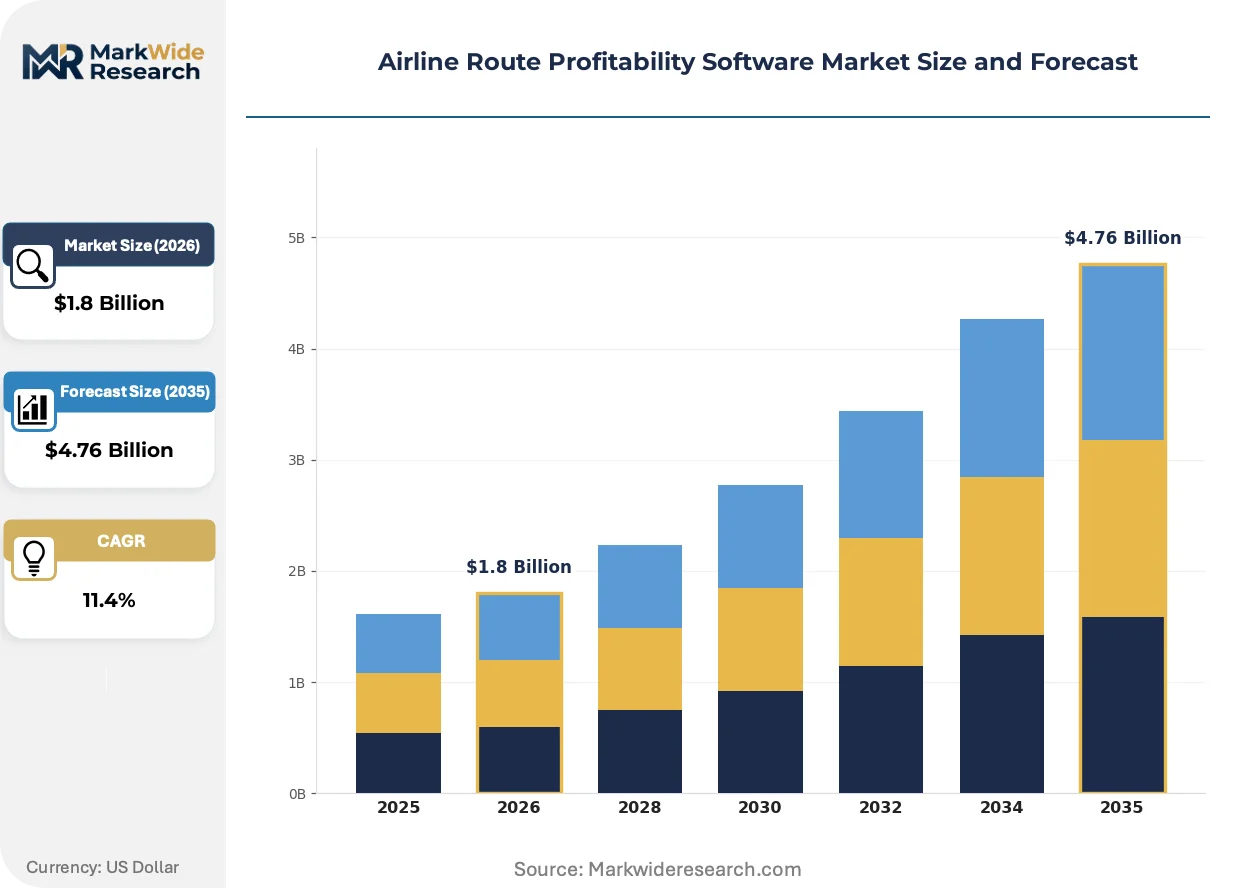
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Revenue Management, Scheduling Tools, Capacity Planning, Route Optimization Application: Passenger Transport, Cargo Services, Charter Operations, Codeshare Agreements End User: Airline Operators, Aviation Consultants, Travel Agencies, Freight Forwarders Deployment: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Sabre Corporation, Amadeus IT Group SA, Lufthansa Systems, SITA, IBM Corporation, Oracle Corporation, PROS Holdings, Inc., Seabury Solutions, Wipro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airline Route Profitability Software Market Strategic Shifts
Algorithmic decision engines are absorbing adjacent functions—pricing, scheduling, and emissions compliance—into unified platforms that compress vendor consolidation timelines.
Graph neural networks applied to demand forecasting are rewriting how carriers predict passenger booking curves across interconnected city pairs. Full-service carriers in Singapore and Japan are deploying these models for long-haul network planning. The technology is rewriting competitive differentiation by enabling real-time re-optimization that static regression models cannot match.
EASA emissions monitoring requirements under EU Green Deal frameworks are forcing carbon cost allocations into every network planning scenario. European operators must now model route profitability with explicit CO2 price exposure. Low-cost carriers with dense short-haul networks face the steepest compliance curve as they retrofit legacy planning engines.
Airline technology procurement is consolidating vendor relationships as carriers seek integrated platforms over best-of-breed point solutions. Network planning teams are absorbing revenue management functions that previously sat in separate departments. This organizational consolidation is most visible among Asia-Pacific full-service carriers restructuring their commercial technology stacks.
Airline Route Profitability Software Market Segmentation
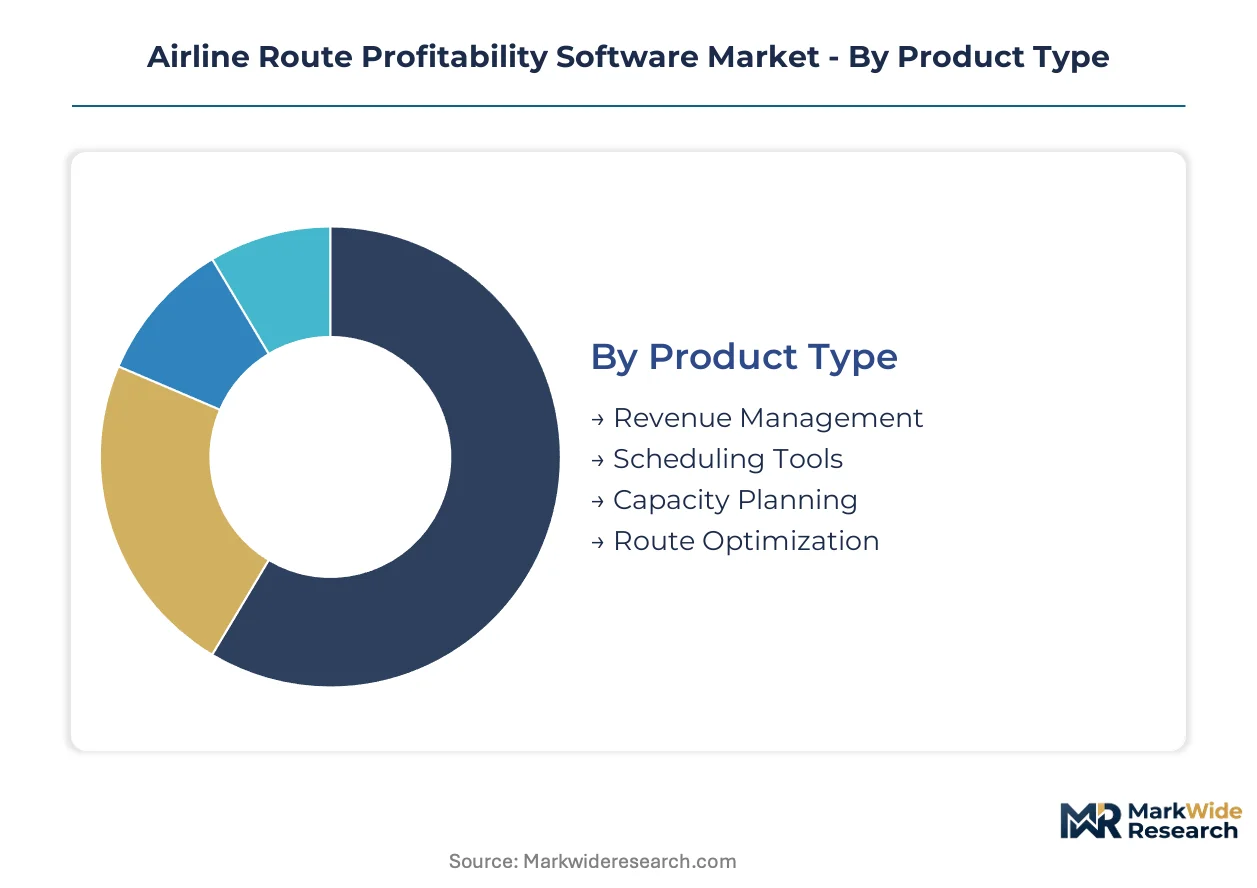
Route profitability software vendors configure their R&D roadmaps around four distinct product architectures. Each segment demands different algorithmic sophistication, integration depth, and compliance feature sets that reshape procurement priorities across carrier types.
Product Type:
Supply concentration clusters around vendors with operations research heritage and airline PSS integration capabilities.
- Revenue Management:Dynamic pricing engines ingest real-time booking curves, competitor fares, and inventory levels to optimize yield per available seat mile. Full-service carriers in Singapore and Japan deploy these modules for long-haul network planning where demand volatility exceeds 40% across seasons.
- Scheduling Tools:These platforms optimize fleet rotation, crew pairing, and maintenance routing against slot constraints and curfew windows. Low-cost carriers in India prioritize this segment as DGCA modernization mandates force digitization of manual scheduling workflows.
- Capacity Planning:Aircraft gauge selection and frequency optimization modules balance load factor targets against capital deployment efficiency.
- Route Optimization:Network flow solvers evaluate new city pair viability using fuel cost projections, competitor capacity, and catchment area demand models.
Revenue Management absorbs the bulk of installed capacity; Cloud-Based deployment architectures are expanding most quickly.
Application:
Cost tier differentiation separates enterprise-grade implementations from mid-market configurations across operational domains.
- Passenger Transport:Yield optimization for scheduled services dominates procurement volumes, with algorithms processing passenger booking curves across interconnected city pairs. EASA emissions monitoring requirements under EU Green Deal frameworks now force carbon cost allocations into every network planning scenario for European operators.
- Cargo Services:Freighter route planning integrates commodity-specific demand volatility, perishability constraints, and belly-hold capacity optimization against passenger schedules.
- Charter Operations:Ad-hoc routing tools accommodate mission-specific aircraft positioning without fixed network infrastructure.
- Codeshare Agreements:Revenue proration and schedule synchronization modules manage interline commercial terms across partner airlines.
Passenger Transport commands the dominant share of vendor revenue; Cargo Services is climbing the fastest as e-commerce flows reshape freighter network economics.
End User:
Customer type fragmentation creates distinct sales cycles and implementation complexity profiles across the value chain.
- Airline Operators:Carriers deploy integrated platforms combining pricing, scheduling, and emissions compliance into unified decision engines. Cloud migration pressure from full-service carriers in Asia-Pacific is compressing deployment cycles and forcing legacy on-premises vendors to rearchitect for multi-tenant elasticity.
- Aviation Consultants:Advisory firms license analytical modules for network restructuring and due diligence engagements.
- Travel Agencies:GDS-connected agencies access profitability dashboards for commission optimization and itinerary construction.
- Freight Forwarders:Cargo intermediaries utilize route planning tools to consolidate shipments across multiple carrier contracts.
Airline Operators represent the primary revenue concentration; Aviation Consultants are gaining share fastest as airline restructuring activity accelerates.
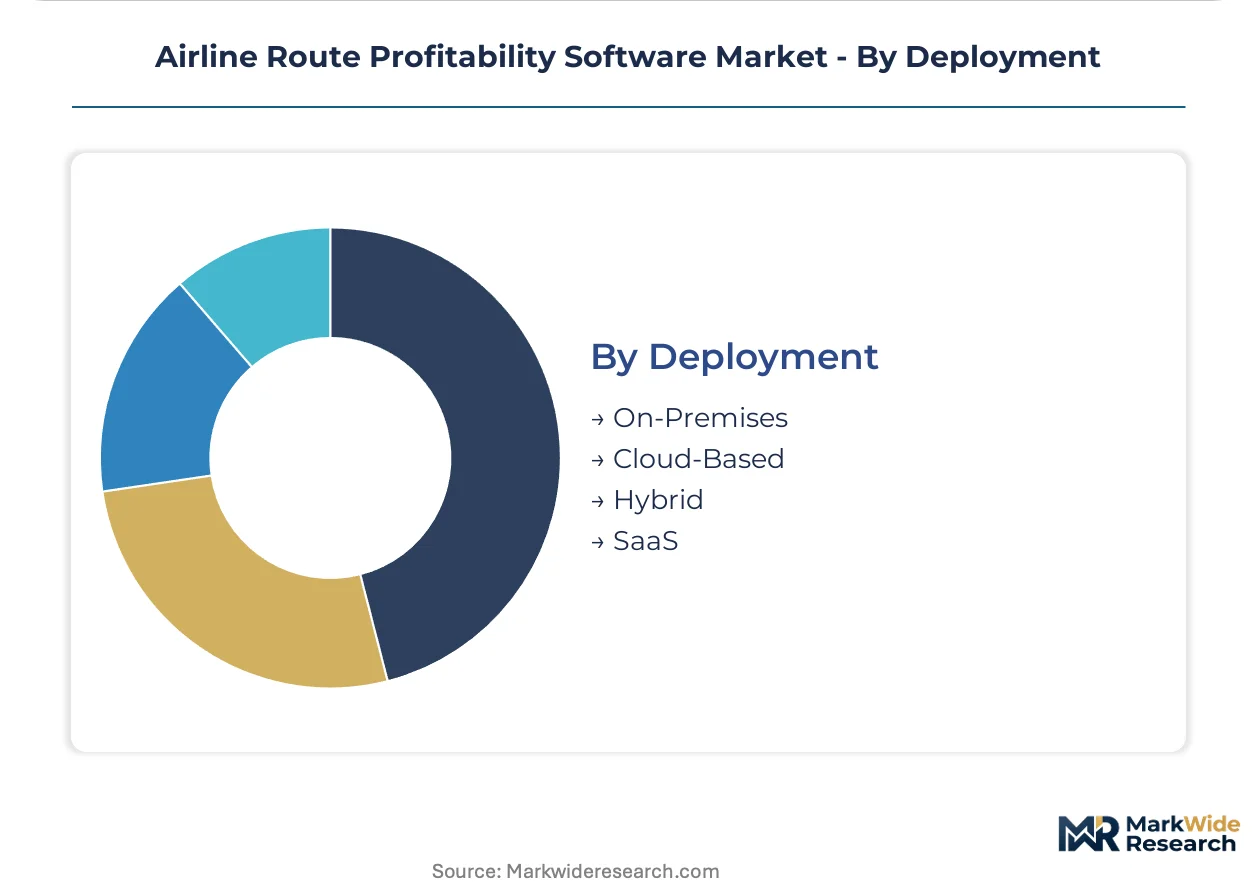
Deployment:
Maturity gradients separate established on-premises installations from emerging elastic compute architectures.
- Cloud-Based:Multi-tenant SaaS platforms deliver sub-second query response times across seasonal demand spikes without overprovisioning base capacity. India's PLI scheme for aviation infrastructure is accelerating domestic airline digitization mandates that favor cloud-native procurement.
- SaaS:Subscription delivery models concentrate margin pools among vendors capable of elastic infrastructure with specialized latency engineering.
- On-Premises:Legacy installations persist among carriers with stringent data sovereignty requirements or deep PSS integration debt.
- Hybrid:Split architectures maintain sensitive pricing data on-premises while offloading compute-intensive optimization to cloud instances.
On-Premises retains significant legacy footprint; Cloud-Based deployment is gaining share fastest as carriers prioritize operational flexibility over capital-intensive infrastructure ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel refining clusters in Singapore and Rotterdam anchor software procurement budgets for route optimization platforms. Carrier hubs in these localities drive demand for real-time margin analytics that integrate volatile energy costs into network planning.
United States
Full-service carriers based near Dallas and Chicago deploy enterprise revenue management systems for hub-and-spoke network optimization. FAA slot utilization mandates under 14 CFR Part 93 force dashboard customization that fragments vendor standardization efforts. Seattle's aerospace technology corridor hosts development centers where cloud-native architectures are tested against sub-second query requirements.
Germany
Lufthansa Group's Frankfurt and Munich hubs anchor European demand for integrated scheduling and emissions compliance modules. EU Green Deal frameworks under EASA jurisdiction embed carbon cost calculations directly into route planning algorithms, creating mandatory upgrade cycles. Berlin's aviation technology cluster concentrates vendor engineering teams serving Central European carriers.
India
Low-cost carriers operating from Delhi, Mumbai, and Bangalore digitize network planning operations under DGCA modernization directives. The PLI scheme for aviation infrastructure accelerates domestic airline procurement of cloud-based revenue management platforms. Hyderabad's IT corridor hosts delivery centers where SaaS implementations are configured for seasonal demand spikes.
Japan
ANA and JAL's Tokyo and Osaka hubs deploy graph neural network demand forecasting for long-haul network re-optimization. METI industrial policy supports AI-native pricing science adoption across full-service carrier commercial technology stacks. Nagoya's aerospace manufacturing belt influences adjacent software development for capacity planning modules.
Singapore
Singapore Airlines' Changi hub anchors Southeast Asian demand for dynamic pricing sophistication across premium and cargo segments. The country's aviation regulator mandates operational data transparency that favors multi-tenant cloud architectures. One-North technology district hosts regional headquarters for vendors serving Asia-Pacific carrier digitization programs.
Airline Route Profitability Software Market Competitive Environment
Global majors compete with regional champions across deployment architecture and regulatory compliance depth. The vendor base separates into three tiers: legacy PSS-integrated incumbents with on-premises heritage, cloud-native specialists with multi-tenant infrastructure, and aviation-focused boutiques with operations research DNA. Consolidation pressure intensifies as carriers seek unified platforms over point solutions. Dominant competitive moves include strategic partnerships with GDS providers and geographic expansion through local system integrators.
Within the integrated platform tier, Sabre Corporation and Amadeus IT Group SA exemplify vendors leveraging global distribution heritage to anchor enterprise-grade deployments. PROS Holdings, Inc. occupies a distinct position representing AI-native pricing science specialization embedded within route planning workflows. These three names capture divergent strategic archetypes: distribution-anchored breadth, hospitality-integrated cross-selling, and algorithmic pricing depth.
| Leading Market Players |
|---|
| Sabre Corporation |
| Amadeus IT Group SA |
| Lufthansa Systems |
| SITA |
| IBM Corporation |
| Oracle Corporation |
| PROS Holdings, Inc. |
| Seabury Solutions |
| Wipro Limited |
| Others |
Value Chain & Pricing Dynamics
Full-service carriers in Asia-Pacific anchor pricing power for cloud-native vendors, compressing deployment timelines and forcing subscription models that bundle implementation support with core platform access.
Pricing Analysis
Implementation services bundled into first-year contracts separate premium SaaS tiers from unbundled self-service configurations. Price differentiation rests on sub-second query performance guarantees and multi-tenant elasticity rather than feature depth alone. Cost compression in mid-market tiers is intensifying because legacy on-premises vendors are slashing migration incentives to defend installed base. Low-cost carriers in India exhibit highest price sensitivity; Singapore-based full-service carriers prioritize latency engineering over per-seat economics.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Ireland, and Singapore. Algorithm development draws from operations research talent pools in Germany, India, and Japan. Supply chain risk centers on regulatory data sovereignty requirements that fragment multi-tenant architectures across jurisdictional boundaries. Distribution runs through direct enterprise sales teams supplemented by aviation-specialized system integrators in regional technology corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase as graph neural networks displace static regression models for demand forecasting, compressing vendor consolidation timelines.
For Market Incumbents: Extend platform breadth through native emissions compliance modules before EASA mandates harden procurement criteria. Cloud migration pressure from Asia-Pacific full-service carriers threatens on-premises revenue streams; accelerate multi-tenant rearchitecture to defend renewal rates. Prioritize API friction reduction that currently extends SaaS deployment timelines. For New Entrants and Emerging Players: Enter via India's PLI scheme beneficiaries building greenfield digital capabilities without legacy migration burdens. Target mid-tier cargo operators in Rotterdam and Singapore where freighter network economics are reshaping procurement priorities. Lead with AI-native pricing science that merges machine learning yield engines with operations research solvers. For Investors and Strategic Acquirers: The window for entry favors aviation-focused boutiques with operations research DNA and existing airline PSS integration capabilities. Long-term viability hinges on unified platform positioning rather than point solution depth. Watch for carbon border adjustment mechanism announcements as inflection indicators for emissions-tracking software demand spreading to non-European carriers.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies pricing, scheduling, and emissions compliance into single vendor relationships for Asia-Pacific carriers. |
| Acquisition of Specialist Firm | Absorbs operations research talent scarce among incumbent vendors competing for PhD-level optimization specialists. |
| Strategic Partnership | Aligns with GDS providers to anchor enterprise-grade deployments through existing distribution heritage. |
| Geographic Expansion | Establishes delivery centers in Hyderabad and Berlin to serve DGCA modernization and EU Green Deal compliance cycles. |
| Product Launch | Introduces graph neural network demand forecasting modules that enable real-time network re-optimization for long-haul carriers. |
Study Parameters
Multi-period observation of carrier procurement cycles, vendor R&D roadmaps, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with airline network planning executives, revenue management directors, aviation technology procurement officers, and cloud infrastructure specialists. Secondary validation drew from EASA emissions monitoring directives, FAA slot utilization regulations, DGCA modernization circulars, SEC vendor filings, and IATA industry statistics. Bottom-up segment sizing triangulated against top-down market aggregation.
Input-output matrices mapped deployment model adoption curves, end-user digitization maturity, and regional regulatory compliance intensity across the analysis window. Segmentation dimensions modeled include product architecture, application domain, carrier type, and deployment elasticity. CAGRs were derived from slope analysis of technology substitution rates and procurement budget reallocation patterns. Forecast inputs incorporated cloud migration velocity indices and carbon pricing scenario sensitivity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or sudden slot allocation reforms. Projections reflect assumptions about algorithmic convergence timelines and carrier organizational consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Brand Management Software Market
Software & Services
Productivity Software Publishing Market
Software & Services
Global Time Series Analysis Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Pet Tracking Software Market
Software & Services
Online Recruitment Software Market
Software & Services
Pure Play Software Testing Market
Software & Services
Global Absence Management Software Market
Software & Services
Intellectual Property Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Global Product Lifecycle Management Software Market
Software & Services
Global Club Management Software Market
Software & Services
Global Third-Party Logistics Software Market
Software & Services
Global Campaign Management Software Market
Software & Services
Global Contract Management Software Market
Software & Services
Deck Design Software Market