
 Global Knowledge Management Software Market | 2026-2036
Global Knowledge Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Knowledge Management Software Market Foresight
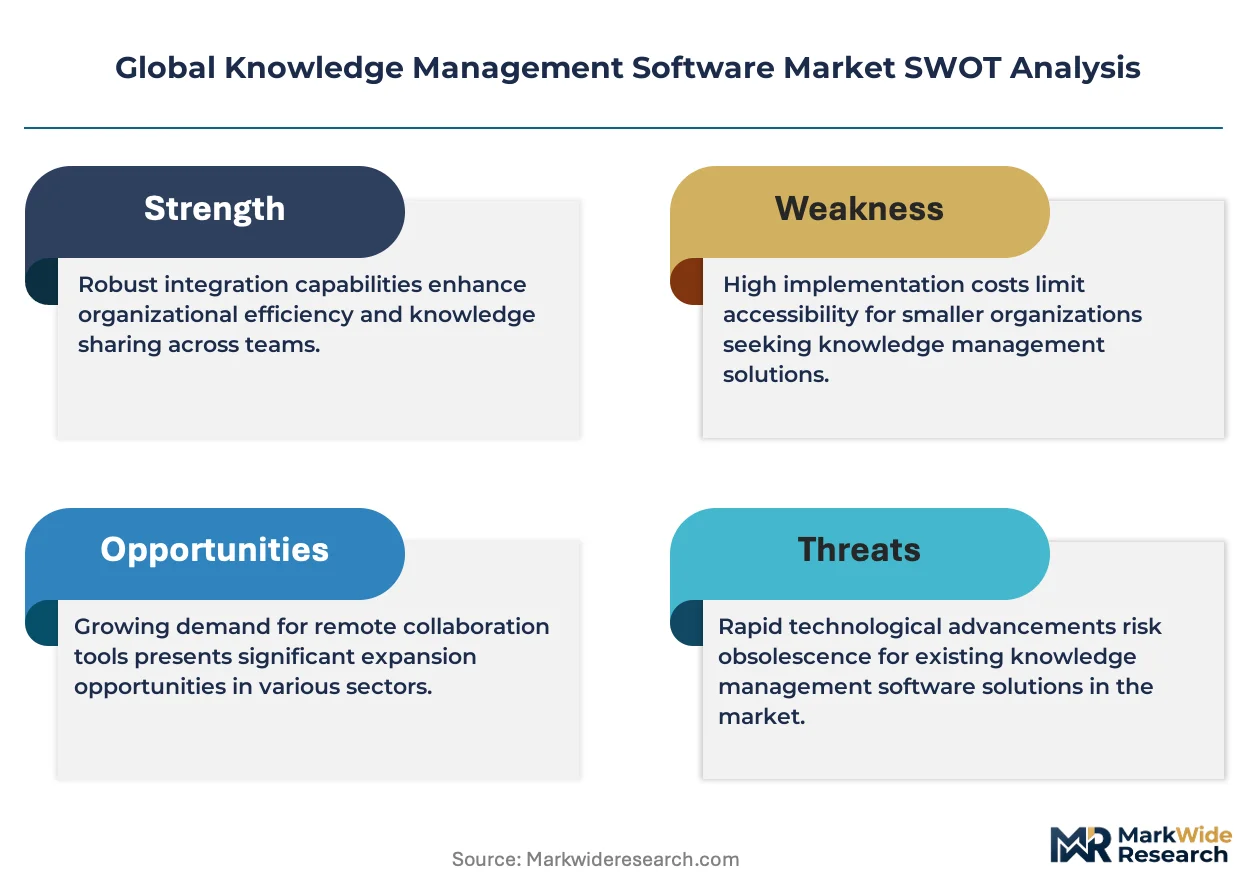
Subscription-based financing and asset-light SaaS procurement models are reshaping competitive dynamics in knowledge management software, lowering barriers for mid-market buyers to access enterprise-grade capabilities. Microsoft Corporation leverages its Azure cloud infrastructure to anchor integrated knowledge services within broader productivity suites. Salesforce sustains competitive positioning through deep CRM-knowledge layer connectivity. Atlassian Corporation specializes in developer-centric documentation and team collaboration tools that dominate technical knowledge workflows.
Knowledge management software encompasses platforms that capture, organize, retrieve, and distribute structured and unstructured organizational information through semantic search, natural language processing, and machine learning-driven recommendation engines. These systems serve the primary commercial purpose of reducing information retrieval latency and preserving institutional expertise across distributed workforces. Cloud-based deployment leads segment value contribution as enterprises prioritize elastic scalability and reduced capital expenditure, while workflow automation represents the fastest-expanding solution category as organizations seek to embed knowledge directly into operational processes. Content management retains mature, high-margin status among large government and financial services accounts with stringent archival requirements.
The EU AI Act and GDPR compliance obligations enforced by European regulators are elevating demand for auditable knowledge governance and consent-tracked information retrieval systems. The U.S. SEC record-keeping rules and HIPAA data access requirements similarly shape product specifications for financial and healthcare sector buyers. Stakeholders must monitor evolving cross-border data localization mandates and assess whether their knowledge architectures can adapt to fragmented sovereignty requirements without sacrificing unified search experiences.
Market Dynamics
AI-powered semantic search is collapsing traditional taxonomy-based information architectures, forcing vendors to reengineer core retrieval engines around large language models and vector embeddings.
Growth Catalysts
- GDPR Article 17 Right to Erasure:European enterprises are procuring knowledge governance platforms that automate consent tracking and data lineage documentation to satisfy deletion mandates.
- Financial Services Compliance Workflows:SEC record-keeping rules and MiFID II documentation requirements are driving unified platforms that merge client advisory notes with audit trails.
- Cloud-Native Microservices Architecture:Containerized deployment models are enabling elastic scaling of knowledge repositories without capital-intensive hardware procurement cycles.
Market Restraints
- Data Residency Fragmentation:Cross-border data localization mandates in Germany, India, and China are forcing vendors to maintain redundant infrastructure, elevating operational complexity.
- Legacy System Integration Debt:Decades-old enterprise content management systems impose API limitations that throttle real-time knowledge synchronization.
- Specialized Talent Scarcity:Shortages of machine learning engineers with domain expertise in natural language processing are constraining vendor R&D velocity.
Strategic Opportunities
- India's PLI Scheme for IT Hardware:Domestic data center incentives are creating localized cloud infrastructure for knowledge platforms serving regulated sectors.
- Workflow Automation Convergence:Integration of robotic process automation with knowledge retrieval is embedding intelligence directly into operational decision points.
- Small and Medium Enterprise Channel:Verticalized SaaS marketplaces are democratizing access to enterprise-grade knowledge capabilities for mid-market buyers.
Industry Challenges
- Algorithmic Auditability Requirements:EU AI Act mandates for explainable recommendations are forcing engineering teams to retrofit opaque neural networks with interpretable output layers.
- Multi-Cloud Orchestration Complexity:Enterprises distributing knowledge workloads across Azure, AWS, and Google Cloud are encountering synchronization failures and latency inconsistencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Knowledge Management Software Market |
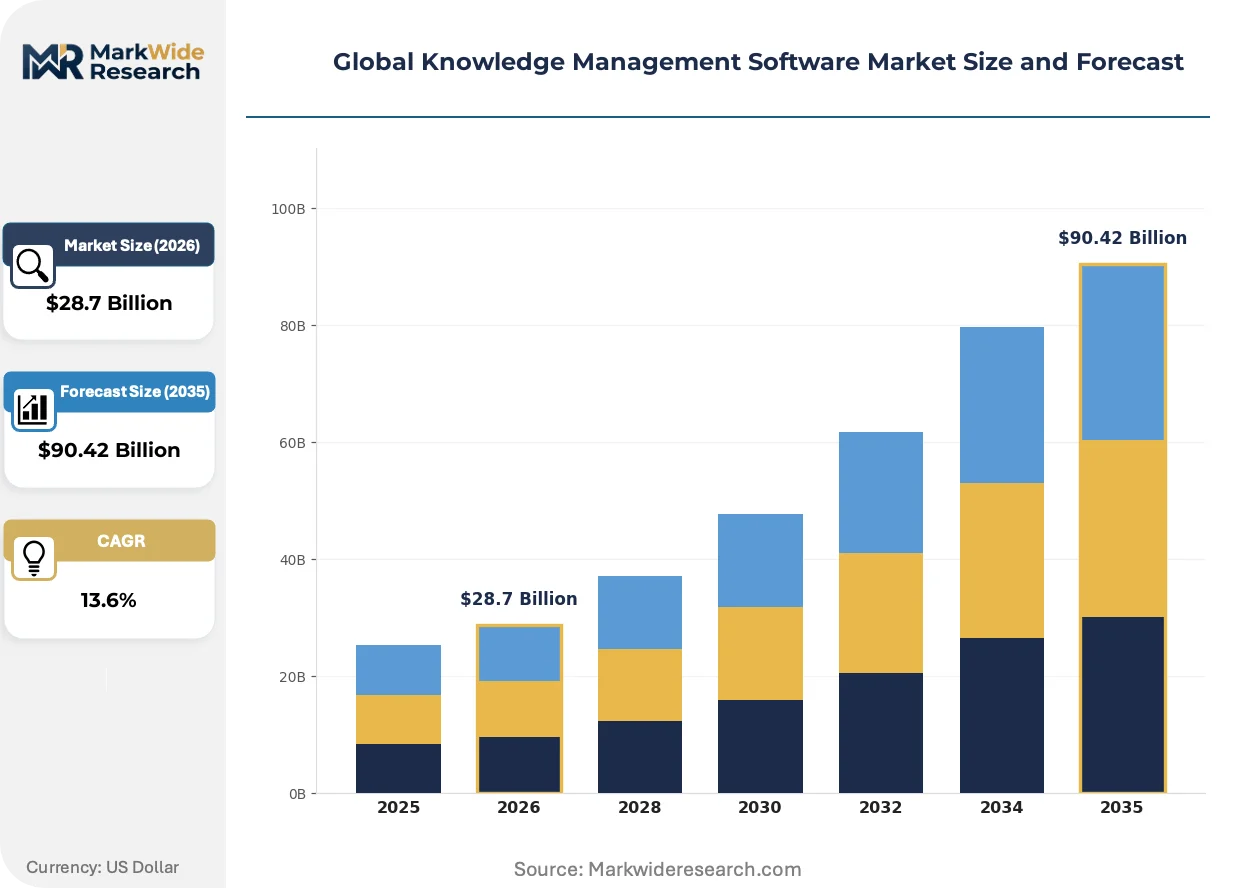
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $90.42 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Offering: Content Management, Collaboration, Document Management, Workflow Automation, Analytics Use Case: Customer Support, Product Development, Sales Enablement, Compliance Management, Employee Training End User Industry: Information Technology, Telecommunications, Financial Services, Government Agencies, Education |
| Companies Covered | Salesforce, Zendesk, Microsoft Corporation, Coveo, Notion Labs, Atlassian Corporation, IBM Corporation, OpenText Corporation, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Knowledge Management Software Market Shifts & Advancements
Generative AI is fundamentally altering how organizations capture and distribute expertise, compressing the gap between information creation and actionable retrieval. Three interconnected developments are restructuring competitive dynamics.
Retrieval-augmented generation architectures are collapsing the distinction between static knowledge bases and dynamic conversational interfaces. Enterprise buyers in financial services and healthcare are deploying these systems to surface regulated content through natural language queries rather than Boolean search strings. The structural consequence is collapsing traditional document management licensing models as per-seat pricing gives way to consumption-based API metering.
The EU AI Act's risk-based classification framework is elevating documentation requirements for high-stakes knowledge applications. Providers serving credit underwriting and medical diagnosis workflows must maintain model cards, training data provenance, and human oversight logs. German automotive manufacturers and French pharmaceutical firms are advancing procurement specifications that disqualify vendors lacking auditable governance tooling.
Outcome-based engagement models are displacing perpetual license agreements in enterprise software procurement. Buyers in United States healthcare systems and United Kingdom professional services firms are contracting for measurable reductions in information retrieval time or compliance incident rates. This shift concentrates vendor risk but accelerates adoption among budget-constrained public sector organizations seeking guaranteed performance thresholds.
Global Knowledge Management Software Market Segmentation
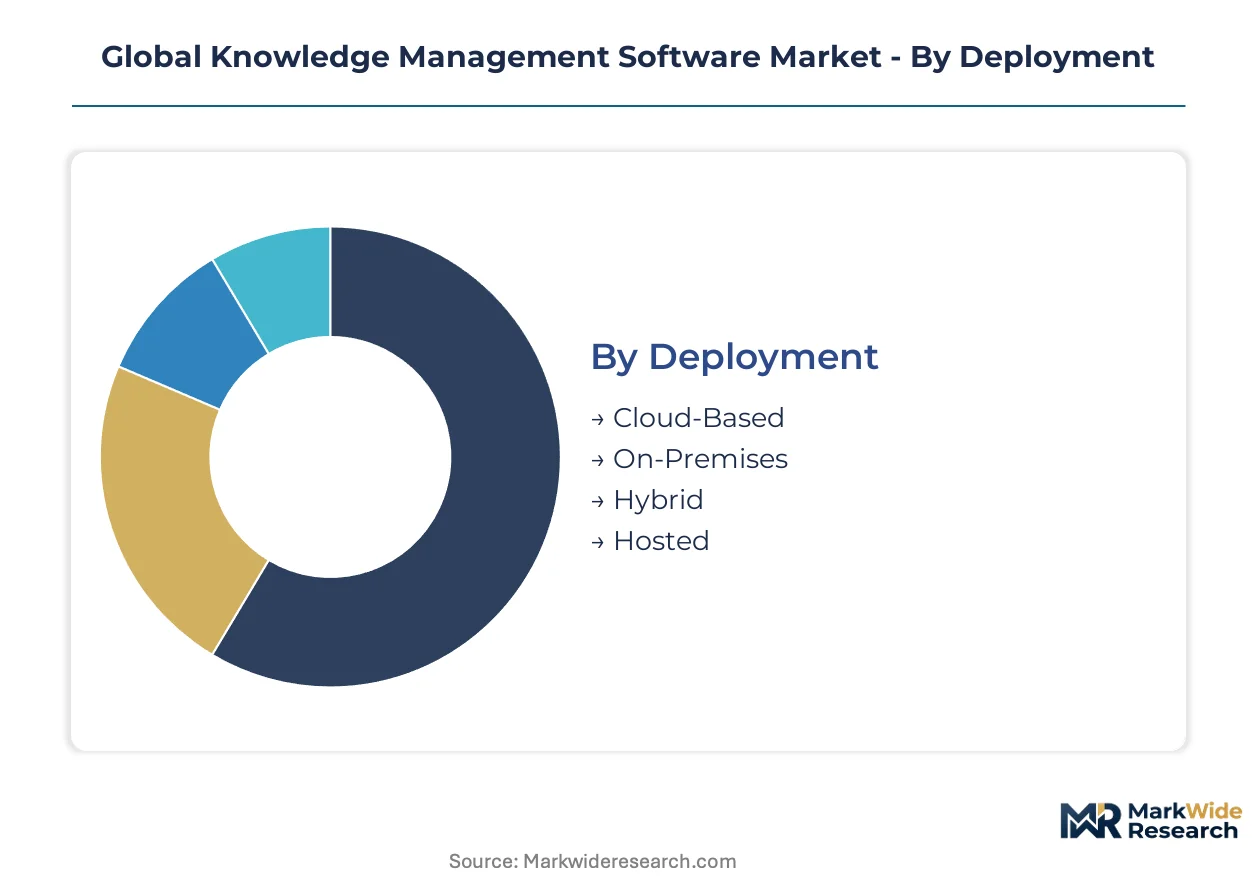
Segmentation in knowledge management software reveals how deployment architecture, solution depth, and industry verticals create distinct procurement patterns. Buyers prioritize different capability bundles based on regulatory exposure, workforce distribution, and integration complexity with legacy systems.
Deployment:
After-sales service intensity varies dramatically across deployment modes, with cloud-based implementations demanding continuous vendor engagement for security patching and API maintenance while on-premises solutions shift operational burden to internal IT teams.
- Cloud-Based:Multi-tenant architectures with elastic scaling capabilities serve distributed workforces through browser-based interfaces. Financial services firms in the United States and Germany are consolidating procurement around these platforms to satisfy GDPR Article 17 erasure mandates and SEC record-keeping rules without capital-intensive infrastructure.
- On-Premises:Dedicated hardware installations within corporate data centers preserve complete data sovereignty and offline availability. Government agencies in India and defense contractors across multiple geographies specify these deployments to meet classified information handling protocols and BIS cybersecurity certifications.
- Hybrid:Split workloads between private infrastructure and public cloud orchestration balance latency-sensitive operations with burst capacity. Manufacturing clusters in Germany leverage this architecture to keep proprietary design data local while pushing collaborative documentation to shared environments.
- Hosted:Single-tenant cloud environments managed by third-party providers deliver dedicated resource isolation without capital expenditure. Mid-market professional services firms in the United Kingdom prefer this model for client-matter confidentiality without internal infrastructure expertise.
Cloud-Based deployments hold the largest share; momentum sits with Hybrid configurations as enterprises navigate fragmented data sovereignty requirements.
Solution Offering:
Margin profiles diverge sharply across solution categories, with workflow automation commanding premium pricing for embedded intelligence while content management competes on scale economies and archival compliance depth.
- Content Management:Structured repositories with versioning, retention policies, and legal hold capabilities preserve institutional records. Large government accounts and financial services institutions in Germany prioritize these systems for MiFID II documentation retention and GDPR audit trail maintenance.
- Collaboration:Real-time editing, threaded discussions, and presence awareness synchronize distributed team knowledge creation. Technology sector buyers in India and the United States drive procurement volume as remote engineering teams require seamless handoff of technical specifications.
- Document Management:Capture, indexing, and retrieval systems for scanned and native electronic files. Healthcare networks under HIPAA compliance in the United States specify these for patient record lifecycle management.
- Workflow Automation:Rule-based routing and robotic process automation embedding knowledge retrieval into operational decision points. Banking operations in India and insurance claims processing in the United States are expanding fastest here.
- Analytics:Usage pattern analysis, knowledge gap identification, and expertise location mapping. Human capital-intensive consultancies in the United Kingdom deploy these to quantify knowledge asset utilization.
Content Management retains the largest installed base; Workflow Automation gains share fastest as operational intelligence demands intensify.
Use Case:
Application context determines integration architecture, with customer-facing scenarios requiring CRM connectivity and compliance use cases demanding immutable audit trails.
- Customer Support:Unified agent desktops surfacing resolution knowledge across channels. Telecommunications providers in India and the United States standardize on these to reduce average handle times and improve first-contact resolution rates.
- Product Development:Technical specification libraries, lessons-learned repositories, and cross-functional design collaboration. Automotive manufacturers in Germany and software firms in the United States anchor R&D productivity around these capabilities.
- Sales Enablement:Competitive intelligence, proposal templates, and objection handling guidance synchronized to CRM opportunity stages. Financial services advisors under MiFID II in Germany and SEC jurisdiction in the United States require embedded compliance documentation.
- Compliance Management:Policy distribution, attestation tracking, and regulatory change management with defensible audit trails. Healthcare systems under HIPAA in the United States and EU AI Act-covered entities in Germany specify these for demonstrable governance.
- Employee Training:Curated learning paths, competency assessment, and expertise certification tracking. Education institutions and corporate learning functions in India and the United Kingdom prioritize skills-based progression mapping.
Customer Support holds the largest share; Compliance Management climbs fastest as regulatory enforcement tightens across jurisdictions.
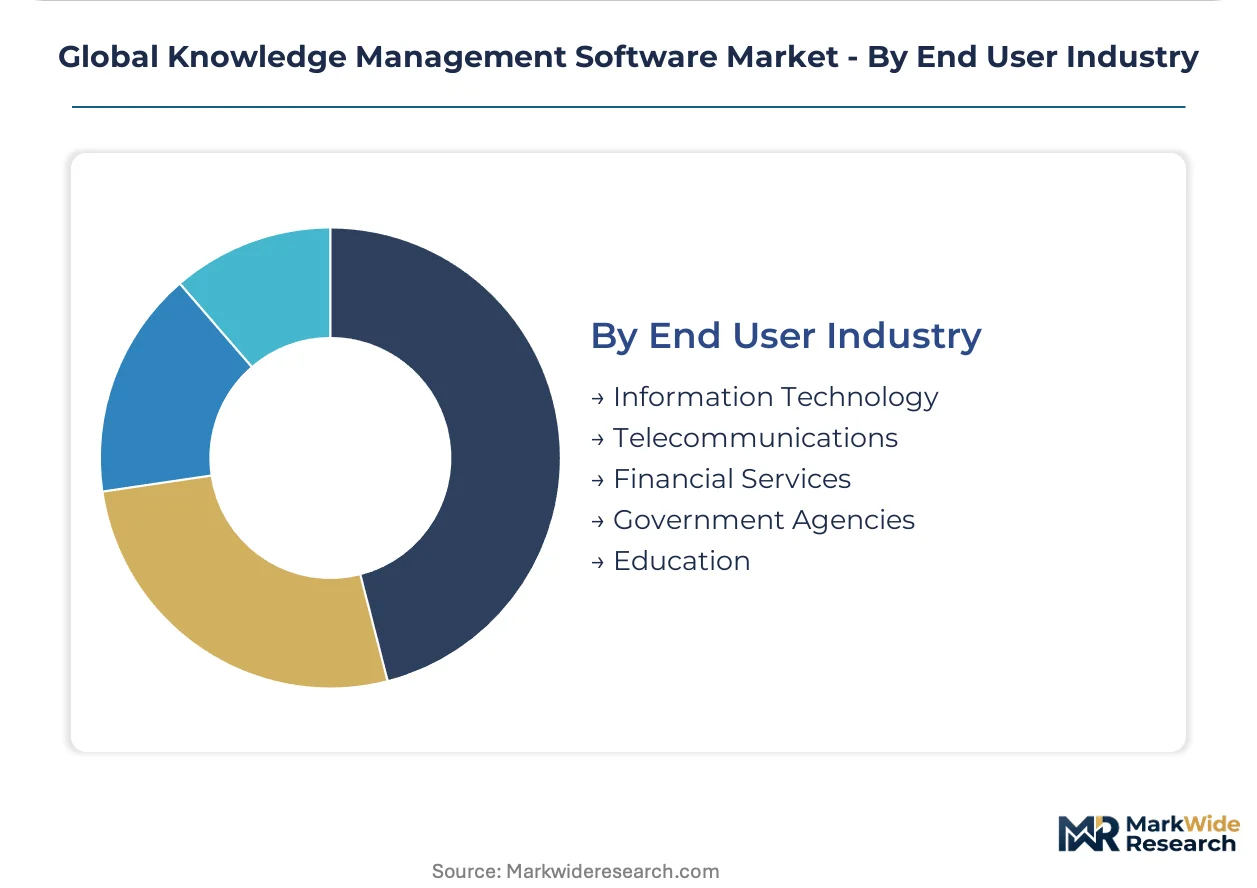
End User Industry:
Customer type concentration shapes vendor specialization, with financial services and government segments demanding certified security architectures that mid-market technology buyers rarely require.
- Information Technology:Developer documentation, API knowledge bases, and agile team coordination. Software firms in the United States and India dominate procurement volume with rapid iteration cycles and distributed engineering teams.
- Telecommunications:Network operations documentation, customer service knowledge, and regulatory filing management. Operators in India and Germany maintain extensive proprietary technical libraries for infrastructure maintenance.
- Financial Services:Client advisory workflows, transaction documentation, and compliance record retention. Banks and asset managers under SEC, MiFID II, and RBI supervision across the United States, Germany, and India represent the most demanding specification environment.
- Government Agencies:Classified information handling, public service delivery knowledge, and inter-agency coordination. National and state-level bodies in India, Germany, and the United States specify FedRAMP, BIS, or comparable security certifications.
- Education:Curriculum repositories, research collaboration platforms, and administrative process documentation. Universities and vocational institutions in the United Kingdom and India are modernizing legacy library systems.
Information Technology holds the largest share; Financial Services expands most quickly as advisory digitization and regulatory documentation demands converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial services firms and technology enterprises dominate procurement across concentrated metropolitan clusters, with regulatory enforcement intensity determining deployment architecture choices.
United States
SEC record-keeping rules and HIPAA data access requirements drive unified platform adoption among asset managers and healthcare networks. Financial advisors under MiFID II-equivalent supervision require embedded compliance documentation. New York and San Francisco metropolitan areas concentrate SaaS procurement decisions for enterprise knowledge infrastructure.
Germany
GDPR Article 17 erasure mandates and EU AI Act algorithmic auditability requirements elevate demand for consent-tracked retrieval systems. Automotive manufacturers in Bavaria and pharmaceutical firms in Baden-Württemberg specify auditable governance tooling for high-stakes knowledge applications.
India
PLI scheme incentives for IT hardware and RBI supervisory expectations accelerate localized cloud infrastructure procurement. Banking operations in Mumbai and technology services clusters in Bangalore expand workflow automation deployments for operational intelligence embedding.
United Kingdom
Professional services firms under outcome-based contracting models prioritize measurable retrieval time reductions. London-based consultancies and Manchester healthcare systems drive consumption-based API metering adoption over perpetual licensing.
Japan
METI industrial digitization programs and aging workforce expertise preservation needs stimulate knowledge capture platform investment. Manufacturing headquarters in Tokyo and Osaka prefectures deploy semantic search to collapse information retrieval latency.
Global Knowledge Management Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Cloud hyperscalers leverage infrastructure dominance to bundle knowledge services within productivity suites. Pure-play specialists differentiate through vertical workflow depth and developer-centric tooling. Independent software vendors anchor mid-market penetration through verticalized SaaS marketplaces. Strategic moves concentrate on M&A for AI retrieval capabilities and strategic partnerships for multi-cloud orchestration.
Within the platform-integrated tier, Microsoft Corporation and Salesforce exemplify archetypes that embed knowledge layers within broader enterprise software ecosystems. Atlassian Corporation occupies a position representing developer-centric documentation specialists that dominate technical knowledge workflows. These three entities collectively illustrate how competitive positioning stratifies between infrastructure-anchored bundling and workflow-specific depth.
| Leading Market Players |
|---|
| Salesforce |
| Zendesk |
| Microsoft Corporation |
| Coveo |
| Notion Labs |
| Atlassian Corporation |
| IBM Corporation |
| OpenText Corporation |
| ServiceNow |
| Others |
Supply & Pricing Matrix
Elastic compute overcapacity across United States and Western European hyperscaler regions compresses infrastructure margins while amplifying pricing leverage for knowledge platform vendors with differentiated AI retrieval capabilities. This utilization asymmetry rewards vendors who bundle proprietary semantic search layers atop commodity cloud resources.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FedRAMP-authorized and ISO 27001-certified deployments commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels aligns with compliance depth, with financial services and government buyers absorbing premium tiers for auditable governance while mid-market technology firms cluster in standard consumption-based API metering. Cost compression in economy tiers intensifies as open-source retrieval engines commoditize basic semantic search functionality. Price-sensitive buyers concentrate among small professional services firms lacking dedicated procurement functions, while least-sensitive demand flows from United States healthcare networks under HIPAA enforcement and German automotive manufacturers facing EU AI Act documentation mandates.
Supply Chain Analysis
Upstream feedstock for knowledge management platforms draws from three concentrated technology bases: United States hyperscaler infrastructure, Taiwan semiconductor fabrication for AI acceleration hardware, and Indian software engineering talent pools for natural language processing development. Raw material dependencies center on GPU compute clusters, vector database licensing, and pretrained large language model APIs. Single-source vulnerability concentrates in NVIDIA's dominance of training-grade silicon, creating procurement risk for vendors scaling retrieval-augmented generation architectures. Distribution runs through direct enterprise sales organizations for large accounts, supplemented by cloud marketplace channels for mid-market consumption and verticalized SaaS resellers serving regulated industry niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from generative AI-native entrants offering conversational knowledge interfaces that bypass traditional taxonomy investments. Defense requires embedding proprietary retrieval capabilities into operational workflows before standalone chat interfaces capture user attention.
For Market Incumbents: Build data moat depth by capturing proprietary vertical knowledge graphs in financial services and healthcare before open-source models erode differentiation. Acquire specialized workflow automation vendors to embed retrieval into operational decision points rather than remaining at the information layer. Channel control through hyperscaler marketplace positioning defends against API commoditization threatening per-seat pricing models.
For New Entrants and Emerging Players: Build out verticalized solutions for compliance management use cases in United Kingdom professional services and Indian banking operations where incumbent platforms show integration fragility. White-space opportunity concentrates in mid-market manufacturing clusters across Germany seeking hybrid deployment architectures for proprietary design data protection. Go-to-market leverage rests on outcome-based contracting guaranteeing measurable retrieval time reductions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among workflow automation specialists embedding knowledge retrieval into operational processes rather than standalone content repositories. Long-term viability favors vendors with demonstrated EU AI Act compliance tooling and multi-cloud orchestration capabilities. Acquisition target archetype combines vertical workflow depth with auditable governance infrastructure. Signal to watch: procurement specification shifts toward explainable recommendation requirements in German automotive and French pharmaceutical tenders.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding knowledge layers within Microsoft Azure and Salesforce CRM ecosystems captures enterprise procurement consolidation. |
| Acquisition of Specialist Firm | Vertical workflow depth in financial services compliance documentation defends against generative AI-native substitution. |
| Strategic Partnership | Multi-cloud orchestration alliances with AWS and Google Cloud address synchronization failures troubling distributed deployments. |
| Product Launch | Retrieval-augmented generation architectures collapse document management licensing models toward consumption-based API metering. |
| Geographic Expansion | Localized cloud infrastructure under India's PLI scheme serves RBI-supervised banking operations with data residency compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K disclosures, hyperscaler capex reports, and regulatory filing databases covering GDPR enforcement actions and EU AI Act implementation guidance. Primary interviews engaged chief technology officers, IT procurement officers, platform engineers, and channel partners across United States, Germany, and India. Secondary validation drew from cloud marketplace transaction data, enterprise software licensing registries, and compliance certification listings. Bottom-up deployment estimates triangulate against top-down market sizing from vendor revenue disclosures and installed base proxies.
Forecast inputs incorporate deployment model migration patterns, vertical adoption intensity, and regulatory enforcement trajectories across the analysis window. Segmentation dimensions modeled include deployment architecture, solution offering depth, use case application, end-user industry vertical, organization size tier, and regional adoption pattern. CAGRs derive from elasticity-adjusted growth rate projections calibrated to historical technology substitution cycles. Industry-specific inputs center on GDPR Article 17 automation demand and SEC record-keeping digitization timelines.
Sensitivities concentrate around cross-border data localization mandate expansion, generative AI capability commoditization velocity, and hyperscaler pricing power shifts. Forecasts embed assumptions regarding regulatory enforcement consistency and enterprise cloud migration continuity. Cross-checking against vendor-reported annual recurring revenue benchmarks and compliance certification issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Stock Media Software Market
Software & Services
Global SEO Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Global Virtual Data Room (VDR) Market
Software & Services
Backend-As-A-Service Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
North America Deck Design Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Embedded Software and Tools Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
HVAC Solution Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
Test Management Software Market