
 Global Customer Experience Software Market | 2026-2036
Global Customer Experience Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Customer Experience Software Market Foresight
Subscription-based delivery of real-time sentiment analysis and predictive routing modules is rebalancing how vendors monetize customer experience platforms. Salesforce Service Cloud leverages its AppExchange ecosystem to sustain developer loyalty across enterprise accounts. Zendesk anchors its position in mid-market segments through intuitive agent-workflow design. Qualtrics dominates experience management by embedding statistical modeling directly into survey-to-action pipelines.
Customer experience software encompasses applications that capture, analyze, and act upon behavioral signals across touchpoints through APIs, machine-learning inference layers, and unified identity resolution; its primary commercial purpose is reducing churn cost and compressing feedback-to-remediation cycles. Voice of Customer platforms lead solution-type revenue by operationalizing unstructured feedback into service tickets. Cloud-Based deployment captures the majority of new bookings as enterprises retire on-premises call-center hardware. Customer Journey Analytics represents the fastest-expanding solution type because it connects marketing spend to downstream retention outcomes.
The EU AI Act, GDPR, and HIPAA constrain how experience platforms process biometric sentiment data and cross-border customer records, forcing vendors to architect region-specific data residency. The Federal Communications Commission shapes telephony-integrated software through robocall mitigation rules that affect outbound engagement channels. Stakeholders must weigh sovereign-cloud requirements against the latency advantages of centralized AI training infrastructure.
Market Dynamics
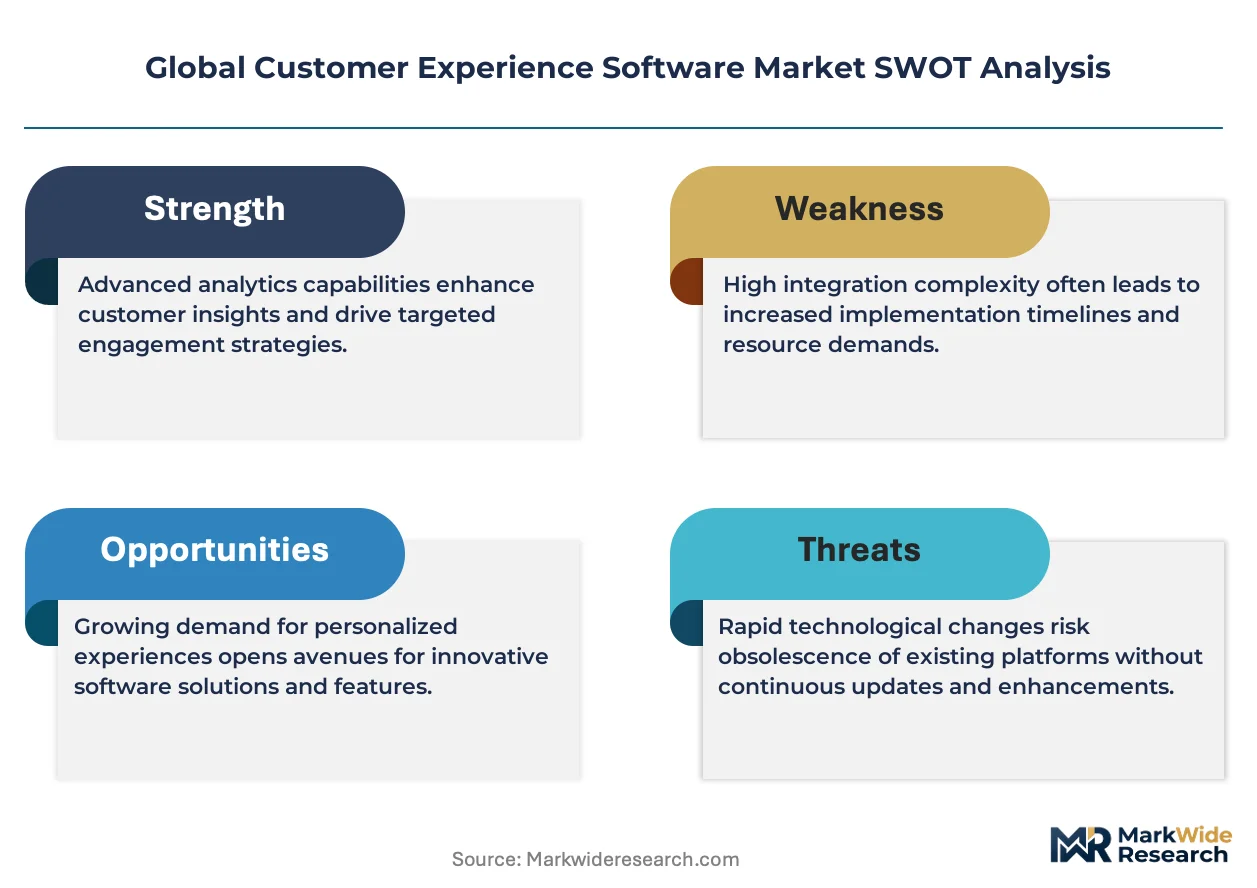
Real-time sentiment inference at the edge is compressing feedback-to-action cycles from weeks to minutes, forcing vendors to rearchitect data pipelines around low-latency processing nodes rather than centralized cloud warehouses.
Growth Catalysts
- EU AI Act compliance mandates:Financial services institutions in Germany and France must deploy auditable decision trails for automated customer interactions, accelerating procurement of consent-management layers.
- Contact center modernization cycles:Legacy telephony infrastructure in the United States is reaching end-of-life, creating replacement demand for API-first engagement platforms that unify voice, chat, and asynchronous messaging.
- Biometric authentication integration:Voiceprint and facial recognition modules are embedding into authentication flows, reducing fraud losses while streamlining customer verification across banking and healthcare portals.
Market Restraints
- Cross-border data fragmentation:GDPR data-residency requirements and India's data-localization directives force vendors to maintain redundant infrastructure across Frankfurt, Mumbai, and Virginia, inflating operational overhead.
- GPU compute cost volatility:Training and inference for large-language customer service models depends on NVIDIA H100 availability, creating margin pressure when semiconductor supply tightens.
- Interoperability limitations:Proprietary data schemas in legacy CRM systems resist API integration, requiring expensive middleware development for enterprise deployments.
Strategic Opportunities
- India's digital public infrastructure:The Account Aggregator framework and UPI payment rails enable consent-based financial data sharing, opening embedded finance experiences for CX platforms targeting retail banking.
- Predictive churn modeling:Machine learning pipelines that correlate product usage telemetry with cancellation signals are expanding into subscription software and telecommunications verticals previously underserved by journey analytics.
- Regulatory sandboxes:The UK's Financial Conduct Authority and Monetary Authority of Singapore are permitting limited deployments of AI-driven customer engagement tools under supervised experimentation, reducing compliance risk for early movers.
Industry Challenges
- Conversational AI training data scarcity:High-quality multilingual dialogue corpora for Indic languages and regional Arabic dialects remain limited, degrading intent recognition accuracy in emerging markets.
- ISO 27001 and SOC 2 certification timelines:Enterprise procurement committees require completed audits before contract execution, extending sales cycles by four to six months for vendors lacking pre-existing attestations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Customer Experience Software Market |
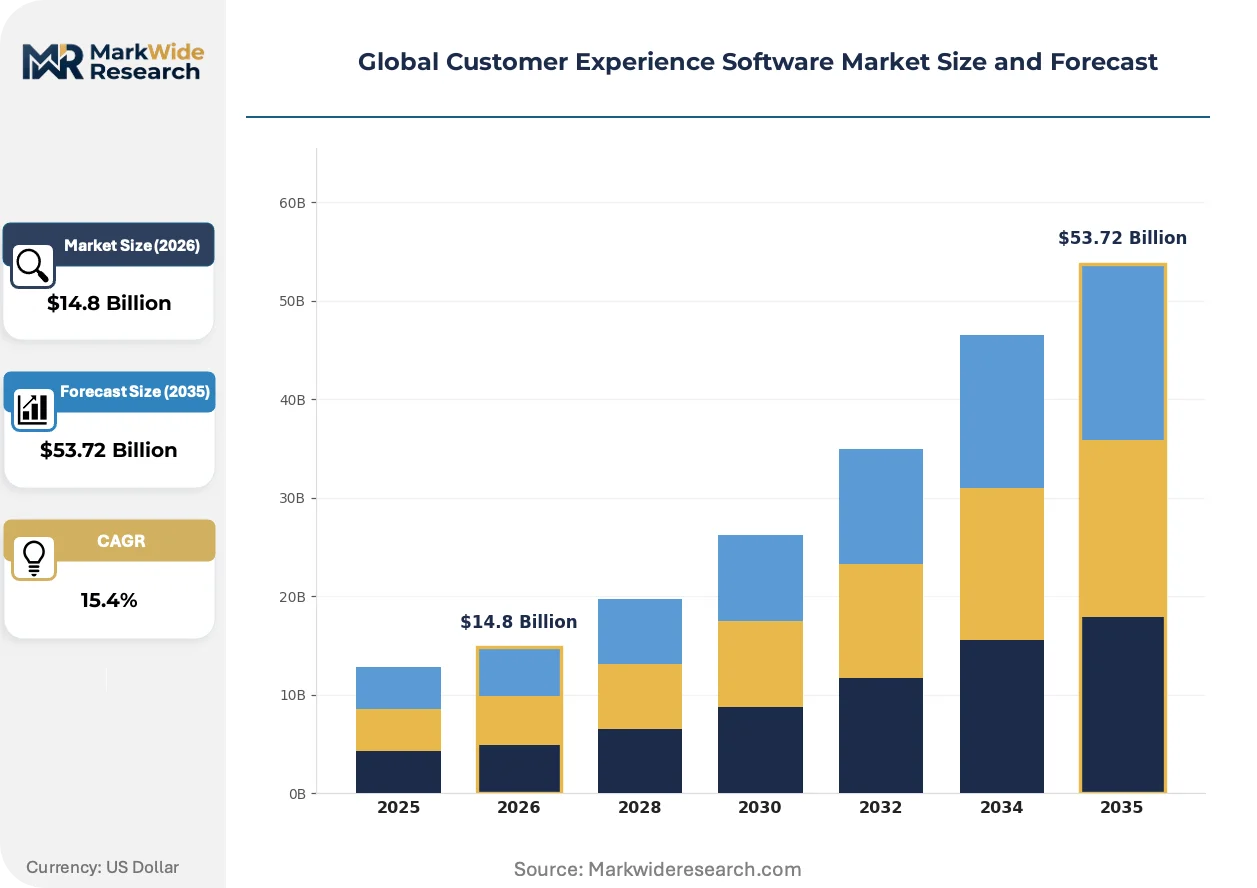
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $53.72 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution Type: Voice of Customer, Customer Journey Analytics, Customer Data Platform, Engagement Management, Personalization Engine Application: Customer Support, Sales Enablement, Marketing Optimization, Product Feedback Analysis, Loyalty Programs End User Industry: BFSI Institutions, Telecommunications Providers, Hospitality Operators, Education Services, Public Sector Agencies |
| Companies Covered | HubSpot, Sogolytics, Qualtrics, Microsoft Dynamics 365, Salesforce Service Cloud, Medallia, Adobe Experience Manager, Genesys, Zendesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Customer Experience Software Market Shifts & Advancements
Edge-deployed inference engines and sovereign-cloud architectures are redistributing where customer intelligence gets processed, shifting competitive advantage from scale to latency-optimized localization.
Real-time emotion detection is expanding into video-based support channels, analyzing micro-expressions during telehealth consultations and high-value insurance claims. Healthcare providers in the United States are piloting these tools to flag patient distress before abandonment. The technology is expanding into compliance documentation, automatically tagging interactions requiring human supervisor review under HIPAA and state-level telemedicine regulations.
The EU AI Act's risk-based classification system imposes documentation burdens on high-risk customer-facing automation, including credit scoring and biometric identification. Vendors must maintain technical files and conformity assessments for each algorithmic component. German automotive finance subsidiaries and Dutch insurance underwriters are most affected, restructuring procurement checklists to prioritize providers with pre-established EU notified-body relationships.
Enterprise buyers are unbundling monolithic CX suites, purchasing best-of-breed sentiment analysis, workforce management, and journey orchestration tools through marketplace integrations rather than single-vendor contracts. Mid-market retailers in India and Southeast Asia are driving this fragmentation, stitching together Twilio communications infrastructure with localized WhatsApp Business API providers and domestic payment gateways.
Global Customer Experience Software Market Segmentation
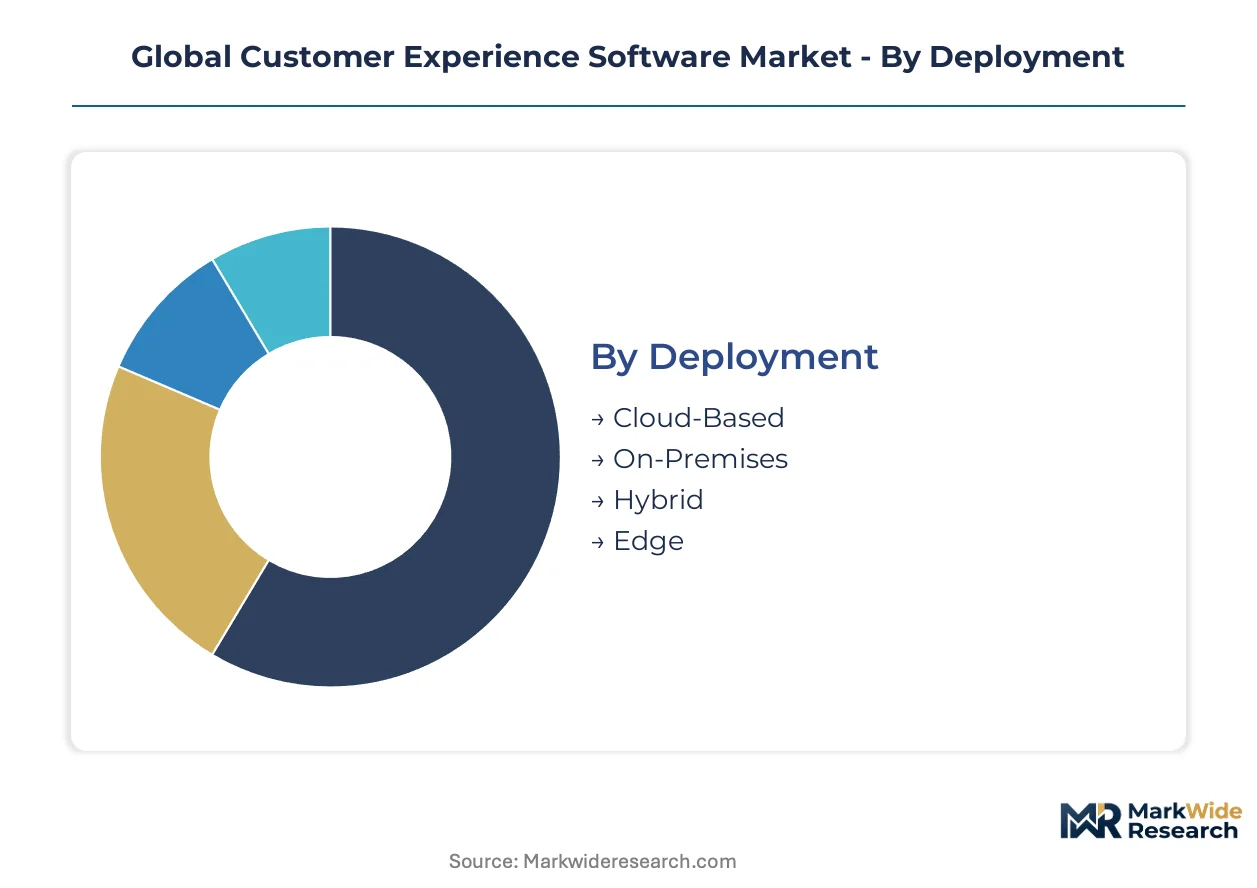
Deployment architecture determines latency performance and compliance posture for customer experience platforms. Solution type selection reflects whether enterprises prioritize feedback capture, journey visualization, or real-time personalization. Application focus and end-user industry shape integration requirements and pricing elasticity.
Deployment:
Supply concentration in hyperscale cloud regions is redistributing toward sovereign and edge alternatives.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for sentiment analysis and predictive routing. Financial services institutions in Germany and the United States are retiring on-premises call-center hardware, though EU AI Act documentation burdens are extending procurement cycles. This deployment mode captures the majority of new bookings as enterprises prioritize API-first engagement platforms.
- On-Premises:Dedicated infrastructure within enterprise data centers preserves full control over biometric authentication flows and patient records. Healthcare providers in the United States under HIPAA constraints maintain these deployments for telehealth consultations requiring human supervisor review protocols.
- Hybrid:Workload orchestration across private and public environments balances latency-sensitive inference at the edge with centralized model training. Telecommunications providers in India use this architecture to comply with data-localization directives while leveraging cloud analytics.
- Edge:Inference engines deployed at point-of-presence nodes compress feedback-to-action cycles from weeks to minutes. Hospitality operators in Singapore pilot real-time emotion detection for high-value guest interactions.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge.
Solution Type:
Cost tier differentiation separates enterprise-grade statistical modeling from mid-market workflow automation.
- Voice of Customer:Platforms operationalizing unstructured feedback into service tickets through survey-to-action pipelines. BFSI institutions in France deploy these tools for auditable decision trails under EU AI Act mandates.
- Customer Journey Analytics:Correlation engines connecting marketing spend to downstream retention outcomes. Expanding most quickly because subscription software and telecommunications verticals previously underserved by journey analytics are adopting predictive churn modeling.
- Customer Data Platform:Unified identity resolution across fragmented touchpoints. Retail banking in India leverages Account Aggregator framework consent rails for embedded finance experiences.
- Engagement Management:Workforce optimization and agent routing for omnichannel contact centers. Public sector agencies in Germany modernize legacy telephony through these modules.
- Personalization Engine:Real-time recommendation systems driven by behavioral signal processing. Education services in the United States deploy these for adaptive learning pathways.
Voice of Customer dominates current procurement volumes. Customer Journey Analytics shows the steepest expansion trajectory.
Application:
Volume concentration in customer support is fragmenting as sales and marketing functions adopt specialized tools.
- Customer Support:Ticket management, knowledge bases, and agent assist layers for issue resolution. Hospitality operators in Southeast Asia stitch together Twilio infrastructure with WhatsApp Business API providers for this function.
- Sales Enablement:Conversation intelligence and pipeline analytics for revenue teams. BFSI institutions in Singapore pilot AI-driven engagement tools under Monetary Authority of Singapore regulatory sandboxes.
- Marketing Optimization:Campaign attribution and audience segmentation for acquisition efficiency. Telecommunications providers in Germany use these applications to reduce churn cost.
- Product Feedback Analysis:Telemetry correlation with feature usage and cancellation signals. Subscription software vendors in the United States deploy machine learning pipelines here.
- Loyalty Programs:Points orchestration and reward personalization for retention. Education services in India experiment with these for student engagement.
Customer Support anchors installed base. Sales Enablement is gaining share fastest among new deployments.
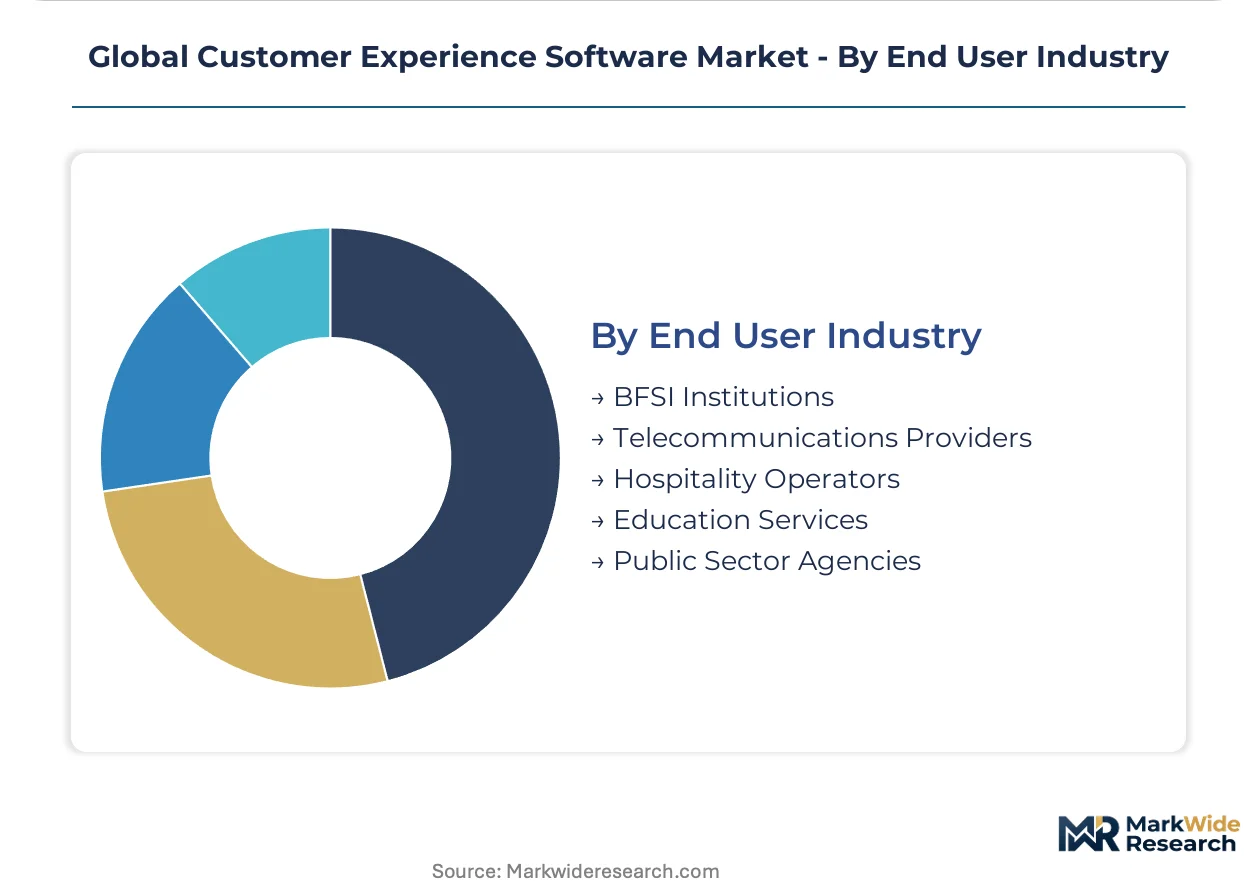
End User Industry:
Margin structures vary sharply between regulated financial services and cost-constrained public sector procurement.
- BFSI Institutions:Banks, insurers, and wealth managers requiring biometric authentication and fraud prevention. German automotive finance subsidiaries restructure procurement checklists to prioritize EU notified-body relationships for algorithmic credit scoring components.
- Telecommunications Providers:Subscription-based carriers managing high-volume support interactions. These enterprises in the United States face FCC robocall mitigation rules affecting outbound engagement channels.
- Hospitality Operators:Hotels, airlines, and restaurants prioritizing guest experience and loyalty. Micro-expression analysis during high-value claims interactions is piloting in this sector.
- Education Services:Universities and edtech platforms deploying adaptive learning and student success analytics. ISO 27001 certification timelines extend sales cycles here by four to six months.
- Public Sector Agencies:Government contact centers and citizen service portals. GDPR data-residency requirements and India's data-localization directives force redundant infrastructure across Frankfurt, Mumbai, and Virginia for these deployments.
BFSI Institutions command premium pricing. Telecommunications Providers represent the largest addressable volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing CX software procurement toward jurisdictions with clearer AI governance frameworks, as German and French financial institutions prioritize auditable decision trails while US enterprises optimize for scale economics in less prescriptive compliance environments.
United States
FCC robocall mitigation rules and HIPAA constraints on biometric sentiment data are accelerating contact-center modernization cycles among healthcare providers and telecommunications carriers. Legacy telephony infrastructure in Texas and California is reaching end-of-life, creating replacement demand for API-first engagement platforms that unify voice, chat, and asynchronous messaging. The Greater Boston cluster hosts specialized workforce optimization vendors serving financial services institutions.
Germany
EU AI Act compliance mandates for automated customer interactions are restructuring procurement checklists at automotive finance subsidiaries and insurance underwriters. BFSI institutions in Frankfurt and Munich must deploy auditable decision trails, accelerating investment in consent-management architectures with pre-established EU notified-body relationships. The Baden-Württemberg industrial corridor concentrates journey analytics deployments linking marketing spend to retention outcomes.
India
Data-localization directives under RBI guidelines and the Account Aggregator framework are forcing redundant infrastructure deployment across Mumbai and Bangalore. TRAI regulations on telemarketing consent are shaping outbound engagement channel architectures. The Karnataka-Telangana corridor anchors cloud-based CX platform development for retail banking embedded finance experiences leveraging UPI payment rails.
Singapore
Monetary Authority of Singapore regulatory sandboxes are permitting limited deployments of AI-driven customer engagement tools under supervised experimentation. BFSI institutions pilot conversation intelligence and pipeline analytics for revenue teams with reduced compliance risk. The city-state's data-center concentration supports edge-deployed inference engines for hospitality operators piloting real-time emotion detection.
United Kingdom
Financial Conduct Authority regulatory sandboxes and GDPR data-residency requirements are influencing vendor selection criteria among London-based wealth managers and insurers. The UK-EU regulatory divergence is creating procurement complexity for enterprises operating across both jurisdictions. The London-Southeast cluster concentrates sales enablement tool adoption correlating product usage telemetry with cancellation signals.
Global Customer Experience Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated platforms dominating enterprise accounts while best-of-breed point solutions capture mid-market fragmentation. The vendor ecosystem organizes around three archetypes: hyperscale cloud-native suites, vertical-specific workflow optimizers, and API-first communications infrastructure providers. M&A activity concentrates on journey analytics capabilities and consent-management layer acquisitions. Strategic partnerships between sentiment analysis engines and legacy CRM integrators are accelerating.
Among cloud-native platform providers, Salesforce Service Cloud and Zendesk exemplify divergent positioning strategies, with the former leveraging ecosystem breadth for enterprise retention and the latter anchoring mid-market segments through agent-workflow design. Qualtrics occupies a distinct position embedding statistical modeling directly into survey-to-action pipelines for experience management. These three entities represent the primary competitive anchors shaping how enterprises evaluate unified versus modular procurement approaches.
| Leading Market Players |
|---|
| HubSpot |
| Sogolytics |
| Qualtrics |
| Microsoft Dynamics 365 |
| Salesforce Service Cloud |
| Medallia |
| Adobe Experience Manager |
| Genesys |
| Zendesk |
| Others |
Supply & Pricing Matrix
EU AI Act documentation burdens gate qualified supply for premium-tier CX platforms, forcing vendors with pre-established notified-body relationships to command pricing premiums while excluding uncertified competitors from financial services procurement in Germany and France.
Pricing Analysis
Capacity additions in India are reshaping price floors for cloud-based deployment tiers as domestic hyperscalers expand Mumbai and Bangalore data-center footprints. Three-tier pricing structure across premium, standard, and economy levels separates EU AI Act-compliant suites with full audit trails from basic sentiment-analysis modules. Cost compression in mid-market segments is intensifying because Zendesk and Twilio infrastructure providers compete on agent-seat economics. Telecommunications providers in the United States exhibit highest price sensitivity due to FCC robocall mitigation compliance costs, while German BFSI institutions accept premium pricing for consent-management architectures with biometric authentication modules.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA H100 GPU availability for training large-language customer service models, creating margin pressure when semiconductor supply tightens. Software development concentrates in the United States, India, and Germany, with inference-engine deployment tethered to regional data-residency requirements. Raw material dependencies span cloud compute credits, API gateway infrastructure, and multilingual dialogue corpora for Indic languages. Tariff exposure runs through cross-border data-transfer mechanisms affecting EU-US data flows. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and systems-integrator channel partners serving mid-market retailers in Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in customer experience software rests on GPU compute cost normalization and the shift toward value-based pricing for predictive churn modeling modules in subscription software verticals.
For Market Incumbents: Lock in ecosystem loyalty by deepening AppExchange-style developer marketplaces that embed third-party sentiment analysis tools into core platforms. Prioritize EU notified-body certification investments to defend against emerging API-first challengers targeting German automotive finance subsidiaries. Vertical integration into edge-deployed inference engines preserves latency advantages as sovereign-cloud requirements fragment infrastructure procurement. For New Entrants and Emerging Players: The price-point gap between Qualtrics-tier enterprise suites and mid-market workflow tools creates white-space for specialized journey analytics vendors targeting telecommunications churn modeling. India's Account Aggregator framework enables embedded finance experiences for retail banking CX platforms previously underserved by predictive routing. A channel partnership strategy with domestic WhatsApp Business API providers accelerates penetration of Southeast Asian hospitality operators. For Investors and Strategic Acquirers: Roll-up economics work for vertical-specific consent-management layer specialists because EU AI Act compliance mandates are restructuring procurement checklists toward auditable decision-trail providers. Target acquisition archetypes include ISO 27001-certified workforce optimization vendors with pre-existing healthcare HIPAA attestations. Watch for GPU supply normalization as the inflection signal for margin recovery in AI-driven engagement tool categories.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies voice, chat, and messaging APIs for retiring legacy telephony in Texas and California contact centers. |
| Acquisition of Specialist Firm | Adds journey analytics capabilities connecting marketing spend to retention outcomes for telecommunications verticals. |
| Strategic Partnership | Combines Twilio communications infrastructure with localized WhatsApp Business API providers in Southeast Asia. |
| Product Launch | Introduces edge-deployed emotion detection for real-time guest interaction analysis in Singapore hospitality. |
| Geographic Expansion | Establishes redundant Mumbai and Bangalore infrastructure for RBI data-localization compliance in retail banking. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers, secondary validation through SEC filings and hyperscaler capex disclosures, and technical documentation from API gateway providers — were reconciled against bottom-up and top-down triangulation. Conversations with platform engineers, integration specialists, and channel partners at systems integrators informed deployment architecture segmentation. Secondary sources included App Annie mobile SDK data, FERC telecommunications infrastructure filings, and EU AI Act implementation guidance from notified bodies. Cross-referencing vendor revenue disclosures against enterprise procurement committee timelines established certification-driven sales cycle patterns.
Historical growth trajectories were cross-referenced against panel input from customer experience software vendors to anchor projections across the analysis window. Segmentation dimensions modeled include deployment architecture, solution type, organization size tier, vertical industry, and regional regulatory cluster. CAGRs were derived from S-curve adoption modeling for cloud-based platforms and replacement-cycle analysis for on-premises call-center hardware. Forecast inputs incorporated EU AI Act implementation timelines and India's Account Aggregator framework penetration rates.
Caveats apply where GPU supply constraints, GDPR enforcement variations, or TRAI telemarketing consent rule changes could materially shift the outlook. Forecasts reflect documented assumptions about contact-center modernization cycle timing and sovereign-cloud infrastructure buildout pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Embedded Operating Systems Market
Software & Services
Landing Page Creation Software Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
Employee Advocacy Software Market
Software & Services
Air Cargo Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Global Claims Processing Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Africa HR Payroll Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Computer Engineering Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Global Remote Desktop Management Market