
 Binary Drivers Market | 2026-2036
Binary Drivers Market Size, Share, and Industry Trends Forecast 2026-2036
Binary Drivers Market Outlook
Modular driver bundling with integrated controller-sensor kits is expanding buyer choice in industrial automation procurement. NVIDIA Corporation leverages its CUDA ecosystem to anchor GPU-accelerated binary driver stacks for edge inference workloads. Intel Corporation sustains dominance in x86-architecture driver foundations through deep OEM firmware partnerships. Broadcom Inc. specializes in ASIC-optimized drivers for high-speed switching fabrics in data center interconnects.
Binary drivers are software modules that translate digital control signals into discrete on/off states for actuators, sensors, and switches, typically operating at logic levels between 1.8V and 5V with switching speeds measured in microseconds. They serve as the critical interface layer between microcontrollers and physical devices across industrial, automotive, and consumer systems. Controllers command the largest installed base due to their central role in programmable logic architectures, while actuators capture accelerating demand from robotic motion platforms. The wired connectivity segment retains entrenched share in safety-critical automotive and industrial deployments where latency tolerance approaches zero.
The US FCC governs wireless driver emissions for unlicensed spectrum operation, while the EU Cyber Resilience Act mandates vulnerability disclosure and secure-update mechanisms for connected driver modules. China's MIIT enforces GB standards for electromagnetic compatibility in domestically deployed industrial control systems. Stakeholders must monitor divergence between regional cybersecurity certification timelines and silicon node migration schedules to avoid stranded development investment.
Market Dynamics
The Binary Drivers Market faces intensifying certification pressure from the EU Cyber Resilience Act and IEC 61508 functional-safety mandates, forcing embedded module suppliers to revalidate legacy architectures while semiconductor foundries in Taiwan and South Korea constrain component availability for industrial automation buyers.
Growth Catalysts
- EU Cyber Resilience Act:Mandatory vulnerability disclosure and secure-update mechanisms for connected driver modules are creating replacement demand across Europe's industrial base as legacy systems face compliance deadlines.
- Robotic motion platforms:Accelerating deployment of precision actuators in automotive assembly and logistics automation is expanding addressable unit volumes for high-speed switching drivers.
- Taiwan semiconductor foundries:Concentrated advanced-node capacity anchors component supply for GPU-accelerated edge inference workloads requiring specialized binary driver stacks.
Market Restraints
- Silicon node migration costs:Foundry pricing for automotive-grade process nodes has compressed margin structures for mid-tier driver module suppliers unable to pass through wafer cost increases.
- Single-source ASIC dependency:Data center interconnect vendors face supply concentration risk from Broadcom's dominance in high-speed switching fabric drivers, limiting buyer negotiation leverage.
- Legacy 5V logic compatibility:Industrial automation buyers maintain entrenched installed bases of 5V-tolerant peripherals, slowing adoption of 1.8V-optimized driver architectures despite efficiency gains.
Strategic Opportunities
- Japan precision-equipment clusters:Underpenetrated demand from semiconductor manufacturing equipment and medical device makers offers premium pricing for IEC 61508-certified driver modules with deterministic switching guarantees.
- Modular controller-sensor bundling:Procurement consolidation around integrated kits is opening channel access for driver suppliers with embedded firmware partnerships, displacing discrete component sourcing.
- China MIIT electromagnetic compatibility standards:Domestic certification requirements for industrial control systems are creating captive market space for locally compliant driver architectures as import substitution accelerates.
Industry Challenges
- Functional-safety engineering talent:Scarce expertise in IEC 61508 SIL certification processes is extending product development timelines and inflating compensation costs for qualified firmware architects.
- Multi-regulatory certification parallelism:Divergent cybersecurity disclosure timelines between EU Cyber Resilience Act implementation and US FCC wireless emissions rules are forcing redundant validation investments.
- Legacy microcontroller integration:Binary driver suppliers must maintain backward compatibility with decade-old programmable logic architectures, fragmenting firmware development resources across obsolete and modern instruction sets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binary Drivers Market |
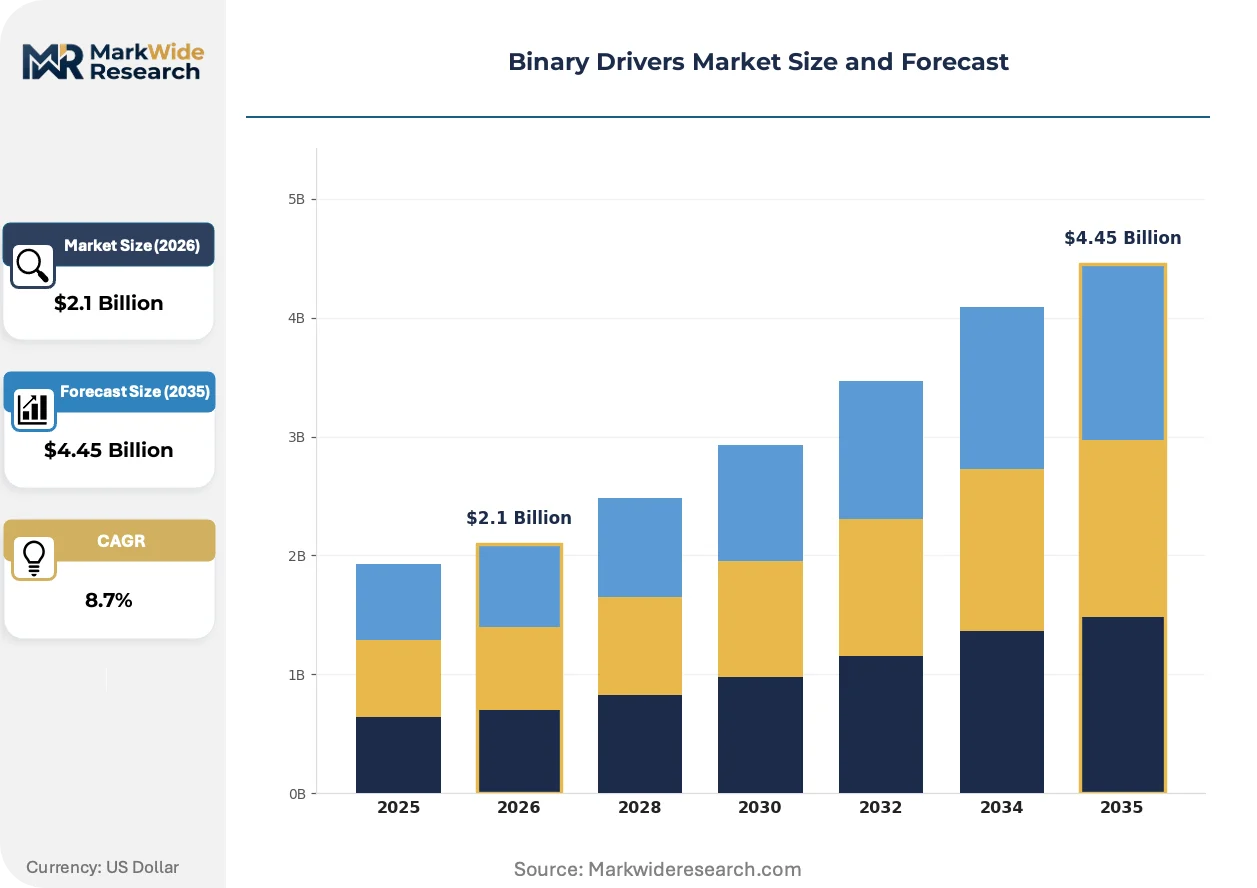
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Sensors, Switches, Actuators, Controllers Application: Industrial Automation, Consumer Electronics, Automotive Systems, Home Appliances Connectivity: Wired, Wireless, Bluetooth, Zigbee End User: OEMs, System Integrators, Distributors, Retailers |
| Companies Covered | Intel Corporation, Microsoft Corporation, NVIDIA Corporation, Broadcom Inc., Logitech, Google, Maxim Integrated, Advanced Micro Devices, Qualcomm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binary Drivers Market Strategic Shifts
GPU-accelerated inference at the edge is rewriting performance requirements for binary driver architectures, while regulatory fragmentation between cybersecurity and safety standards is compressing product development windows across all major supply regions.
Silicon carbide gate driver ICs are converging with 800V automotive traction inverters to enable sub-microsecond switching speeds that minimize switching losses in electric powertrain modules. Tier-1 automotive suppliers in Germany's electronics corridor are qualifying these devices for series production. This technology convergence is compressing the performance gap between silicon-based and wide-bandgap driver solutions, forcing incumbent suppliers to accelerate roadmap investments or cede premium inverter socket positions.
The EU Cyber Resilience Act's mandatory secure-update mechanisms are mandating over-the-air firmware patch capabilities for all connected driver modules deployed in European industrial and automotive applications. Manufacturers must now maintain cryptographic key infrastructure and vulnerability disclosure processes across product lifetimes exceeding fifteen years. Automotive electronics suppliers face the steepest compliance burden, as their modules combine wireless connectivity with safety-critical actuator control functions subject to both cybersecurity and functional-safety audits.
Buyer consolidation around integrated controller-sensor-driver kits is displacing discrete component procurement in industrial automation channels. System integrators in Japan's precision-equipment sector now specify bundled architectures to reduce commissioning complexity and warranty exposure. This pattern is most visible in semiconductor manufacturing equipment, where end-users demand single-vendor accountability for motion control subsystems rather than managing multi-source driver, encoder, and amplifier compatibility matrices.
Binary Drivers Market Segmentation
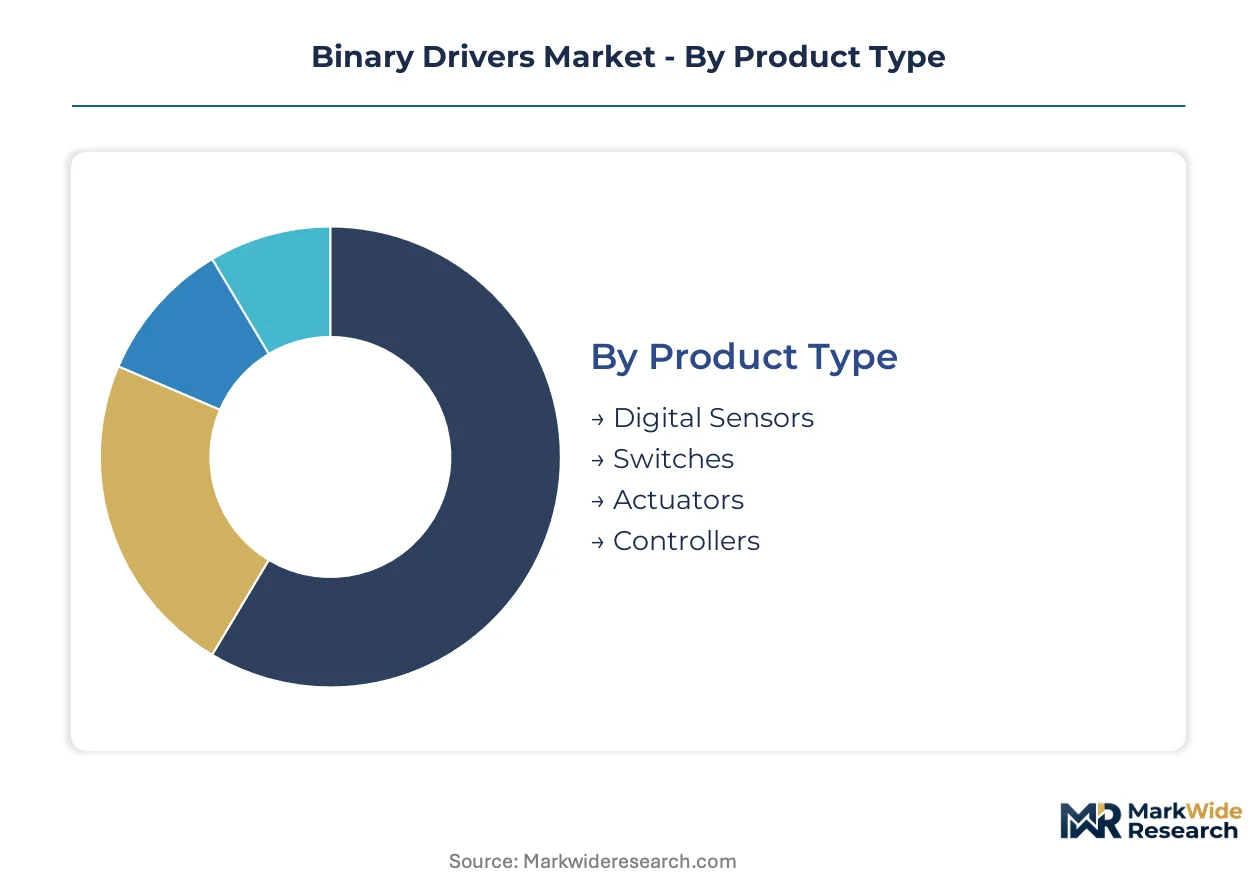
Binary driver procurement hinges on matching voltage logic levels, switching latency tolerances, and certification grades to specific deployment environments. Buyers segment requirements across product architecture, application criticality, connectivity constraints, and channel relationships to optimize total cost of ownership.
Product Type:
Engineering teams prioritize switching speed determinism and voltage compatibility when specifying driver modules for integration into larger control systems.
- Controllers:These modules execute programmable logic sequences with microsecond-level timing precision across 1.8V to 5V logic thresholds. Germany's automotive electronics corridor sources IEC 61508-certified controllers for safety-critical powertrain management, though legacy 5V peripheral compatibility constrains architecture migration.
- Actuators:Precision motion platforms in Japan's semiconductor manufacturing equipment sector demand sub-microsecond switching guarantees for robotic positioning subsystems. Silicon carbide gate driver integration with 800V traction inverters is compressing performance gaps against silicon-based alternatives.
- Digital Sensors:Signal conditioning modules for industrial process monitoring operate at standardized logic levels with EMI-hardened enclosures.
- Switches:Discrete on/off state translators serve as interface layers between microcontrollers and physical devices in consumer and automotive applications.
Controllers lead on scale; actuators lead on momentum.
Application:
End-use environments dictate functional-safety certification depth and electromagnetic compatibility requirements.
- Industrial Automation:Factory floor deployments require deterministic switching with zero latency tolerance for safety interlocks and motion control. Taiwan and South Korean foundries anchor component supply for programmable logic architectures, while the EU Cyber Resilience Act mandates secure-update mechanisms for European installations.
- Automotive Systems:Powertrain and chassis control modules combine wireless connectivity with actuator functions, subjecting suppliers to overlapping cybersecurity and functional-safety audits. Germany's Tier-1 suppliers qualify silicon carbide drivers for series production in electric vehicle inverters.
- Consumer Electronics:Cost-optimized driver stacks prioritize integration density over certification depth for mass-market appliances.
- Home Appliances:Motor control and user interface modules operate at reduced switching frequencies with basic EMI compliance.
Industrial automation commands the largest installed base; automotive systems are climbing the fastest.
Connectivity:
Latency tolerance and regulatory jurisdiction determine wired versus wireless architecture selection.
- Wired:Copper-based interconnects retain entrenched share where latency approaches zero, particularly in safety-critical automotive braking and industrial emergency-stop circuits. The US FCC governs emissions for unlicensed spectrum operation, reinforcing wired preference in electromagnetic-sensitive environments.
- Wireless:Radio-frequency modules enable flexible deployment in logistics automation and remote monitoring applications. The EU Cyber Resilience Act's mandatory vulnerability disclosure requirements impose fifteen-year cryptographic key infrastructure obligations on European wireless deployments.
- Bluetooth:Short-range protocols serve consumer electronics and home automation with standardized pairing security.
- Zigbee:Mesh networking stacks address low-power industrial sensor networks with deterministic routing.
Wired connectivity dominates current procurement volumes; wireless architectures are gaining share fastest.
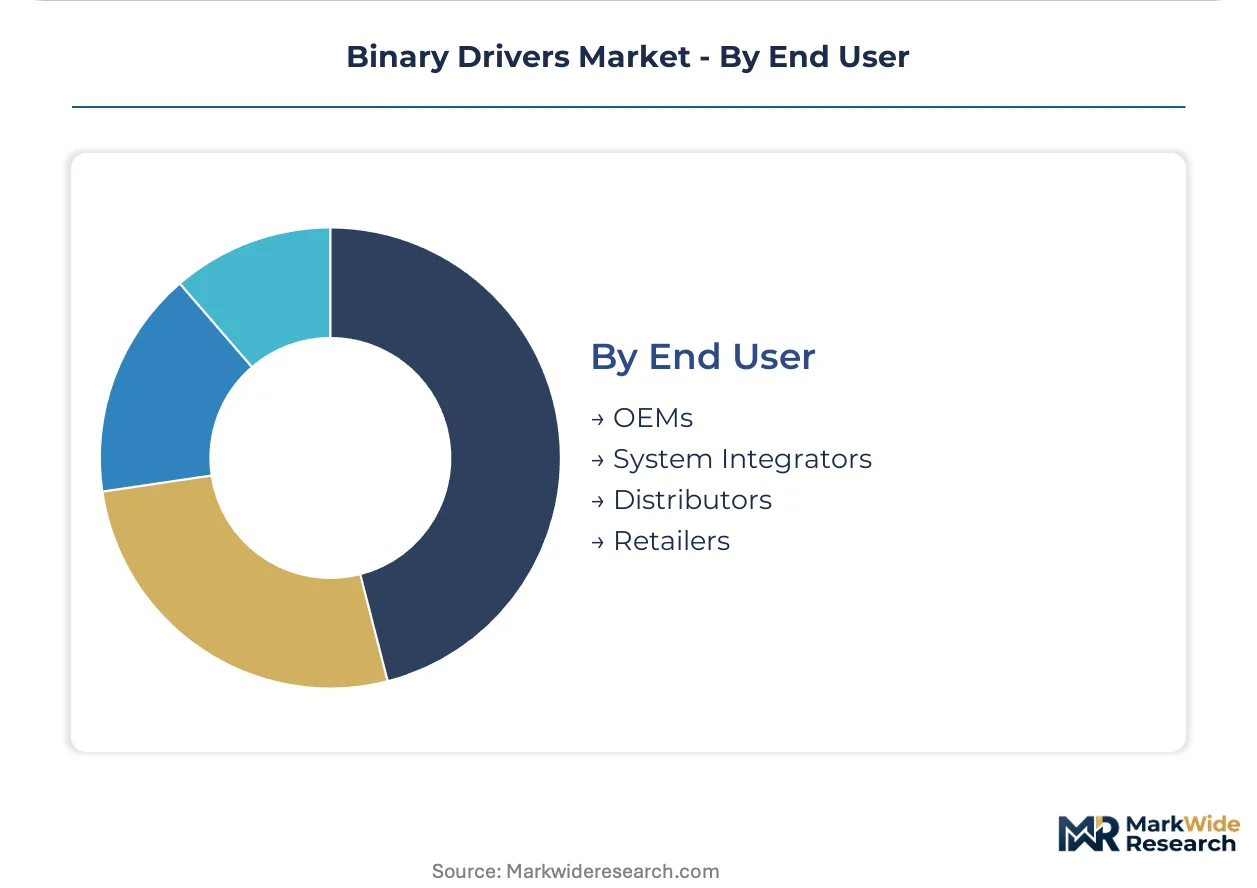
End User:
Channel position determines technical support requirements and pricing negotiation leverage.
- OEMs:Original equipment manufacturers with captive firmware development teams specify driver modules for direct integration into product platforms. Deep OEM partnerships anchor Intel's dominance in x86-architecture driver foundations.
- System Integrators:Japan's precision-equipment sector increasingly specifies bundled controller-sensor-driver kits to reduce commissioning complexity and warranty exposure in semiconductor manufacturing equipment.
- Distributors:Inventory aggregation and technical pre-sales support serve mid-tier industrial automation buyers without direct foundry relationships.
- Retailers:Consumer-facing channels move standard-grade modules for replacement and hobbyist markets with minimal application engineering.
OEMs lead on scale; system integrators lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Binary driver technology originated in the United States during the early era of programmable logic controllers, with subsequent scaling concentrated in East Asian semiconductor manufacturing corridors and European automotive electronics hubs.
United States
Defense and aerospace applications drive demand for radiation-hardened driver modules with deterministic switching guarantees. The FCC governs wireless emissions for unlicensed spectrum operation in industrial automation deployments. Silicon Valley maintains firmware engineering clusters for GPU-accelerated edge inference workloads.
Germany
Tier-1 automotive suppliers qualify silicon carbide gate drivers for 800V electric vehicle traction inverters. The KBA enforces type approval standards for safety-critical powertrain control modules. Stuttgart and Munich anchor the automotive electronics corridor where IEC 61508 certification depth determines supplier selection.
Japan
Precision-equipment makers in semiconductor manufacturing and medical devices demand sub-microsecond switching guarantees for robotic positioning subsystems. METI coordinates national standards alignment with IEC functional-safety frameworks. Nagoya and Osaka host clusters where bundled controller-sensor-driver kits displace discrete procurement.
South Korea
Memory and display panel manufacturers consume high-volume driver ICs for factory automation and test equipment. The MFDS regulates electromagnetic compatibility in domestically deployed industrial control systems. Seoul Capital Area foundries anchor advanced-node capacity for specialized binary driver architectures.
Taiwan
Semiconductor foundries constrain component availability for industrial automation buyers through concentrated advanced-node capacity allocation. The National Communications Commission enforces wireless equipment certification for connected driver modules. Hsinchu Science Park hosts the dominant supply base for programmable logic controller driver stacks.
Binary Drivers Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification depth and foundry access dimensions. The vendor base stratifies into three tiers: semiconductor incumbents with captive foundry relationships, fabless specialists with ASIC-optimized architectures, and modular kit assemblers serving system integrators. Dominant competitive moves include strategic partnerships for controller-sensor bundling and vertical integration into firmware development to capture recurring service revenue.
Within the semiconductor incumbent tier, Intel Corporation and NVIDIA Corporation exemplify divergent strategic positioning. Intel anchors x86-architecture driver foundations through deep OEM firmware partnerships spanning industrial and automotive channels. NVIDIA occupies the GPU-accelerated inference vector where CUDA ecosystem lock-in protects premium pricing for edge workloads. Broadcom sits within the ASIC-specialist archetype, serving data center interconnect vendors with high-speed switching fabric solutions where single-source concentration limits buyer leverage.
| Leading Market Players |
|---|
| Intel Corporation |
| Microsoft Corporation |
| NVIDIA Corporation |
| Broadcom Inc. |
| Logitech |
| Maxim Integrated |
| Advanced Micro Devices |
| Qualcomm |
| Others |
Value Chain & Pricing Dynamics
Germany's Tier-1 automotive suppliers anchor procurement volumes for IEC 61508-certified driver modules, forcing a three-tier pricing structure across premium, standard, and economy levels that stratifies by certification depth and foundry access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates IEC 61508 SIL-certified automotive modules from industrial-grade controllers and consumer-tier switches. Price differentiation rests on functional-safety certification grade and Taiwan foundry allocation priority. Cost compression in mid-tier industrial controllers is intensifying because automotive buyers are absorbing advanced-node wafer premiums. System integrators in Japan's precision-equipment clusters show the lowest price sensitivity due to bundled kit procurement, while consumer electronics OEMs drive the hardest unit-cost negotiations.
Supply Chain Analysis
China's MIIT electromagnetic compatibility standards and domestic-content acceleration are reshaping sourcing patterns for industrial control systems deployed within its borders. Component supply draws from Taiwan's Hsinchu Science Park foundries, South Korea's Seoul Capital Area memory specialists, and Germany's automotive electronics corridor. Silicon carbide substrates, automotive-grade process nodes, and copper interconnect raw materials anchor bill-of-materials exposure. Single-source vulnerability concentrates in Broadcom's high-speed switching fabric drivers for data center interconnects. Distribution runs through direct OEM partnerships for certified modules and distributor networks for standard-grade replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Binary Drivers Market functions as a stable compounder where regulatory compliance mandates—particularly the EU Cyber Resilience Act and IEC 61508—generate replacement demand that sustains pricing power across product lifecycles exceeding fifteen years.
For Market Incumbents: Deepen backward integration into firmware development to capture recurring secure-update service revenue as the EU Cyber Resilience Act mandates fifteen-year cryptographic infrastructure maintenance. Expand captive foundry relationships in Taiwan and South Korea to defend allocation priority against emerging GPU-accelerated edge inference competitors. Prioritize IEC 61508 SIL certification investment as scarce functional-safety engineering talent extends rival development timelines. For New Entrants and Emerging Players: Enter via Japan's precision-equipment clusters where bundled controller-sensor-driver kit demand outpaces established supplier capacity in semiconductor manufacturing equipment. Target China's domestically compliant driver architectures as MIIT electromagnetic compatibility standards accelerate import substitution. Pursue system integrator partnerships rather than discrete component channels to bypass entrenched OEM firmware relationships. For Investors and Strategic Acquirers: Semiconductor foundries with captive driver module divisions are the most active acquirer in this space, seeking to vertically integrate downstream into firmware and certification capabilities. The long-term viability window favors targets with established IEC 61508 audit trails and automotive OEM qualification records. Watch for inflection when EU Cyber Resilience Act compliance deadlines trigger accelerated replacement cycles across Europe's industrial base.| Strategic Initiative | Industry Significance |
|---|---|
| Controller-Sensor-Driver Kit Integration | Reduces commissioning complexity for Japan's semiconductor equipment makers seeking single-vendor accountability. |
| Silicon Carbide Gate Driver Qualification | Enables 800V traction inverter deployment by Germany's Tier-1 automotive suppliers. |
| Secure-Update Infrastructure Buildout | Satisfies EU Cyber Resilience Act cryptographic key mandates across fifteen-year product lifecycles. |
| Backward Integration into Firmware | Captures recurring service revenue from vulnerability disclosure and patch management obligations. |
| Domestic Certification Compliance | Unlocks captive market space under China's MIIT electromagnetic compatibility standards. |
Study Parameters
Direct dialogue with semiconductor foundry procurement directors, automotive Tier-1 supplier platform engineers, industrial automation system integrators, and functional-safety certification auditors grounded qualitative insights. Secondary validation drew from SEC 10-K filings, Taiwan National Communications Commission equipment certifications, EU Cyber Resilience Act implementation guidance, and IEC 61508 audit documentation. Bottom-up unit shipment estimates across voltage logic levels and switching speed tiers triangulated against top-down semiconductor wafer allocation data.
Bottom-up modeling segmented the market by product architecture, application criticality, connectivity constraints, and end-user channel position across the analysis window. Value outputs incorporated foundry pricing trajectories for automotive-grade process nodes, certification cost amortization schedules, and bundled kit premium capture rates. CAGRs derived from regression analysis of historical replacement cycles and regulatory compliance deadline impacts.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in real-time foundry capacity allocation data introduce uncertainty bands around near-term supply constraints. Forecasts reflect documented assumptions regarding EU Cyber Resilience Act enforcement timing and silicon carbide substrate cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Animation Software Market
Software & Services
Asia-Pacific Printing Software Market
Software & Services
North America Workforce Management Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Camp Management Software Market
Software & Services
Preschool Education Software Market
Software & Services
Global Content Management Systems (CMS) Market
Software & Services
Global Online Assessment Software Market
Software & Services
Saas Based HRM Market
Software & Services
Middle East HR Payroll Software Market
Software & Services
Global License Management Market
Software & Services
Staffing Software Market
Software & Services
Global Retail Execution Software Market