
 Preventive Maintenance Software Market | 2026-2036
Preventive Maintenance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Preventive Maintenance Software Market Outlook
Cloud infrastructure is consolidating around subscription models as the dominant delivery substrate for maintenance platforms. IBM Corporation leverages its Watson IoT backbone to anchor predictive analytics capabilities across heavy industrial accounts. SAP SE sustains deep ERP integration that dominates manufacturing procurement channels. Oracle Corporation competes through database-native architectures that extend real-time asset monitoring into enterprise data lakes.
Preventive maintenance software orchestrates scheduled inspection, lubrication, calibration, and component replacement protocols through digital work order systems, typically integrating vibration analysis thresholds, thermal imaging triggers, and oil particulate counters to preempt equipment failure. Its primary commercial purpose is eliminating unplanned downtime in capital-intensive operations. Cloud-based deployment leads segment economics by converting perpetual licenses into recurring revenue pools, while work order management solutions occupy the deepest margin tier due to their integration complexity with existing CMMS installations. Asset tracking functions represent the fastest-expanding module category as RFID and IoT sensor costs decline.
OSHA mandates in the United States, the EU Machinery Directive through CE marking requirements, and Japan's METI industrial standards collectively shape platform compliance architectures by mandating documented maintenance trails for critical equipment. FDA 21 CFR Part 11 in pharmaceutical and food processing environments further tightens electronic record-keeping specifications, forcing validation-grade software investments. Stakeholders must monitor how carbon accounting rules under CSRD and emerging SEC climate disclosure requirements will embed emissions tracking into maintenance scheduling logic.
Market Dynamics
Cloud migration mandates under the EU AI Act and parallel digital governance frameworks are compressing upgrade cycles for legacy asset management systems across capital-intensive industries. This regulatory pressure is forcing platform vendors to rearchitect subscription delivery models while industrial buyers absorb compliance-driven procurement costs.
Growth Catalysts
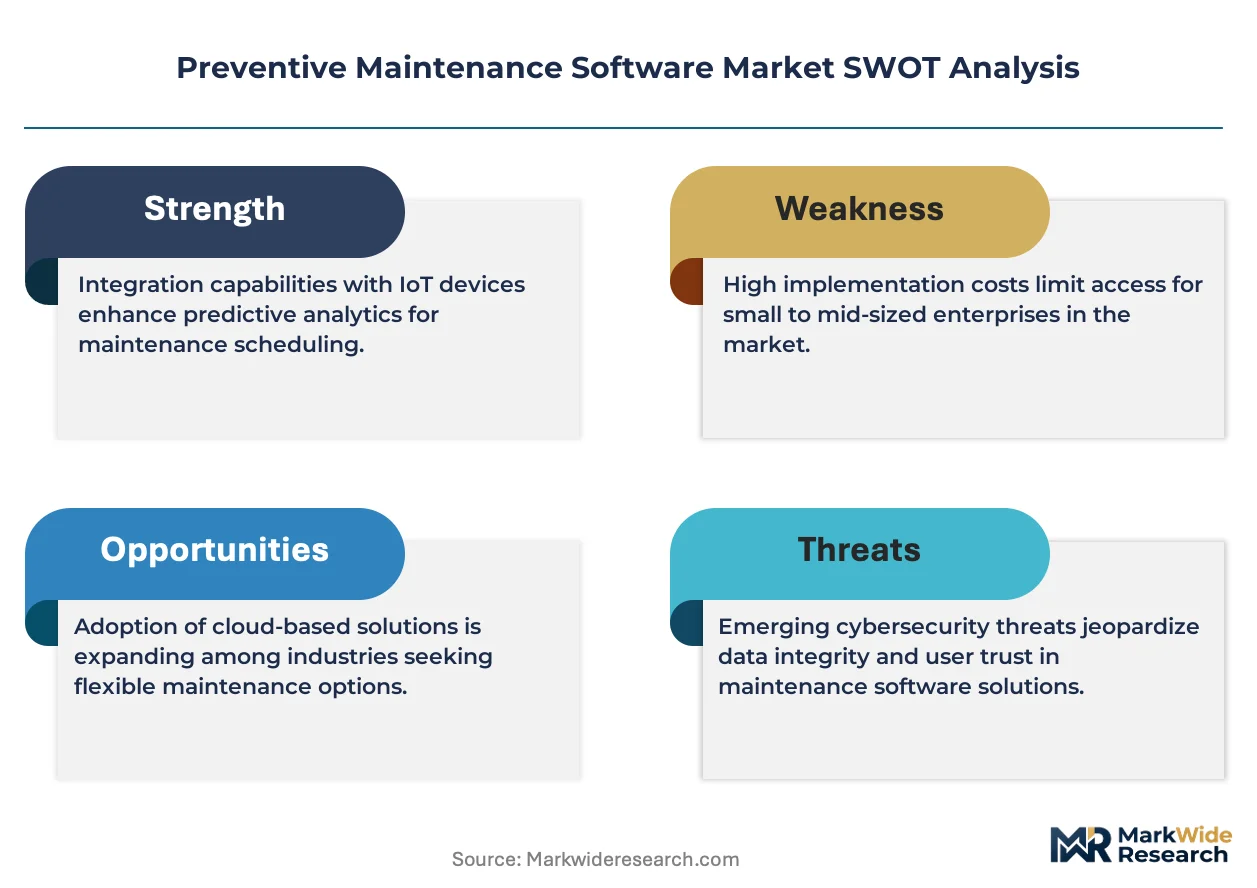
- EU AI Act cloud mandates:Documented audit trails for critical equipment maintenance are becoming compulsory across German, French, and Italian manufacturing bases, accelerating replacement of paper-based systems.
- Oil and gas predictive scheduling:Offshore platforms in the North Sea and Gulf of Mexico are integrating vibration analysis thresholds with digital work order systems to preempt compressor failures.
- RFID cost collapse:Sensor hardware prices below five dollars per unit are enabling granular asset tracking in mid-sized food processing facilities previously priced out of IoT deployments.
Market Restraints
- Legacy CMMS integration complexity:Proprietary data formats in twenty-year-old installations require expensive middleware development, inflating total cost of ownership for brownfield deployments.
- Semiconductor supply concentration:Taiwan and South Korea dominate industrial-grade sensor chip fabrication, exposing maintenance platform vendors to geographic supply shocks.
- FDA 21 CFR Part 11 validation costs:Pharmaceutical manufacturers face six-figure software validation expenses that deter mid-tier facilities from upgrading electronic record-keeping systems.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for capital goods are attracting greenfield automotive and electronics plants requiring native preventive maintenance platforms.
- CSRD carbon accounting convergence:Embedded emissions tracking in maintenance scheduling logic opens new module revenue streams for European industrial software vendors.
- Digital twin integration:Convergence of physics-based simulation with real-time sensor feeds enables virtual commissioning of maintenance protocols before physical execution.
Industry Challenges
- Industrial cybersecurity skill scarcity:Maintenance technicians lack training in OT/IT network segmentation, exposing connected sensor architectures to ransomware infiltration.
- Multi-year ERP synchronization timelines:SAP and Oracle core system upgrades frequently stall preventive maintenance module rollouts by eighteen to thirty-six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Preventive Maintenance Software Market |
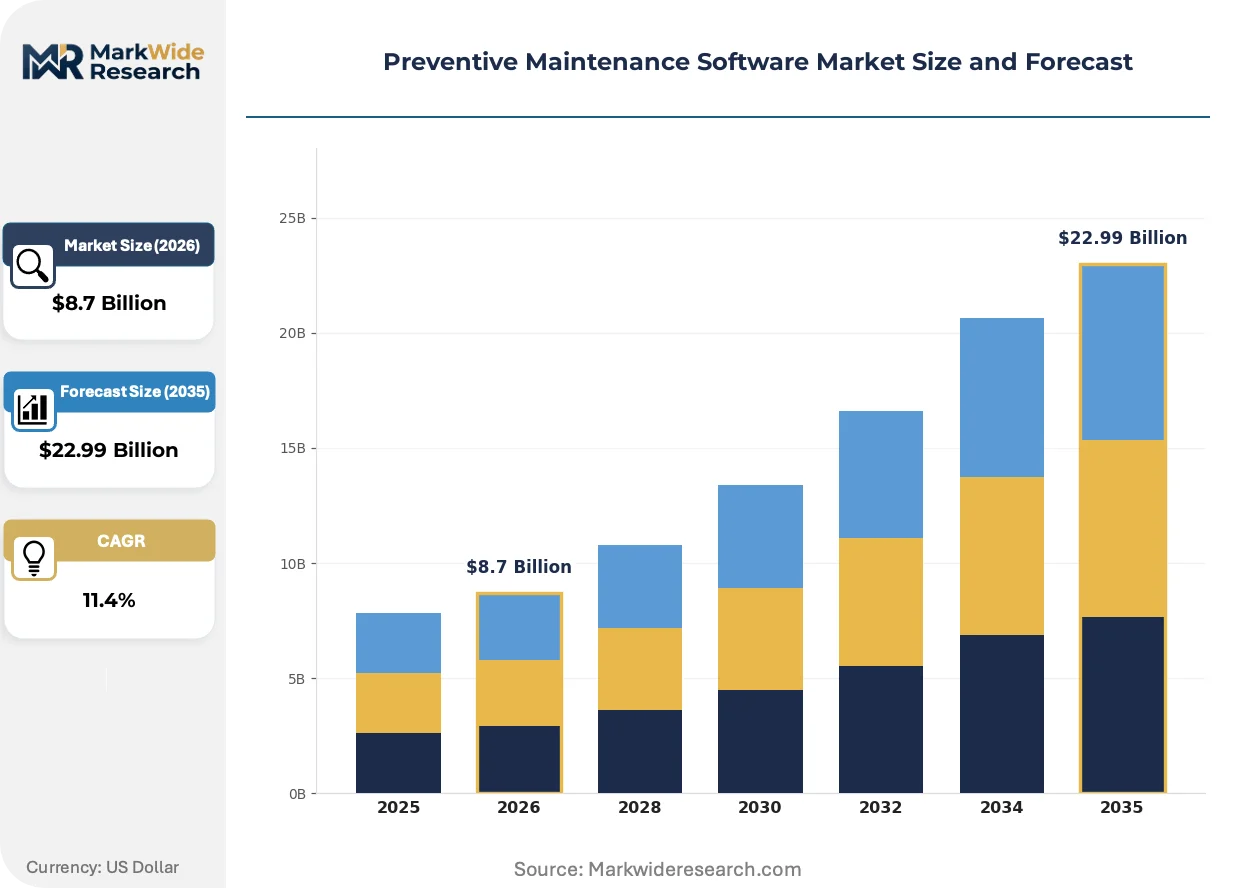
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile End User: Manufacturing, Healthcare, Retail, Transportation Deployment: Single Tenant, Multi-Tenant, Local, Hosted Solution: Work Order Management, Asset Tracking, Reporting, Scheduling |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Schneider Electric SE, Honeywell, Rockwell Automation, Inc., Infor, Inc., Bentley Systems, Incorporated, GE Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Preventive Maintenance Software Market Strategic Shifts
Generative AI interfaces are compressing technician training curves while edge computing architectures reduce latency for real-time failure prediction. These shifts are redefining how maintenance data flows between plant floors and enterprise systems.
Edge-native vibration analysis is rewriting predictive maintenance economics. On-chip machine learning inference eliminates round-trip latency to cloud data centers. Automotive stamping plants in Stuttgart and Wolfsburg are deploying these systems at scale. The technology is compressing response windows from minutes to milliseconds for critical press failures.
The EU Machinery Directive's updated CE marking requirements now mandate digital maintenance logs for Category 3 safety systems. Industrial machinery exporters must retrofit documentation capabilities or lose market access. German packaging equipment manufacturers are absorbing the steepest compliance costs as they revalidate entire product lines.
Subscription pricing is displacing perpetual licenses across mid-market manufacturing. Buyers prefer operational expenditure treatment for software assets. Japanese precision toolmakers and US metal fabricators are driving this transition fastest, with three-year contracts now dominating new procurement. Vendors respond by unbundling implementation services from recurring platform fees.
Preventive Maintenance Software Market Segmentation
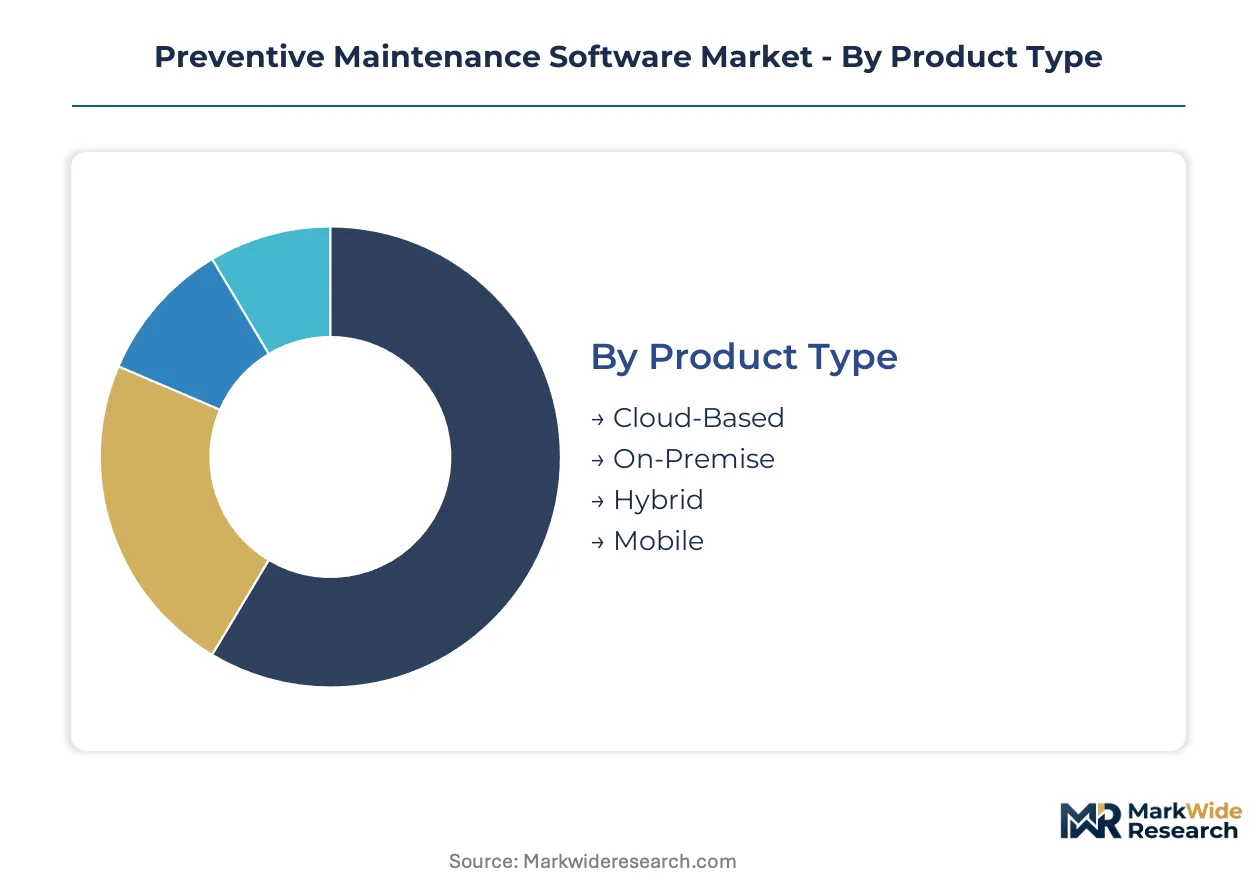
Preventive maintenance software vendors architect product lines around deployment flexibility and integration depth. Segmentation choices determine whether platforms capture recurring subscription revenue or remain trapped in perpetual license cycles. Buyers prioritize segments that compress mean time to repair while satisfying audit requirements under OSHA, EU Machinery Directive, and FDA 21 CFR Part 11.
Product Type:
Customization versus standardization tension runs deepest here, with cloud-native architectures enabling rapid configuration while on-premise installations demand heavy professional services.
- Cloud-Based:Multi-tenant architectures with API-first design patterns support elastic scaling across distributed manufacturing footprints. Demand concentrates in German automotive stamping plants and Japanese precision toolmakers modernizing under METI digital standards, driven by EU AI Act mandates for documented audit trails and subscription-based operational expenditure treatment.
- On-Premise:Air-gapped installations with localized data sovereignty satisfy defense contractors and pharmaceutical manufacturers facing FDA 21 CFR Part 11 validation requirements. North American food processors with legacy SCADA investments absorb the highest total cost of ownership due to middleware complexity.
- Hybrid:Edge-cloud orchestration layers synchronize real-time sensor inference with centralized analytics repositories.
- Mobile:Native iOS and Android field technician applications with offline synchronization capabilities.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Mobile as RFID sensor costs collapse below five dollars per unit.
End User:
Cost tier stratification separates capital-intensive process industries from asset-light service operations, with compliance burden and equipment criticality driving pricing power.
- Manufacturing:Discrete and process manufacturers deploy vibration analysis thresholds, thermal imaging triggers, and oil particulate counters through digital work order systems. Demand clusters in Stuttgart and Wolfsburg automotive clusters and US Gulf Coast petrochemical corridors, propelled by predictive scheduling modules that preempt compressor failures on offshore platforms.
- Healthcare:Hospital systems and medical device manufacturers require FDA-validated electronic record-keeping with 21 CFR Part 11 compliance. Mid-tier facilities face six-figure validation expenses that deter upgrades from paper-based maintenance logs.
- Retail:Distributed facility footprints with homogeneous equipment fleets prioritize standardized checklists over predictive analytics.
- Transportation:Fleet maintenance operations with mobile asset bases emphasize geolocation integration and fuel system monitoring.
Manufacturing commands the deepest margin pools. Healthcare exhibits the steepest expansion trajectory as CSRD carbon accounting rules embed emissions tracking into maintenance scheduling logic.
Deployment:
Application criticality dictates tenant isolation requirements, with safety-system Category 3 equipment under updated EU Machinery Directive CE marking mandating dedicated infrastructure.
- Single Tenant:Dedicated instance architectures with isolated database schemas and custom security postures. Nuclear facilities and pharmaceutical cleanrooms in Switzerland and France specify these configurations to satisfy ANSM and Swissmedic validation protocols.
- Multi-Tenant:Shared resource pools with logical segmentation and standardized update cadences. Mid-market metal fabricators across the US Midwest and Japanese electronics assemblers drive volume, attracted by three-year subscription contracts displacing perpetual licenses.
- Local:Bare-metal installations with direct hardware control for latency-sensitive vibration analysis.
- Hosted:Managed private cloud with vendor-operated infrastructure but client-dedicated resources.
Multi-Tenant deployments carry the broadest installed base. Single Tenant configurations are climbing the fastest as CE marking requirements tighten for Category 3 safety systems.
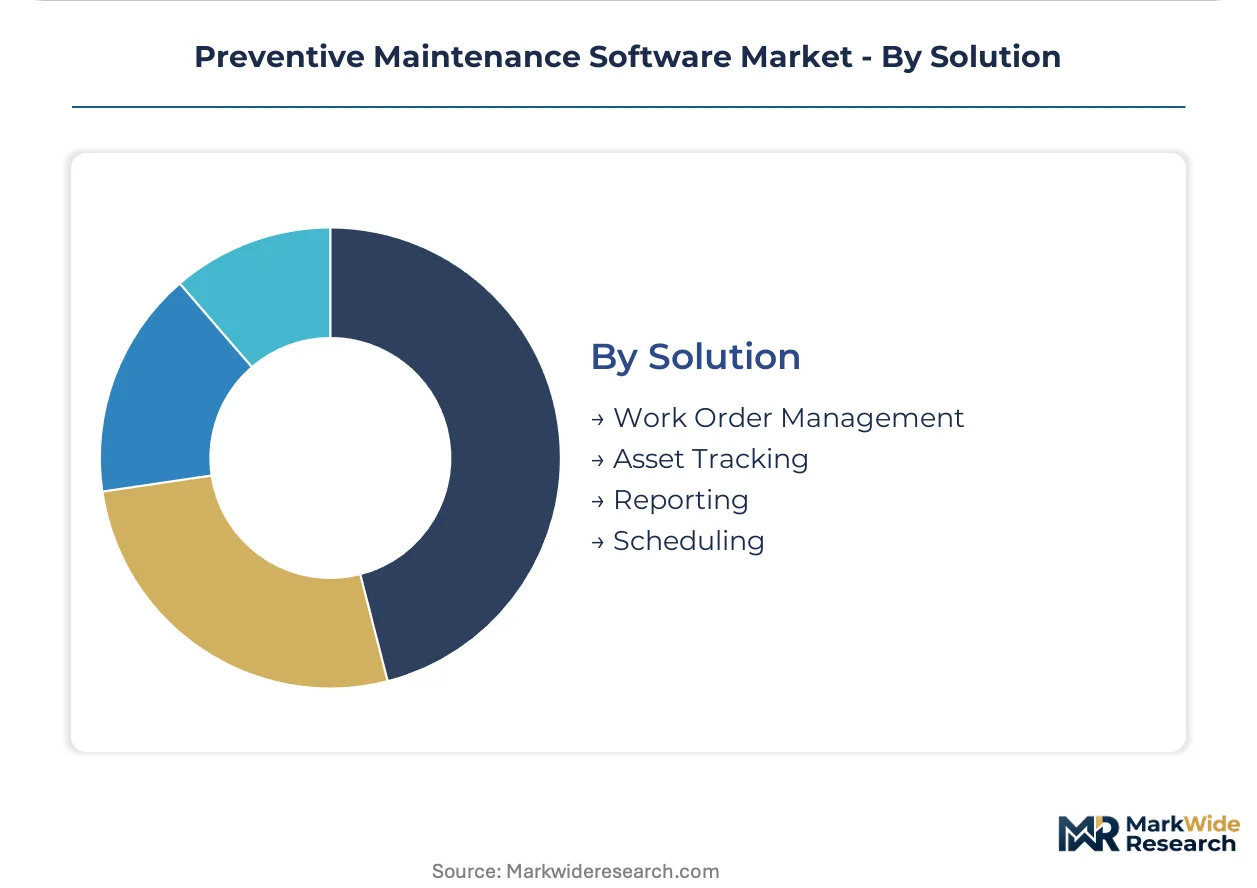
Solution:
Margin concentration follows integration complexity, with work order management requiring deepest CMMS interoperability while asset tracking benefits from hardware cost deflation.
- Work Order Management:Digital work order systems orchestrating scheduled inspection, lubrication, calibration, and component replacement protocols. Demand concentrates in brownfield German packaging equipment manufacturers revalidating entire product lines under updated EU Machinery Directive requirements, constrained by twenty-year-old proprietary CMMS data formats requiring expensive middleware development.
- Asset Tracking:RFID and IoT sensor-based location and condition monitoring with real-time dashboard visualization. Food processing facilities in Italy and Spain previously priced out of IoT deployments now adopt granular tracking as hardware costs decline, enabled by generative AI interfaces compressing technician training curves.
- Reporting:Compliance documentation engines with automated regulator submission formatting.
- Scheduling:Predictive algorithms integrating equipment runtime data with maintenance resource availability.
Work Order Management absorbs the greatest implementation services revenue. Asset Tracking is gaining share fastest as edge-native vibration analysis rewrites predictive maintenance economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive stamping plants in Stuttgart and Wolfsburg anchor the highest concentration of predictive maintenance deployments. Manufacturing clusters across four additional countries are modernizing legacy asset management systems under tightening regulatory mandates.
United States
OSHA mandates for documented maintenance trails drive platform upgrades across Gulf Coast petrochemical corridors. The SEC's emerging climate disclosure requirements are embedding emissions tracking into maintenance scheduling logic for heavy industrial accounts. Houston and Corpus Christi refineries are integrating vibration analysis thresholds with digital work order systems to preempt compressor failures.
Germany
EU AI Act cloud migration mandates are compressing upgrade cycles for brownfield packaging equipment manufacturers. Updated CE marking requirements under the EU Machinery Directive now compel digital maintenance logs for Category 3 safety systems. Bavarian automotive suppliers are absorbing the steepest compliance costs as they revalidate entire product lines.
Japan
METI industrial standards shape platform compliance architectures for precision toolmakers modernizing legacy systems. Three-year subscription contracts are displacing perpetual licenses fastest among Nagoya-area electronics assemblers. Toyota City industrial clusters are deploying edge-native vibration analysis to compress response windows from minutes to milliseconds.
India
PLI scheme production-linked incentives for capital goods are attracting greenfield automotive and electronics plants requiring native preventive maintenance platforms. The country's national industrial standards body is aligning certification requirements with ISO asset management frameworks. Gujarat and Tamil Nadu manufacturing corridors are seeing the steepest greenfield software procurement.
Preventive Maintenance Software Market Competitive Environment
Global majors compete with regional champions across integration depth and compliance-grade validation capabilities. The vendor base clusters around three tiers: ERP-native suites with deep manufacturing procurement channels, industrial automation specialists with OT-domain expertise, and cloud-native challengers with API-first architectures. Dominant competitive moves include vertical integration into sensor hardware and strategic partnerships with semiconductor fabricators to secure chip supply.
Within the ERP-native tier, SAP SE and Oracle Corporation exemplify database-centric architectures that extend real-time asset monitoring into enterprise data lakes. IBM Corporation occupies a distinct position anchoring predictive analytics capabilities through its Watson IoT backbone across heavy industrial accounts. These three entities represent contrasting approaches to compliance architecture: SAP through deep manufacturing procurement integration, Oracle through data lake extensibility, and IBM through AI-infused inference layers.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Schneider Electric SE |
| Honeywell |
| Rockwell Automation, Inc. |
| Infor, Inc. |
| Bentley Systems, Incorporated |
| GE Digital |
| Others |
Value Chain & Pricing Dynamics
German automotive OEM procurement clusters anchor pricing power for preventive maintenance platforms, compressing vendor margins through three-year subscription standardization while EU AI Act compliance premiums sustain tier separation.
Pricing Analysis
Input-cost pass-through from semiconductor sensor components and cloud infrastructure fees is reshaping SaaS tier boundaries. Pricing stratifies across FDA-validated, CE-marked, and standard deployment tiers, with certification grade commanding 40-60% premiums. Cost compression in mid-market manufacturing subscriptions is intensifying because Japanese precision toolmakers negotiate volume aggregation. Healthcare facilities prove least price-sensitive due to 21 CFR Part 11 validation lock-in, while mid-sized food processors exhibit highest elasticity.
Supply Chain Analysis
Industrial-grade sensor chip fabrication rests on Taiwan and South Korea, with cloud data center capacity concentrating in the United States, Germany, and Japan. Critical inputs include ARM-based microcontrollers, RFID tags, and hyperscaler compute instances. Single-source vulnerability in Taiwan semiconductor fabrication exposes platform vendors to geographic supply shocks. Distribution runs through direct enterprise sales teams with implementation service bundling, supplemented by SAP and Oracle channel partnerships for ERP-integrated deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive maintenance software has matured into a late-cycle quality market where FDA-validated and CE-marked platforms capture disproportionate value as industrial buyers prioritize audit-grade documentation over cost minimization.
For Market Incumbents: To counter cloud-native challengers with API-first architectures, SAP and Oracle must deepen ERP integration moats while IBM accelerates Watson IoT edge deployment. Certification investment in FDA 21 CFR Part 11 and EU Machinery Directive compliance creates switching cost barriers against unvalidated entrants. Backward integration into sensor hardware secures supply continuity against Taiwan concentration risk. For New Entrants and Emerging Players: Capture mid-sized food processing facilities in Italy and Spain previously priced out of IoT deployments, where RFID cost collapse below five dollars per unit enables greenfield penetration. India's PLI scheme manufacturing corridors offer the most penetrable geography for native platform builds. Channel partnerships with local system integrators bypass direct competition with ERP-native incumbents. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking OT-domain expertise to complement hardware portfolios. Five-to-ten year viability hinges on carbon accounting module development under CSRD convergence. Watch for SEC climate disclosure rulemaking as inflection signal for emissions-tracking maintenance platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep CMMS interoperability with SAP and Oracle systems captures manufacturing procurement channels. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure secure elastic cloud capacity for multi-tenant architectures. |
| Acquisition of Specialist Firm | Edge-native vibration analysis startups compress latency for automotive stamping plant deployments. |
| Geographic Expansion | Greenfield presence in Gujarat and Tamil Nadu corridors leverages India's PLI scheme incentives. |
| Product Launch | CSRD-compliant carbon accounting modules open new revenue streams from European industrial accounts. |
Study Parameters
Bottom-up manufacturing facility modeling reconciled against top-down cloud vendor tracking forms the analytical core. Primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combine with secondary validation against SEC 10-K filings, EU Machinery Directive compliance databases, and METI industrial standards documentation. Triangulation between demand-side deployment surveys and supply-side platform vendor disclosures ensures coverage alignment.
Historical trendline analysis of subscription revenue conversion and sensor hardware cost curves informs projection mechanics across deployment model, organization size, vertical integration complexity, and regional adoption pattern dimensions. CAGRs derive from segment-level run-rate aggregation against regulatory mandate timing. Edge computing penetration rates and FDA validation pipeline throughput serve as industry-specific forecast inputs throughout the modeling period.
Regulatory enforcement delays, semiconductor supply disruption, and ERP upgrade cycle extension are the dominant revision risks. Forecasts reflect assumptions about EU AI Act implementation timelines and cloud migration cost absorption capacity. A concentrated set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Charity Accounting Software Market
Software & Services
Photo Editing Software Market
Software & Services
US Software Consulting Market
Software & Services
PCB CAD Software Market
Software & Services
Live Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Global IVR Software Market
Software & Services
Architecture, Engineering, and Construction (AEC) Software Market
Software & Services
Job Description Management Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
US Enterprise Legal Management Software Market
Software & Services
Global Survey Software Market
Software & Services
Combat Management Systems Software Market
Software & Services
Programmable Automation Controller Software Market
Software & Services
Website Builder Tool Market
Software & Services
Global Policy Management Software Market