
 Global Application Release Automation Market | 2026-2036
Global Application Release Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Application Release Automation Market Foresight
Cloud-native CI/CD pipelines is reshaping how enterprises validate and push code to production, replacing manual handoffs with policy-governed automation. Microsoft Corporation leverages its Azure DevOps ecosystem to anchor enterprise release workflows across hybrid environments. IBM Corporation competes through specialized mainframe DevOps integration that sustains relevance in financial services infrastructure. Broadcom Inc. dominates the mainframe application testing segment through its acquisition-derived portfolio depth.
Application Release Automation encompasses the tools, platforms, and practices that orchestrate the movement of software from development through staging to production environments, incorporating environment provisioning, artifact management, and rollback capabilities with sub-minute recovery objectives. Its primary commercial purpose is eliminating deployment failures that cost enterprises revenue and customer trust during critical release windows. Deployment Automation leads solution adoption as organizations eliminate snowflake server configurations, while Release Orchestration captures expanding margin pools through SaaS-based value-added analytics. Hybrid Cloud deployment environments represent the fastest-growing structural segment as enterprises straddle legacy data center investments with elastic public cloud capacity.
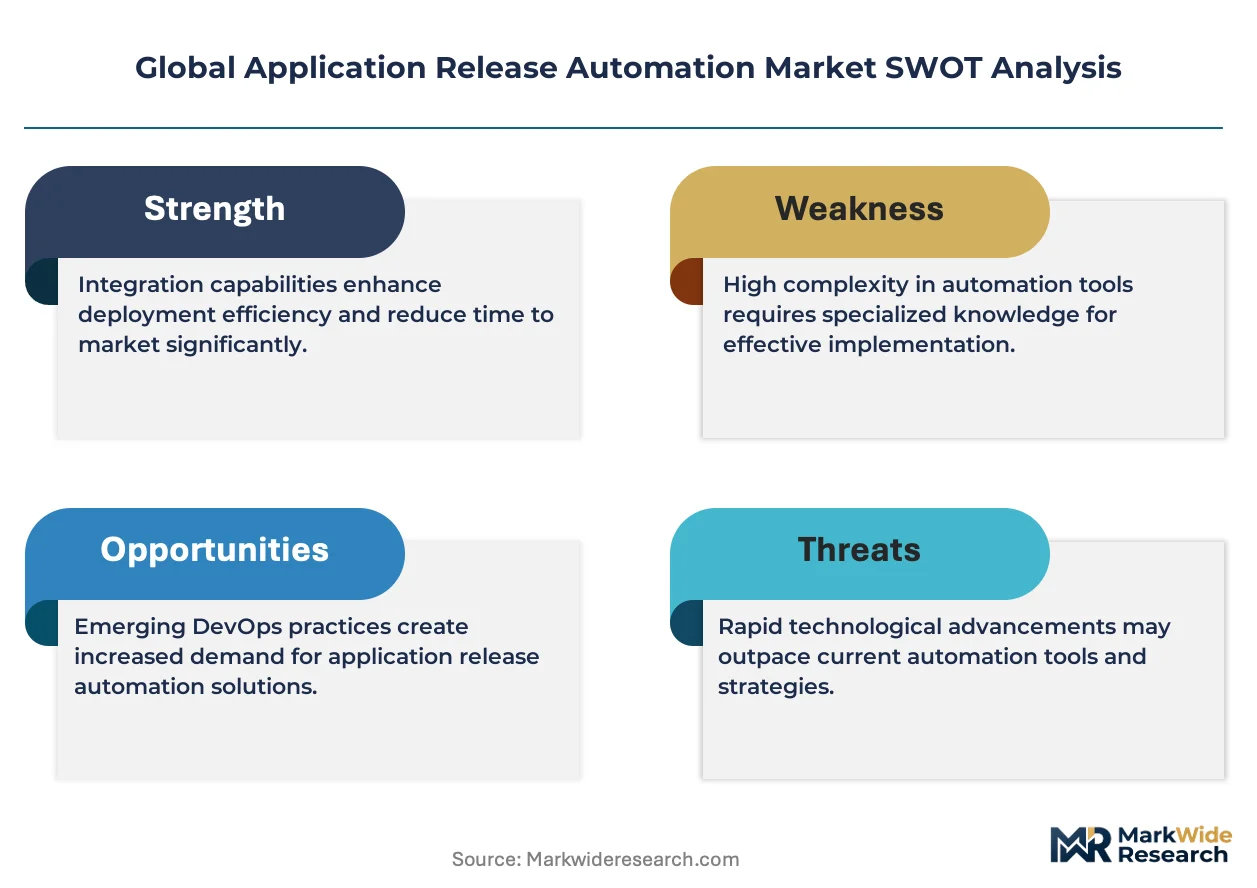
FedRAMP authorization requirements from US government agencies shape product roadmaps for vendors serving federal IT modernization contracts. The EU AI Act and GDPR impose algorithmic accountability and data residency constraints on automated release pipelines processing personal information in European deployments. ISO 27001 and SOC 2 Type II certifications function as table stakes for vendor selection in BFSI procurement cycles. Stakeholders must monitor how platform engineering team budgets reallocate between bundled suite purchases and best-of-breed toolchain assembly.
Market Dynamics
Containerization and Kubernetes-native tooling are displacing legacy script-based release methods across enterprise IT estates, forcing vendors to rearchitect platforms for ephemeral infrastructure while maintaining compliance audit trails.
Growth Catalysts
- FedRAMP Authorization:US government agencies mandate FedRAMP-authorized release automation platforms for federal IT modernization contracts, creating a compliance-driven procurement pipeline for vendors.
- Financial Services DevOps:Banks and insurers in North America deploy release orchestration tools to satisfy SEC and FINRA audit requirements for deployment traceability.
- GitOps Methodologies:Infrastructure-as-code practices using Git as the single source of truth are accelerating automated rollback capabilities and environment consistency.
Market Restraints
- Legacy Mainframe Integration Costs:Enterprises with IBM z/OS estates face prohibitive integration expenses connecting modern CI/CD pipelines to COBOL-based release workflows.
- Specialized Talent Scarcity:Shortage of platform engineers with Kubernetes, Helm, and policy-as-code expertise constrains deployment velocity for mid-market adopters.
- Toolchain Fragmentation:Proliferation of point solutions for security scanning, artifact management, and observability creates integration debt and vendor management overhead.
Strategic Opportunities
- EU AI Act Compliance:European enterprises require automated governance checkpoints in release pipelines for algorithmic accountability, creating demand for policy-as-code enforcement tools.
- India PLI Scheme:Manufacturing incentives under India's Production Linked Incentive scheme are driving software localization requirements and domestic data center buildouts.
- Edge Computing Deployments:Convergence of 5G network slicing and container orchestration enables automated application delivery to distributed edge nodes in telecommunications infrastructure.
Industry Challenges
- Platform Engineering Skill Gaps:Organizations struggle to staff internal platform teams capable of maintaining self-service developer portals and golden path templates.
- Multi-Cloud Policy Consistency:Engineering teams face complexity harmonizing security policies across AWS, Azure, and GCP deployment targets without configuration drift.
- SOC 2 Type II Audit Burden:SaaS release automation vendors must sustain continuous compliance monitoring and evidence collection for BFSI procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Application Release Automation Market |
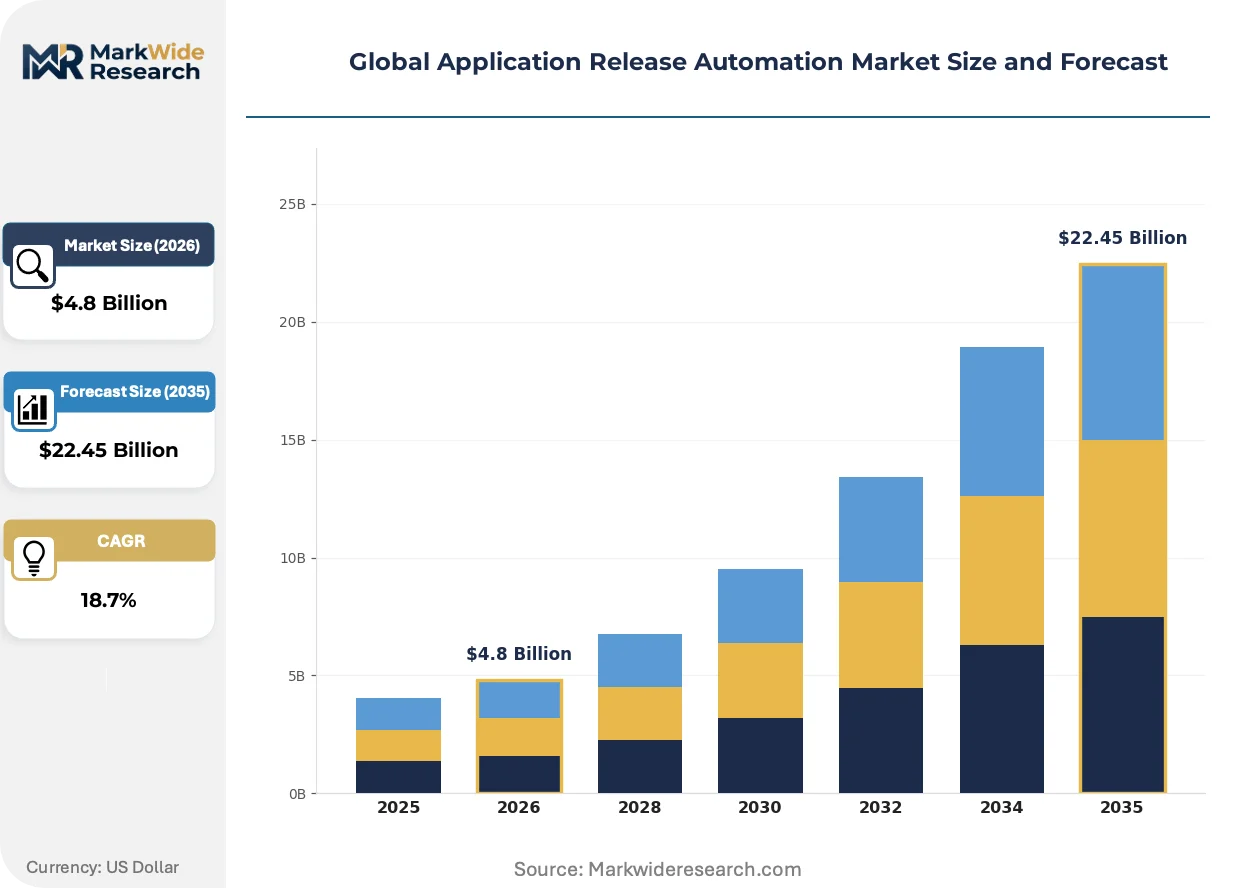
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Deployment Automation, Release Orchestration, Configuration Management, Compliance Management, Monitoring Deployment Environment: On-Premises, Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User Industry: BFSI, Telecommunications, IT & Software, Government Organizations, Media & Entertainment Application: Continuous Delivery, Continuous Integration, Infrastructure Automation, Testing Automation, Change Management |
| Companies Covered | Microsoft Corporation, IBM Corporation, Broadcom Inc., Micro Focus International plc, BMC Software Inc., Red Hat, Inc., VMware, Inc., CloudBees, Inc., Digital.ai, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Application Release Automation Market Shifts & Advancements
Release automation platforms are embedding intelligence and governance deeper into deployment pipelines, transforming from execution engines into policy enforcement layers. This evolution reflects pressure from regulated sectors demanding provable compliance at velocity.
Agentic AI for deployment validation is digitizing pre-production testing by autonomously generating test scenarios from production traffic patterns. Financial services firms in London and Singapore are piloting these systems to compress release validation cycles. The technology is digitizing risk assessment workflows that previously required manual security and performance sign-offs.
The EU AI Act's algorithmic accountability requirements are mandating automated documentation generation and bias detection checkpoints within European release pipelines. Vendors serving German automotive and French healthcare sectors must embed model cards and explainability artifacts into deployment artifacts. This regulatory compression is favoring platforms with native policy-as-code frameworks over bolt-on compliance modules.
Platform engineering team budgets are rotating toward internal developer platforms that abstract toolchain complexity behind self-service interfaces. Enterprise buyers in the United States and United Kingdom are consolidating point solutions into bundled suites with embedded analytics. This procurement consolidation pressures best-of-breed vendors to demonstrate integration depth or risk displacement during contract renewals.
Global Application Release Automation Market Segmentation
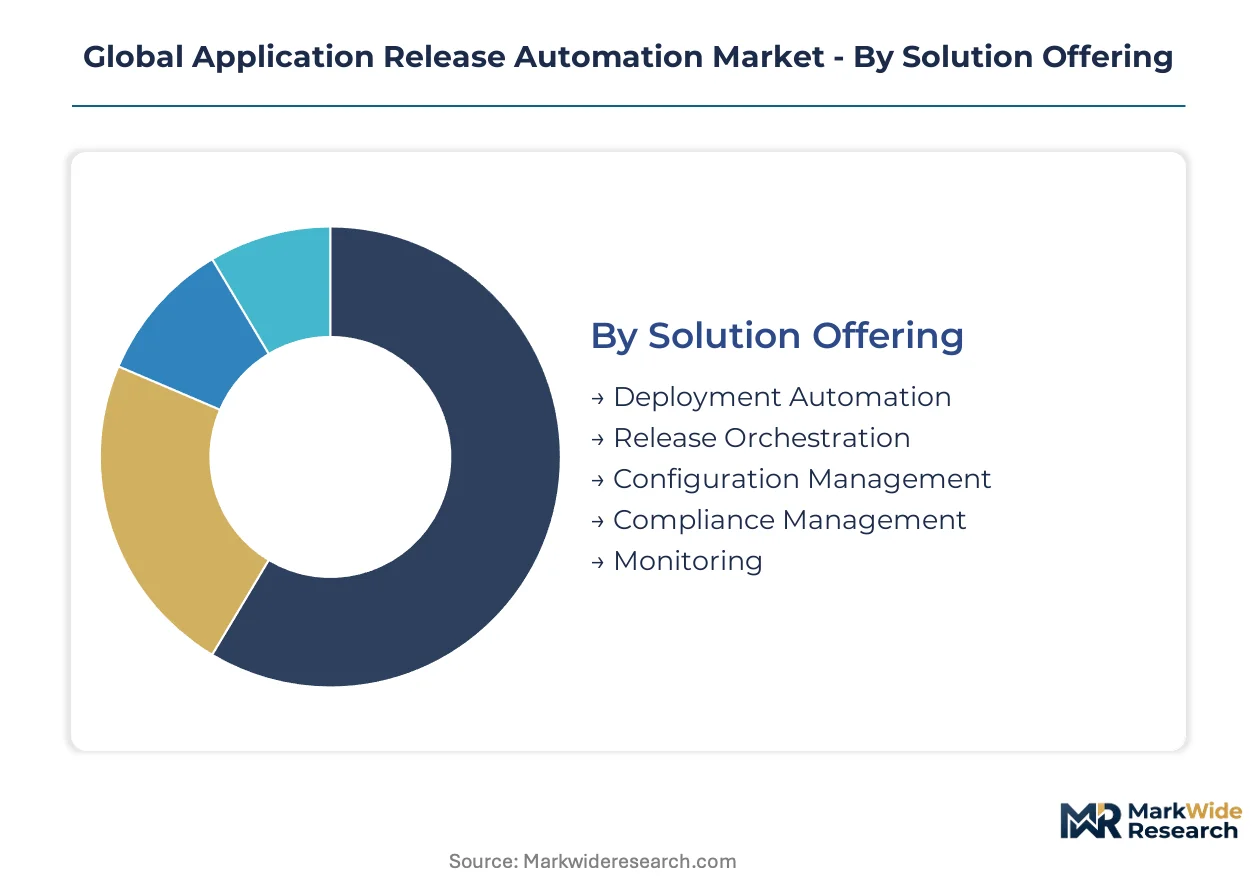
Application Release Automation vendors structure product portfolios around deployment velocity requirements and compliance posture. Segmentation reveals where platform engineering budgets concentrate and which infrastructure patterns command premium pricing.
Solution Offering:
Mature deployment tooling dominates procurement budgets while emerging governance modules capture expanding margin pools.
- Deployment Automation:Eliminates snowflake server configurations through standardized artifact promotion and environment provisioning. Financial services firms in the United States deploy these tools to satisfy SEC audit requirements for deployment traceability and rollback capabilities.
- Release Orchestration:Coordinates multi-stage pipelines across distributed teams with policy-governed approval gates. SaaS-based deployments with embedded analytics are climbing the fastest as enterprises consolidate point solutions into bundled suites.
- Configuration Management:Maintains environment consistency through infrastructure-as-code repositories and drift detection.
- Compliance Management:Embeds automated evidence collection and audit trail generation directly into deployment workflows.
- Monitoring:Provides real-time pipeline observability with sub-minute recovery objective tracking.
Deployment Automation handles the majority of throughput; Release Orchestration is expanding most quickly on share.
Deployment Environment:
Cost tier segmentation separates legacy data center commitments from elastic consumption models.
- Hybrid Cloud:Straddles on-premises investments with burst capacity to public cloud, requiring policy consistency across boundaries. Enterprises in Germany and Japan prioritize this model for data residency compliance under GDPR and METI guidelines.
- Public Cloud:Delivers fully managed release automation through hyperscaler marketplaces with consumption-based pricing. FedRAMP-authorized platforms in the United States are gaining share fastest among government contractors.
- On-Premises:Retains complete control over deployment infrastructure for air-gapped environments.
- Private Cloud:Offers dedicated tenancy with cloud-native tooling on owned hardware.
- Multi-Cloud:Harmonizes release pipelines across AWS, Azure, and GCP deployment targets.
On-Premises retains the largest installed base; Hybrid Cloud shows the steepest expansion trajectory.
End User Industry:
Application patterns vary sharply by regulatory exposure and release frequency requirements.
- BFSI:Demands SOC 2 Type II certified platforms with immutable audit trails for FINRA and SEC examinations. Banks in Singapore and Switzerland deploy these tools to compress release windows without compromising compliance posture.
- IT & Software:Prioritizes developer velocity through self-service portals and golden path templates. Technology firms in India and Israel are climbing fastest as platform engineering teams mature.
- Telecommunications:Orchestrates 5G network slicing and edge container deployments.
- Government Organizations:Mandates FedRAMP authorization for federal IT modernization contracts.
- Media & Entertainment:Supports high-velocity content delivery with elastic scaling requirements.
BFSI commands the highest average contract values; IT & Software is gaining share fastest.
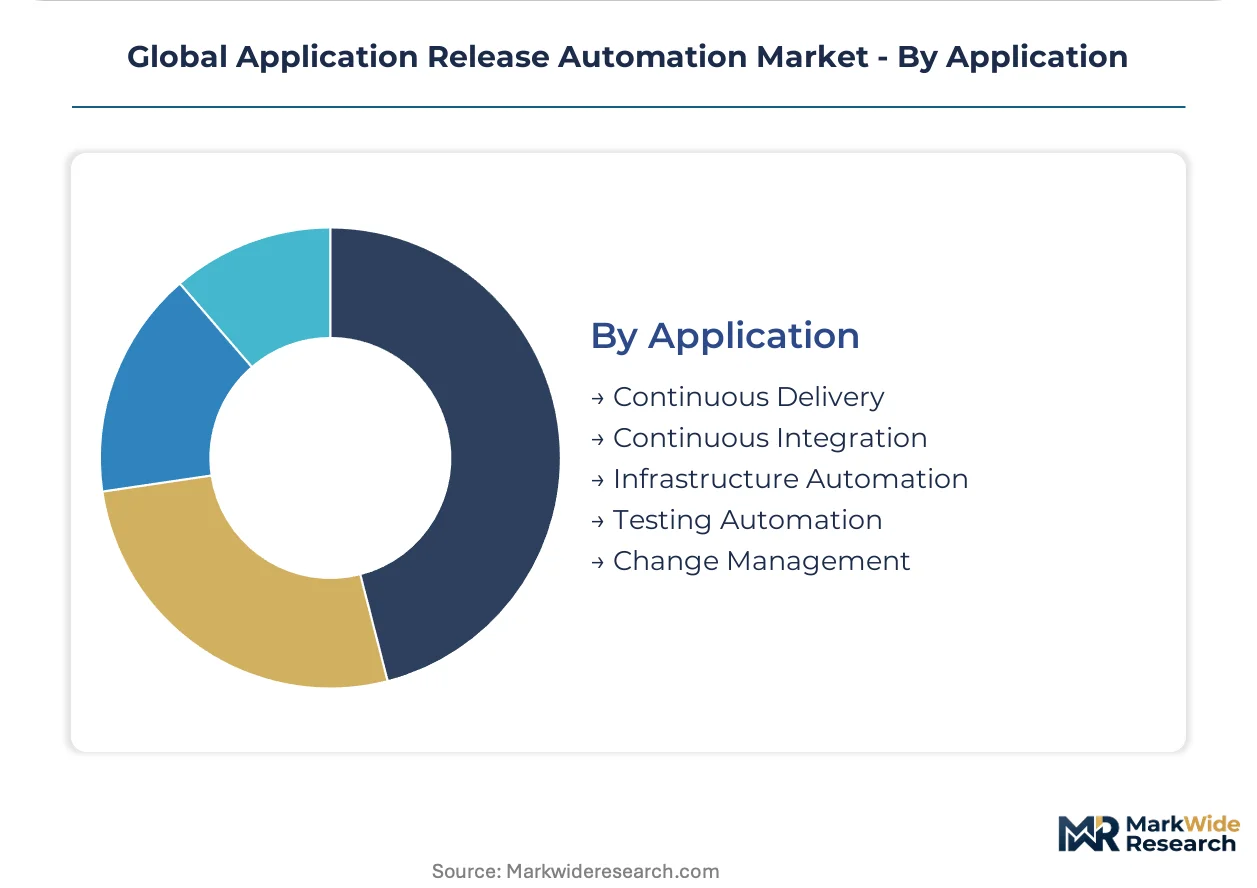
Application:
Functional use cases map to distinct stages of the software delivery lifecycle.
- Continuous Delivery:Automates the complete path from code commit to production deployment with automated rollback triggers. Enterprises in the United Kingdom and Australia adopt these pipelines to eliminate manual handoffs.
- Continuous Integration:Validates code changes through automated build and test execution. GitOps methodologies using Git as single source of truth are accelerating adoption in Nordic markets.
- Infrastructure Automation:Provisions and configures environment resources through declarative specifications.
- Testing Automation:Integrates security scanning and performance validation into pipeline gates.
- Change Management:Enforces approval workflows and risk assessment documentation.
Continuous Delivery anchors enterprise spending; Continuous Integration is climbing fastest on deployment velocity demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israeli platform engineering firms export release orchestration expertise to German automotive manufacturers seeking EU AI Act compliance tooling. This trade corridor reflects broader patterns where specialized DevOps capability concentrates in technology clusters and diffuses into regulated manufacturing economies.
United States
FedRAMP authorization mandates from federal agencies drive procurement of government-compliant release automation platforms. SEC audit requirements for deployment traceability shape vendor roadmaps serving financial services buyers. Platform engineering teams in San Francisco and Seattle anchor enterprise adoption of Kubernetes-native tooling for hybrid cloud estates.
Germany
Automotive OEMs in Stuttgart and Munich deploy policy-as-code frameworks to satisfy EU AI Act algorithmic accountability requirements. The KBA and national data protection authorities enforce strict documentation standards for automated pipelines processing personal information. Industrial software clusters in Bavaria specialize in mainframe DevOps integration for legacy manufacturing systems.
United Kingdom
Financial services firms in the City of London compress release windows while maintaining FCA and PRA audit trails for deployment governance. GitOps methodologies accelerate adoption among technology firms in Manchester and Cambridge seeking environment consistency. Platform engineering budgets rotate toward bundled suites with embedded compliance analytics.
India
IT services exporters in Bangalore and Hyderabad build internal developer platforms to serve North American and European enterprise clients. The PLI scheme for manufacturing drives software localization requirements and domestic data center investments. Platform engineering talent scarcity constrains deployment velocity for mid-market adopters outside major technology hubs.
Singapore
Banks and asset managers deploy release orchestration tools to satisfy MAS technology risk management guidelines for deployment traceability. The Monetary Authority of Singapore mandates immutable audit trails for financial institutions' critical system changes. Technology clusters in one-north and Changi Business Park anchor regional headquarters for multinational DevOps vendors.
Global Application Release Automation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where hyperscaler ecosystems anchor enterprise procurement. Consolidation pressures intensify as platform engineering teams consolidate point solutions into bundled suites. Three archetypes dominate: hyperscaler-anchored suites, mainframe DevOps specialists, and Kubernetes-native challengers. Dominant competitive moves include strategic partnerships with cloud providers and portfolio diversification into policy-as-code governance modules.
Among North American technology conglomerates, Microsoft Corporation and IBM Corporation exemplify contrasting platform strategies. Microsoft anchors enterprise workflows through Azure DevOps ecosystem integration across hybrid environments. IBM sustains relevance in financial services infrastructure through specialized mainframe DevOps capabilities. CloudBees, Inc. occupies a position within the Kubernetes-native specialist tier, representing the shift toward GitOps-centered release methodologies.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Broadcom Inc. |
| Micro Focus International plc |
| BMC Software Inc. |
| Red Hat, Inc. |
| VMware, Inc. |
| CloudBees, Inc. |
| Digital.ai, Inc. |
| Others |
Supply & Pricing Matrix
San Francisco Bay Area platform engineering talent clusters anchor premium pricing for Kubernetes-native release automation, with vendor concentration in this hub translating into sustained margin capture for FedRAMP-authorized suites serving federal contractors.
Pricing Analysis
Legacy script-based tooling, current-generation SaaS orchestration platforms, and emerging agentic AI-augmented pipelines occupy distinct pricing tiers. Subscription-based SaaS tiers dominate revenue models, with FedRAMP authorization and SOC 2 Type II certification functioning as primary price differentiation drivers. Cost compression in mid-market segments intensifies as hyperscaler marketplaces commoditize baseline deployment automation. Government contractors exhibit lowest price sensitivity due to compliance mandates, while mid-market IT services firms in India face acute budget constraints.
Supply Chain Analysis
Flex, Jabil, and specialized DevOps tooling foundries in Taiwan, Ireland, and the United States hold concentrated contract-manufacturing capacity for release automation hardware appliances. Intellectual property development draws from open-source Kubernetes communities, proprietary policy-as-code frameworks, and hyperscaler API ecosystems. Single-source vulnerability around GitOps repository providers represents structural risk. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and systems integrators serving BFSI verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform engineering team consolidation into bundled suite procurement has shifted buyer power toward CIO-led vendor rationalization programs, compressing margins for point-solution specialists unable to demonstrate integration depth.
For Market Incumbents: Insulate core revenue streams by deepening mainframe DevOps integration for financial services incumbents and accelerating policy-as-code module development to capture EU AI Act compliance budgets. Threat from Kubernetes-native challengers demands counter-investment in internal developer platform abstraction layers. Certification maintenance in FedRAMP and ISO 27001 anchors renewal rates. For New Entrants and Emerging Players: Mid-market platform engineering teams in Southeast Asian manufacturing hubs represent the most penetrable entry point for GitOps-native tooling without legacy integration burdens. European automotive OEMs scrambling for algorithmic accountability automation offer second white-space target. Go-to-market through hyperscaler co-selling programs bypasses direct enterprise sales cost structure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors policy-as-code governance specialists with embedded compliance analytics over pure-play deployment automation vendors. Long-term viability rests on ability to serve regulated sector procurement cycles with continuous audit evidence generation. Watch for platform engineering budget reallocation velocity as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks federal IT modernization contract access for vendors serving government buyers. |
| Policy-as-Code Module Development | Captures EU AI Act compliance budgets from German automotive and French healthcare sectors. |
| Mainframe DevOps Integration | Sustains relevance in North American financial services infrastructure with COBOL interoperability. |
| Hyperscaler Marketplace Listing | Reduces customer acquisition cost through Azure, AWS, and GCP co-selling program participation. |
| Internal Developer Platform Acquisition | Consolidates point solutions into self-service portals with embedded golden path templates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with platform engineering directors, DevOps tooling procurement officers, compliance auditors at BFSI institutions, and federal IT contractors; alongside secondary validation through SEC 10-K filings, hyperscaler capex disclosures, FedRAMP authorization databases, and open-source project contribution metrics. Bottom-up deployment velocity estimates triangulated against top-down platform engineering budget surveys.
Forecast inputs considered deployment environment segmentation, solution tier adoption curves, and vertical compliance intensity across the projection horizon. Modeled dimensions spanned SaaS versus on-premises deployment models, enterprise versus mid-market organization scale, and regulated versus non-regulated vertical penetration. CAGRs derived from historical platform engineering budget reallocation patterns and compliance mandate implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in federal IT spending cycles, hyperscaler infrastructure investment, or EU regulatory enforcement intensity would shift the trajectory. Quarterly review of FedRAMP authorization velocity, platform engineering headcount growth, and compliance fine issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software As a Service (Saas) Market
Software & Services
Library Management Software Market
Software & Services
Human Resource Management Software Market
Software & Services
Mobile Backend As a Service (Mbaas) Market
Software & Services
Global Data Governance Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Global Decision Support Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Audio Editing Software Market
Software & Services
Preschool Education Software Market
Software & Services
Global Server Management Software Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Global Coworking Space Management Software Market
Software & Services
BIM Objects Software Market
Software & Services
Global Brain Training Software Market