
 Social Software As a Collaborative ERP Tool Market | 2026-2036
Social Software As a Collaborative ERP Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Social Software As a Collaborative ERP Tool Market Analytics
Enterprise software developer talent is collapsing across North America and Western Europe, forcing vendors to automate platform deployment and reduce implementation friction. Microsoft Corporation leverages its Azure infrastructure to bundle collaborative ERP modules with existing productivity suites. Salesforce Inc anchors its position through deep CRM-to-ERP workflow integration that reduces custom coding requirements. Atlassian Corporation Plc specializes in project management tools that bridge agile methodologies with resource planning systems.
Social software as a collaborative ERP tool refers to platforms that embed real-time messaging, document sharing, and task coordination directly into enterprise resource planning workflows, typically operating through REST APIs and single-sign-on architectures that synchronize with legacy databases. These systems serve primarily to eliminate silos between operational departments and reduce email-dependent coordination overhead. Cloud-based deployment leads in new implementations due to lower capital requirements and faster rollout cycles, while on-premises solutions retain share among healthcare and defense end users with strict data residency requirements. Manufacturing end users represent the fastest-growing segment as shop-floor-to-office connectivity demands rise, whereas document management solutions capture mature margin pools in regulated industries.
FDA 21 CFR Part 11 requirements shape validation protocols for collaborative tools deployed in pharmaceutical manufacturing, while GDPR and the EU AI Act mandate audit trails and algorithmic transparency in European deployments. The SEC's cybersecurity disclosure rules are extending compliance burdens to ERP-adjacent platforms used by publicly traded firms. Stakeholders must weigh whether to consolidate around integrated suites from dominant vendors or maintain modular architectures that permit vendor switching as regulatory thresholds tighten.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for collaborative ERP tools, forcing legacy vendors to re-platform or lose manufacturing accounts to agile competitors with lower implementation friction.
Growth Catalysts
- EU AI Act compliance mandates:European manufacturers must embed algorithmic audit trails into collaborative workflows, creating mandatory upgrade cycles for ERP-adjacent platforms.
- Shop-floor connectivity demands:German Mittelstand firms require real-time coordination between production lines and back-office planning systems.
- REST API standardization:Universal interface protocols reduce custom integration costs and accelerate multi-vendor environment deployments.
Market Restraints
- Specialized developer scarcity:Enterprise software engineering talent shortages in North America and Western Europe inflate implementation costs and extend project timelines.
- Healthcare data residency requirements:Strict localization mandates in defense and pharmaceutical sectors block cloud-first vendors from capturing on-premises share.
- Legacy database synchronization complexity:Cobol-era ERP systems resist real-time API integration, forcing expensive middleware layers.
Strategic Opportunities
- India's PLI scheme for manufacturing:Subsidized domestic production capacity creates demand for integrated communication and resource planning tools among new industrial entrants.
- FDA 21 CFR Part 11 validation protocols:Pharmaceutical manufacturers require compliant collaborative platforms, opening specialized vertical markets.
- Edge-to-cloud workflow convergence:Combining IoT sensor streams with centralized ERP dashboards enables predictive maintenance integrations.
Industry Challenges
- Single-sign-on architecture complexity:Multi-factor authentication requirements across federated identity systems create user experience friction and support ticket volume.
- GDPR audit trail implementation:Real-time messaging platforms must reconstruct conversation histories for regulatory examinations without performance degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Social Software As a Collaborative ERP Tool Market |
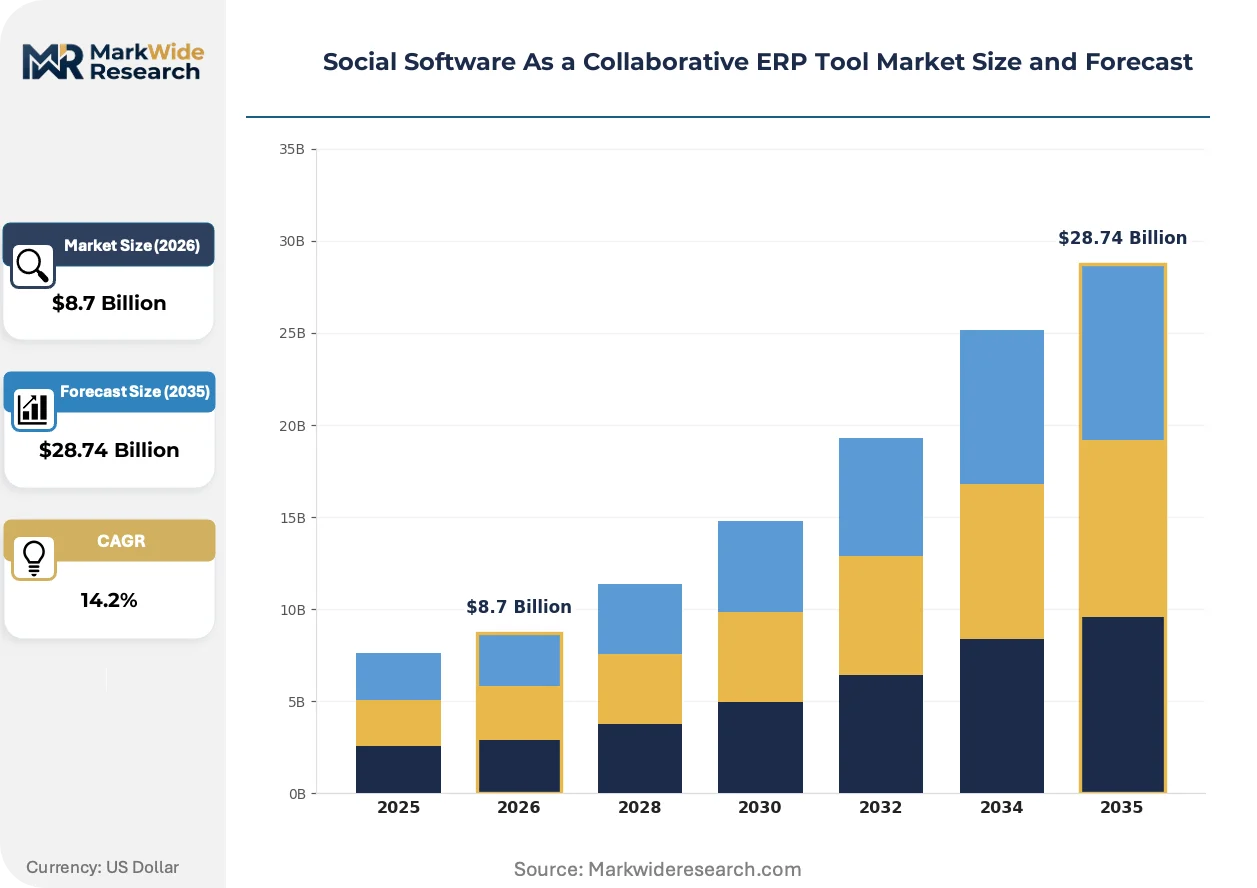
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Manufacturing, Retail, Healthcare, Education Solution: Project Management, Document Management, Communication, Analytics Feature: Real-Time Collaboration, User Access Control, Integration Capabilities, Reporting Tools |
| Companies Covered | Microsoft Corporation, Salesforce Inc, Google LLC, Zoom Video Communications Inc, Atlassian Corporation Plc, Cisco Systems, Oracle Corporation, IBM Corporation, Epicor Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Social Software As a Collaborative ERP Tool Market Evolving Landscape
Embedded collaboration layers are displacing standalone communication tools as manufacturers demand unified environments where messaging, document control, and resource planning share a single data model.
Microservices-based ERP modules are miniaturizing monolithic system architectures. Discrete manufacturing operations in Germany adopt containerized deployment patterns that isolate shop-floor data streams from corporate financial systems. This fragmentation is miniaturizing vendor lock-in risks and accelerating replacement cycles for legacy suites.
GDPR and the EU AI Act are mandating algorithmic transparency in automated workflow recommendations. European deployments now require explainable AI documentation for resource allocation suggestions. Pharmaceutical manufacturers face the steepest compliance burden as FDA 21 CFR Part 11 overlaps with European data governance requirements.
Subscription pricing for collaborative ERP tools is compressing traditional perpetual license models. German automotive suppliers and French aerospace subcontractors favor consumption-based arrangements that scale with project volume. This shift pressures vendors to meter API calls and storage rather than seat counts.
Social Software As a Collaborative ERP Tool Market Segmentation
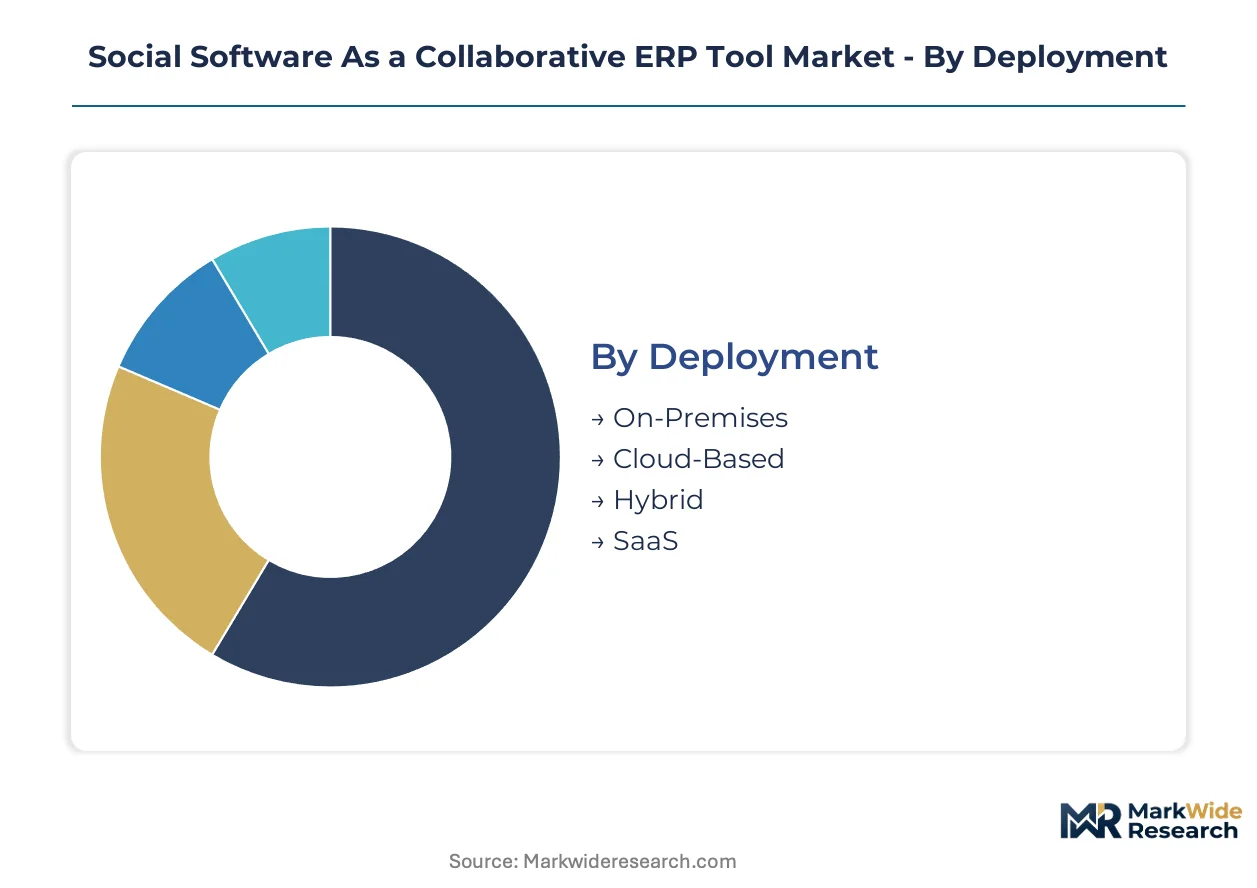
Segmentation in the Social Software As a Collaborative ERP Tool Market reveals how deployment choices, end-user requirements, and solution architectures determine vendor profitability. Each dimension exposes distinct margin pressures and growth vectors that shape competitive positioning.
Deployment:
Margin pools concentrate in recurring revenue models that minimize customer acquisition costs and extend lifetime value.
- Cloud-Based:Multi-tenant architectures distribute infrastructure costs across tenant bases while enabling automatic feature updates. German automotive suppliers and French aerospace subcontractors favor consumption-based arrangements that scale with project volume, compressing traditional perpetual license models.
- SaaS:Subscription metering around API calls and storage rather than seat counts aligns vendor incentives with customer usage patterns. Indian manufacturing entrants under the PLI scheme prefer SaaS deployments for rapid rollout without capital expenditure burdens.
- On-Premises:Healthcare and defense sectors with strict data residency requirements sustain this segment despite higher total cost of ownership.
- Hybrid:Combines edge processing for sensitive operations with cloud analytics for cross-facility visibility.
The dominant share belongs to Cloud-Based, while SaaS is closing the gap fastest.
End User:
Application intensity varies sharply across sectors, with operational complexity dictating solution sophistication and pricing power.
- Manufacturing:Shop-floor-to-office connectivity demands drive the steepest expansion trajectory as industrial IoT integration becomes mandatory. German Mittelstand firms require real-time coordination between production lines and back-office planning systems.
- Healthcare:FDA 21 CFR Part 11 validation protocols and strict localization mandates create specialized vertical markets with defensible margins.
- Retail:Omnichannel inventory synchronization and workforce scheduling dominate functional requirements.
- Education:Budget constraints favor lightweight implementations with limited customization scope.
Manufacturing commands the largest revenue base, though Healthcare delivers superior margin retention.
Solution:
Customer type determines module bundling strategies, with integrated suites capturing enterprise accounts and point solutions penetrating mid-market niches.
- Project Management:Agile methodology bridges with resource planning systems through containerized deployment patterns. Discrete manufacturing operations in Germany adopt microservices that isolate shop-floor data streams from corporate financial systems.
- Document Management:Mature margin pools in regulated industries where version control and audit trails carry compliance weight. Pharmaceutical manufacturers face overlapping FDA and European data governance requirements.
- Communication:Real-time messaging platforms must reconstruct conversation histories for GDPR examinations without performance degradation.
- Analytics:Predictive maintenance integrations combine IoT sensor streams with centralized ERP dashboards.
Project Management leads in new deal volume, while Document Management sustains the highest renewal rates.
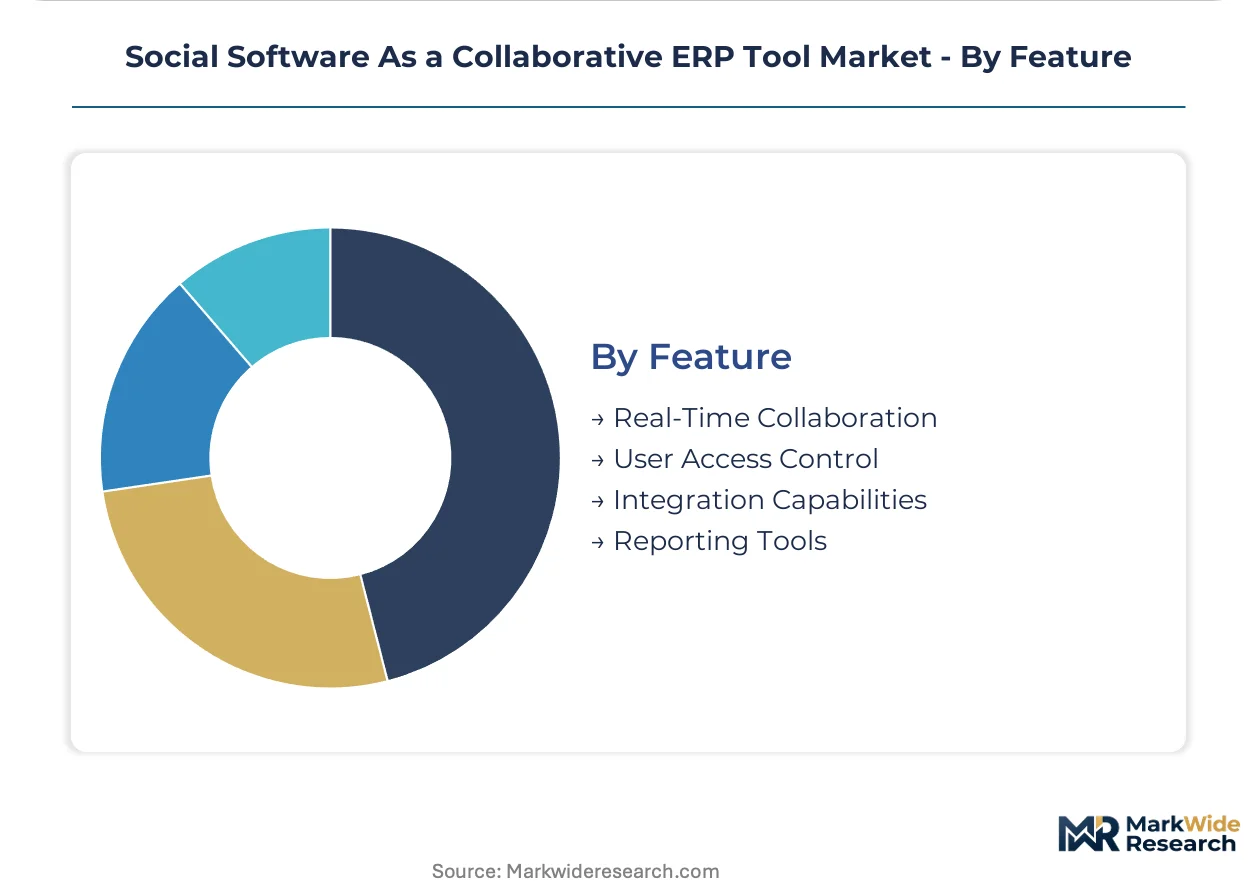
Feature:
Technology maturity separates commodity functionality from differentiated capabilities that command pricing premiums.
- Integration Capabilities:REST API standardization reduces custom integration costs and accelerates multi-vendor environment deployments. Universal interface protocols enable synchronization with legacy databases through single-sign-on architectures.
- Real-Time Collaboration:Embedded layers displace standalone communication tools as manufacturers demand unified environments where messaging and resource planning share a single data model.
- User Access Control:Multi-factor authentication requirements across federated identity systems create user experience friction and support ticket volume.
- Reporting Tools:Explainable AI documentation for resource allocation suggestions becomes mandatory under EU AI Act compliance mandates.
Integration Capabilities anchors procurement decisions, with Real-Time Collaboration gaining priority in manufacturing RFPs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR and the EU AI Act anchor European demand for audit-ready collaborative ERP platforms. National regulators across manufacturing-heavy economies are mandating algorithmic transparency in automated workflow systems.
Germany
German Mittelstand manufacturers drive shop-floor-to-office connectivity investments. The KBA enforces strict data governance for automotive supply chain platforms. Industrial clusters in Baden-Württemberg and Bavaria deploy real-time coordination tools between production lines and back-office systems.
United States
Cloud-native ERP adoption accelerates among pharmaceutical manufacturers seeking FDA 21 CFR Part 11 validation. The SEC's cybersecurity disclosure rules extend compliance burdens to ERP-adjacent platforms. Boston and San Francisco Bay Area biotech clusters prioritize compliant collaborative environments.
India
PLI scheme beneficiaries require integrated communication tools for new manufacturing capacity. BIS standards shape data localization requirements for industrial software. Gujarat and Maharashtra industrial corridors attract SaaS deployments from domestic entrants.
Japan
Automotive and electronics manufacturers modernize legacy ERP through REST API integrations. METI guidelines promote supply chain digitization standards. Nagoya and Osaka industrial zones adopt microservices-based coordination platforms.
United Kingdom
Post-Brexit regulatory divergence creates demand for flexible compliance architectures. The Information Commissioner's Office enforces GDPR-aligned audit trail requirements. London financial services and Midlands manufacturing clusters seek hybrid deployment models.
Social Software As a Collaborative ERP Tool Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in collaborative ERP tooling. Cloud hyperscalers bundle messaging and resource planning modules into productivity suites, while pure-play vendors defend niches through agile methodology integration. Strategic archetypes include platform consolidators, vertical specialists, and API-native challengers. Dominant competitive moves encompass strategic partnerships with industrial IoT providers and geographic expansion through localized compliance offerings.
Within the platform consolidator tier, Microsoft Corporation and Salesforce Inc exemplify divergent integration strategies. Atlassian Corporation Plc occupies a position among agile methodology specialists bridging project management with enterprise resource planning. These three entities represent the primary competitive anchors in a market where REST API standardization and single-sign-on architectures determine customer stickiness.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Salesforce Inc |
| Google LLC |
| Zoom Video Communications Inc |
| Atlassian Corporation Plc |
| Cisco Systems |
| Oracle Corporation |
| IBM Corporation |
| Epicor Software |
| Others |
Value Network & Pricing Analysis
FDA 21 CFR Part 11 validation protocols gate both supplier qualification and price differentiation in pharmaceutical manufacturing deployments, forcing vendors to absorb compliance costs upfront while commanding certification premiums from buyers who cannot tolerate regulatory failure.
Pricing Analysis
Long-term subscription contracts dominate enterprise procurement, with German automotive suppliers and French aerospace subcontractors favoring consumption-based arrangements that meter API calls and storage rather than seat counts. Price differentiation rests on GDPR audit trail sophistication and EU AI Act algorithmic transparency certification, with healthcare buyers showing lowest price sensitivity due to compliance non-negotiability while Indian PLI scheme entrants drive cost compression through rapid SaaS adoption. Pricing pressure intensifies as REST API standardization commoditizes basic integration layers.
Supply Chain Analysis
Azure and AWS hyperscaler infrastructure concentration in Ireland, Germany, and Virginia creates single-source vulnerability for cloud-native deployments, while specialized edge hardware for hybrid configurations draws from Taiwan semiconductor fabs and Japanese industrial sensor manufacturers. Supply chain risk centers on EU data residency enforcement blocking cross-border instance migration. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships in manufacturing-heavy regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as shop-floor connectivity demands splinter buyer requirements across vertical-specific compliance regimes.
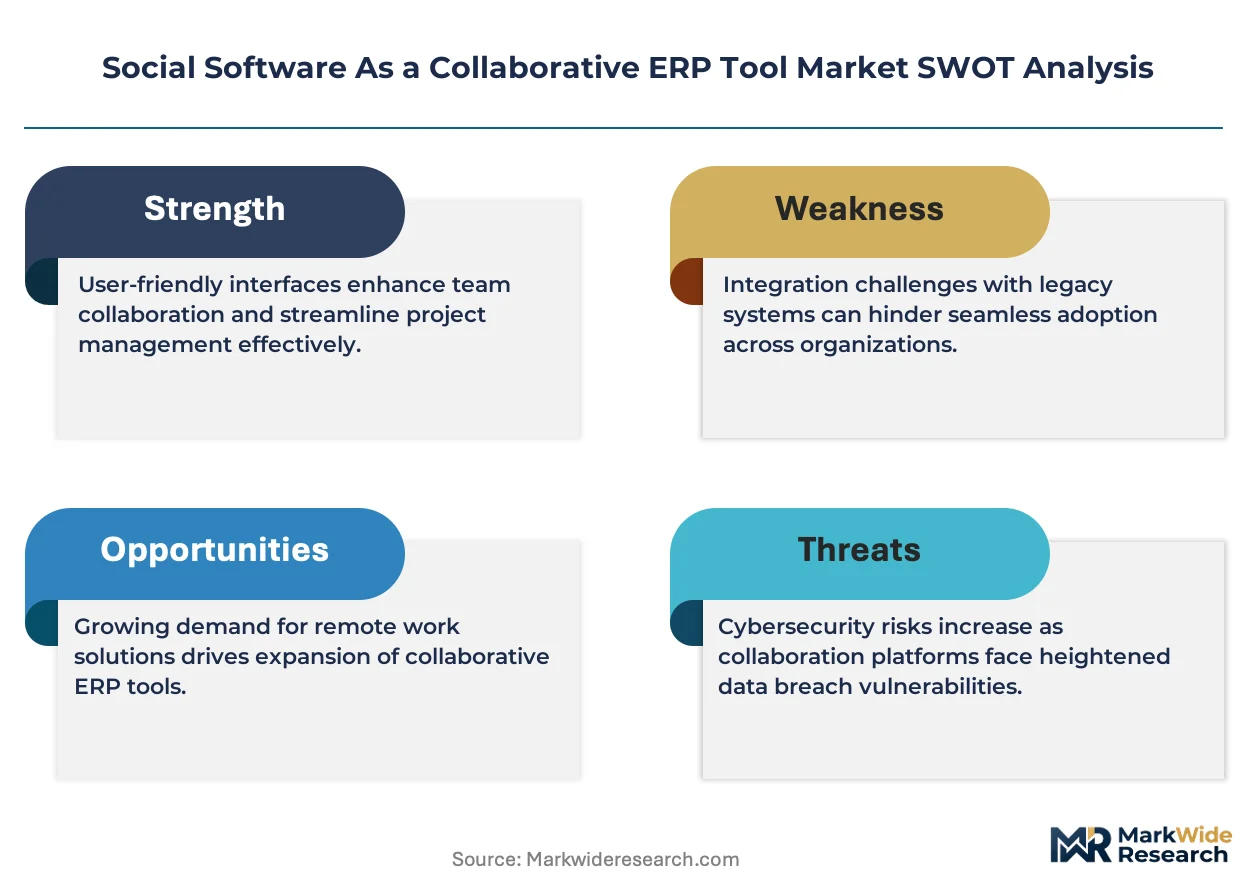
For Market Incumbents: Secure API-native challenger acquisition opportunities before REST standardization erodes integration moats. Fortify position through embedded algorithmic audit trail development that anticipates EU AI Act enforcement waves. Prioritize German Mittelstand account retention via localized edge-to-cloud deployment expertise. For New Entrants and Emerging Players: Lead with FDA 21 CFR Part 11 pre-validated modules targeting mid-tier pharmaceutical contract manufacturers underserved by suite consolidators. Penetrate India's PLI scheme manufacturing corridors through BIS-compliant SaaS offerings with rapid deployment guarantees. Anchor go-to-market around shop-floor IoT integration rather than back-office replacement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microservices-based ERP modules as containerization reduces infrastructure overhead. Target acquisition profiles should emphasize vertical specialists with captive compliance documentation libraries rather than horizontal feature breadth. Watch for inflection signals in German KBA enforcement patterns affecting automotive supply chain platform mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | REST API standardization enables Microsoft Azure to bundle collaborative ERP with existing productivity suites. |
| Vertical Specialist Acquisition | Pure-play vendors with FDA validation protocols capture defensible margin pools in pharmaceutical manufacturing. |
| Geographic Expansion | Localized GDPR compliance offerings open German Mittelstand accounts resistant to US-centric deployments. |
| Strategic Partnership | Industrial IoT provider alliances accelerate edge-to-cloud workflow convergence for predictive maintenance. |
| Product Launch | Microservices-based modules isolate shop-floor data streams from corporate financial systems in Baden-Württemberg. |
Research Methodology
A standing panel of CTOs, IT procurement officers, platform engineers, and integration specialists provided ongoing calibration across primary interview cycles, with secondary validation drawing from SEC filings, hyperscaler capex disclosures, EU regulatory filings, and industrial software procurement databases. Bottom-up deployment estimates triangulated against top-down market sizing from cloud infrastructure spend analysis.
Consistency checks validated outputs against external benchmarks across the analysis window, with segmentation modeling deployment mode, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from fitted growth curves applied to cloud-native and on-premises installation bases separately, incorporating EU AI Act compliance timeline assumptions and FDA validation protocol adoption rates as industry-specific inputs.
Forecasts assume regulatory continuity in GDPR enforcement and EU AI Act implementation timelines; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as German KBA automotive supply chain mandates and Indian BIS data localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Personalisation Software Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
Team Collaboration Tools Market
Software & Services
Server Virtualization Software Market
Software & Services
Simulation Software Market
Software & Services
Load Balancing Software Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Sales Training Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Animation Design Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Global Text to Speech (TTS) Software Market