
 Courier Software Market | 2026-2036
Courier Software Market Size, Share, and Industry Trends Forecast 2026-2036
Courier Software Market Analysis
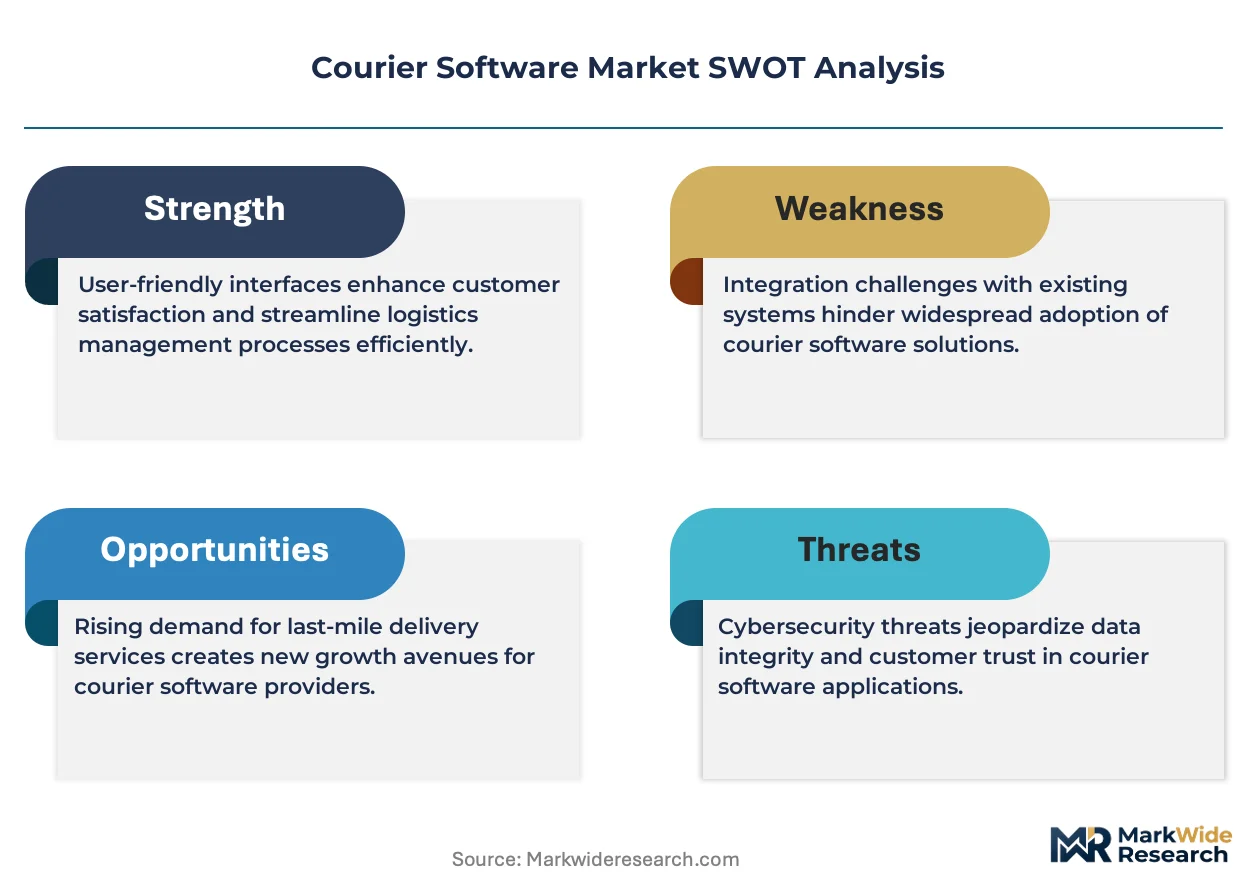
Fragmentation among mid-market e-commerce sellers is repositioning procurement patterns across the courier software value chain. Onfleet leverages cloud-native architecture to anchor its presence among third-party logistics aggregators. Bringg competes through enterprise-grade delivery orchestration tools that sustain multi-carrier visibility. Routific specializes in route optimization algorithms that differentiate its offering for regional courier fleets operating under tight margin constraints.
Courier software encompasses digital platforms that automate dispatch, real-time tracking, proof-of-delivery capture, and fleet coordination through GPS telemetry, API integrations, and machine-learning-driven route calculation. These systems serve commercial logistics operators by reducing per-stop costs and improving delivery density in urban distribution networks. Cloud-Based deployment leads the market by accessibility and lower capital barriers, while Route Optimization functions capture disproportionate R&D investment due to their direct fuel-cost impact. SaaS models are expanding fastest among Small Enterprises seeking scalable subscription pricing without infrastructure overhead.
FDA guidelines on pharmaceutical cold-chain documentation, EU GDPR requirements for geolocation data retention, and the EU AI Act's algorithmic transparency mandates collectively shape product development priorities for courier platforms handling sensitive shipments. Compliance with these frameworks determines market access for vendors serving healthcare logistics and cross-border e-commerce channels. Stakeholders must evaluate how evolving algorithmic accountability standards will affect automated dispatch systems before committing to platform architectures.
Market Dynamics
Cloud-native dispatch architecture is compressing deployment timelines from months to weeks, forcing incumbent vendors to refactor legacy codebases or lose mid-market accounts to agile challengers.
Growth Catalysts
- EU AI Act Algorithmic Transparency:Mandates for explainable routing decisions are accelerating R&D investment in interpretable machine learning models for automated dispatch systems.
- Pharmaceutical Cold-Chain Logistics:FDA documentation requirements for temperature-controlled shipments are driving courier networks to adopt integrated sensor-software platforms with audit-ready data trails.
- German Last-Mile Automation:Mid-sized courier networks in Bavaria and North Rhine-Westphalia are deploying autonomous sorting and electric fleet management tools at scale.
Market Restraints
- GDPR Geolocation Retention Limits:Cross-border parcel tracking faces structural friction from divergent EU member state interpretations of data localization requirements.
- Cloud Infrastructure Concentration:Dependency on hyperscale providers in Ireland and Frankfurt creates single-point-of-failure risk for SaaS delivery platforms.
- API Interoperability Gaps:Proprietary data formats from legacy warehouse management systems impose technical limitations on real-time fleet synchronization.
Strategic Opportunities
- India E-Commerce Logistics:Underpenetrated tier-2 and tier-3 cities present white space for route optimization vendors adapting to fragmented addressing systems.
- Carbon Accounting Integration:EU Green Deal reporting requirements create regulatory tailwind for platforms embedding emissions calculation into delivery workflows.
- Computer Vision + Edge Computing Convergence:Proof-of-capture systems combining on-device image processing with cloud analytics enable new service tiers for high-value freight.
Industry Challenges
- Embedded Systems Engineering Talent:Shortage of developers with GPS telemetry and real-time data pipeline expertise constrains product roadmap velocity.
- ISO 27001 Certification Timelines:Enterprise procurement gates require information security management system accreditation that stretches 12-18 months for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Courier Software Market |
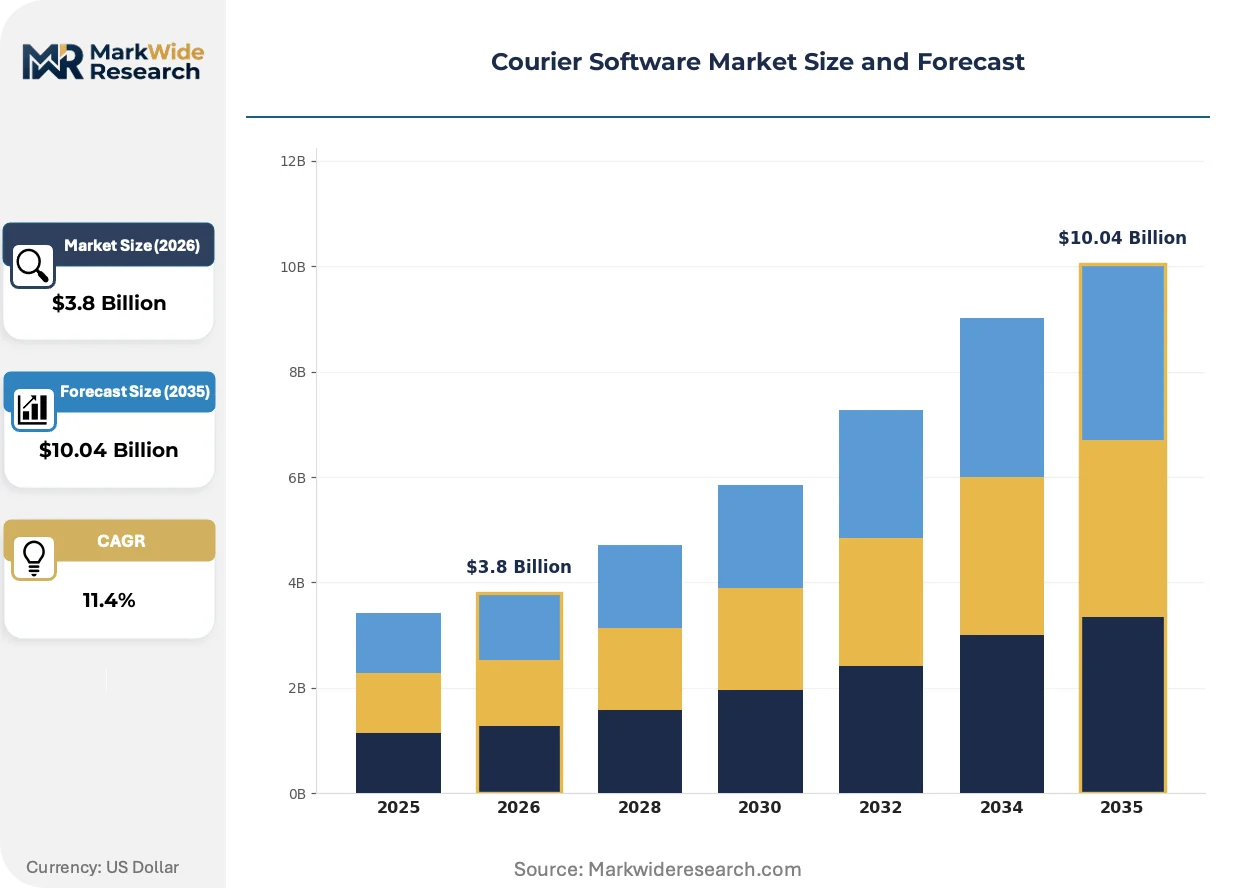
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small Enterprises, Large Enterprises, Startups, Freelancers Service Type: Tracking, Route Optimization, Delivery Management, Customer Support Integration Level: API, Third-Party Services, Payment Gateways, Others |
| Companies Covered | Shipday, AfterShip, Quick Delivery, Routific, Bringg, Onfleet, Deliforce, CXT Software, EasyParcel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Courier Software Market Emerging Trajectories
Machine-learning inference at the network edge is rewriting cost structures for real-time decision-making, while regulatory pressure on algorithmic accountability forces architectural redesigns.
Dynamic route recalculation engines powered by reinforcement learning are overtaking static optimization heuristics in urban density applications. Regional courier fleets operating sub-100 vehicle networks adopt these tools fastest, compressing fuel costs and stop times simultaneously. The shift is overtaking incumbent vendors whose batch-processing architectures cannot sustain sub-second re-routing.
EU AI Act risk classification rules for automated decision systems now govern dispatch software handling cross-border e-commerce flows. Platforms must document training data provenance and maintain human oversight interfaces for high-risk deployments. Healthcare logistics operators in Germany and the Netherlands face the steepest compliance ramps, restructuring procurement criteria around algorithmic auditability.
Subscription-based pricing for delivery management platforms is displacing perpetual license models among small logistics operators. Third-party logistics aggregators in France and Spain now bundle software access with carrier capacity, unbundling traditional vendor-direct relationships. The restructuring concentrates buying power with platform intermediaries and compresses standalone software margins.
Courier Software Market Segmentation
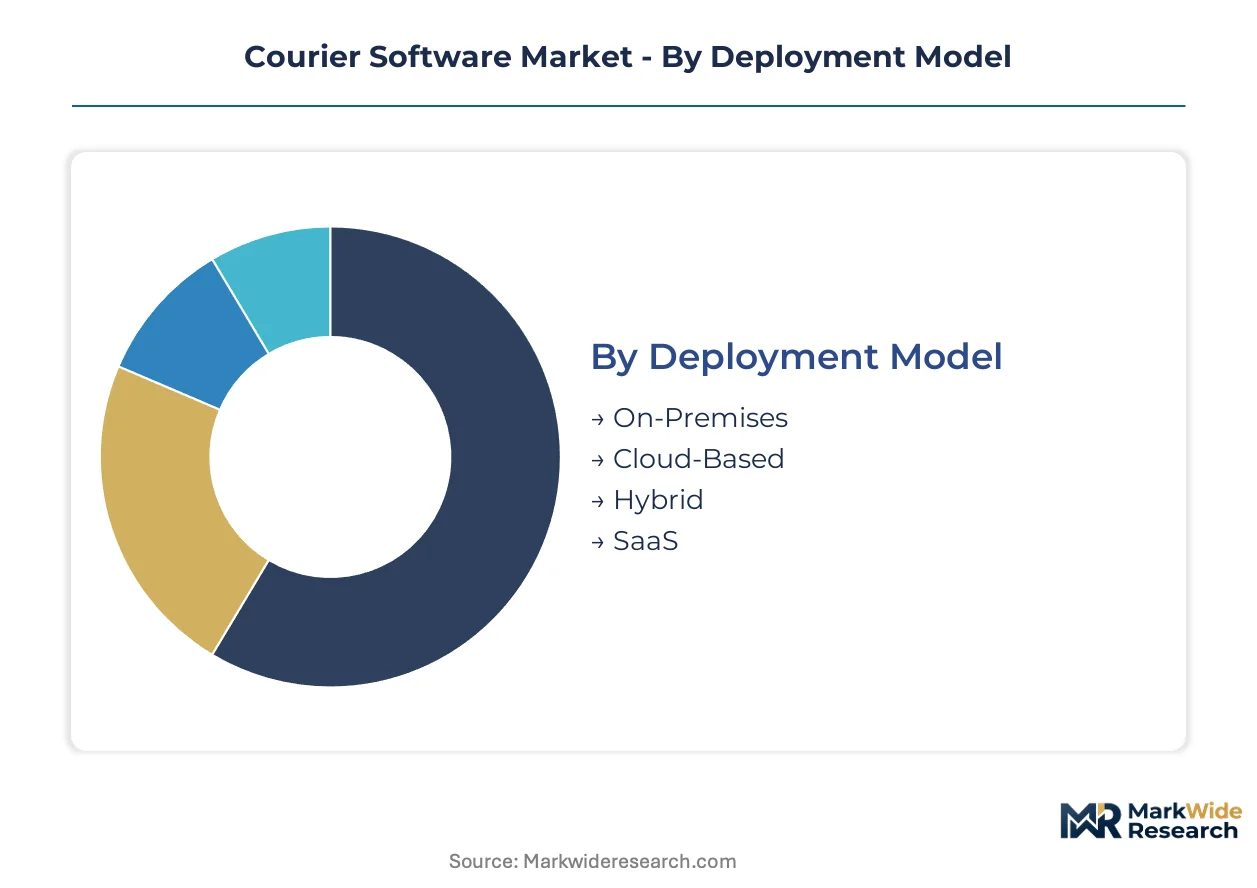
Courier software procurement patterns diverge sharply across deployment architectures and operational scale. Upgrade cycles for legacy dispatch systems now compress from multi-year horizons to quarterly release schedules, forcing vendors to architect for modularity.
Deployment Model:
Replacement timelines vary dramatically by infrastructure commitment, with cloud-native platforms enabling fastest migration paths.
- Cloud-Based:Multi-tenant architectures with auto-scaling compute resources eliminate server maintenance overhead. German mid-sized courier networks in Bavaria and North Rhine-Westphalia prioritize this model for rapid fleet expansion without capital expenditure.
- SaaS:Subscription pricing with usage-based tiers aligns costs directly with delivery volume fluctuations. Small enterprises across France and Spain adopt this fastest where third-party logistics aggregators bundle software access with carrier capacity.
- On-Premises:Single-tenant installations on client-owned hardware persist among healthcare logistics operators requiring air-gapped cold-chain documentation systems.
- Hybrid:Split architectures keeping sensitive dispatch data local while routing analytics flow to cloud endpoints.
Volume placements concentrate in Cloud-Based deployments; the faster expansion belongs to SaaS.
End User:
Customer sophistication dictates feature depth requirements and integration complexity tolerance.
- Large Enterprises:Multi-carrier visibility dashboards with ERP synchronization and custom SLA tracking. EU AI Act compliance documentation for algorithmic dispatch decisions drives procurement criteria among cross-border e-commerce operators in Germany and the Netherlands.
- Small Enterprises:Streamlined mobile-first interfaces with minimal configuration overhead. Regional courier fleets operating sub-100 vehicle networks across Spain adopt route recalculation engines fastest for fuel cost compression.
- Startups:API-first platforms enabling rapid marketplace integration without dedicated IT infrastructure.
- Freelancers:Individual driver applications with proof-of-capture and instant payment settlement.
Revenue concentration sits with Large Enterprises; steepest expansion trajectory emerges among Small Enterprises.
Service Type:
Functional modules compete for R&D investment based on measurable operational impact.
- Route Optimization:Reinforcement learning engines enabling sub-second dynamic recalculation against traffic and delivery priority shifts. Urban density applications in tier-2 Indian cities with fragmented addressing systems present white-space demand.
- Delivery Management:Unified dispatch, fleet coordination, and customer notification workflows. Pharmaceutical cold-chain operators require integrated sensor-software platforms with FDA-compliant audit trails.
- Tracking:Real-time GPS telemetry with predictive arrival windows.
- Customer Support:Automated exception handling and self-service delivery rescheduling.
Deployment breadth favors Delivery Management; algorithmic differentiation concentrates in Route Optimization.
Integration Level:
Interoperability architecture determines platform stickiness within logistics technology stacks.
- API:REST and GraphQL endpoints enabling bidirectional data flow with warehouse management systems. Proprietary data formats from legacy WMS vendors impose technical limitations on real-time fleet synchronization.
- Payment Gateways:Embedded settlement processing for cash-on-delivery reconciliation and driver instant payouts.
- Third-Party Services:Pre-built connectors to carrier networks, mapping providers, and communication platforms.
- Others:Custom EDI mappings and legacy protocol adapters for enterprise ERP environments.
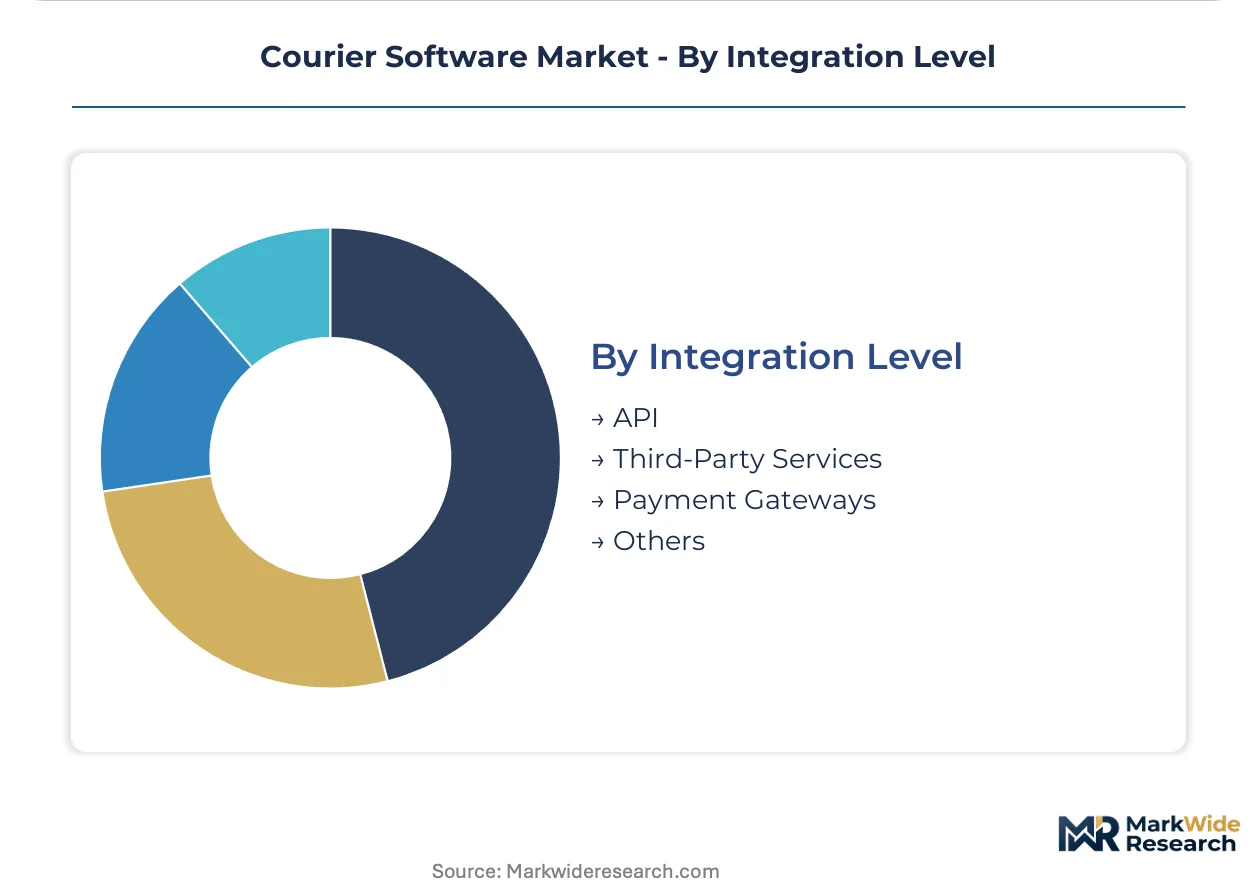
Integration density clusters around API architectures; payment gateway embedding climbs fastest as monetization models evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German last-mile automation investments anchor courier software demand across the analysis window. Bavarian and North Rhine-Westphalian networks deploy cloud-native dispatch platforms at accelerating velocity. Regulatory pressure from Brussels reshapes procurement criteria throughout the continent.
United States
FDA cold-chain documentation mandates drive pharmaceutical logistics operators toward integrated sensor-software platforms. HIPAA requirements govern geolocation data handling for healthcare deliveries. The Greater Boston corridor concentrates temperature-controlled courier networks upgrading audit-ready tracking systems.
Germany
EU AI Act algorithmic transparency rules restructure automated dispatch procurement for cross-border e-commerce operators. KBA vehicle telemetry standards intersect with GDPR geolocation retention limits for fleet management platforms. Mid-sized courier networks in Bavaria and North Rhine-Westphalia deploy autonomous sorting infrastructure at scale.
United Kingdom
Post-Brexit customs documentation complexity elevates demand for multi-carrier visibility dashboards among third-party logistics aggregators. Information Commissioner's Office guidance on automated decision-making affects route optimization deployment. The Midlands logistics corridor concentrates SaaS adoption among regional courier fleets seeking subscription pricing flexibility.
India
Tier-2 and tier-3 e-commerce penetration creates white-space demand for route optimization vendors adapting to fragmented addressing systems. DGFT cross-border trade documentation requirements shape platform integration priorities. The Bangalore-Chennai logistics belt anchors cloud-native delivery management adoption among emerging logistics aggregators.
France
ANSM pharmaceutical distribution traceability standards elevate cold-chain software requirements for healthcare logistics operators. CNIL algorithmic accountability guidance affects automated dispatch system design. The Lyon logistics cluster concentrates electric fleet management platform deployment among urban courier networks.
Courier Software Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue API-first modular architectures and vertical-specific compliance bundles. The vendor base stratifies across cloud-native challengers, legacy system incumbents, and logistics-aggregator-owned platforms. Three archetypes dominate: route optimization specialists, enterprise delivery orchestration providers, and carrier-agnostic SaaS vendors. Competitive moves concentrate on strategic partnerships with third-party logistics aggregators and rapid ISO 27001 certification acceleration.
Within the route optimization tier, Routific and Onfleet exemplify cloud-native positioning among regional courier networks. Bringg anchors enterprise-grade delivery orchestration for multi-carrier visibility requirements. These three entities represent divergent architectural bets: reinforcement learning engines versus dispatch automation versus carrier integration density.
| Leading Market Players |
|---|
| Shipday |
| AfterShip |
| Quick Delivery |
| Routific |
| Bringg |
| Onfleet |
| Deliforce |
| CXT Software |
| EasyParcel |
| Others |
Supply Flow & Price Mechanics
Cloud-native dispatch architecture migration simultaneously compresses deployment cost structures and concentrates procurement leverage among hyperscale infrastructure providers in Ireland and Frankfurt. SaaS subscription models displace perpetual licenses as third-party logistics aggregators bundle software access with carrier capacity, restructuring vendor-direct relationships and compressing standalone margins.
Pricing Analysis
Volume concentration in SaaS tiers runs against margin preservation in enterprise-grade delivery orchestration. Three-tier pricing structure across premium, standard, and economy levels separates API integration depth, algorithmic transparency certification, and customer support tiers. Pricing pressure stems from third-party logistics aggregators consolidating buying power through bundled procurement. Small enterprises exhibit highest price sensitivity due to per-delivery volume volatility, while pharmaceutical cold-chain operators prioritize audit-ready compliance over cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and India anchor cloud infrastructure deployment for courier software platforms serving cross-border e-commerce flows. Software development draws from GPS telemetry hardware manufactured in Taiwan, edge computing components from South Korea, and machine learning talent concentrated in Bangalore and Berlin. Single-source vulnerability persists in hyperscale cloud dependency for SaaS delivery platforms. Distribution runs through third-party logistics aggregators bundling software access with carrier capacity across France and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reinforcement learning engines are displacing static route optimization heuristics, compressing fuel costs and stop times for regional courier fleets while forcing architectural redesigns among batch-processing incumbents.
For Market Incumbents: Deploy ISO 27001 certification acceleration to defend enterprise procurement gates against agile challengers. Refactor legacy codebases toward modular API-first architectures to retain mid-market accounts threatened by cloud-native deployment timelines measured in weeks rather than months. Channel control through direct third-party logistics aggregator partnerships offsets margin compression from bundled procurement.
For New Entrants and Emerging Players: API-first modular architectures open white-space penetration in tier-2 and tier-3 Indian cities where fragmented addressing systems demand adaptive route optimization. Target regional courier fleets operating sub-100 vehicle networks across Spain and Bavaria with mobile-first interfaces requiring minimal configuration overhead. Go-to-market through third-party logistics aggregator partnerships concentrates distribution leverage without dedicated enterprise sales infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by logistics-aggregator-owned platforms seeking vertical software integration. Long-term viability hinges on algorithmic auditability compliance with EU AI Act risk classification rules for automated dispatch systems. Watch procurement criteria restructuring among German and Dutch healthcare logistics operators as the inflection signal for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Compresses deployment timelines from months to weeks for mid-market courier networks. |
| EU AI Act Compliance Certification | Enables market access for automated dispatch systems serving cross-border e-commerce. |
| Strategic Partnership with 3PL Aggregators | Restructures vendor-direct relationships through bundled software-carrier procurement. |
| Acquisition of Route Optimization Specialist | Secures reinforcement learning expertise for sub-second dynamic recalculation capabilities. |
| ISO 27001 Certification Acceleration | Unlocks enterprise procurement gates requiring 12-18 month accreditation timelines. |
Methodological Framework
Document review covered SEC filings from logistics technology vendors, EU regulatory publications on algorithmic accountability, and hyperscaler infrastructure capex disclosures, complemented by interviews with CTOs at regional courier networks, IT procurement officers at third-party logistics aggregators, platform engineers specializing in GPS telemetry integration, and channel partners distributing delivery management solutions. Secondary validation drew from customs records of GPS hardware imports, Gartner enterprise software spending surveys, and KBA vehicle telemetry standard documentation. Bottom-up sizing of deployment model segments triangulated against top-down addressable market estimates from e-commerce logistics expansion projections.
Segmentation outputs across deployment architecture, organization size, vertical compliance requirements, and regional adoption patterns anchored the analytical framework over the projection horizon. CAGRs derived from logistic curve modeling of SaaS penetration rates against legacy on-premises replacement cycles. Industry-specific inputs included EU AI Act implementation timelines affecting procurement criteria and pharmaceutical cold-chain documentation mandates reshaping sensor-software platform requirements.
The model holds under steady regulatory implementation schedules and cloud infrastructure availability; deviation in GDPR geolocation retention interpretation or hyperscale provider service disruptions would shift deployment model trajectories. Forecasts reflect documented assumptions on third-party logistics aggregator consolidation velocity and algorithmic transparency compliance cost curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global 360 Degree Feedback Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Information Technology Service Management (ITSM) Market
Software & Services
Global Database Software Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
PAC Programming Software Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Collaborative Authoring Tools Market
Software & Services
Global Pharmaceutical Manufacturing Software Market
Software & Services
API Testing Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Commerce As a Service (Caas) Market
Software & Services
IT Service Management Tools Market
Software & Services
Photo Editor App Market