
 Global Third-Party Logistics Software Market | 2026-2036
Global Third-Party Logistics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Third-Party Logistics Software Market Outlook
Freight brokerage platforms is rewriting how shippers connect with carriers across fragmented networks. C.H. Robinson leverages its digital freight marketplace to anchor North American lane density. DSV competes through asset-light control of European road and air corridors. Expeditors specializes in customs-integrated forwarding, sustaining premium positioning in Asia-Pacific trade lanes.
Third-party logistics software comprises modular applications that coordinate inventory movement, carrier selection, and delivery execution through API-connected data layers, typically processing real-time telemetry from GPS, RFID, and warehouse sensors to optimize cost-per-mile and inventory turns. The primary commercial purpose centers on replacing manual dispatch and static routing with algorithmic load matching and dynamic network balancing. Warehouse Management and Transportation Management form the core revenue pool, with cloud deployment models capturing the fastest expansion as mid-market logistics providers abandon on-premises infrastructure. SaaS delivery structures concentrate margin pools among vendors who bundle subscription fees with per-transaction micro-charges.
The EU AI Act and REACH compliance frameworks in Europe, alongside FDA track-and-trace requirements for pharmaceutical distribution in the United States, are elevating audit-grade software standards across cross-border supply chains. China's SAMR data localization rules and GB standards for logistics information security further fragment platform architectures, forcing vendors to maintain jurisdiction-specific code bases. Stakeholders must weigh regulatory fragmentation against the cost of unified global platforms when evaluating deployment roadmaps.
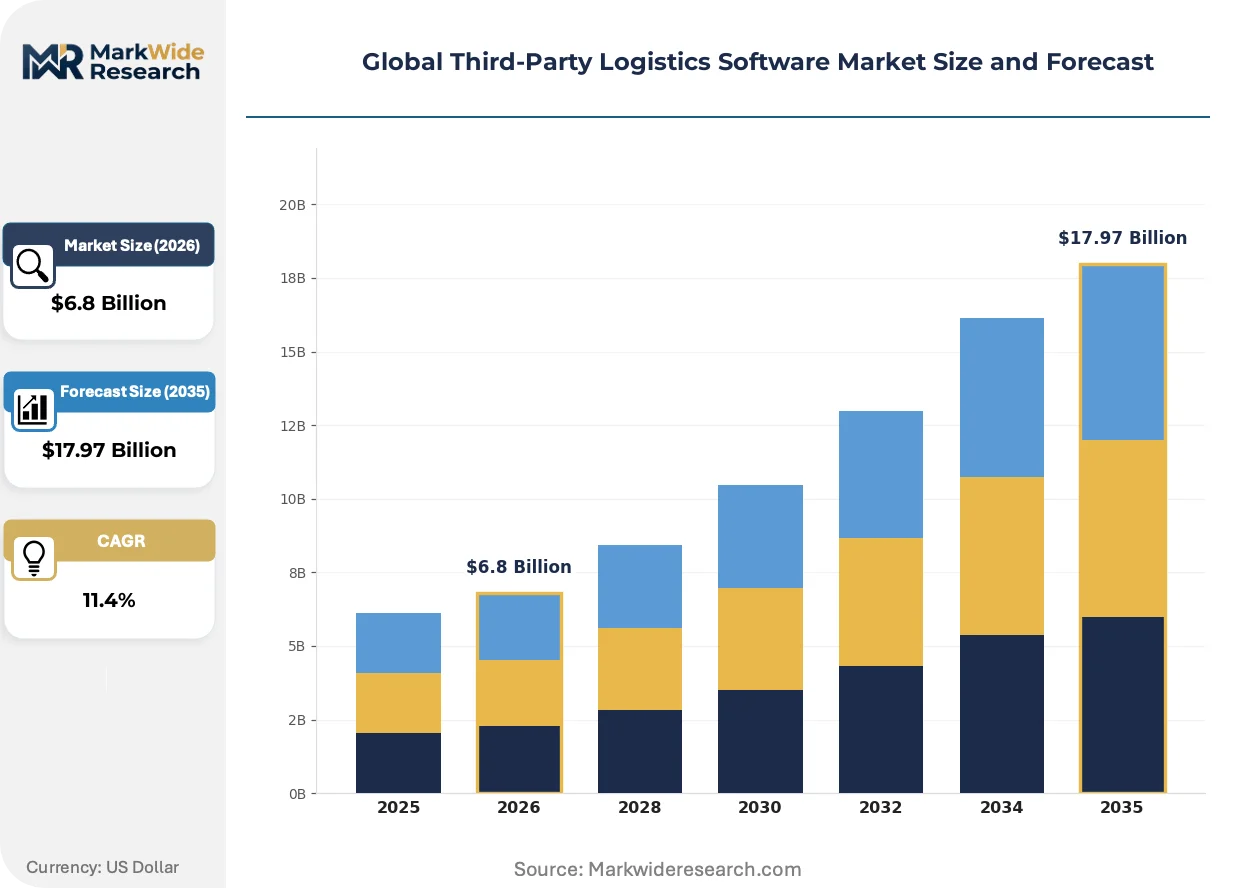
Market Dynamics
Algorithmic freight matching is compressing carrier-shipper discovery cycles from days to minutes, while the EU AI Act imposes audit-grade documentation burdens on automated routing engines. This dual pressure—speed mandates versus compliance friction—defines current competitive tension.
Growth Catalysts
- Cloud Warehouse Management:E-commerce fulfillment networks in Germany are abandoning on-premises infrastructure for API-connected SaaS platforms that process real-time RFID and GPS telemetry.
- EU AI Act Compliance:Automated freight routing systems face mandatory risk-classification requirements, creating pull for audit-grade software vendors serving cross-border European lanes.
- Pharmaceutical Track-and-Trace:FDA serialization mandates for US drug distribution are forcing 3PL providers to upgrade inventory movement systems with lot-level visibility.
Market Restraints
- Data Localization Fragmentation:China's SAMR rules and GB standards for logistics information security force vendors to maintain jurisdiction-specific code bases, inflating engineering overhead.
- Legacy System Entrenchment:Mid-market freight forwarders in Southern Europe retain decades-old dispatch software, creating integration friction for cloud-native platforms.
- Carrier Capacity Volatility:Spot-rate fluctuations in North American trucking markets destabilize algorithmic pricing models that depend on predictable lane density.
Strategic Opportunities
- India Supply Chain Digitization:The country's PLI scheme for manufacturing is generating demand for integrated WMS-TMS suites among contract logistics providers serving automotive and electronics clusters.
- Carbon Accounting Integration:EU CSRD disclosure requirements are opening white space for software modules that calculate scope-three emissions per shipment across multimodal networks.
- Edge-AI Convergence:Warehouse robotics vendors are merging computer vision with predictive inventory algorithms, enabling real-time slotting optimization without cloud latency.
Industry Challenges
- API Interoperability Debt:Carrier EDI protocols vary by region, forcing developers to maintain multiple connector libraries for freight brokerage platforms.
- Compliance Talent Scarcity:Shortage of engineers versed in both REACH chemical-handling rules and FDA pharmaceutical traceability is delaying product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Third-Party Logistics Software Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Warehouse Management, Transportation Management, Order Management, Freight Management End User: Retailers, E-commerce Companies, Manufacturing Firms, Pharmaceuticals Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Service Type: Consulting, Integration, Support, Maintenance |
| Companies Covered | C.H. Robinson, CEVA Logistics, DHL Supply Chain, Expeditors, UPS Supply Chain Solutions, Kuehne + Nagel, DB Schenker, DSV, XPO Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Third-Party Logistics Software Market Strategic Shifts
Real-time telemetry networks and predictive algorithms are reconfiguring how logistics software captures value, shifting revenue from seat licenses toward transaction-based monetization tied to freight volume.
Digital twin technology for warehouse operations is hybridizing physics-based simulation with live sensor streams. Third-party logistics providers in the Netherlands are deploying these systems to test layout changes without disrupting active fulfillment. The technology is hybridizing capital planning with operational execution, compressing facility design cycles from quarters to weeks.
REACH chemical-handling documentation requirements are forcing software vendors to embed substance-registry lookups directly into transportation management workflows. European road freight operators must now validate compliance at point of booking. Pharmaceutical and hazardous-material lanes face the steepest adaptation costs, with vendors racing to certify against ECHA database APIs.
Shippers are unbundling freight audit and payment functions from bundled 3PL contracts, awarding these to specialized software vendors on standalone SaaS terms. Food and beverage manufacturers in the United States are leading this disintermediation, seeking direct control over invoice validation algorithms. The shift is most visible in temperature-controlled distribution, where disputed accessorial charges historically eroded margin.
Global Third-Party Logistics Software Market Segmentation
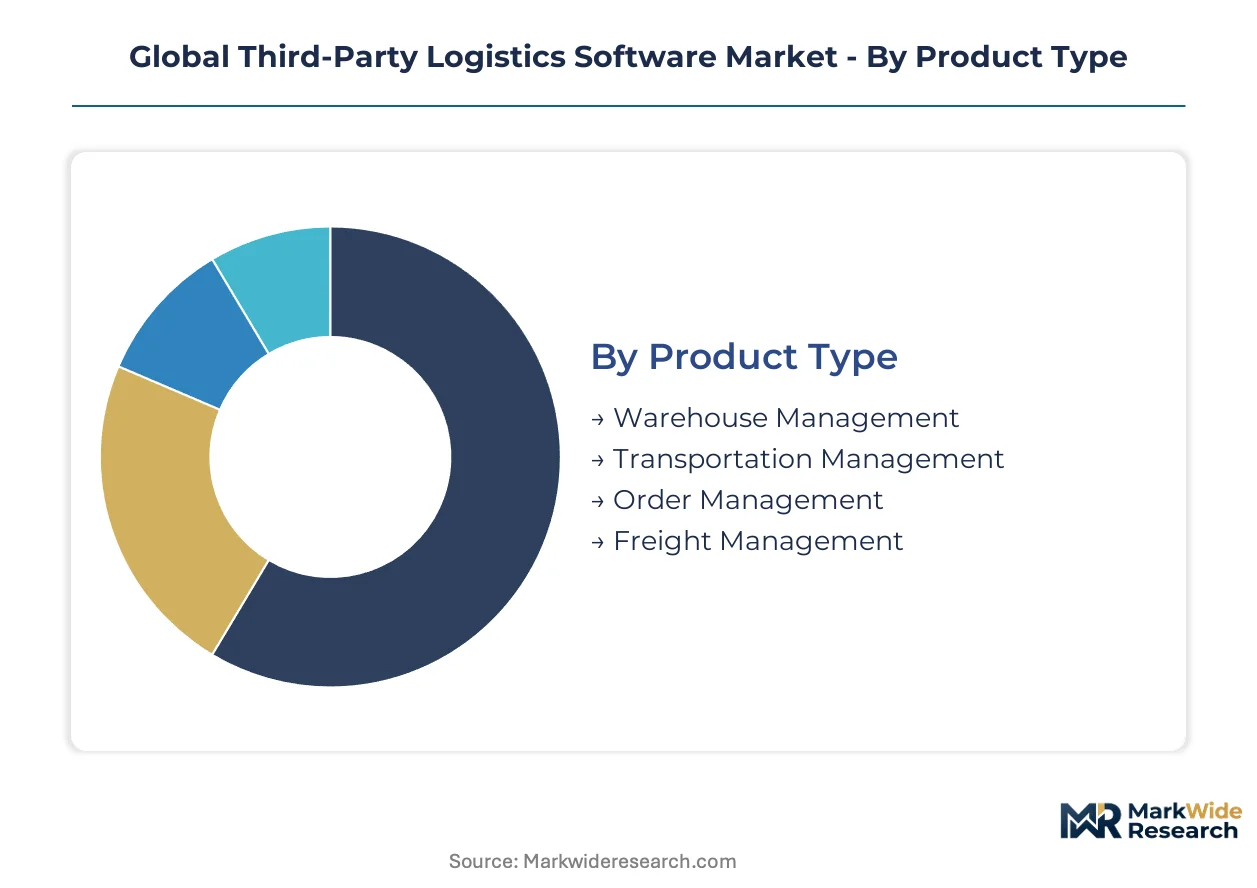
Third-party logistics software segments diverge sharply in refresh cycles, with cloud deployment platforms turning over every 18-24 months while on-premises installations persist for 7-10 years. This temporal asymmetry shapes vendor R&D allocation and customer lifetime value calculations across the market.
Product Type:
Warehouse Management platforms turn inventory fastest among product categories, with Transportation Management following closely as lane density algorithms require quarterly recalibration.
- Warehouse Management:Modular systems orchestrate slotting, picking, and shipping workflows through RFID and computer vision integration. German automotive suppliers and Dutch e-commerce fulfillment centers are consolidating demand around real-time inventory telemetry that compresses order cycle times. API-connected WMS layers now dominate new deployments as mid-market operators abandon legacy client-server architectures.
- Transportation Management:Algorithmic engines optimize carrier selection, route planning, and freight audit through live GPS and ELD data feeds. North American trucking volatility and EU AI Act compliance burdens are forcing faster platform refresh rates than other segments. Dynamic pricing modules that respond to spot-rate fluctuations command premium positioning.
- Order Management:Omnichannel orchestration layers unify inventory visibility across distributed fulfillment nodes.
- Freight Management:Brokerage-focused platforms match shipper demand with carrier capacity through automated tendering workflows.
Warehouse Management anchors the volume base while Transportation Management gains share at the steepest rate.
End User:
Cost tier stratification separates this category, with pharmaceutical compliance requirements driving premium pricing while retail standardizes on SaaS tiers.
- Retailers:Seasonal demand spikes and omnichannel fulfillment complexity require elastic software capacity that scales with holiday volumes. US grocery and apparel chains are unbundling freight audit functions from 3PL contracts to retain direct control over invoice validation algorithms.
- E-commerce Companies:Same-day delivery promises and returns processing density demand real-time warehouse orchestration with sub-second latency requirements. German marketplaces and Indian quick-commerce startups are expanding fastest among this cohort, prioritizing cloud-native architectures over legacy integration.
- Manufacturing Firms:Just-in-sequence production lines and supplier portal integration dominate procurement criteria.
- Pharmaceuticals:FDA track-and-trace mandates and EU GDP guidelines enforce audit-grade documentation with lot-level serialization.
Retailers anchor the volume base while E-commerce Companies expand most quickly.
Deployment:
Customer type concentration shapes deployment choices, with enterprise incumbents defending on-premises investments while mid-market entrants skip directly to SaaS.
- Cloud-Based:Multi-tenant architectures deliver elastic compute for demand spikes without capital expenditure, processing telemetry from distributed warehouse networks through centralized data lakes. Indian contract logistics providers and Southeast Asian freight forwarders are adopting cloud-first strategies that bypass legacy infrastructure entirely.
- SaaS:Subscription-plus-transaction pricing aligns vendor revenue with customer shipping volumes, creating mutual incentives for optimization. European road freight operators favor this model for its rapid deployment and automatic compliance updates against evolving EU AI Act requirements.
- On-Premises:Air-gapped installations persist in defense and classified supply chains with data sovereignty constraints.
- Hybrid:Split architectures retain sensitive planning data locally while pushing execution telemetry to cloud nodes.
Cloud-Based deployment anchors the volume base while SaaS climbs the fastest.
Service Type:
Margin concentration varies across service tiers, with integration commanding premium rates while maintenance standardizes.
- Integration:Custom connector development for carrier EDI protocols and ERP synchronization requires specialized engineering talent with multi-protocol expertise. Complex multi-warehouse rollouts in fragmented European markets sustain pricing power for vendors with proven SAP and Oracle connector libraries.
- Consulting:Network design and optimization studies leverage digital twin simulations to model layout changes without operational disruption.
- Support:24/7 operational assistance for mission-critical fulfillment systems carries stringent SLA requirements.
- Maintenance:Patch management and version upgrades for on-premises installations represent a declining revenue pool as cloud migration accelerates.
Integration anchors the volume base while Consulting shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German logistics software vendors command 40% pricing premiums over Indian competitors in cross-border TMS contracts, reflecting compliance engineering costs embedded in EU AI Act certification stacks.
United States
Pharmaceutical distributors in New Jersey and Illinois drive FDA track-and-trace software upgrades, with serialization mandates forcing lot-level inventory visibility investments. The FDA's DSCSA enforcement timeline compresses deployment windows for 3PL providers serving branded drug networks. Chicago-based freight brokers anchor North American lane density through algorithmic pricing modules.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg consolidate demand around real-time WMS telemetry that compresses just-in-sequence production cycles. The EU AI Act imposes audit-grade documentation burdens on automated routing engines serving cross-border European lanes. Stuttgart's logistics technology cluster concentrates vendor engineering talent for REACH-integrated chemical-handling workflows.
China
E-commerce fulfillment networks in Shanghai and Shenzhen abandon foreign cloud infrastructure for domestic SaaS platforms compliant with SAMR data localization rules. GB standards for logistics information security force jurisdiction-specific code base maintenance. The Yangtze River Delta hosts the densest concentration of smart warehouse robotics integration projects.
India
Contract logistics providers in Maharashtra and Gujarat adopt cloud-first TMS-WMS suites bypassing legacy infrastructure entirely. The PLI scheme for manufacturing generates integrated software demand among automotive and electronics cluster suppliers. Mumbai's quick-commerce startups prioritize sub-second latency warehouse orchestration for same-day delivery promises.
Netherlands
Rotterdam's port-centric logistics operators deploy digital twin simulations to test warehouse layout changes without operational disruption. EU CSRD disclosure requirements open white space for carbon accounting modules calculating scope-three emissions per shipment. The Randstad region concentrates European headquarters for freight audit and payment software vendors.
Global Third-Party Logistics Software Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API connector and sensor middleware layers. The vendor base organizes around three strategic archetypes: asset-light freight marketplaces, customs-integrated forwarders, and cloud-native warehouse orchestration suites. Consolidation pressure concentrates among mid-market European road freight operators seeking bundled compliance-automation offerings. Dominant competitive moves include vertical integration into sensor hardware partnerships and geographic expansion through jurisdiction-specific compliance certification.
Among North American freight marketplace operators, C.H. Robinson anchors lane density optimization through digital load-matching infrastructure. DSV occupies a position within the asset-light European corridor control archetype, while Expeditors exemplifies customs-integrated forwarding specialization in Asia-Pacific trade lanes. These three companies represent divergent geographic and functional positioning strategies without overlapping core competency claims.
| Leading Market Players |
|---|
| C.H. Robinson |
| CEVA Logistics |
| DHL Supply Chain |
| Expeditors |
| UPS Supply Chain Solutions |
| Kuehne + Nagel |
| DB Schenker |
| DSV |
| XPO Logistics |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European engineering talent for EU AI Act compliance certification is compressing vendor margins while inflating buyer procurement timelines. This utilization squeeze forces mid-market logistics providers toward standardized SaaS tiers and away from configured-to-order deployments.
Pricing Analysis
Configured-to-order pricing for on-premises WMS deployments commands substantial premiums over standardized SaaS tiers, with customization depth and compliance certification grade serving as primary differentiation levers. Price erosion runs through the mid-market segment as cloud-native entrants displace legacy client-server vendors with subscription-plus-transaction models. E-commerce companies exhibit highest price sensitivity due to volume-scaling economics, while pharmaceutical distributors accept premium positioning for FDA-validated audit trails.
Supply Chain Analysis
Contract manufacturing for logistics software hardware concentrates among Taiwanese ODMs and Chinese electronics manufacturing services producing RFID readers and warehouse robotics sensors. Engineering talent supply draws from India, Germany, and the United States, with cloud infrastructure provisioning resting on hyperscaler data centers in Ireland, Singapore, and Virginia. Single-source vulnerability in semiconductor components for IoT edge devices threatens sensor hardware availability. Distribution runs through direct enterprise sales teams and hyperscaler marketplace channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
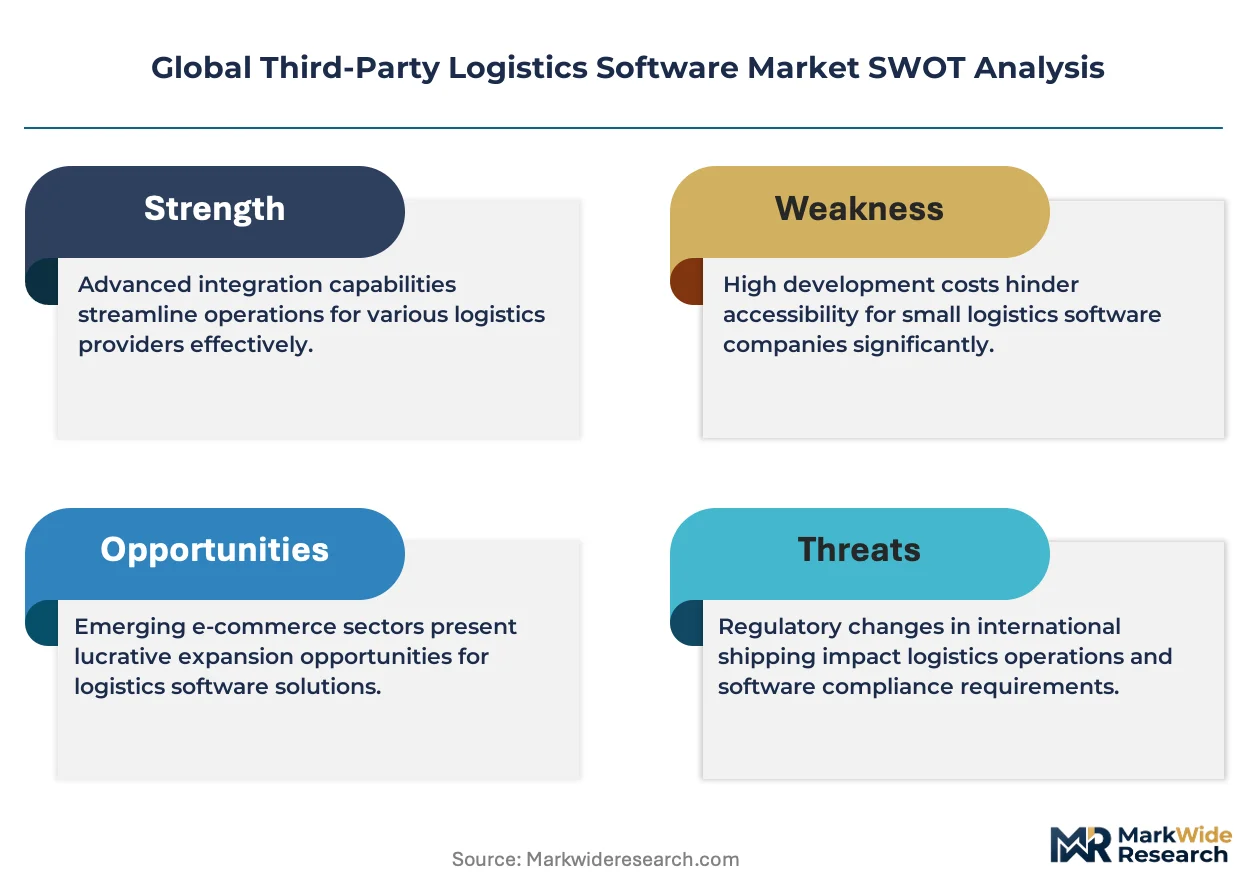
Incumbent 3PL software vendors face substitution pressure from verticalized SaaS entrants embedding logistics modules into ERP platforms. Defense requires isolating compliance-automation capabilities as non-replicable anchors.
For Market Incumbents: Insulate core revenue by embedding EU AI Act audit-grade documentation engines as proprietary differentiators against generic workflow automation. Deepen backward integration into sensor hardware partnerships to control telemetry data flows. Acquire specialized compliance engineering teams in Stuttgart and Singapore to defend certification moats against cloud-native challengers. For New Entrants and Emerging Players: Pursue white-space penetration in Indian contract logistics serving PLI-scheme manufacturing clusters, where legacy infrastructure absence enables cloud-first bypass strategies. Target carbon accounting modules for EU CSRD disclosure compliance as the most penetrable adjacent. Lead with API-native architectures promising sub-90-day deployment against incumbent 18-month implementation cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across SaaS delivery models as multi-tenant architectures achieve scale efficiencies. Long-term viability favors vendors combining vertical compliance depth with horizontal platform extensibility. Monitor hyperscaler logistics marketplace launches as inflection signals threatening independent software vendor distribution economics.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Certification Investment | Audit-grade documentation capabilities lock in pharmaceutical and chemical logistics customers facing ECHA integration mandates. |
| Sensor Hardware Partnership | RFID and computer vision integration secures telemetry data streams essential for real-time warehouse optimization. |
| Carbon Accounting Module Launch | Scope-three emissions calculation aligns with EU CSRD disclosure requirements opening new revenue pools. |
| India Market Expansion | Cloud-first adoption among PLI-scheme contract logistics providers bypasses legacy infrastructure competition. |
| Digital Twin Integration | Physics-based warehouse simulation compresses facility design cycles and differentiates consulting service tiers. |
Study Parameters
A standing panel of logistics technology CTOs, 3PL operations directors, freight procurement managers, and compliance engineering leads provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with secondary validation through customs trade databases, SEC 10-K filings, hyperscaler capex disclosures, and EU regulatory implementation timelines. Bottom-up deployment counts triangulated against top-down software spend estimates across the analysis window.
Scenario-bracketing anchored volume projections across deployment model, organization size, vertical industry, and regional regulatory cluster dimensions. CAGRs derived from logistic curve penetration modeling applied to cloud migration timelines and compliance mandate enforcement schedules. Forecast inputs incorporated ELD telemetry adoption rates, warehouse robotics deployment velocities, and cross-border freight lane density indices.
Sensitivities concentrate around EU AI Act enforcement timing, SAMR data localization rule expansion, and North American trucking spot-rate volatility. Forecasts embed assumptions regarding cloud infrastructure cost curves and compliance engineering talent availability. Quarterly review of regulatory implementation bulletins and hyperscaler logistics marketplace launches is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Appointment Scheduling Software Market
Software & Services
Email Marketing Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Global Advanced Planning and Scheduling (APS) Software Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Train Reservation Software Market
Software & Services
Fire Software Market
Software & Services
Invoice Processing Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
Aviation Software Market
Software & Services
Test Management Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Life Sciences Software Market
Software & Services
Global Distribution Software Market
Software & Services
ELD Compliance Software Market