
 Rail Bellows Market | 2026-2036
Rail Bellows Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Bellows Market Analysis
Silicone elastomer is repositioning rail bellows economics as operators trade up from neoprene for extended service intervals and broader temperature tolerance. Hutchinson SA leverages its polymer science heritage to anchor premium silicone supply contracts with European OEMs. CRRC Corporation Limited dominates procurement within China's state rail ecosystem through backward integration into captive rubber compounding. Dellner Couplers AB specializes in modular bellows architectures that simplify field replacement across Scandinavian and Baltic networks.
Rail bellows are flexible, accordion-shaped sealing elements typically molded from reinforced elastomer compounds with wall thicknesses of 2-5 mm and convolution counts ranging from three to seven; they protect critical train interfaces from moisture ingress, debris accumulation, and acoustic transmission while accommodating suspension travel and body-to-bogie articulation. Single bellows configurations remain the volume baseline for metro and commuter fleets where cost sensitivity prevails, though multi-bellows assemblies capture disproportionate margin in high-speed applications demanding redundant sealing and tuned stiffness profiles. Dust protection and noise reduction applications are outpacing pure suspension bellows as urban rail operators face tighter community noise ordinances and tunnel ventilation standards.
China's GB standards and SAMR certification requirements shape domestic product specifications, while REACH and RoHS in Europe constrain phthalate plasticizer selection across PVC and rubber formulations. The EU Green Deal's embodied carbon tracking is beginning to ripple through rail supply chains, pressuring bellows makers to document polymer sourcing and vulcanization energy intensity. Stakeholders must monitor how regional decarbonization timelines recalibrate material acceptance criteria and retrofit obligations for existing rolling stock.
Market Dynamics
The rail bellows market pivots on material substitution economics as silicone elastomer compounds displace neoprene across temperature-critical applications, reshaping supplier qualification protocols and fleet lifecycle cost models simultaneously.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon propellants accelerates silicone formulation adoption for European high-speed rail fleets requiring compliant sealing solutions.
- Urban noise ordinances:Tunnel ventilation standards and community acoustic limits in dense metropolitan corridors drive specification upgrades toward multi-convolution bellows with integrated damping layers.
- East Asian fleet expansion:Suspension and vibration isolation assemblies for new high-speed train orders concentrate procurement volume with specialized elastomer compounders.
Market Restraints
- Petrochemical feedstock volatility:Silicone polymer precursor costs fluctuate with methanol and silicon metal spot markets, compressing compounder margins during contract renegotiations.
- Domestic sourcing mandates:China's GB standards and SAMR certification requirements create effective procurement barriers for non-local bellows producers seeking CRRC supply chain entry.
- Thermoplastic vulcanizate substitution:TPV materials with comparable fatigue resistance threaten commodity neoprene bellows in cost-sensitive metro applications.
Strategic Opportunities
- EU Green Deal embodied carbon tracking:Vulcanization energy documentation and polymer provenance certification open premium positioning for low-carbon silicone suppliers.
- Retrofit aftermarket:Noise reduction retrofits on legacy rolling stock in German and French urban networks create replacement demand for advanced acoustic bellows.
- Digital twin integration:Predictive maintenance platforms converging with IoT sensor arrays enable condition-based bellows replacement contracts.
Industry Challenges
- REACH compliance complexity:Phthalate plasticizer restrictions and SVHC candidate list updates force continuous reformulation of PVC and rubber compounds.
- Multi-material bonding expertise:Fabric-reinforced silicone-to-metal adhesion requires specialized vulcanization technicians in short supply across European manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Bellows Market |
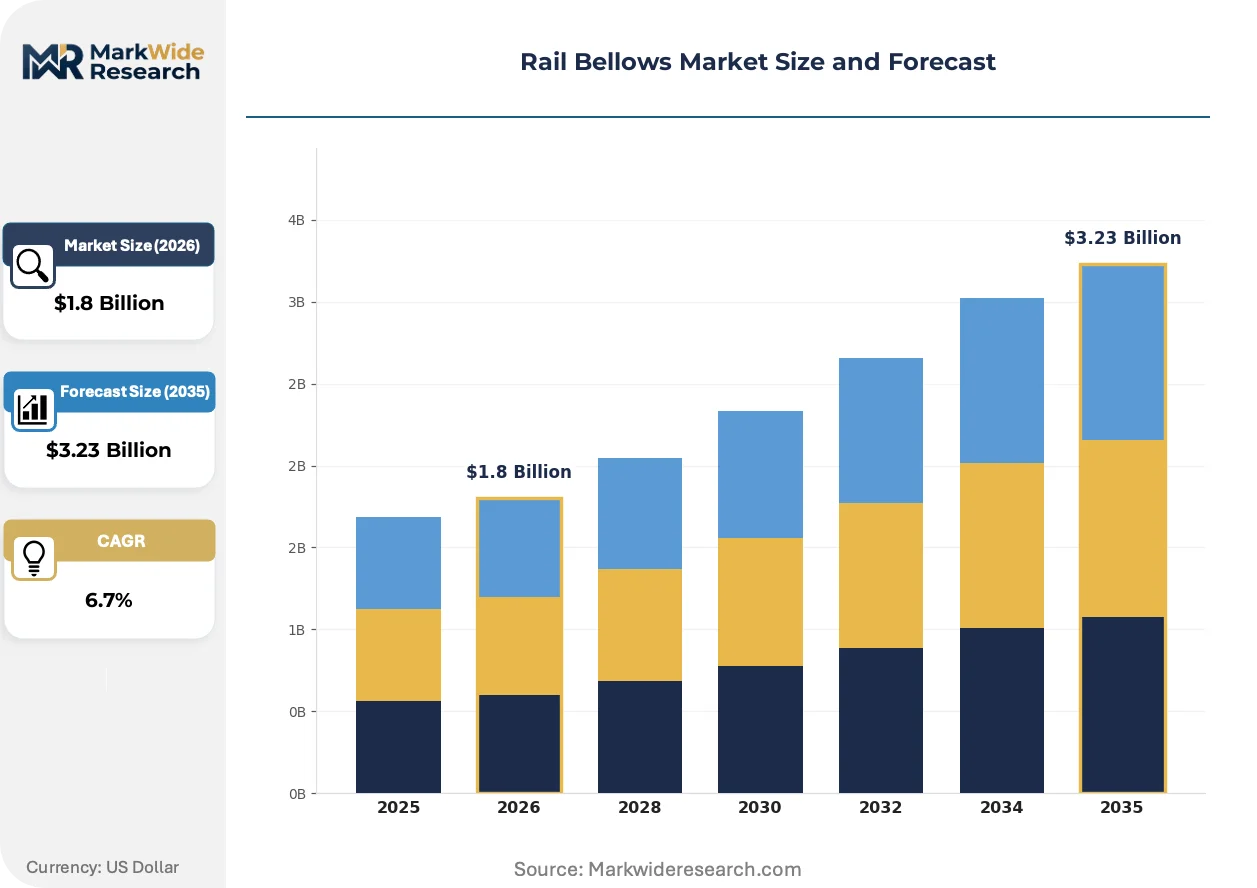
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bellows, Double Bellows, Triple Bellows, Multi-Bellows Material: Rubber, PVC, Silicone, Neoprene End User: Rail Operators, Infrastructure Providers, Maintenance Companies, Manufacturers Application: Suspension Systems, Vibration Isolation, Dust Protection, Noise Reduction |
| Companies Covered | Dellner Couplers AB, Hutchinson SA, ATG Autotechnik GmbH, Cavotec Group, Schleifring GmbH, CRRC Corporation Limited, Narita Seisakusho Co., Ltd., Bosch Rexroth AG, Shijiazhuang Anjie Electric Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Bellows Market Emerging Trajectories
Active material science breakthroughs and regulatory carbon accounting are converging to restructure how rail operators evaluate total cost of ownership across sealing component lifecycles.
Modular bellows architectures with standardized flange interfaces are decentralizing maintenance economics across Scandinavian and Baltic rail networks. Regional operators facing dispersed fleet footprints adopt field-replaceable cartridge designs that reduce depot downtime. This modularity is decentralizing service revenue from original equipment manufacturers toward certified third-party maintenance providers.
REACH and RoHS constraints on phthalate plasticizers are tightening formulation latitude for European compounders. The restriction cascade forces substitution toward bio-based plasticizers and peroxide-cured silicone systems in bellows production. High-speed applications with extended temperature cycling requirements bear the steepest compliance-driven cost adjustments.
Chinese state rail procurement is consolidating specification authority within CRRC's backward-integrated supply chain. Domestic compounders with captive silicone blending capacity capture disproportionate share of new fleet orders. This concentration is visible in procurement patterns for Beijing and Shanghai metro expansions, where local certification holders exclude foreign bellows suppliers from tender participation.
Rail Bellows Market Segmentation
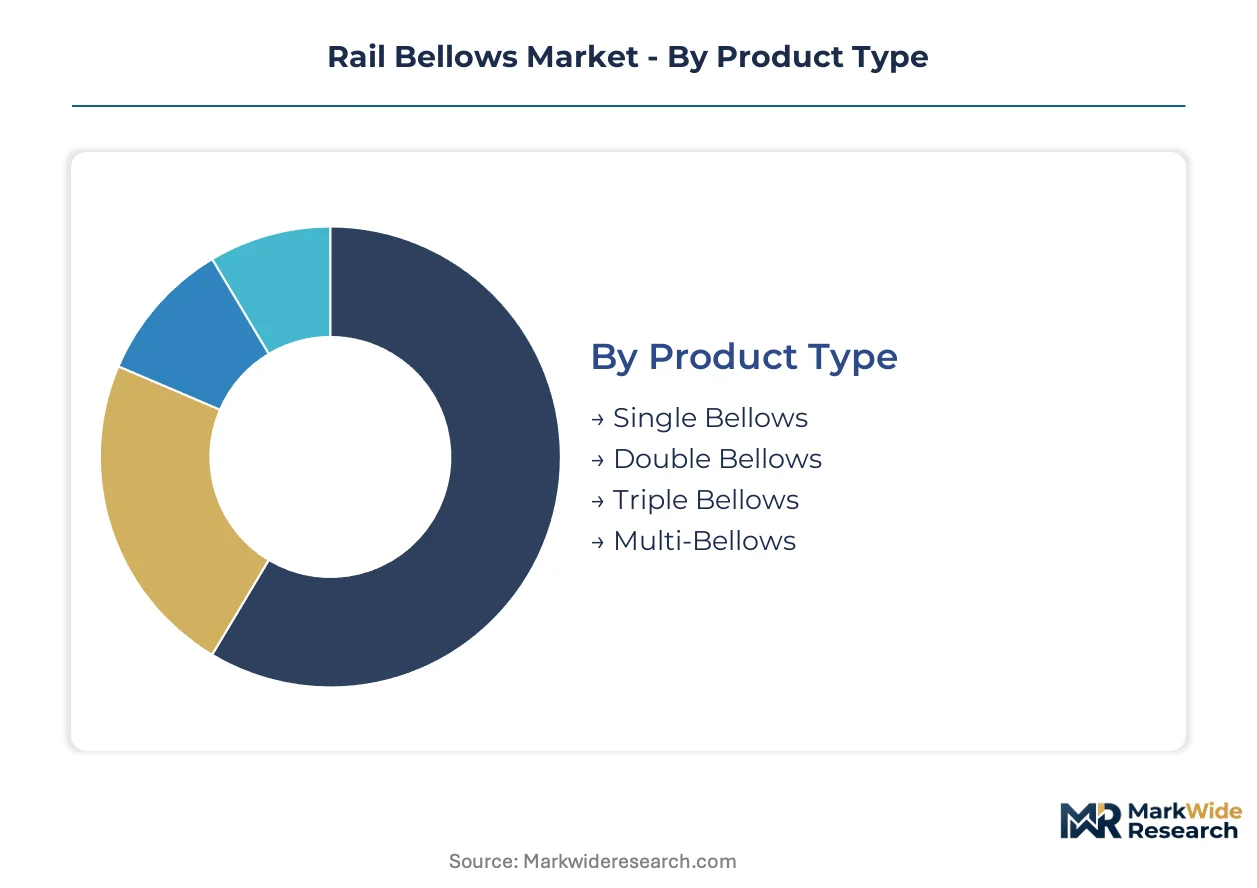
Rail bellows segmentation reveals how material chemistry and convolution architecture split procurement between cost-optimized metro fleets and performance-driven high-speed corridors. Product and material tiers map directly to lifecycle cost models and regional regulatory exposure.
Product Type:
Single bellows dominate unit volume across commuter rail networks. Multi-bellows assemblies command premium positioning through redundant sealing architectures.
- Single Bellows:Molded elastomer bodies with three convolutions and 2-3 mm wall thickness serve as the baseline configuration for urban metro fleets. Procurement concentrates in China's CRRC supply chain where domestic sourcing mandates favor local compounders for Beijing and Shanghai metro expansions.
- Double Bellows:Dual-chamber designs with intermediate reinforcement rings address intermediate duty cycles in regional intercity services. Demand clusters in German and French networks undergoing noise reduction retrofits under EU Green Deal embodied carbon tracking requirements.
- Triple Bellows:Three-stage convolution stacks with tuned stiffness profiles suit high-frequency suspension articulation.
- Multi-Bellows:Assemblies exceeding four convolutions integrate acoustic damping layers for tunnel ventilation compliance.
Mature deployment sits with Single Bellows. Newer deployment is concentrated in Multi-Bellows.
Material:
Neoprene retains cost-sensitive volume while silicone captures specification upgrades for temperature-critical applications.
- Silicone:Peroxide-cured formulations with -50°C to 200°C operating range displace neoprene in high-speed rail fleets facing EU F-Gas Regulation compliance deadlines. East Asian operators specify advanced silicone assemblies for expanded fleet orders requiring extended service intervals.
- Neoprene:Chloroprene-based compounds with moderate oil resistance and 2-5 mm molded walls remain the metro fleet default. Cost pressure from thermoplastic vulcanizate substitutes threatens this segment in Scandinavian and Baltic networks.
- Rubber:Natural and synthetic blends with fabric reinforcement for structural load bearing.
- PVC:Plasticized formulations constrained by REACH phthalate restrictions across European supply chains.
Silicone formulations are expanding most quickly. Neoprene retains the largest installed base.
End User:
OEM procurement patterns diverge sharply from aftermarket replacement economics across maintenance networks.
- Rail Operators:State-owned and private fleet managers specify bellows assemblies through rolling stock procurement tenders. China's state rail ecosystem concentrates orders with CRRC-backward-integrated compounders holding SAMR certification.
- Maintenance Companies:Third-party service providers adopt modular cartridge designs for field replacement in dispersed Scandinavian networks. Dellner Couplers AB anchors supply contracts for standardized flange interfaces.
- Infrastructure Providers:Track and tunnel system integrators procure sealing elements for fixed installations.
- Manufacturers:Rolling stock builders integrate bellows into bogie and suspension subassemblies.
Procurement authority is consolidating with Rail Operators. Maintenance Companies are capturing expanding aftermarket share.
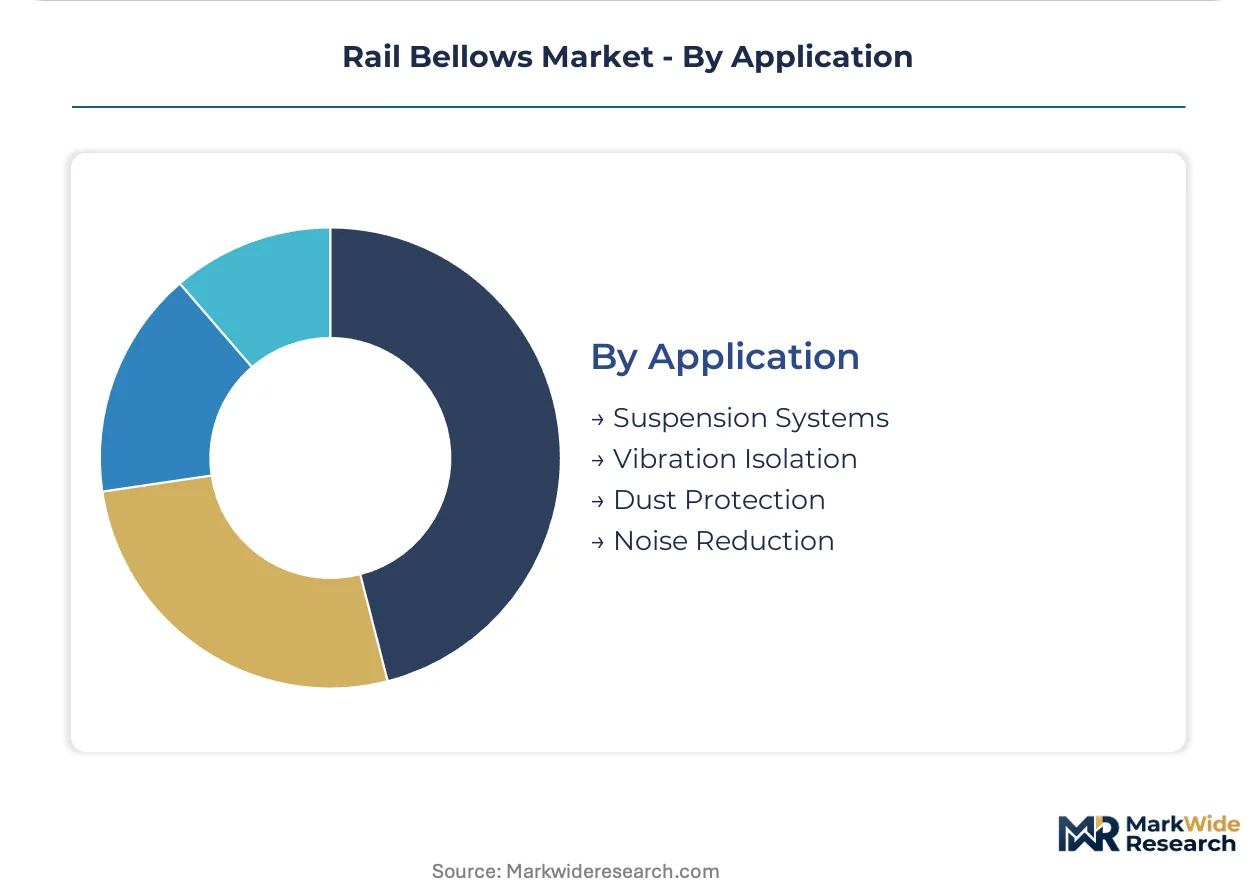
Application:
Pure suspension functions face margin pressure as acoustic and environmental sealing applications capture specification premiums.
- Noise Reduction:Multi-convolution bellows with integrated damping layers address urban noise ordinances in dense metropolitan corridors. Tunnel ventilation standards in German networks drive retrofit demand for advanced acoustic assemblies.
- Dust Protection:Sealed convolution architectures prevent debris ingress in desert and high-particulate operating environments. Specifications tighten across Middle Eastern and Australian rail networks.
- Suspension Systems:Articulation joints accommodating body-to-bogie movement remain the traditional volume application.
- Vibration Isolation:Tuned stiffness bellows decouple powertrain and track-induced oscillations from passenger compartments.
Deployment maturity rests with Suspension Systems. Steepest expansion trajectory belongs to Noise Reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rail bellows procurement concentrates where high-speed fleet orders and metro expansions intersect with domestic sourcing mandates. State rail operators in East Asia and Europe drive specification upgrades through environmental and noise regulations.
China
CRRC Corporation Limited anchors procurement through backward-integrated supply chains for Beijing and Shanghai metro expansions. SAMR certification requirements and GB standards exclude foreign bellows suppliers from state tender participation. Domestic compounders with captive silicone blending capture fleet orders across the Yangtze River Delta manufacturing cluster.
Germany
Deutsche Bahn's noise reduction retrofits for legacy rolling stock create replacement demand for advanced acoustic bellows. EU F-Gas Regulation and REACH phthalate restrictions force reformulation toward peroxide-cured silicone systems. Industrial concentration in Bavaria and Baden-Württemberg hosts specialized vulcanization technicians for fabric-reinforced bonding.
Japan
East Japan Railway and Central Japan Railway specify extended-service-interval bellows for Shinkansen fleet renewals. METI guidelines on embodied carbon tracking pressure suppliers to document polymer provenance. Manufacturing clusters in the Nagoya-Chubu corridor specialize in tuned stiffness profiles for high-frequency suspension articulation.
France
SNCF's urban network retrofits under EU Green Deal requirements drive multi-convolution bellows adoption for tunnel ventilation compliance. ECHA restrictions on SVHC candidates cascade through PVC and rubber compound supply chains. The Île-de-France region concentrates maintenance provider networks adopting modular cartridge designs.
Sweden
Dispersed fleet footprints across Scandinavian networks favor field-replaceable bellows architectures. Dellner Couplers AB anchors supply contracts for standardized flange interfaces among regional operators. Baltic corridor integration extends procurement patterns into neighboring rail networks.
Rail Bellows Market Vendor Landscape
Backward integration dominates the current landscape as compounders secure captive silicone blending capacity and OEMs internalize rubber formulation. The vendor base splits between state-integrated rail suppliers and independent specialists serving fragmented maintenance networks. Three archetypes prevail: polymer science heritage firms, state-captive manufacturers, and modular architecture specialists. Capacity expansion in East Asian silicone compounding and strategic partnerships for European REACH compliance represent the dominant competitive vectors.
Among European heritage compounders, Hutchinson SA exemplifies premium silicone supply positioning through polymer science depth. State-captive manufacturing is represented by CRRC Corporation Limited, whose backward integration into rubber compounding mirrors China's domestic sourcing mandates. Dellner Couplers AB occupies the modular specialist tier, anchoring field-replaceable supply relationships across Scandinavian maintenance networks. These three illustrate how geographic regulatory exposure and supply chain configuration shape competitive positioning.
| Leading Market Players |
|---|
| Dellner Couplers AB |
| Hutchinson SA |
| ATG Autotechnik GmbH |
| Cavotec Group |
| Schleifring GmbH |
| CRRC Corporation Limited |
| Narita Seisakusho Co., Ltd. |
| Bosch Rexroth AG |
| Shijiazhuang Anjie Electric Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Peroxide-cured silicone formulation transitions are simultaneously elevating compounder cost structures and concentrating procurement leverage among East Asian suppliers with captive blending capacity. This production-method shift repositions neoprene as a stranded cost tier while rewarding backward-integrated manufacturers with pricing power over temperature-critical specifications.
Pricing Analysis
Volume concentrates in single-bellows neoprene configurations for metro fleets, while margin pools in multi-convolution silicone assemblies for high-speed corridors. Price differentiation hinges on SAMR certification tier and vulcanization energy documentation under EU Green Deal requirements. Cost compression in neoprene tiers is intensifying because thermoplastic vulcanizate substitutes threaten commodity positioning. Maintenance companies in Scandinavian networks exhibit highest price sensitivity; high-speed rail operators in East Asia demonstrate lowest sensitivity due to extended service interval value.
Supply Chain Analysis
Specialized vulcanization technician shortages in Bavaria and Baden-Württemberg constrain European fabrication capacity despite design leadership. Manufacturing gravity centers on China, Germany, and Japan, with polymer precursor supply drawing from methanol and silicon metal spot markets concentrated in East Asian trading hubs. Single-source vulnerability pervades CRRC's backward-integrated supply chain under domestic sourcing mandates. Distribution runs through OEM-integrated procurement for new fleet orders and certified third-party maintenance networks for retrofit aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone elastomer chemistry is displacing neoprene as the baseline specification across temperature-critical rail applications, compressing legacy compounder margins while opening premium positioning for certified suppliers. This technology-transition phase rewards stakeholders who anchor procurement relationships before specification standards crystallize.
For Market Incumbents: To counter thermoplastic vulcanizate substitution in metro segments, incumbents should anchor backward integration into silicone polymer blending and secure REACH-compliant formulation documentation ahead of SVHC candidate list expansions. Capacity addition in Yangtze River Delta manufacturing clusters captures CRRC procurement concentration.
For New Entrants and Emerging Players: Digital twin integration platforms offer the most penetrable entry vector for condition-based replacement contracts with dispersed Scandinavian maintenance networks. White-space targets include acoustic bellows retrofits for German urban noise ordinances and modular cartridge designs for Baltic corridor operators. Go-to-market execution should prioritize certified flange standardization partnerships with Dellner Couplers AB's established interface architecture.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by state-integrated rail OEMs seeking captive silicone compounding capacity. Long-term viability favors compounders with documented polymer provenance and vulcanization energy intensity metrics aligned with EU Green Deal embodied carbon tracking. The signal to watch is ECHA restriction cascade acceleration into phthalate plasticizer alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive polymer blending secures CRRC procurement access under SAMR certification requirements. |
| REACH-Compliant Formulation Certification | Peroxide-cured systems preempt ECHA SVHC restrictions on phthalate plasticizers in European supply chains. |
| Modular Cartridge Architecture Development | Standardized flange interfaces decentralize maintenance revenue toward third-party service providers. |
| Digital Twin Platform Integration | IoT sensor convergence enables predictive replacement contracts with rail operators. |
| EU Green Deal Carbon Documentation | Vulcanization energy provenance certification opens premium positioning for low-carbon silicone suppliers. |
Methodological Framework
Independent corroboration across compounder procurement directors, OEM platform engineers, and maintenance service heads underwrites the qualitative findings in this study. Primary fieldwork with CRRC supply chain managers, Deutsche Bahn retrofit specification leads, and Scandinavian fleet maintenance directors combined with secondary validation from customs trade data, REACH registration dossiers, and SAMR certification records. Bottom-up segment sizing and top-down market triangulation anchored volume estimates.
Comparable-period anchoring referenced historical silicone-neoprene substitution patterns across temperature-critical sealing applications to calibrate the projection horizon. The analytical framework modeled product type, material chemistry, end-user procurement authority, and application function dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted fleet expansion schedules and regulatory compliance timeline acceleration. Forecast inputs incorporated EU F-Gas Regulation phasedown deadlines and METI embodied carbon tracking guideline implementations.
The model holds under stable petrochemical feedstock pricing and sustained domestic sourcing mandate enforcement; deviation in methanol spot volatility or SAMR certification scope expansion would shift supplier competitive positioning. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Electro-Pneumatic Train Brakes Market
Railway
Railway Pantograph Market
Railway
Railroad Brake Shoe Market
Railway
Rail Brace Market
Railway
Automatic Train Control Market
Railway
South Korea Connected Rail Market
Railway
Gangway for Railway Vehicles Market
Railway
Solar Powered Train Market
Railway
Global Train Brake Market
Railway
Automatic Train Operation System Market
Railway
India Rail Freight Transport Market
Railway
Heritage Railways Trains Market
Railway
Rail Transit Traction Converter Market
Railway
Freight Cars Market
Railway
Tugger Trains Market
Railway
Train Exterior Lighting Market