
 Canada Home Equity Lending Market | 2026-2036
Canada Home Equity Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Home Equity Lending Market Outlook
Prime-rate-plus pricing tiers is redrawing competitive positioning across Canadian home equity products. RBC Royal Bank leverages its branch network density to dominate high-loan-to-value originations in urban Ontario. Scotiabank anchors its position through specialized renovation-lending programs targeting suburban mortgage holders. TD Canada Trust differentiates via integrated digital pre-approval flows that compress closing timelines for existing customers.
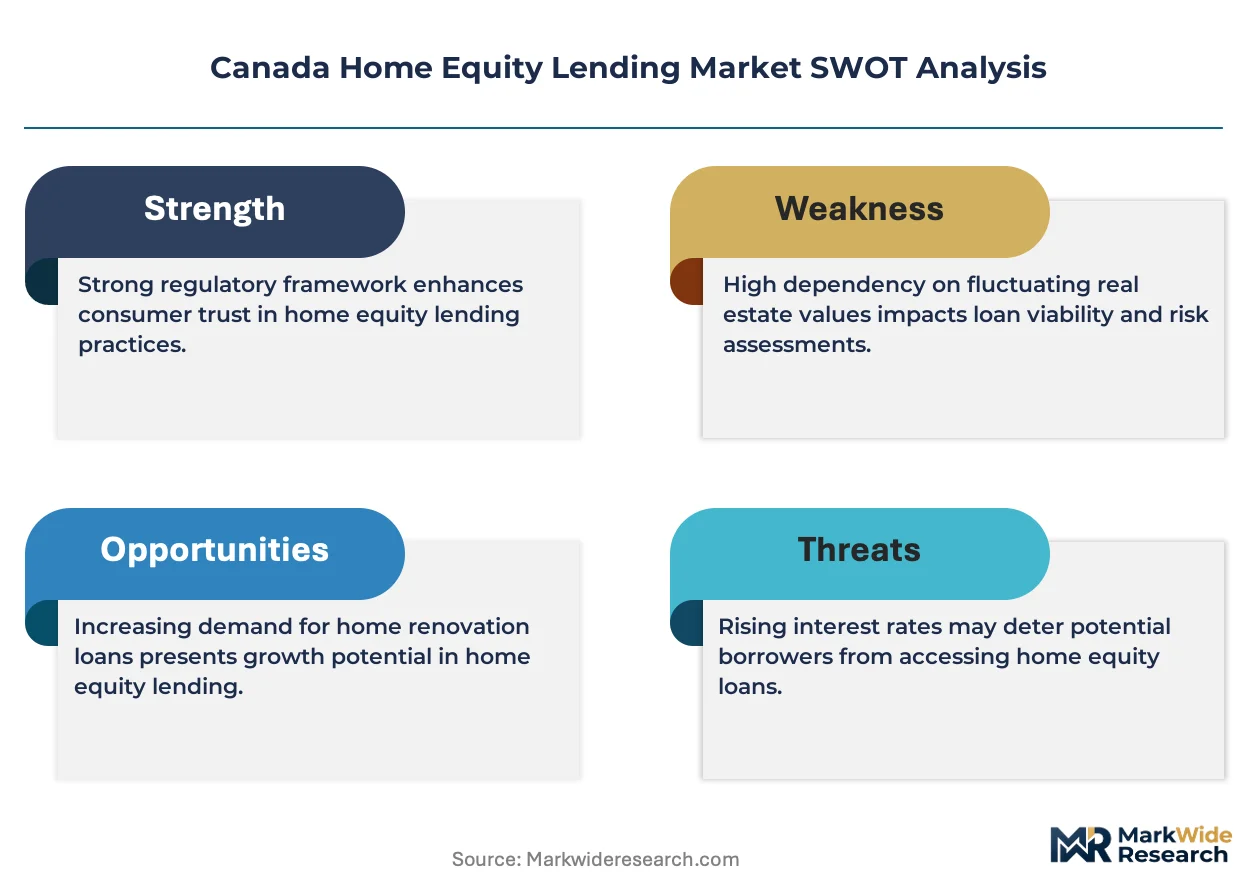
Canada home equity lending encompasses secured credit facilities collateralized by residential property value exceeding outstanding first-mortgage balances, typically structured as revolving lines or term loans with variable or fixed interest rate parameters tied to prime or government bond benchmarks. These instruments finance property improvements, liability consolidation, or capital deployment while preserving primary mortgage terms. Home Equity Line of Credit products command the largest outstanding balance pool due to payment flexibility and reusable capacity structures. Home Equity Loan segments generate superior margin profiles through fixed amortization schedules and rate certainty premiums. Reverse Mortgage categories attract fastest volume expansion as demographic aging accelerates wealth-extraction demand from long-tenure homeowners.
OSFI's B-20 guideline framework and mortgage stress-test requirements constrain maximum qualifying ratios and shape product accessibility across all federally regulated lenders. CMHC securitization standards and provincial credit union oversight by FSRA Ontario and BCFSA determine funding cost structures and capital treatment for balance-sheet retention. Stakeholders must monitor policy rate transmission mechanics and housing supply elasticity indicators to anticipate origination volume inflections and margin compression risks.
Market Dynamics
OSFI's B-20 mortgage stress-test framework is compressing qualifying ratios and redirecting borrower flows toward alternative lending channels across Canadian home equity products.
Growth Catalysts
- Demographic wealth extraction:Aging homeowners in Ontario and British Columbia are unlocking long-tenure property equity through reverse mortgage structures. CMHC securitization standards support funding availability for these instruments.
- Renovation financing demand:Suburban mortgage holders in Greater Toronto Area corridors are deploying home equity lines for property improvements. FSRA Ontario oversight maintains consumer protection standards while enabling product innovation.
- Digital pre-approval infrastructure:Automated valuation models and integrated banking platforms are compressing closing timelines. Existing customer data pools enable rapid collateral assessment without branch visits.
Market Restraints
- Policy rate transmission volatility:Bank of Canada overnight rate adjustments transmit immediately into variable-rate home equity products. Borrower qualification capacity fluctuates with each monetary policy cycle.
- Metropolitan supply concentration:Origination volume clusters in Vancouver and Toronto metropolitan areas. Regional housing market corrections in these corridors transmit directly into portfolio performance.
- Stress-test qualification friction:OSFI B-20 guidelines impose minimum qualifying rates above contracted rates. Maximum loan-to-value thresholds constrain product accessibility for high-leverage borrowers.
Strategic Opportunities
- Atlantic Canada penetration:Nova Scotia and New Brunswick housing markets show underdeveloped home equity utilization relative to Ontario. Aging in-migration from Ontario retirees creates wealth-extraction demand.
- Climate retrofit financing:CMHC Greener Homes Loan program creates dedicated capital pools for energy-efficient renovation lending. Property-assessed clean energy structures enable novel collateralization mechanics.
- Credit union channel expansion:Provincial regulators in Alberta and Saskatchewan oversee deposit-taking institutions with localized underwriting flexibility. Community-based lenders capture segments disqualified by federal stress-test requirements.
Industry Challenges
- Appraisal capacity constraints:Automated valuation model adoption lags in rural and exurban territories. Human appraiser shortages in Northern Ontario and Prairie provinces extend closing timelines.
- Legacy core system integration:Established lenders face middleware complexity when embedding fintech origination platforms. Real-time collateral monitoring requires data architecture upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Home Equity Lending Market |
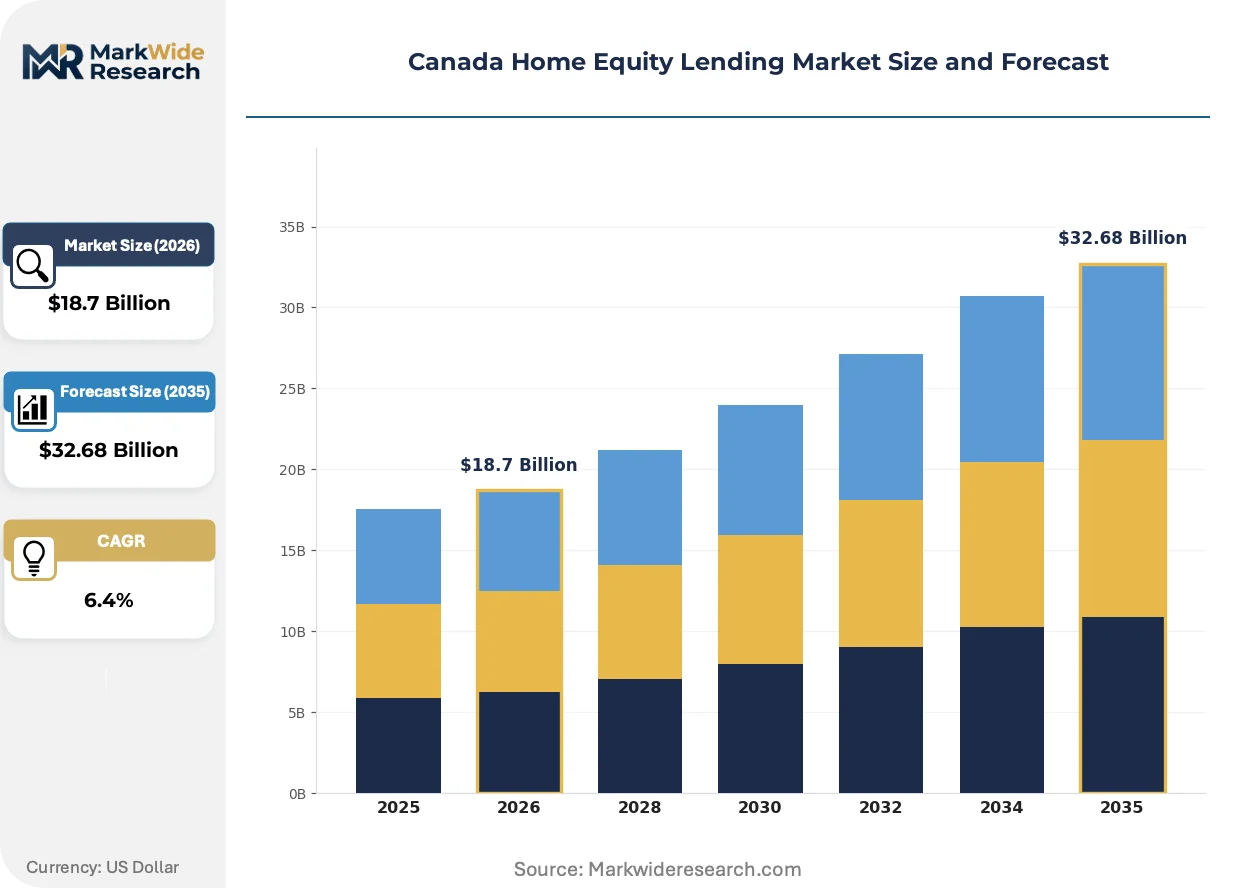
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Home Equity Line of Credit, Home Equity Loan, Reverse Mortgage, Second Mortgage End User: Homeowners, Real Estate Investors, First-time Buyers, Financial Institutions Distribution Channel: Banks, Credit Unions, Online Lenders, Mortgage Brokers Application: Home Renovation, Debt Consolidation, Education Funding, Major Purchases |
| Companies Covered | Tangerine Direct Bank, Bank of Montreal, HSBC Bank Canada, RBC Royal Bank, Scotiabank, National Bank of Canada, First Ontario Credit Union, TD Canada Trust, B2B Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Home Equity Lending Market Strategic Shifts
Open banking data sharing protocols are enabling real-time income verification and collateral monitoring, compressing underwriting cycles while reshaping borrower expectations for home equity access speed.
Artificial intelligence-driven credit decisioning is fragmenting traditional risk-tiering models across Canadian home equity lending. Alternative data sources including cash-flow patterns and property-level energy efficiency scores now supplement bureau reports. Fintech originators in Ontario and British Columbia are deploying these tools to capture borrowers near federal qualification thresholds. Incumbent banks are responding through partnerships with data aggregation platforms rather than proprietary development.
OSFI's evolving B-20 guideline interpretations are tightening maximum gross debt service ratios for uninsured mortgage products. Federally regulated lenders must hold additional capital against high-loan-to-value home equity exposures. This regulatory pressure is accelerating product migration toward provincially regulated credit unions in Alberta and Quebec. BCFSA and FSRA Ontario are consequently reviewing their own capital adequacy frameworks to maintain competitive parity.
Borrower preference is rotating toward fixed-rate certainty within home equity loan structures rather than variable-rate line flexibility. Rate volatility exposure from Bank of Canada policy cycles is driving this behavioral shift among risk-averse homeowners. Origination mix in Vancouver and Toronto corridors now tilts toward term-loan products with rate-lock features. Lenders are responding by widening fixed-rate spreads to capture this preference premium.
Canada Home Equity Lending Market Segmentation
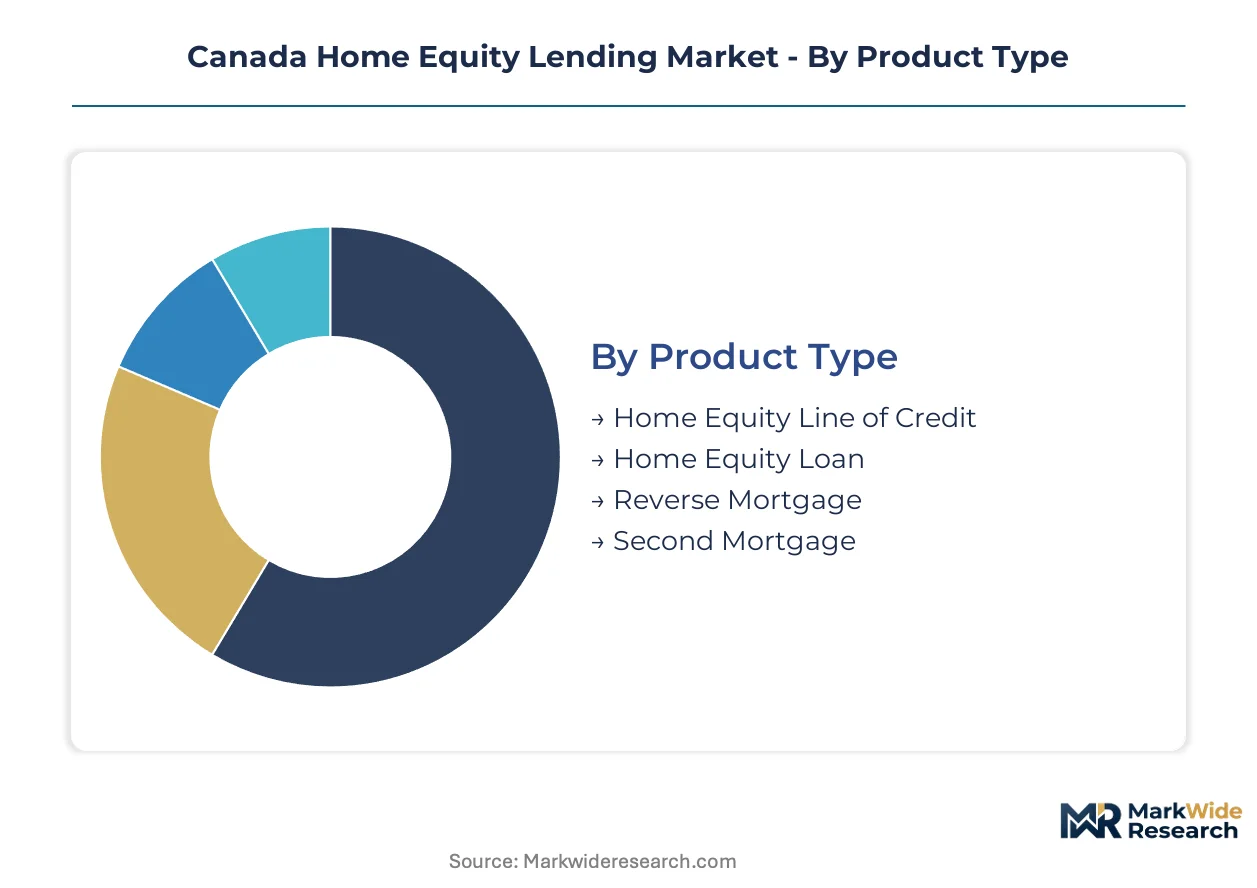
Product architecture across Canadian home equity lending channels reflects divergent risk appetites and customer relationship models. Segment-specific capital treatments under OSFI and provincial frameworks reshape origination economics for each distribution pathway.
Product Type:
Branch networks and digital platforms route distinct product categories toward borrower segments with varying liquidity needs and rate sensitivity profiles.
- Home Equity Line of Credit:Revolving secured facilities with variable-rate pricing tied to prime benchmarks enable repeated drawdowns without requalification. Demand concentrates among established homeowners in Greater Toronto Area corridors seeking flexible renovation financing without disrupting first-mortgage terms.
- Reverse Mortgage:Non-recourse structures with deferred repayment mechanics extract equity from long-tenure properties without monthly servicing obligations. Aging homeowners in Vancouver and Victoria metropolitan areas deploy these instruments for retirement income supplementation amid elevated property valuations.
- Home Equity Loan:Fixed-rate term products with amortizing repayment schedules provide capital certainty for one-time liquidity events.
- Second Mortgage:Subordinate lien positions behind existing first mortgages carry elevated risk premiums and shorter durations.
By volume, Home Equity Line of Credit leads. By growth pace, Reverse Mortgage is expanding most quickly.
End User:
Customer-type segmentation determines underwriting intensity and collateral monitoring protocols across origination channels.
- Homeowners:Primary residential occupants with established occupancy tenure and income documentation form the core collateral pool. Suburban mortgage holders in Ontario deploy home equity products for property improvements and liability consolidation.
- Real Estate Investors:Portfolio holders with multiple rental properties access leveraged capital against accumulated equity positions. BCFSA oversight in British Columbia imposes additional disclosure requirements on investment-purpose lending.
- First-time Buyers:Entry-level purchasers with limited equity positions rarely qualify for standalone home equity products.
- Financial Institutions:Lenders themselves participate as borrowers through interbank secured facilities and covered bond programs.
Homeowners dominate origination flow by count. Real Estate Investors generate superior margin per transaction.
Distribution Channel:
Channel economics reflect regulatory jurisdiction and capital treatment divergences between federal and provincial oversight regimes.
- Banks:Federally chartered institutions with national branch networks originate the majority of high-loan-to-value exposures. OSFI B-20 stress-test requirements constrain maximum qualifying ratios for uninsured products.
- Credit Unions:Provincially regulated deposit-takers in Alberta and Quebec operate under localized capital frameworks with underwriting flexibility. FSRA Ontario and BCFSA oversight enables product structures disqualified at federal institutions.
- Online Lenders:Digital-native originators leverage automated valuation models and alternative data for rapid collateral assessment.
- Mortgage Brokers:Intermediary channels aggregate borrower applications across multiple funding sources for rate optimization.
Banks retain the largest balance-sheet share. Credit Unions are gaining volume fastest among borrowers near federal qualification thresholds.
Application:
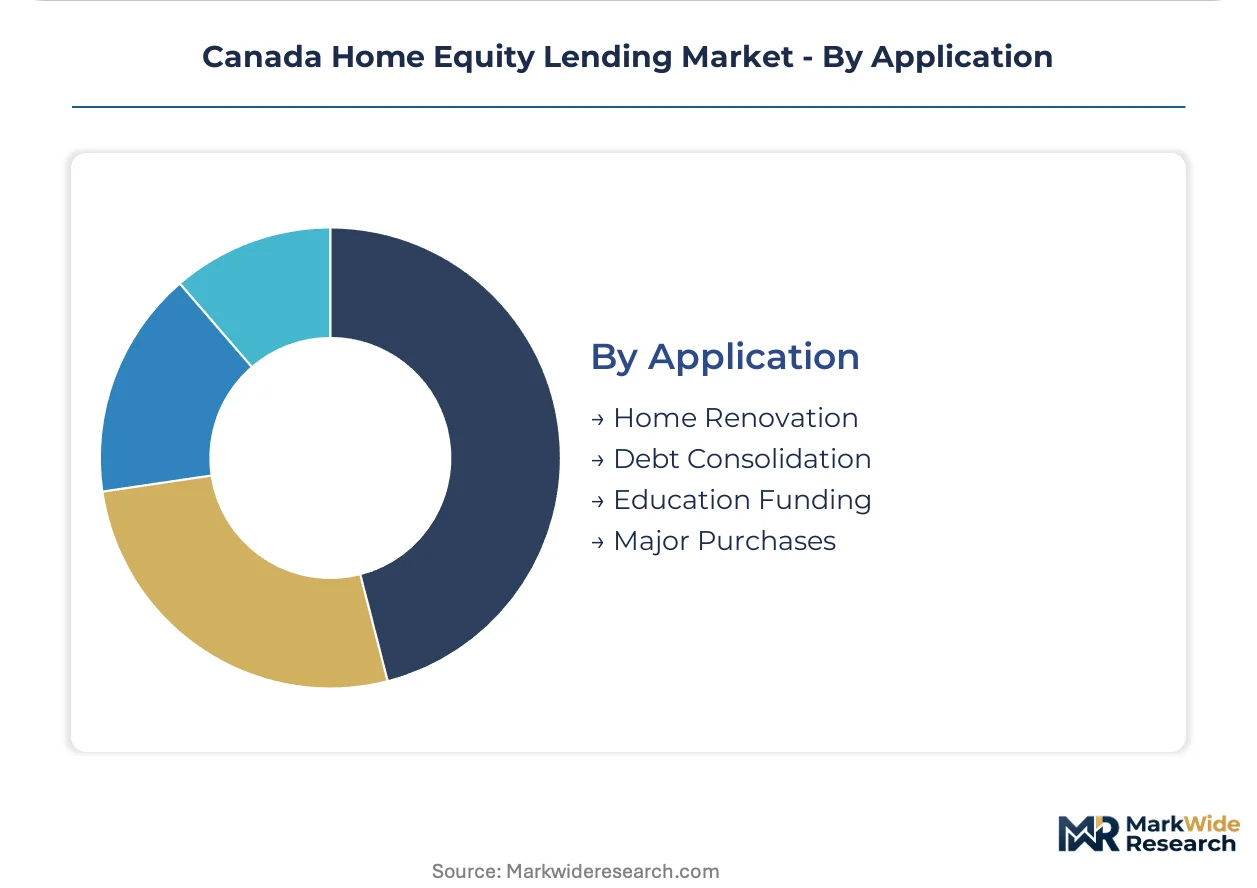
Use-case segmentation shapes loan structure preferences and repayment behavior patterns across borrower cohorts.
- Home Renovation:Property improvement financing commands the largest application share, with CMHC Greener Homes Loan program creating dedicated capital pools for energy-efficient retrofits. Atlantic Canada in-migration corridors show underdeveloped utilization relative to Ontario.
- Debt Consolidation:Liability restructuring applications reduce monthly servicing burdens through secured refinancing of unsecured obligations. Borrower flows concentrate among suburban mortgage holders facing variable-rate payment shocks.
- Education Funding:Post-secondary tuition financing through home equity structures preserves registered education savings plan integrity.
- Major Purchases:Vehicle acquisition and business capital deployment represent smaller application categories with shorter intended durations.
Home Renovation anchors volume. Debt Consolidation applications climb fastest amid policy rate volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's home equity lending activity clusters heavily in Ontario and British Columbia, where elevated property valuations and aging homeowner demographics concentrate demand. Provincial regulatory divergence between OSFI federal oversight and provincial credit union frameworks creates uneven competitive terrain across sub-regions.
Ontario
Greater Toronto Area suburban mortgage holders deploy home equity lines for renovation financing at rates exceeding national averages. FSRA Ontario maintains consumer protection standards while enabling product innovation that federal stress-test requirements constrain elsewhere. Aging in-migration from retirees creates wealth-extraction demand in Ottawa and Niagara corridors.
British Columbia
Vancouver and Victoria metropolitan areas anchor reverse mortgage expansion as long-tenure homeowners extract equity amid elevated valuations. BCFSA oversight imposes additional disclosure requirements on investment-purpose lending that shapes product structuring. Digital pre-approval infrastructure compresses closing timelines in Lower Mainland urban clusters.
Alberta
Calgary and Edmonton housing markets show underdeveloped home equity utilization relative to Ontario benchmarks. Provincial regulators oversee deposit-taking credit unions with localized underwriting flexibility that captures borrowers disqualified by federal B-20 stress-test requirements. Energy sector income volatility shapes borrower qualification patterns.
Quebec
Montreal metropolitan corridors concentrate origination volume with distinct language-market servicing requirements. Provincially regulated credit unions operate under capital frameworks that enable product structures unavailable at federally chartered institutions. Aging homeowner demographics in Quebec City drive reverse mortgage inquiry growth.
Atlantic Canada
Nova Scotia and New Brunswick housing markets exhibit underdeveloped home equity penetration relative to central Canada. Ontario retiree in-migration creates demographic tailwinds for wealth-extraction products in Halifax and Moncton corridors. CMHC securitization standards support funding availability as regional appraisal capacity constraints extend closing timelines.
Canada Home Equity Lending Market Competitive Environment
Concentration sits with federally chartered banks that dominate high-loan-to-value originations through national branch network density. OSFI capital adequacy requirements and B-20 stress-test frameworks constrain product accessibility at these institutions, creating competitive openings for provincially regulated alternatives. Two strategic archetypes define the competitive map: integrated deposit-taking banks with digital pre-approval infrastructure, and community-based credit unions with localized underwriting flexibility. Dominant competitive moves include branch network optimization in urban corridors and middleware partnerships with fintech origination platforms.
Among the integrated banking tier, RBC Royal Bank and Scotiabank exemplify archetypes competing on network density versus specialized program targeting. TD Canada Trust occupies a position emphasizing digital workflow compression. Tangerine Direct Bank represents the direct-banking model with streamlined overhead structures. Bank of Montreal and National Bank of Canada anchor Quebec-focused competitive positioning. First Ontario Credit Union sits within the provincially regulated tier that captures borrower flows near federal qualification thresholds.
| Leading Market Players |
|---|
| Tangerine Direct Bank |
| Bank of Montreal |
| HSBC Bank Canada |
| RBC Royal Bank |
| Scotiabank |
| National Bank of Canada |
| First Ontario Credit Union |
| TD Canada Trust |
| B2B Bank |
| Others |
Value Chain & Pricing Dynamics
Twenty-one-day collateral valuation cycles concentrate origination capacity in urban appraisal districts, amplifying pricing power for lenders with automated valuation model infrastructure while compressing margins for competitors dependent on manual assessment in exurban territories.
Pricing Analysis
OSFI's B-20 guideline framework dictates the pricing tier structure across Canadian home equity products, separating prime-rate-plus offerings for qualified borrowers from alternative channel rates for stress-test-disqualified applicants. Rate differentiation hinges on loan-to-value thresholds and borrower debt-service ratios, with fixed-rate term products commanding certainty premiums over variable lines. Pricing pressure stems from Bank of Canada policy transmission mechanics that immediately reset variable-rate margins. First-time equity access seekers show highest price sensitivity; long-tenure homeowners with substantial unencumbered value demonstrate lowest.
Supply Chain Analysis
Collateral assessment bottlenecks in Northern Ontario and Prairie provinces constrain origination velocity, creating regional funding access disparities that concentrate profitable volume in Toronto and Vancouver metropolitan corridors. Funding draws from CMHC securitization pools, bank deposit bases, and provincial credit union networks. Single-source vulnerability rests on automated valuation model vendor concentration. Distribution runs through branch networks, digital platforms, and mortgage broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's home equity lending market sits in a cyclical recovery phase as Bank of Canada rate stabilization restores borrower qualification capacity and releases pent-up renovation financing demand accumulated through the tightening cycle.
For Market Incumbents: Consolidate appraisal technology partnerships to compress collateral assessment timelines below competitor benchmarks. Deepen data architecture investments for real-time income verification through open banking protocols. Fintech originators threaten branch-dependent customer acquisition economics; middleware integration with automated valuation platforms offers defensive positioning. For New Entrants and Emerging Players: Anchor in Atlantic Canada corridors where Ontario retiree in-migration creates demographic tailwinds for wealth-extraction products. Nova Scotia and New Brunswick show underdeveloped home equity penetration relative to central Canada benchmarks. Climate retrofit financing through CMHC Greener Homes Loan structures offers differentiated origination positioning. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-structural play because aging homeowner cohorts across Ontario and British Columbia will sustain reverse mortgage expansion regardless of cyclical rate movements. Acquisition targets should display provincial regulatory licenses enabling stress-test-exempt product structures. Watch OSFI B-20 guideline reinterpretations as the signal for capital requirement inflections that reshape competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Valuation Model Deployment | Compresses collateral assessment timelines from weeks to days in rural territories. |
| Open Banking Integration | Enables real-time income verification that accelerates underwriting cycles for existing customers. |
| Credit Union Channel Partnership | Captures borrower flows disqualified by federal OSFI stress-test requirements. |
| Climate Retrofit Program Participation | Accesses CMHC Greener Homes Loan capital pools for energy-efficient renovation lending. |
| Reverse Mortgage Product Expansion | Addresses demographic wealth-extraction demand from aging long-tenure homeowners. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with lending executives, mortgage broker network heads, provincial regulatory affairs officers, and credit union portfolio managers; and secondary validation against OSFI guideline publications, CMHC securitization disclosures, Bank of Canada monetary policy transmissions, and provincial financial authority oversight frameworks. Bottom-up origination volume estimates triangulated against top-down balance-sheet aggregation from federally regulated institution filings.
Across the analysis window, the forecasting framework modeled product type segmentation, distribution channel economics, and end-use application patterns alongside regional regulatory jurisdiction clusters. CAGRs derived from historical origination trajectory analysis adjusted for policy rate transmission lags and housing supply elasticity indicators. Stress-test qualification thresholds and automated valuation model adoption curves served as primary demand-side forecast inputs.
Underlying assumptions cover Bank of Canada policy rate stabilization, with deviation risk concentrated in metropolitan housing market corrections and OSFI capital adequacy reinterpretations. Practitioners should keep alternative scenarios live as B-20 guideline enforcement intensity and open banking data sharing protocol adoption evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Micro Lending Market
Loans and Leasing
Asia-Pacific Motorcycle Loan Market
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Russia Car Loan Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
Global Financial Leasing Market
Loans and Leasing
South Korea Auto Loan Market
Loans and Leasing
United States Digital Lending Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
India Car Loan Market
Loans and Leasing
Indonesia Mortgage/Loan Brokers Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
North America Motorcycle Loan Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
NPL Servicing Market