
 Australia Coal Market | 2026-2036
Australia Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Coal Market Outlook
Mining engineering talent is bifurcating the Australia coal sector as experienced geologists and pit supervisors retire faster than universities replenish pipelines. BHP Group Ltd sustains operational continuity through aggressive graduate recruitment and automation deployment across its Queensland coking coal assets. Whitehaven Coal Limited specializes in high-CV thermal products from its New South Wales mines, securing long-haul contracts with Asian power utilities. Yancoal Australia Ltd leverages Chinese parent-company capital to maintain scale across its Hunter Valley operations.
Australia coal encompasses carbon-rich sedimentary rock formations graded by rank, calorific value, and ash content, with coking coal requiring specific plasticity and coke strength indices for blast furnace feed. Thermal coal fires boilers for electricity generation, while metallurgical variants reduce iron ore in steelmaking. Coking coal commands premium pricing due to limited global deposits with suitable rheological properties, whereas thermal coal faces structural pressure from renewable substitution in domestic power. Steel manufacturing end-use absorbs the highest-margin Australian exports, particularly from Queensland's hard coking seams. Export markets dominate volume flows, with direct sales to Japanese and Korean mills preserving price discovery mechanisms.
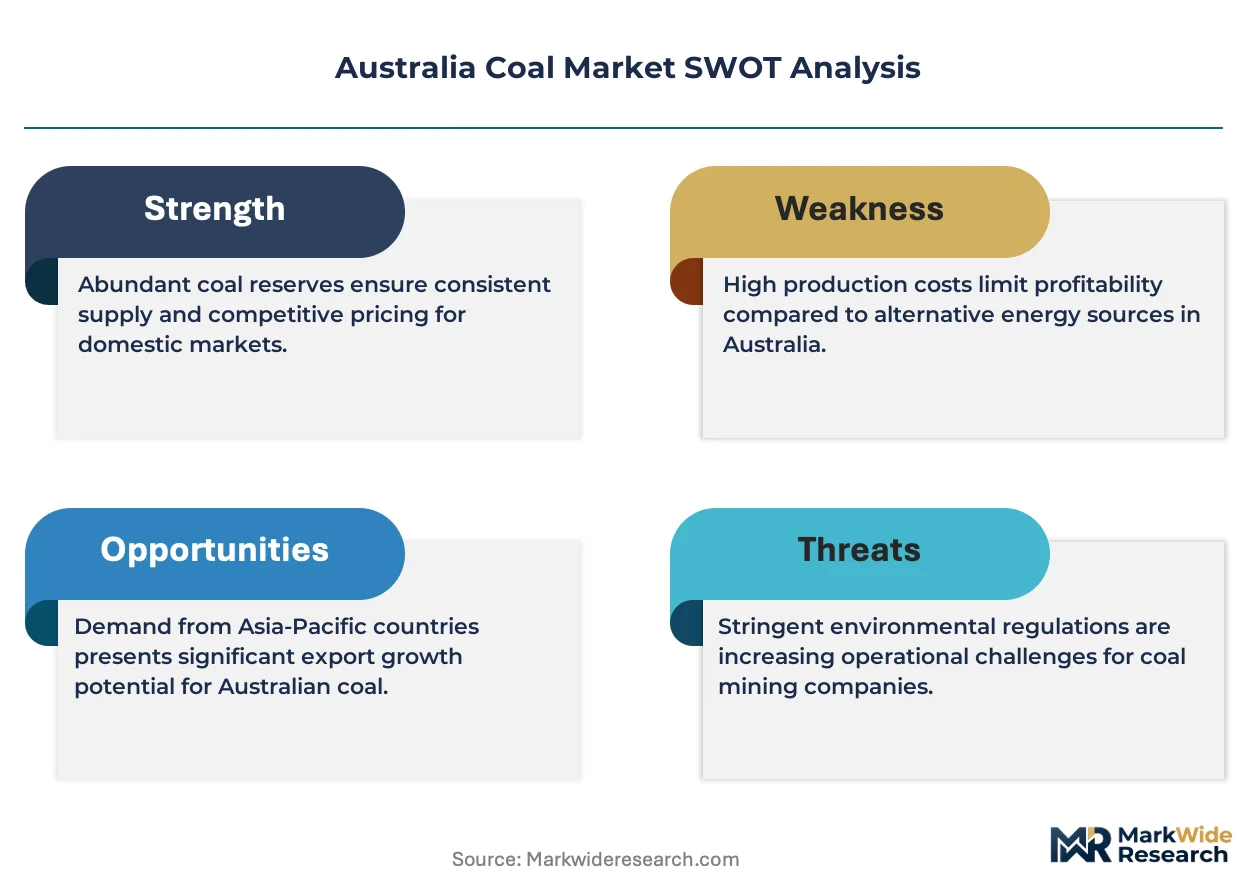
The Clean Energy Regulator administers Australia's Safeguard Mechanism, forcing large coal producers to acquire carbon credits or abate emissions below facility baselines. State environmental authorities in Queensland and New South Wales impose progressive rehabilitation bonds and water licensing conditions that extend project approval timelines. The National Greenhouse and Energy Reporting scheme mandates transparent emissions disclosure, shaping investor risk assessments for mine developments. Stakeholders must weigh reserve depletion schedules against escalating compliance costs and capital allocation shifts toward metallurgical-quality deposits.

Market Dynamics
The Australia coal market is experiencing acute pressure from the Safeguard Mechanism reforms, which are compressing emissions baselines for large mining facilities and forcing capital reallocation toward metallurgical-grade deposits with lower carbon intensity per unit value.
Growth Catalysts
- Steel decarbonization timelines:Japanese and Korean blast furnace operators are locking in long-haul coking coal contracts to secure supply before alternative reducing agents mature. This preserves Australian hard coking seam economics.
- Queensland infrastructure expansion:Port capacity upgrades at Hay Point and Abbot Point are decongesting export bottlenecks for Bowen Basin producers. Throughput gains directly lift realized prices for mine operators.
- Clean Energy Regulator credit markets:The Safeguard Mechanism's carbon credit trading system creates compliance expenditure predictability. Large facilities can hedge abatement costs through forward credit purchases.
Market Restraints
- Renewable substitution in domestic power:Grid-scale solar and wind capacity additions in New South Wales and Queensland are structurally displacing baseload thermal coal demand from the National Electricity Market.
- Progressive rehabilitation bonding:Queensland's Department of Environment and Science mandates escalating financial assurances for mine closure liabilities. Capital gets trapped in escrow rather than deployed to growth.
- Geographic concentration of premium seams:Hard coking coal reserves with optimal plasticity and coke strength indices cluster narrowly in Queensland's Bowen Basin. Supply disruption risk concentrates in a single geological province.
Strategic Opportunities
- Hunter Valley thermal optimization:New South Wales operations can pivot toward high-CV, low-ash products for Asian industrial boilers rather than grid power. This captures premium pricing outside the renewable-exposed electricity sector.
- Automation convergence with geology:Autonomous haulage systems combined with real-time seam characterization sensors enable selective mining of metallurgical zones within marginal thermal deposits.
- Carbon capture integration:The Safeguard Mechanism's baseline decline trajectory incentivizes pilot-scale post-combustion capture at coal-fired power stations. Early movers secure offset revenue streams and facility longevity.
Industry Challenges
- Mining engineering succession gaps:Experienced pit supervisors and resource geologists are retiring faster than Australian universities replenish graduate pipelines. BHP Group and Whitehaven Coal compete aggressively for shrinking talent pools.
- Water licensing complexity:Queensland's Department of Regional Development, Manufacturing and Water imposes cumulative impact assessments that extend approval timelines for new bores and extraction permits.
- Integration friction with legacy processing plants:Older coal handling preparation plants lack sensor density for real-time quality sorting. Retrofit capex competes with greenfield metallurgical project returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Coal Market |
| Market Size in 2026 | $48.60 Billion |
| Market Size in 2035 | $53.15 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Coal, Coking Coal, Anthracite, Bituminous Coal End User: Power Generation, Steel Manufacturing, Cement Production, Chemical Industry Distribution Channel: Direct Sales, Distributors, Online Sales, Export Markets Application: Electricity Generation, Metallurgical Processes, Industrial Heat, Carbon Black Production |
| Companies Covered | BHP Group Ltd, Yancoal Australia Ltd, Whitehaven Coal Limited, Glencore, Centennial Coal Company Ltd, Bloomfield Collieries Pty Ltd, Washington H. Soul Pattinson, New Hope Corporation, MACH Energy Australia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Coal Market Strategic Shifts
Automation and emissions monitoring technologies are compressing operating cost structures while regulatory transparency requirements reshape capital allocation priorities across Australian coal basins.
Autonomous haulage systems are displacing conventional truck-and-shovel operations in Queensland's open-cut coking coal mines. BHP's Daunia and Caval Ridge operations have deployed fully autonomous truck fleets that operate 24-hour cycles without shift-change downtime. Labor productivity gains are compressing unit costs and enabling extraction from deeper, lower-grade seams that manual operations could not economically access.
The Safeguard Mechanism's declining baselines are forcing facility-level emissions accounting granularity. Australia's Clean Energy Regulator now mandates monthly reporting against production-adjusted benchmarks rather than annual averages. Large coal producers must invest in continuous emissions monitoring systems and third-party verification audits. Queensland metallurgical facilities face the steepest compliance cost curves due to fugitive methane from gassy seams.
Japanese steel mills are consolidating procurement through direct equity stakes in Australian mines rather than arm's-length contracts. JFE Steel and Nippon Steel have acquired minority positions in Bowen Basin coking coal assets to secure volume certainty. This equity-linked sourcing model is displacing traditional quarterly price negotiations and spot market exposure. The shift is most visible in premium hard coking coal tiers where Japanese buyers previously dominated price discovery.
Australia Coal Market Segmentation
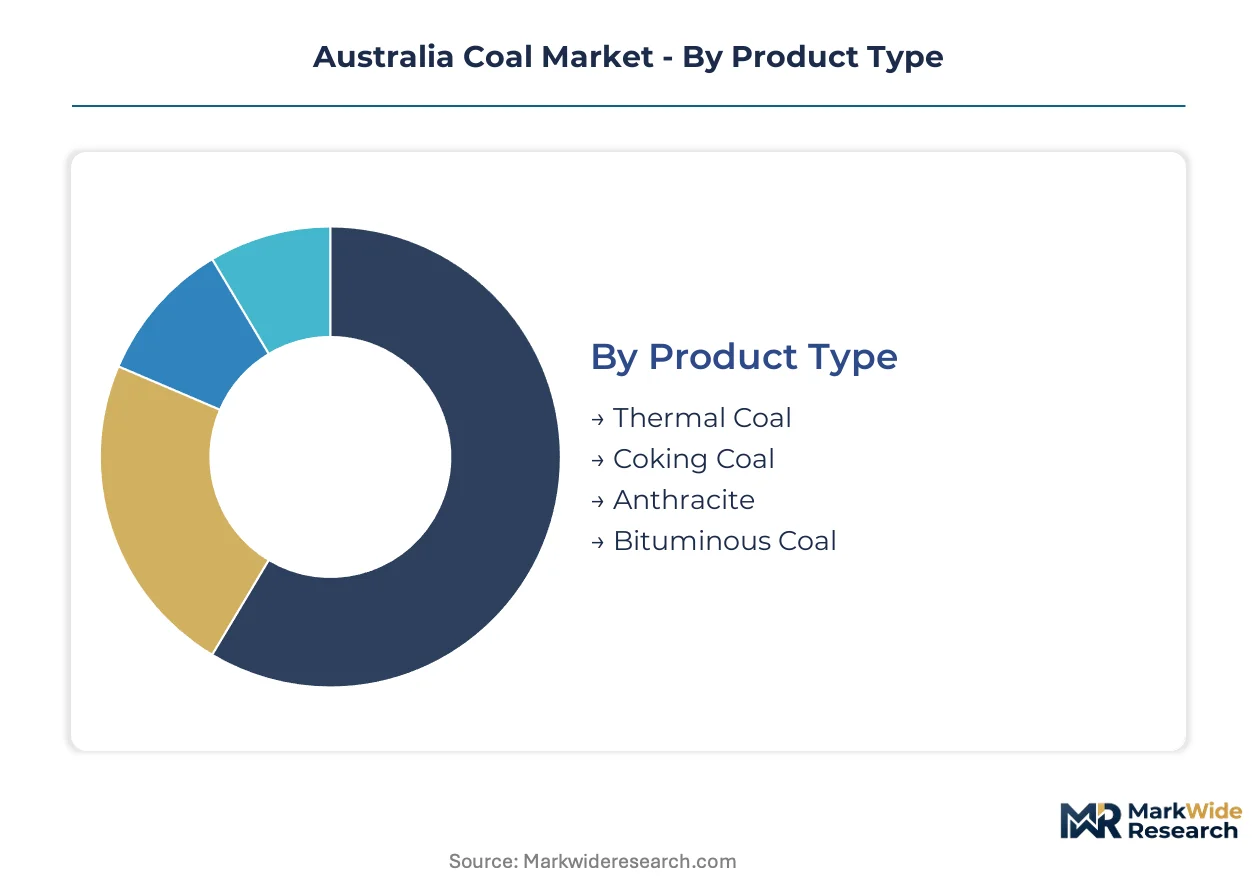
Segmentation in the Australia coal market reflects divergent regulatory pressures across product grades and end-use applications. The Clean Energy Regulator's Safeguard Mechanism applies differential baseline calculations depending on coal rank and combustion purpose. Understanding these divisions clarifies where capital is concentrating versus retreating.
Product Type:
The Clean Energy Regulator calibrates Safeguard Mechanism baselines by coal rank, with metallurgical grades attracting less stringent treatment per unit value than thermal products.
- Thermal Coal:Lower-rank sedimentary deposits with calorific values typically below 6,000 kcal/kg, combusted for electricity generation. Queensland and New South Wales power utilities absorb domestic volumes, though National Electricity Market demand is structurally compressing as grid-scale solar and wind displace baseload fossil capacity.
- Coking Coal:Premium hard coking varieties from Queensland's Bowen Basin exhibit specific plasticity and coke strength indices essential for blast furnace feed. Japanese and Korean steel mills lock in long-haul contracts to secure supply before alternative reducing agents mature, preserving price premiums.
- Anthracite:Highest-rank coal with elevated carbon density and minimal volatile matter, suited for metallurgical blending and specialized industrial applications.
- Bituminous Coal:Intermediate-rank deposits serving both thermal and metallurgical markets depending on specific quality parameters and preparation plant configuration.
Established volume favors thermal coal; emerging adoption favors coking coal.
End User:
Customer type determines compliance burden intensity, with facilities above Safeguard Mechanism thresholds facing escalating credit acquisition obligations.
- Power Generation:Grid-connected utilities in Queensland and New South Wales face acute renewable substitution pressure. The National Electricity Market's solar and wind additions are structurally displacing baseload thermal demand.
- Steel Manufacturing:Japanese and Korean blast furnace operators anchor export demand for hard coking coal. Direct equity stakes in Bowen Basin mines are displacing traditional quarterly price negotiations.
- Cement Production:Clinker kilns require consistent high-calorific feedstocks, with Australian operations sourcing domestically for process heat requirements.
- Chemical Industry:Coal-to-chemicals facilities utilize carbon feedstocks for ammonia, methanol, and synthetic fuel production, though scale remains limited in Australia.
Steel manufacturing commands margin concentration; power generation faces demand erosion.
Distribution Channel:
Supply chain configuration reflects customer scale and geographic proximity to production basins.
- Direct Sales:Large-volume contracts link Bowen Basin producers directly to Japanese and Korean steel mills, preserving price discovery mechanisms for premium hard coking tiers.
- Distributors:Intermediate traders aggregate smaller volumes for industrial boiler customers and regional power utilities lacking scale for direct mine offtake.
- Online Sales:Digital procurement platforms facilitate spot market transactions for standardized thermal products, though penetration remains limited relative to physical contract structures.
- Export Markets:Port capacity at Hay Point and Abbot Point decongests bottlenecks for international shipments, with throughput gains lifting realized prices for Queensland operators.
Direct sales anchor value capture; export infrastructure expansion enables volume growth.
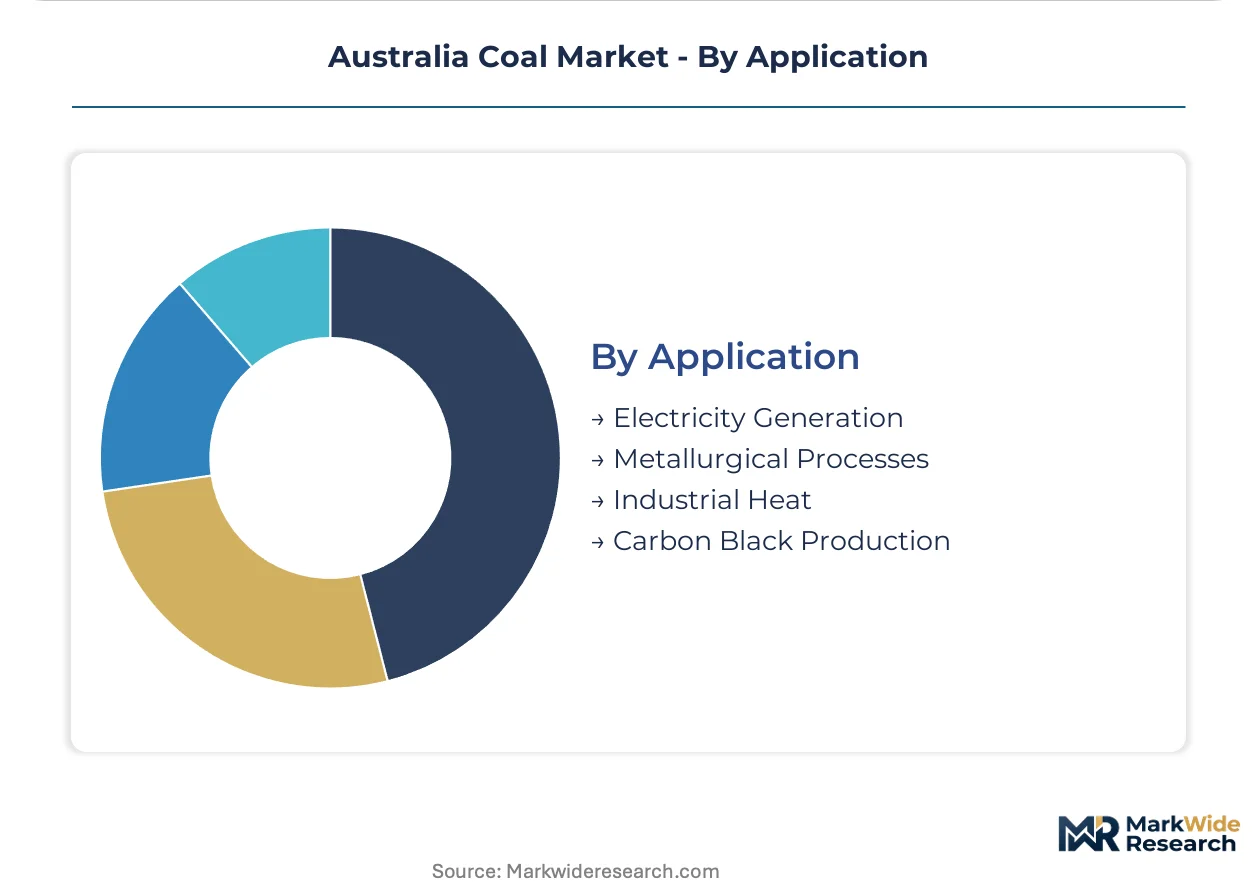
Application:
End-use application aligns coal rank with specific thermal or chemical process requirements.
- Electricity Generation:Pulverized coal combustion in Queensland and New South Wales power stations faces structural displacement from renewable grid additions.
- Metallurgical Processes:Blast furnace coke production consumes hard coking coal with precise rheological properties, with Bowen Basin seams commanding global premium pricing.
- Industrial Heat:High-CV, low-ash thermal products serve Asian industrial boilers outside the renewable-exposed electricity sector, capturing pricing premiums.
- Carbon Black Production:Feedstock oils and coal-derived carbon sources supply tire and pigment manufacturing, though this application represents a minor volume share domestically.
Metallurgical processes sustain premium pricing; electricity generation confronts substitution headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Clean Energy Regulator anchors Queensland's compliance framework, with state environmental authorities layering additional bonding and water licensing conditions across production basins. Sub-regional dynamics diverge sharply between metallurgical coal provinces and thermal-exposed zones.
Queensland
Bowen Basin hard coking coal sustains export economics through Japanese and Korean steel mill contracts. The Department of Environment and Science mandates progressive rehabilitation bonds that escalate with mine life extension. Hay Point and Abbot Point port clusters enable throughput gains that lift realized prices for regional operators.
New South Wales
Hunter Valley thermal operations pivot toward high-CV industrial boiler feed as National Electricity Market demand compresses. The state's Environmental Protection Agency imposes air quality offset requirements on mine expansions. Newcastle port infrastructure handles diversified product flows for Asian industrial customers.
Western Australia
Collie Basin thermal deposits face acute displacement pressure from grid-scale solar and wind additions. The Western Australian Environmental Protection Authority applies cumulative impact assessments to groundwater extraction permits. Domestic power utilities absorb shrinking volumes as the South West Interconnected System diversifies.
Victoria
Latrobe Valley brown coal operations confront structural demand erosion from renewable substitution. The Environment Protection Authority Victoria administers greenhouse gas discharge limits on power generation facilities. Loy Yang and Yallourn power station clusters face accelerated closure timelines under state energy transition policies.
Australia Coal Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Australia coal sector. Diversified mining majors with integrated logistics capabilities occupy distinct competitive positions from pure-play thermal specialists. Three archetypes dominate: integrated diversified miners with autonomous operations, pure-play coking coal developers with direct mill relationships, and Chinese-backed scale operators with parent-company capital access. Competitive intensity concentrates on selective mining automation and carbon credit hedging strategies.
Within the diversified mining tier, BHP Group Ltd and Glencore exemplify operational scale and metallurgical asset concentration. Among pure-play developers, Whitehaven Coal Limited occupies a position emphasizing high-CV thermal and coking product flexibility. Yancoal Australia Ltd represents Chinese capital-backed scale maintenance across Hunter Valley operations. These three anchors illustrate divergent strategic responses to Safeguard Mechanism compliance costs and export market segmentation.
| Leading Market Players |
|---|
| BHP Group Ltd |
| Yancoal Australia Ltd |
| Whitehaven Coal Limited |
| Glencore |
| Centennial Coal Company Ltd |
| Bloomfield Collieries Pty Ltd |
| Washington H. Soul Pattinson |
| New Hope Corporation |
| MACH Energy Australia |
| Others |
Value Chain & Pricing Dynamics
Australia's Clean Energy Regulator calibrates Safeguard Mechanism baselines by coal rank, simultaneously gating which deposits qualify for continued operation and stratifying price realization across metallurgical and thermal tiers. This regulatory architecture forces supply-side qualification to precede price differentiation, with compliant Queensland coking coal commanding structural premiums over thermal products exposed to renewable substitution.
Pricing Analysis
Queensland hard coking coal realizes substantial premia over New South Wales thermal products, with Bowen Basin seams attracting Japanese steel mill equity stakes that compress price volatility. Contract-based long-term offtake dominates premium metallurgical tiers, while spot-market exposure concentrates in standardized thermal grades. Price differentiation rests on coke strength indices and plasticity metrics for coking coal, with volume scale and transport cost arbitrage shaping thermal realizations. Cost compression in domestic power-exposed thermal runs through grid-scale solar additions. Asian industrial boiler buyers exhibit lowest price sensitivity; National Electricity Market utilities face acute margin pressure from renewable substitution.
Supply Chain Analysis
Inventory cycles at Hay Point and Abbot Point port clusters compress lead times for Bowen Basin export cargoes, while Hunter Valley rail bottlenecks extend working capital requirements for New South Wales operators. Supply concentrates in Queensland's metallurgical provinces and New South Wales thermal basins, with Western Australia's Collie deposits shrinking amid grid diversification. Raw material dependencies span diesel fuel for open-cut haulage, ammonium nitrate explosives, and steel grinding media for preparation plants. Single-source vulnerability concentrates in port capacity allocation for premium coking coal. Distribution runs through direct equity-linked contracts to Japanese and Korean mills, with distributor aggregation serving smaller Asian industrial boiler customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retiring pit supervisors and resource geologists are departing faster than Australian universities replenish graduate pipelines, creating a capability scarcity that constrains operational continuity across Queensland and New South Wales operations.
For Market Incumbents: Shield metallurgical asset margins through accelerated automation deployment and selective mining sensor integration that extracts coking zones from marginal thermal deposits. Acquire carbon credit forward positions to hedge Safeguard Mechanism compliance cost trajectories. Prioritize vertical integration into port capacity allocation at Hay Point to secure throughput certainty for Bowen Basin volumes. For New Entrants and Emerging Players: Differentiate on carbon intensity metrics by targeting gassy seam abatement technologies that generate offset revenue streams under Clean Energy Regulator protocols. White-space opportunity concentrates in Hunter Valley high-CV thermal pivot toward Asian industrial boilers outside renewable-exposed electricity sectors. Go-to-market leverage rests on direct mill relationships bypassing traditional quarterly price negotiations. For Investors and Strategic Acquirers: Safeguard Mechanism baseline decline trajectories reshape the acquisition landscape toward metallurgical-quality deposits with lower emissions per unit value. Long-term viability favors Queensland hard coking coal assets with Japanese equity-linked offtake structures. Signal to monitor: Japanese steel mill consolidation pace through direct mine stakes versus arm's-length contract revival.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Deployment | BHP's autonomous haulage fleets at Daunia compress unit costs and enable deeper seam extraction. |
| Carbon Credit Hedging | Forward credit purchases under the Safeguard Mechanism create compliance expenditure predictability for large facilities. |
| Port Capacity Integration | Equity stakes in Hay Point infrastructure decongest export bottlenecks and lift realized prices for Bowen Basin producers. |
| Selective Mining Technology | Real-time seam characterization sensors enable metallurgical zone extraction from marginal thermal deposits. |
| Direct Mill Equity Partnerships | JFE Steel and Nippon Steel minority positions displace quarterly negotiations with volume-certain sourcing models. |
Study Parameters
A spread of perspectives from mine operations managers, Clean Energy Regulator compliance officers, Japanese steel procurement directors, port logistics coordinators, and university mining engineering faculty converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from Queensland Department of Environment and Science licensing records, New South Wales Environmental Protection Agency air quality offset databases, National Greenhouse and Energy Reporting scheme disclosures, customs export statistics, and IEA coal market reports. Bottom-up reserve depletion schedules and top-down export demand projections were triangulated against facility-level production data.
Segmentation dimensions modeled span coal rank tier, end-use application, distribution channel structure, and regional regulatory framework across the projection horizon. CAGRs were derived from production-adjusted demand trajectories incorporating steel decarbonization timelines and renewable substitution elasticities. Industry-specific forecast inputs include Japanese blast furnace coke rate assumptions and Queensland port capacity expansion schedules.
Material uncertainties — Safeguard Mechanism baseline stringency revisions, Japanese steel mill procurement consolidation pace, and Hunter Valley rail infrastructure investment timing — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from regulatory, technological, or demand-side shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
UAE Chemical Logistics Market
Fuels
Fuel Conditioning System Market
Fuels
Gas Hydrates Market
Fuels
Asia-Pacific Commercial Aircraft Aviation Fuel Market
Fuels
Europe Renewable Aviation Fuel Market
Fuels
Gas Feed System Market
Fuels
Coal Briquettes Market
Fuels
India Coal Market
Fuels
Diesel Fuel Water Separator Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Gasoline Octane Improvers Market
Fuels
Compressed Natural Gas Market
Fuels
Global Turbine Oil Market
Fuels
Middle East and Africa Compressed Natural Gas Dispenser Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
Global Charcoal Market