
 Feeding Hopper Market | 2026-2036
Feeding Hopper Market Size, Share, and Industry Trends Forecast 2026-2036
Feeding Hopper Market Analytics
Buyer concentration across food processing and pharmaceutical packaging lines is rebalancing as mid-sized contract manufacturers expand capacity alongside established multinationals. Coperion leverages its twin-screw extrusion heritage to anchor high-throughput pneumatic hopper systems for plastics compounding. Schenck Process competes through gravimetric feeding precision in bulk material handling installations. GEA Group sustains dairy and pharmaceutical sector dominance with stainless-steel hygienic hopper designs that meet stringent clean-in-place protocols.
A feeding hopper is a containerized material handling device engineered with controlled discharge angles, typically constructed from carbon steel, stainless steel, or polymer composites, designed to meter bulk solids or liquids into downstream processing equipment. Mechanical hoppers lead unit volume through simplicity and abrasive material tolerance, while electronic hoppers capture margin pools via load-cell integration and real-time flow modulation. Sensor-activated technology is displacing manual feeding in pharmaceutical and food processing environments where batch consistency and contamination control determine compliance outcomes.
FDA sanitary equipment standards and EFSA material contact regulations shape stainless steel specification and surface finish requirements across North American and European installations. ISO 9001 quality management and CE marking directives govern structural integrity and electromagnetic compatibility for automated feeding systems exported into integrated EU production lines. Stakeholders must monitor evolving MDR traceability requirements as pharmaceutical hopper specifications tighten and sensor-activated architectures become default configurations in regulated end uses.
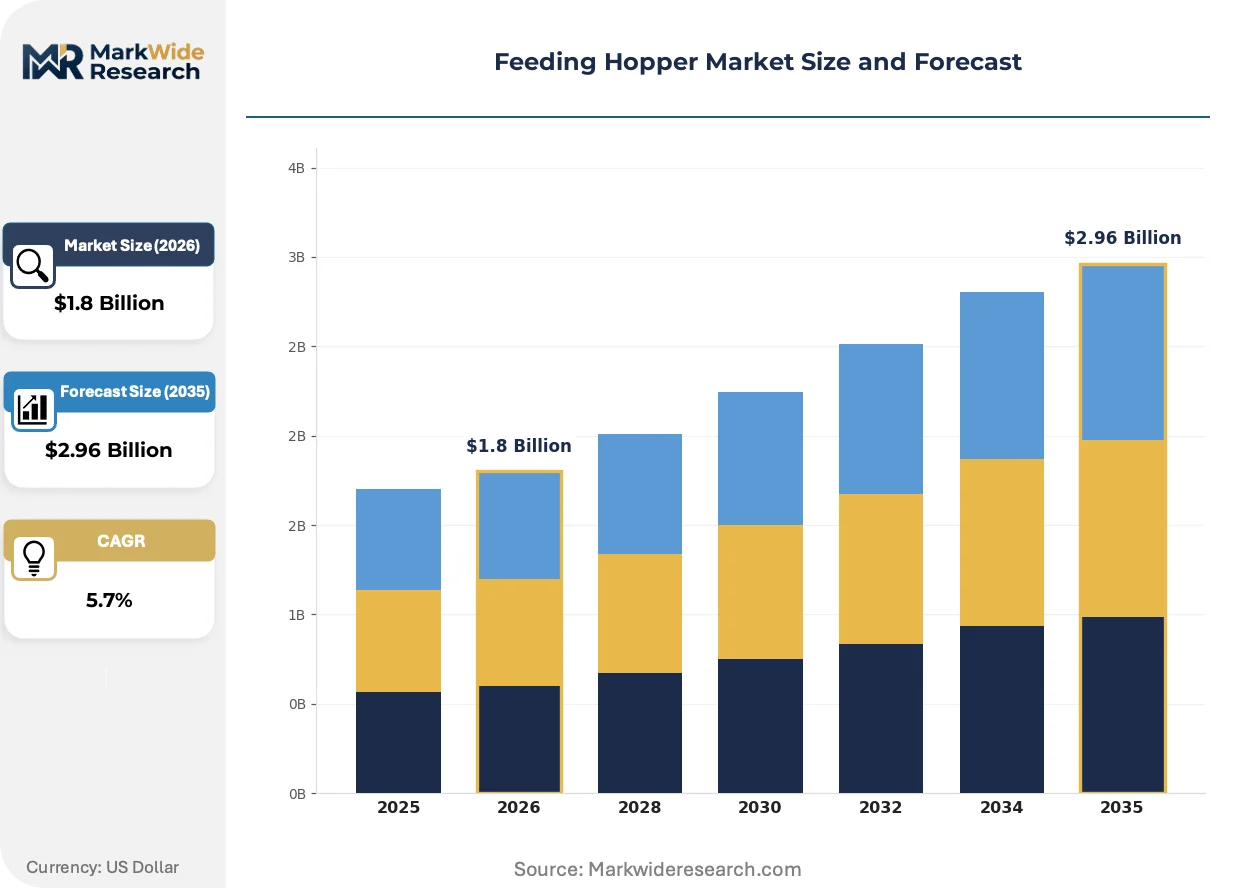
Market Dynamics
Automated bulk material handling systems are displacing manual feeding architectures across food processing and pharmaceutical packaging lines, driven by FDA and EFSA hygiene mandates that now require real-time contamination monitoring and batch traceability.
Growth Catalysts
- EFSA Material Contact Regulations:Stainless steel surface finish specifications for food-grade hoppers are tightening across European dairy processing plants, accelerating replacement cycles for legacy carbon steel installations.
- Sensor-Activated Flow Modulation:Load-cell integration enables real-time discharge control in pharmaceutical batching operations where dose precision determines compliance outcomes.
- German Precision Engineering Clusters:Integrated pneumatic and electronic hopper systems manufactured in Baden-Württemberg supply automated packaging lines across France, Italy, and the Netherlands.
Market Restraints
- Stainless Steel Price Volatility:Nickel and chromium input costs fluctuate with Indonesian and South African supply disruptions, compressing margins for hygienic hopper fabricators.
- Electronics Supply Concentration:Load cells and programmable logic controllers depend on concentrated Asian semiconductor fabrication, exposing European hopper OEMs to extended lead times.
- MDR Traceability Requirements:Medical Device Regulation documentation burdens for pharmaceutical hoppers extend certification timelines and raise compliance overhead for mid-sized suppliers.
Strategic Opportunities
- Modular Retrofit Architectures:Sensor-ready mechanical hoppers allow food processors in Poland and Czechia to upgrade existing lines without full capital replacement.
- CE Marking Alignment:Electromagnetic compatibility and machinery safety directives create competitive moats for EU-certified manufacturers exporting to integrated continental production networks.
- Convergence of Pneumatic Conveying and Gravimetric Feeding:Hybrid systems combine dilute-phase transport with loss-in-weight precision for plastics compounding applications in Belgium and Austria.
Industry Challenges
- Clean-in-Place Integration:Pharmaceutical hoppers must accommodate spray ball configurations and drainage validation protocols that complicate geometric design.
- Legacy System Interoperability:Electronic hoppers with fieldbus communication require protocol translation layers to interface with decades-old programmable controllers in established packaging facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feeding Hopper Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Hoppers, Pneumatic Hoppers, Electronic Hoppers, Gravity Hoppers End User: Agriculture, Food Processing, Pharmaceuticals, Plastics Technology: Automated Feeding, Manual Feeding, Sensor-Activated, Gravity Based Application: Bulk Material Handling, Animal Feed, Packaging, Waste Management |
| Companies Covered | Coperion, GEA Group, Schenck Process, Eriez Manufacturing, Festo, Gericke, Hapman, K-Tron, Movacolor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feeding Hopper Market Evolving Landscape
Real-time process control architectures are compressing the gap between material handling and quality assurance functions, embedding sensing and actuation directly into hopper discharge mechanisms rather than treating them as separate process stages.
Load-cell gravimetric feeding is consolidating position as the default architecture for pharmaceutical and high-precision food applications. Contract manufacturers serving multinational packaging lines specify loss-in-weight hoppers for 90% of new installations. This consolidation is compressing volumetric screw feeder margins to commodity levels while elevating sensor-integrated system pricing power.
EU MDR traceability mandates are reshaping documentation requirements for pharmaceutical hopper suppliers. Equipment must now carry unique device identifiers with lifecycle data accessible to notified bodies. German and Swiss manufacturers are responding by embedding RFID tags and cloud-connected maintenance logs directly into stainless-steel assemblies.
Buyer procurement patterns are fragmenting as mid-sized contract manufacturers gain technical sophistication and direct sourcing authority. These buyers now specify component-level interoperability standards rather than accepting turnkey vendor packages. The shift is most visible in Benelux dairy processing, where engineering departments design integrated lines from disaggregated pneumatic, electronic, and hygienic subsystems.
Feeding Hopper Market Segmentation
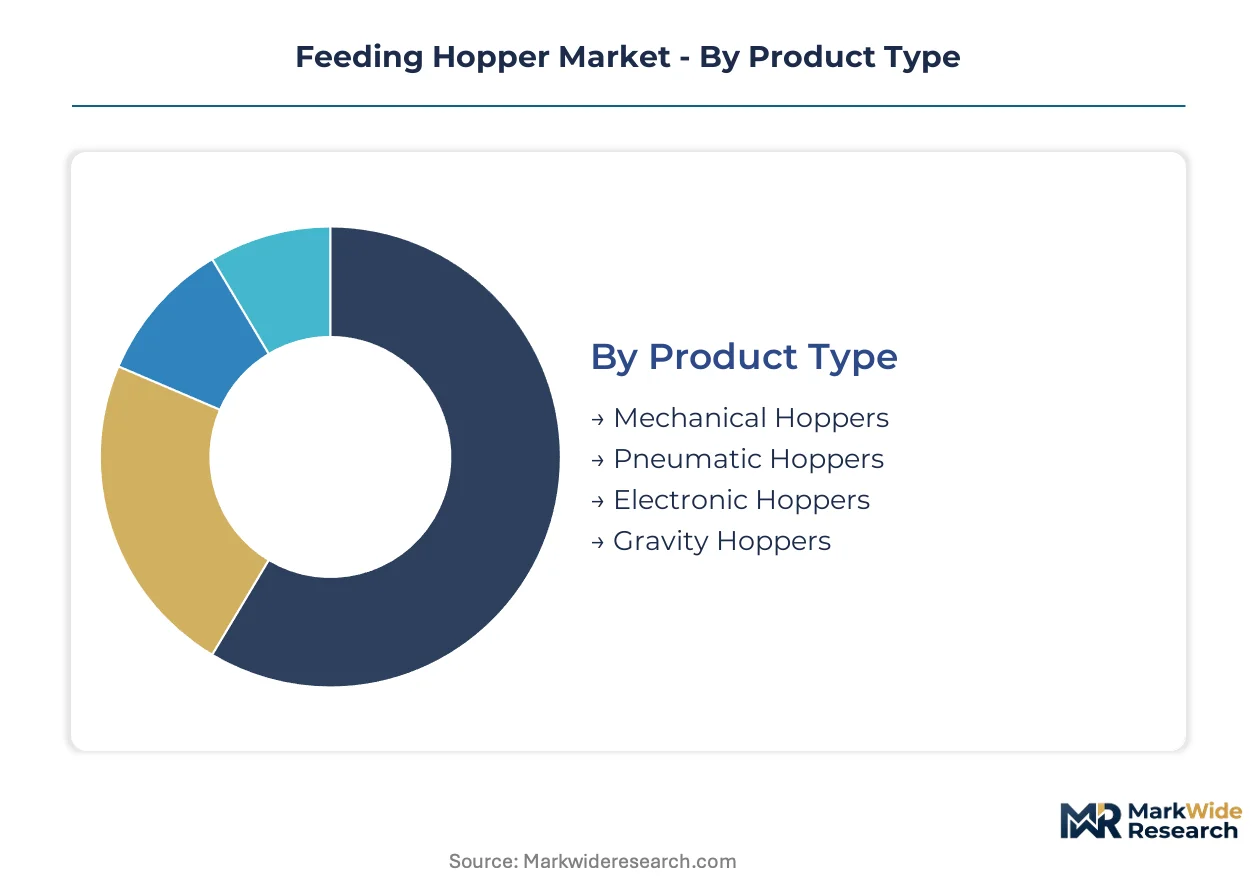
Feeding hopper segmentation reveals how technical specifications, regulatory requirements, and end-use precision demands fragment procurement patterns across European packaging lines and North American processing facilities.
Product Type:
Construction material and actuation mechanism define performance ceilings for abrasive tolerance, discharge precision, and clean-in-place compatibility.
- Mechanical Hoppers:Carbon steel or abrasion-resistant alloy construction handles mineral aggregates and construction feedstocks where particle hardness exceeds pneumatic system tolerance. German quarry operators specify these for limestone pre-crushing stages where electronic sensors would fail under dust loading.
- Electronic Hoppers:Load-cell integration enables real-time gravimetric discharge modulation for pharmaceutical batching where FDA dose precision mandates determine compliance. Swiss contract manufacturers specify these for 90% of new solid-dose packaging lines.
- Pneumatic Hoppers:Dilute-phase transport integration suits plastic pellet conveying in Belgian compounding facilities where material degradation from mechanical agitation must be minimized.
- Gravity Hoppers:Fixed-angle discharge geometry serves low-throughput agricultural grain storage where capital constraints override precision requirements.
Mechanical hoppers lead on scale; electronic hoppers lead on momentum.
End User:
Regulatory stringency and batch traceability requirements stratify equipment specification across sectors.
- Food Processing:Stainless steel surface finishes meeting EFSA material contact regulations dominate European dairy installations. Clean-in-place spray ball integration and drainage validation protocols constrain geometric design freedom.
- Pharmaceuticals:MDR traceability mandates require unique device identifiers and lifecycle data accessibility. RFID tags and cloud-connected maintenance logs embed directly into German and Swiss stainless-steel assemblies.
- Plastics:Abrasive filler handling and high-throughput compounding drive pneumatic-gravimetric hybrid specifications in Austrian injection molding feedstock preparation.
- Agriculture:Cost-sensitive grain and animal feed storage tolerates carbon steel construction with manual discharge gates in Polish cooperative facilities.
Food processing commands installed base; pharmaceuticals are climbing the fastest.
Technology:
Actuation architecture determines labor substitution potential and contamination control capability.
- Sensor-Activated:Photoelectric or capacitive level detection triggers automated refill cycles in pharmaceutical environments where human contact risks batch contamination. These systems are displacing manual architectures across FDA-inspected facilities.
- Automated Feeding:PLC-coordinated discharge sequences integrate with upstream batch management systems in Dutch dairy powder packaging where throughput consistency determines line efficiency.
- Gravity Based:Unpowered discharge relies on material flow characteristics alone, constraining application to free-flowing granules in low-value agricultural handling.
- Manual Feeding:Operator-controlled discharge persists in legacy Czech food processing lines where capital replacement cycles lag regulatory upgrade mandates.
Automated feeding holds dominant share; sensor-activated systems show steepest expansion trajectory.
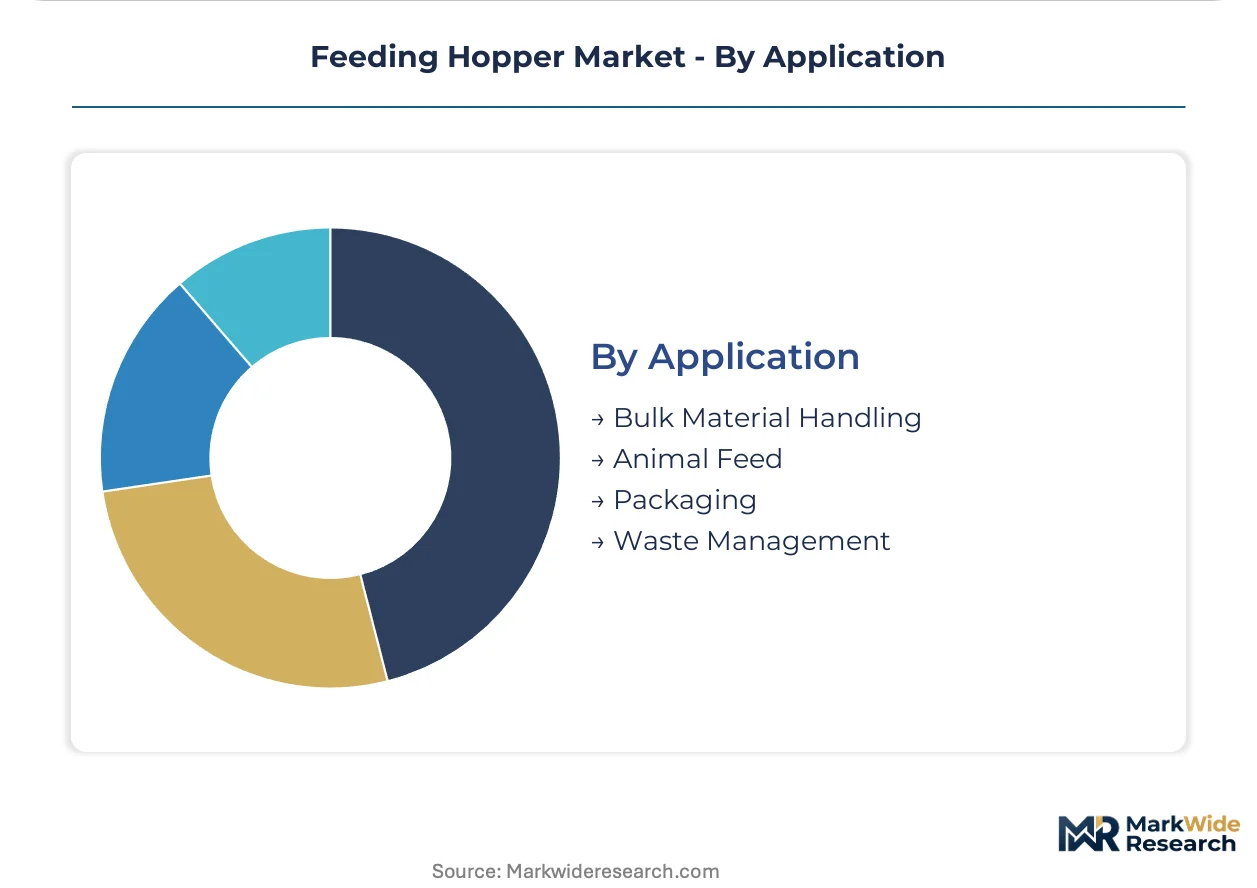
Application:
Material characteristics and downstream process integration requirements shape hopper geometry and discharge mechanism selection.
- Bulk Material Handling:High-capacity pneumatic conveying integration serves plastics compounding and mineral processing where tonnage throughput outweighs dose precision. Schenck Process and Coperion anchor this specification tier.
- Packaging:Loss-in-weight gravimetric feeding dominates pharmaceutical and precision food applications where batch consistency determines regulatory compliance. Contract manufacturers specify these for integrated European packaging lines.
- Animal Feed:Coarse particle tolerance and moisture resistance define specifications for agricultural premix and supplement handling in French livestock nutrition facilities.
- Waste Management:Corrosion-resistant alloys and abrasion-tolerant liners handle municipal and industrial refuse streams in German recycling infrastructure.
Bulk material handling leads on scale; packaging leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters supply integrated pneumatic systems to European packaging lines, while the United States drives sensor-activated adoption through FDA enforcement of real-time contamination monitoring in pharmaceutical facilities.
Germany
Baden-Württemberg fabricators export stainless-steel hygienic hoppers to dairy processors in France and the Netherlands. EFSA material contact regulations tighten surface finish specifications, accelerating replacement of legacy carbon steel installations. Stuttgart-area engineering clusters specialize in CE-marked pneumatic-electronic hybrid systems for automated packaging integration.
United States
FDA sanitary equipment standards mandate load-cell integration for pharmaceutical batching operations where dose precision determines compliance outcomes. Wisconsin and Minnesota food processors expand automated bulk handling to meet evolving hygiene protocols. Chicago-area system integrators deploy sensor-activated architectures across FDA-inspected solid-dose packaging facilities.
Switzerland
Swissmedic traceability requirements drive RFID tag integration and cloud-connected maintenance logs in stainless-steel pharmaceutical hopper assemblies. Basel-region contract manufacturers specify loss-in-weight gravimetric feeding for 90% of new installations. Zurich-area precision fabricators anchor high-specification equipment supply to German and French packaging lines.
Belgium
Plastics compounding facilities in the Antwerp-Ghent corridor specify pneumatic-gravimetric hybrid systems for abrasive filler handling. CE marking alignment on electromagnetic compatibility creates competitive positioning for EU-certified manufacturers. Flemish engineering departments design integrated lines from disaggregated pneumatic, electronic, and hygienic subsystems.
China
GB standards on food contact materials shape stainless steel specification for domestic dairy and beverage processing expansion. Yangtze River Delta fabricators supply mechanical hoppers for mineral aggregate handling where electronic sensors fail under dust loading. Shanghai-area system integrators retrofit sensor-ready architectures onto legacy packaging lines.
Feeding Hopper Market Competitive Landscape
German producers anchor the premium-tier segment; Swiss and American specialists hold positions in precision pharmaceutical applications. The vendor base stratifies across three tiers: integrated engineering conglomerates with extrusion heritage, gravimetric feeding specialists with load-cell expertise, and regional stainless-steel fabricators serving hygienic protocols. Dominant competitive moves include modular retrofit architectures for legacy line upgrades and CE marking alignment for continental EU export positioning.
Among German-based engineering groups, Coperion leverages twin-screw extrusion heritage to represent high-throughput pneumatic system supply, while GEA Group occupies a position in dairy and pharmaceutical sector dominance through stainless-steel hygienic designs. Schenck Process exemplifies gravimetric feeding precision specialists competing in bulk material handling installations. These three anchors illustrate how technical specialization in actuation mechanisms and regulatory compliance creates defensible market positioning.
| Leading Market Players |
|---|
| Coperion |
| GEA Group |
| Schenck Process |
| Eriez Manufacturing |
| Festo |
| Gericke |
| Hapman |
| K-Tron |
| Movacolor |
| Others |
Value Network & Pricing Analysis
Stainless steel input costs cascade from Indonesian nickel mines through Baden-Württemberg fabrication clusters to European dairy processors, compressing margins for hygienic hopper OEMs while elevating pricing power for sensor-integrated electronic systems.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for mechanical hoppers serving mineral aggregate handling. Three-tier pricing structure across premium sensor-activated, standard automated, and economy gravity-fed levels separates CE-marked European systems from carbon steel alternatives. Price differentiation hinges on FDA/EFSA certification tier and load-cell integration depth. Cost compression in mechanical hopper tiers is intensifying because Polish and Czech buyers prioritize retrofit compatibility over full system replacement. Agricultural cooperatives exhibit highest price sensitivity; Swiss pharmaceutical contract manufacturers show least.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme and China's GB standard enforcement are reshaping sourcing patterns for stainless steel fabricators serving Asian dairy expansion. Supply concentrates in Germany, China, and Switzerland for precision-engineered assemblies. Raw material flows draw from Indonesian nickel, South African chromium, and Taiwanese semiconductor fabrication for load cells. Single-source vulnerability in Asian PLC and sensor chip supply exposes European OEMs to extended lead times. Distribution runs through system integrators in Stuttgart, Chicago, and Shanghai who bundle pneumatic, electronic, and hygienic subsystems for end-user packaging lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feeding hopper market functions as a geographic-arbitrage play where EFSA material contact regulations in Europe command 40-60% pricing premiums over GB-standard Chinese equivalents for comparable stainless steel throughput capacity.
For Market Incumbents: Lock in long-term nickel and chromium offtake agreements to buffer Indonesian and South African supply disruptions compressing hygienic hopper margins. Anchor sensor-activated system pricing power through exclusive load-cell integration partnerships with Taiwanese semiconductor distributors, defending against emerging Polish and Czech retrofit specialists undercutting on mechanical hopper replacements. For New Entrants and Emerging Players: Capture modular retrofit architectures in Poland and Czechia where food processors seek sensor-ready mechanical hoppers without full capital replacement. The most penetrable white-space sits in mid-sized Benelux dairy engineering departments specifying disaggregated pneumatic-electronic-hygienic subsystems rather than turnkey vendor packages. Lead with CE marking alignment and fieldbus protocol translation layers as primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where MDR traceability mandates extend certification timelines and raise compliance overhead beyond mid-sized supplier carrying capacity. Five-to-ten-year viability favors gravimetric feeding specialists with load-cell expertise or stainless-steel fabricators with embedded RFID and cloud-connected maintenance capabilities. Target acquisition archetype: German or Swiss precision engineering firms with twin-screw extrusion heritage and established pharmaceutical sector relationships. Watch FDA enforcement intensity on real-time contamination monitoring as inflection indicator for sensor-activated system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Sourcing | Indonesian mining partnerships buffer stainless steel fabricators against raw material volatility. |
| Sensor-Ready Modular Retrofit Launch | Polish and Czech food processors upgrade legacy lines without full capital replacement cycles. |
| CE Marking Alignment Program | Electromagnetic compatibility certification creates competitive moats for EU continental export positioning. |
| RFID-Enabled Traceability Integration | Swissmedic and MDR compliance embeds lifecycle data accessibility into pharmaceutical hopper assemblies. |
| Pneumatic-Gravimetric Hybrid System Development | Belgian and Austrian plastics compounding facilities combine dilute-phase transport with loss-in-weight precision. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German dairy processors, procurement leads at Swiss pharmaceutical contract manufacturers, maintenance directors at Belgian plastics compounding facilities, and aftermarket service heads at Baden-Württemberg OEMs with secondary validation from EFSA material contact regulation filings, FDA sanitary equipment guidance documents, SEC 10-K disclosures from listed engineering conglomerates, and customs trade data on stainless steel hopper exports. Bottom-up installation tracking and top-down market sizing triangulated volume estimates.
Segment-weighting approaches modeled mechanical, electronic, pneumatic, and gravity hopper architectures across food processing, pharmaceutical, plastics, and agricultural end uses, with technology tiers of sensor-activated, automated feeding, gravity-based, and manual systems layered throughout the projection horizon. CAGRs derived from elasticity modeling against regulatory enforcement timelines and capital expenditure patterns at European packaging line operators. Forecast inputs included nickel price volatility indices and semiconductor lead time surveys from Taiwanese fabrication facilities.
Indonesian nickel supply disruptions, South African chromium export restrictions, and Asian semiconductor fabrication bottlenecks are the dominant revision risks to installed base and replacement cycle assumptions. Forecasts reflect documented assumptions on regulatory enforcement intensity and capital availability at mid-sized contract manufacturers. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Grain Mill Grinder Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
Greenhouse Heaters Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
North America Electric Zero Turn Mower Market
Agricultural Equipment
Gardening Equipment Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Fly Trap Market