
 Animal Feed Mixer Market | 2026-2036
Animal Feed Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Feed Mixer Market Analytics
Skilled technician shortages across rural agricultural regions is unwinding delivery timelines for precision mixing equipment. Kuhn Group leverages its European manufacturing footprint to sustain parts availability in fragmented dealer networks. Muyang Group anchors its position through integrated engineering services that span feed mill design through commissioning. Andritz competes on scale with large-capacity horizontal mixer lines purpose-built for industrial dairies.
Animal feed mixers are mechanical blending systems that homogenize grain, protein meals, minerals, and additives into nutritionally complete rations, typically achieving coefficient of variation below five percent for micronutrient dispersion. Horizontal mixers dominate volume sales due to their throughput efficiency in continuous-flow operations, while vertical mixers retain share among smaller livestock farms where capital constraints favor simpler mechanical designs. Computerized technology is capturing margin pools through subscription-based formulation software that locks in recurring revenue beyond hardware sales.
The EPA regulates particulate emissions from feed processing facilities under Clean Air Act standards, while OSHA enforces grain handling safety protocols that shape mixer guarding and dust-control specifications. The EU Green Deal and F-Gas Regulation constrain refrigerant choices in integrated feed cooling systems, nudging manufacturers toward ammonia-based alternatives. Stakeholders must monitor how precision-livestock farming data standards coalesce, as interoperability between mixer controls and herd-management platforms will determine equipment replacement cycles.
Market Dynamics
Precision-livestock farming protocols are compressing replacement cycles for conventional batch mixers across commercial dairy and feedlot operations, forcing capital allocation toward sensor-integrated blending systems that synchronize with herd-management platforms.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:European livestock producers face binding sustainability targets that favor low-waste, batch-controlled feed systems with traceable ingredient provenance.
- Upper Midwest feedlot consolidation:Large-scale cattle finishing operations in Nebraska, Kansas, and Iowa are centralizing feed mill infrastructure, creating concentrated demand for high-throughput horizontal mixer capacity.
- Automated formulation software:Computerized ration optimization tools lock in recurring subscription revenue streams that extend equipment vendor relationships beyond hardware installation.
Market Restraints
- Stainless steel and alloy input volatility:Mixer fabrication depends on nickel and chromium prices that fluctuate with mining supply disruptions and export restrictions.
- Rural technician scarcity:Skilled service personnel shortages across agricultural regions extend commissioning timelines and defer preventive maintenance schedules.
- OSHA grain handling compliance:Dust-control and guarding specifications add engineering cost layers that disadvantage smaller fabricators lacking in-house safety certification expertise.
Strategic Opportunities
- India's dairy cooperative expansion:State-led milk federation growth creates demand for mid-capacity vertical mixers suited to village-level chilling plant integration.
- Ammonia-based cooling convergence:F-Gas Regulation phase-downs position natural refrigerant retrofits as a bundled service opportunity for European mixer-cooler integrated systems.
- Subscription telemetry models:Remote mixer performance monitoring via cellular IoT modules opens recurring revenue channels in fragmented dealer networks.
Industry Challenges
- Controls integration complexity:Proprietary communication protocols between mixer PLCs and third-party herd-management software create interoperability friction during facility upgrades.
- CE marking timeline compression:EU machinery directive conformity assessments for new batch-control features extend product launch schedules by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Feed Mixer Market |
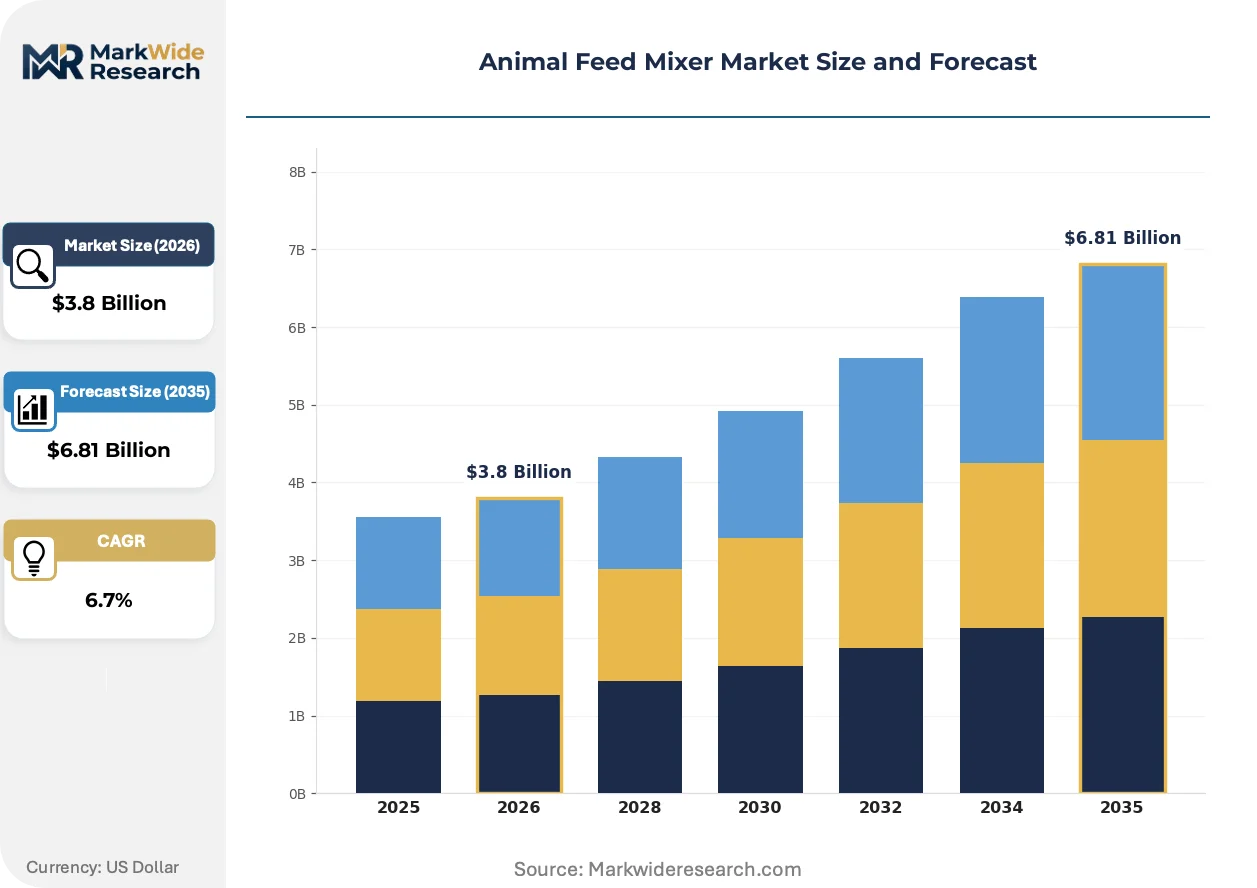
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Mixers, Vertical Mixers, Feed Pelleting Machines, Batch Mixers Technology: Computerized, Manual, Semi-Automatic, Automatic End User: Dairies, Poultry Farms, Livestock Farms, Aquaculture Sales Channel: Direct Sales, Distributors, Online Retailers, Manufacturers |
| Companies Covered | Kuhn Group, Trioliet B.V., Supreme International Limited, Muyang Group, Andritz, Faresin Industries, Bühler, NDEco (New Direction Equipment Co.), Seko Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Feed Mixer Market Evolving Landscape
Feed processing equipment is undergoing a hardware-software decoupling that separates mechanical blending platforms from formulation intelligence, reshaping how vendors capture lifetime customer value.
Near-infrared spectroscopy integration into mixer discharge chutes is bifurcating quality assurance workflows. Large integrated protein producers deploy real-time moisture and protein verification to eliminate laboratory bottlenecks. This capability compression is squeezing standalone analytical instrument suppliers out of the feed mill value chain.
REACH chemical authorization requirements for lubricants and hydraulic fluids used in feed-contact zones are forcing formulation changes across European-installed equipment bases. Manufacturers must qualify alternative grease compounds that maintain wear protection without SVHC classification. German and Dutch feed mill engineering firms are accelerating supplier audits to preempt downstream liability exposure.
Buying committees at multi-site livestock operations now unbundle after-sales service contracts from initial equipment procurement, selecting third-party maintenance providers through competitive tender. This disintermediation pressures OEM service margins in the US Upper Midwest, where independent technician networks have consolidated sufficient scale to challenge factory-authorized coverage. Dairy cooperatives in Wisconsin and Minnesota increasingly source spare parts through agricultural distribution cooperatives rather than direct manufacturer channels.
Animal Feed Mixer Market Segmentation
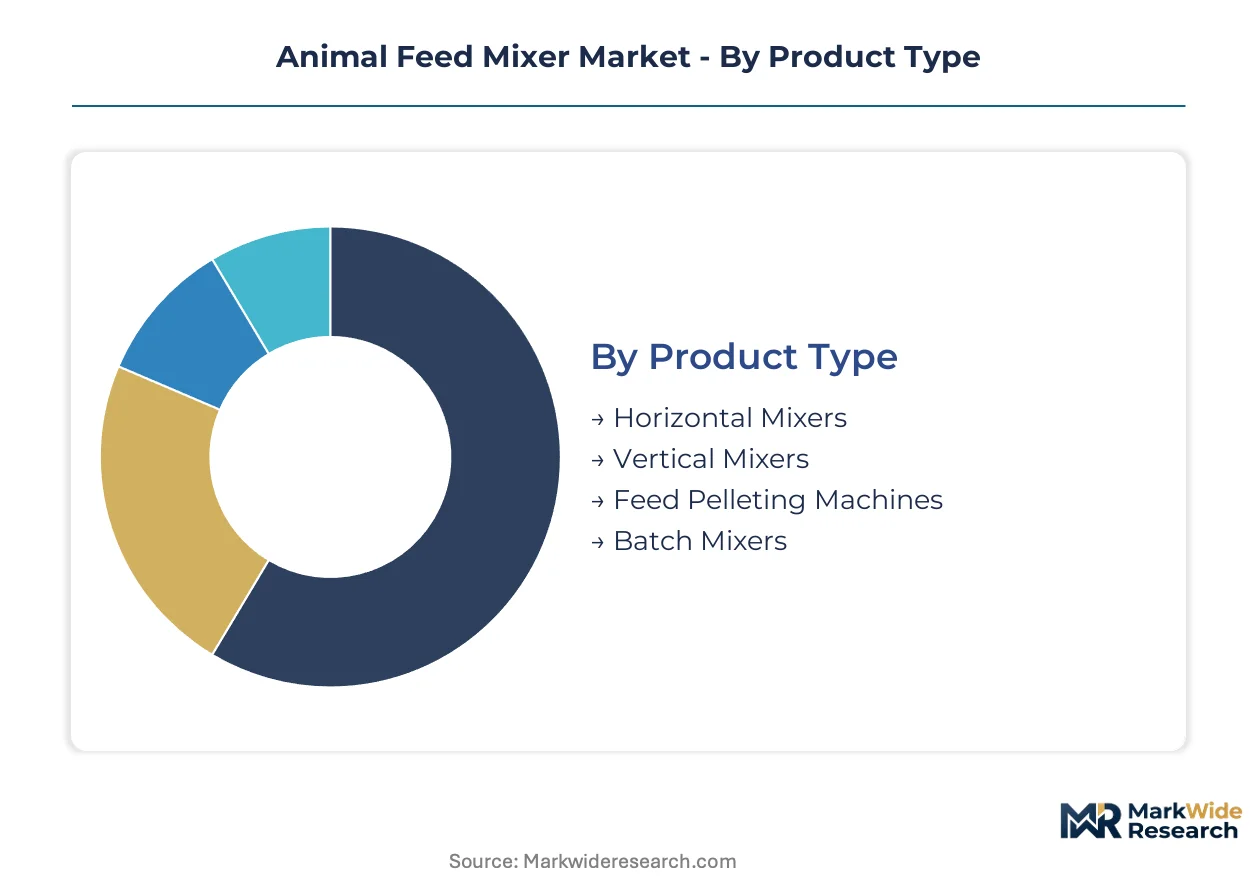
Feed mixer procurement patterns diverge sharply across operational scales and regulatory environments. Equipment specifications must align with herd size, labor availability, and precision-feeding mandates that vary by livestock category and geography.
Product Type:
Horizontal mixers dominate export shipments to large integrated operations, while vertical mixers serve fragmented domestic farm bases where capital constraints limit mechanization.
- Horizontal Mixers:These systems employ rotating paddle or ribbon augers within elongated troughs to achieve continuous-flow throughput exceeding 20 tons per hour. Demand concentrates in Nebraska, Kansas, and Iowa cattle feedlots where centralized feed mill consolidation requires industrial-scale blending capacity. The EU Green Deal's batch-traceability mandates are accelerating replacement of aging horizontal lines with sensor-equipped models.
- Vertical Mixers:Upright auger designs lift and cascade ingredients for smaller batch sizes suited to modest herd operations. Dairy cooperatives across Wisconsin and Minnesota favor these units for their mechanical simplicity and lower technician dependency. Capital constraints at family-scale livestock farms sustain domestic manufacturing footprints for this segment.
- Feed Pelleting Machines:Compression extrusion systems that densify mixed rations for transport efficiency and reduced feed waste.
- Batch Mixers:Discrete-load systems enabling precise ingredient sequencing for medicated feed compliance and ration customization.
Horizontal mixers hold the largest share; momentum sits with batch mixers as precision-livestock protocols expand.
Technology:
Automation intensity correlates with labor cost structures and herd management software adoption rates across end-use segments.
- Computerized:Integrated PLC systems with formulation software, load cell accuracy, and telemetry connectivity. Large integrated protein producers in the Upper Midwest deploy these platforms to synchronize mixing protocols with herd-management databases. Subscription-based software licensing extends vendor relationships beyond hardware installation.
- Automatic:Programmable batch sequencing with minimal operator intervention for mid-scale operations bridging manual and fully computerized systems. European dairy installations under F-Gas Regulation compliance increasingly specify automatic controls for integrated cooling system coordination.
- Semi-Automatic:Operator-assisted loading with automated mixing cycles, prevalent in village-level chilling plant integrations.
- Manual:Basic mechanical agitation requiring direct labor oversight, retaining relevance in developing agricultural economies with surplus rural labor.
Computerized systems command premium positioning; automatic configurations are climbing the fastest as mid-tier operations upgrade from semi-automatic bases.
End User:
Dairy operations drive specification complexity through precision-feeding protocols, while poultry and aquaculture segments prioritize throughput efficiency and pellet durability.
- Dairies:Ration consistency directly impacts milk yield and component quality, demanding coefficient of variation below five percent for micronutrient dispersion. North American automated dairy operations are scaling mixing capacity to meet individual-cow feeding protocols. OSHA grain handling compliance shapes guarding and dust-control specifications for these installations.
- Poultry Farms:High-density operations require continuous-flow mixing to match rapid feed conversion cycles. Broiler integrators in the southeastern United States specify horizontal mixer lines with real-time moisture control.
- Livestock Farms:Cattle, swine, and sheep operations with diversified ration requirements favor flexible batch systems.
- Aquaculture:Specialized pelleting and extrusion needs for sinking and floating feed formulations in shrimp and finfish production.
Dairies hold the largest share; aquaculture represents the steepest expansion trajectory as intensive fish farming scales in coastal regions.
Sales Channel:
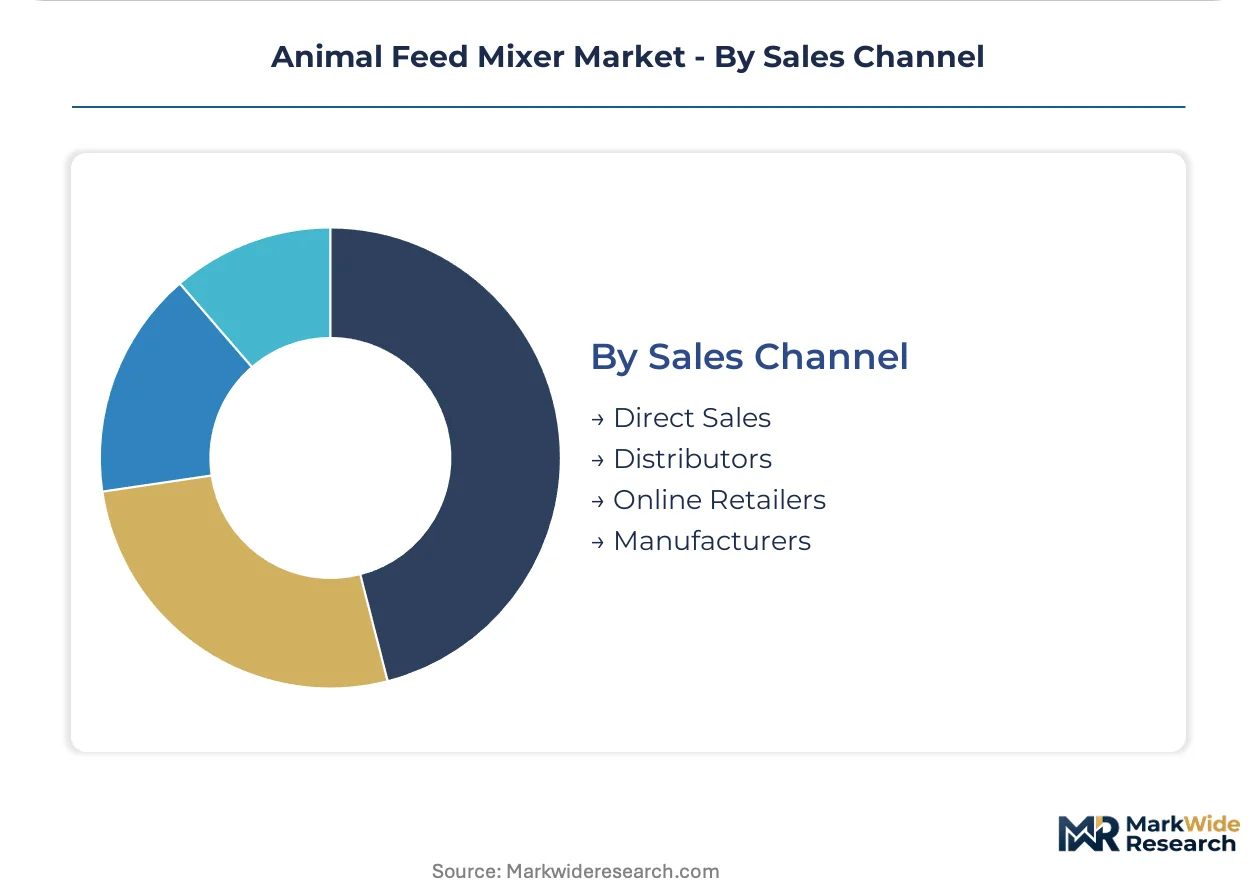
Channel selection reflects equipment complexity, service requirements, and procurement centralization trends among multi-site livestock operators.
- Direct Sales:Manufacturer-led specification and commissioning for large-capacity horizontal mixer installations. Kuhn Group and Andritz deploy direct sales engineers for integrated feed mill projects requiring customized layout design. Dairy cooperatives increasingly unbundle after-sales contracts from initial procurement through competitive tender processes.
- Distributors:Regional inventory and field service networks covering fragmented dealer territories. Independent technician networks in the Upper Midwest have consolidated sufficient scale to challenge factory-authorized coverage.
- Online Retailers:Parts and consumables procurement platforms for standardized components.
- Manufacturers:Factory-direct relationships for replacement equipment and facility expansions at existing customer sites.
Direct sales hold the largest share; distributor channels are gaining share fastest as procurement committees consolidate multi-site maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed mixer pricing power tilts toward European fabricators facing REACH compliance costs, while Upper Midwest US buyers leverage consolidated procurement volumes to compress supplier margins. Equipment specification divergence between these zones reflects contrasting regulatory stringency and operational scale.
United States
Cattle finishing operations across Nebraska, Kansas, and Iowa are centralizing feed mill infrastructure, driving concentrated demand for high-throughput horizontal capacity. OSHA grain handling standards shape guarding and dust-control specifications for new installations. Dairy cooperatives in Wisconsin and Minnesota increasingly unbundle after-sales contracts from initial procurement through competitive tender processes.
Germany
The EU Green Deal's farm-to-fork mandates push livestock producers toward batch-controlled systems with traceable ingredient provenance. REACH chemical authorization requirements for lubricants force formulation changes across installed equipment bases. Engineering firms in Baden-Württemberg and North Rhine-Westphalia accelerate supplier audits to preempt downstream liability exposure.
China
State-led dairy cooperative expansion creates demand for mid-capacity vertical mixers suited to village-level chilling plant integration. National feed safety standards under SAMR oversight tighten micronutrient dispersion requirements. Yangtze River Delta protein producers deploy sensor-integrated blending systems to synchronize with herd-management platforms.
Brazil
Integrated poultry and beef operations scale automated mixing capacity to match rapid feed conversion cycles. ANVISA medicated feed compliance drives specification complexity for batch sequencing systems. São Paulo and Minas Gerais house the dominant equipment procurement clusters for South American protein exports.
India
Milk federation growth under state cooperative programs generates demand for semi-automatic vertical mixers at chilling plant integration points. FSSAI feed safety regulations tighten ingredient traceability requirements. Gujarat and Maharashtra dairy cooperatives favor mechanically simpler designs that minimize technician dependency in rural deployment zones.
Animal Feed Mixer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. European engineering houses anchor the premium segment through integrated formulation software and telemetry connectivity, while Asian fabricators compete on capital efficiency for mid-scale operations. Three archetypes dominate: precision-livestock technology integrators, scale-driven horizontal mixer specialists, and regional vertical mixer fabricators serving fragmented farm bases. Consolidation pressure manifests through M&A activity among dealer networks and capacity expansion for ammonia-cooling-integrated system lines.
Among European-based engineering groups, Kuhn Group and Andritz occupy positions as precision-livestock technology integrators, exemplifying the premium-tier archetype through their manufacturing footprints and integrated service capabilities. Muyang Group anchors the scale-driven specialist tier, representing Chinese fabricators that compete on engineering breadth from feed mill design through commissioning. These three companies illustrate how geographic origin and organizational structure map to distinct competitive positioning within the technology-cost spectrum.
| Leading Market Players |
|---|
| Kuhn Group |
| Trioliet B.V. |
| Supreme International Limited |
| Muyang Group |
| Andritz |
| Faresin Industries |
| Bühler |
| NDEco (New Direction Equipment Co.) |
| Seko Industries |
| Others |
Value Network & Pricing Analysis
Twelve-to-sixteen-week delivery timelines for precision mixing equipment now govern capital planning cycles across North American dairy operations, compressing pricing power for European fabricators facing REACH compliance cost layers while amplifying buyer leverage in consolidated Upper Midwest procurement pools.
Pricing Analysis
Configured-to-order pricing for sensor-integrated horizontal mixer lines commands spreads exceeding standard vertical mixer configurations by margins reflecting software licensing tiers and telemetry bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation intensity, with computerized PLC systems anchoring premium positioning against semi-automatic mid-tier and manual economy offerings. Price differentiation hinges on certification grade—CE-marked batch-control features for EU Green Deal compliance versus OSHA-compliant guarding for US grain handling standards—and geographic delivery cost absorption for remote rural deployments. Pricing pressure stems from stainless steel and alloy input volatility, with nickel and chromium spot movements forcing margin compression across fabrication tiers. Dairy cooperatives in Wisconsin and Minnesota exhibit highest price sensitivity through competitive tender unbundling of after-sales contracts, while large integrated protein producers in Nebraska and Iowa demonstrate lowest sensitivity due to throughput efficiency premiums.
Supply Chain Analysis
Germany and the Netherlands anchor precision-livestock technology fabrication through engineering houses in Baden-Württemberg and North Rhine-Westphalia, while China concentrates mid-capacity vertical mixer production for village-level dairy cooperative deployment. Component sourcing draws from South Korean and Japanese sensor suppliers for PLC-integrated load cell systems, Italian gearbox specialists for horizontal mixer auger drives, and domestic steel mills for alloy trough fabrication. Supply chain risk centers on single-source vulnerability for near-infrared spectroscopy modules deployed in discharge chute quality assurance, with limited qualified vendors extending lead times during capacity constraints. Distribution runs through fragmented dealer networks in rural agricultural regions, challenged by skilled technician scarcity that extends commissioning timelines and creates openings for independent service network consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Animal feed mixer demand cycles track livestock herd expansion and precision-farming capital refresh patterns, with current replacement waves driven by EU Green Deal batch-traceability mandates forcing equipment turnover across European installed bases.
For Market Incumbents: Shield recurring revenue streams by deepening software subscription attach rates for formulation optimization tools, locking out third-party telemetry providers through proprietary PLC protocol integration. Prioritize backward integration into ammonia-based cooling system production to capture F-Gas Regulation retrofit bundling opportunities in European dairy installations. Consolidate dealer network scale through selective acquisition of independent technician networks in the Upper Midwest, where competitive tender processes threaten factory-authorized service margins. For New Entrants and Emerging Players: Differentiate on ammonia-refrigerant retrofit bundling for European horizontal mixer-cooler integrated systems, exploiting incumbent lag in natural refrigerant qualification. Target India's state-led milk federation expansion with semi-automatic vertical mixer offerings suited to village-level chilling plant technician scarcity. Penetrate through agricultural distribution cooperative channel partnerships rather than direct sales, mirroring Wisconsin and Minnesota dairy procurement pattern shifts. For Investors and Strategic Acquirers: Long-term, this sits as a precision-livestock data infrastructure play because mixer telemetry integration determines interoperability positioning within herd-management platform ecosystems. Acquisition focus should center on European engineering houses with REACH-compliant lubricant formulation capabilities and active supplier audit programs. Watch for coalescence of precision-livestock farming data standards as inflection signal, with protocol standardization triggering accelerated replacement cycles for proprietary-control legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures margin pools from Korean and Japanese PLC load cell suppliers while securing supply continuity. |
| Ammonia Cooling System Bundling | Positions European fabricators for F-Gas Regulation phase-down retrofit demand across German and Dutch dairy cooperatives. |
| Subscription Telemetry Model Launch | Extends vendor relationships beyond hardware installation through cellular IoT remote performance monitoring. |
| Dealer Network Consolidation | Challenges independent technician scale in Nebraska and Kansas feedlot territories through selective acquisition. |
| REACH-Compliant Lubricant Qualification | Preempts downstream liability exposure for European-installed equipment bases under ECHA chemical authorization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade data, and EU machinery directive conformity assessments, with input from feed mill engineering directors, agricultural distribution cooperative procurement managers, OEM aftermarket service heads, and dairy cooperative operations leads. Bottom-up equipment shipment analysis triangulates against top-down livestock herd capacity modeling across the projection horizon.
Segmentation dimensions modeled span product type, automation technology tier, livestock category end-use, and sales channel structure, with additional granularity on ammonia-cooling integration status for European regulatory compliance tracking. CAGRs derive from installed base replacement cycle compression analysis and precision-livestock farming adoption curve modeling, incorporating SAMR feed safety standard evolution in China and FSSAI traceability tightening in India as regional demand shapers.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement continuity and OSHA grain handling standard stability; material deviation in regulatory stringency or livestock commodity price cycles would warrant model refresh. Recalibration cycles align with material shifts in precision-livestock data standard coalescence and REACH chemical authorization timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Livestock Farm Equipment Market
Livestock Equipment
Livestock Panel Gates Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Automatic Hog Feeder Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Automated Feeding System Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Russia Horse Riding Equipment Market
Livestock Equipment
Robotics Milking Systems Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Poultry Feeder Market