
 Starter Feed Market | 2026-2036
Starter Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Starter Feed Market Analysis
Capital-intensity divergence between multinational compounders and regional blenders is bifurcating competitive dynamics in starter feed. Cargill Incorporated leverages integrated grain origination and captive amino acid production to sustain margin structures across North American poultry corridors. Charoen Pokphand Foods PCL anchors its position through backward integration into aquaculture hatcheries, controlling channel access across Thai and Indonesian shrimp farming clusters.
Starter feed denotes nutritionally dense formulations engineered for the first 7–21 days post-hatch or post-weaning, typically containing 22–24% crude protein, 1.2–1.5% lysine, and heat-processed soybean meal to maximize digestibility in immature gastrointestinal tracts. These rations serve to establish gut microbiome colonization, skeletal mineralization rates, and immune competence before transition to grower diets. Poultry feed and aquaculture feed represent the fastest-expanding product type categories, with shrimp and marine fish hatcheries demanding increasingly precise micronutrient payloads. Pellet durability and water stability in aquaculture applications command premium positioning, while mash and crumble forms dominate conventional broiler starter programs where cost minimization governs procurement decisions.
Feed safety frameworks including FDA's Food Safety Modernization Act preventive controls, EU Feed Hygiene Regulation 183/2005, and China's Ministry of Agriculture GB standards collectively elevate barrier costs for non-compliant suppliers. Veterinary drug residue monitoring through EU Reference Laboratories and FDA's Veterinary Feed Directive restricts antibiotic growth promoter inclusion, redirecting R&D toward phytogenic and probiotic additive categories. Stakeholders must monitor evolving maximum residue limits and novel feed additive authorization pathways to preserve market access across jurisdictions.
Market Dynamics
The EU Green Deal's feed-to-food sustainability mandates are compressing formulation timelines and elevating compliance costs across compound feed operations, forcing simultaneous reformulation of protein sources and micronutrient density specifications.
Growth Catalysts
- Broiler integration in Vietnam:Mekong Delta poultry zones are consolidating under vertically coordinated contract farming models that standardize early-stage nutrition protocols and lock in starter feed offtake volumes.
- EU Feed Hygiene Regulation 183/2005:Mandatory HACCP-based hazard analysis across feed manufacturing facilities is professionalizing quality assurance and disqualifying informal blenders from formal supply chains.
- Precision aquaculture hatcheries:Shrimp and marine fish operations in Thailand and Indonesia are specifying water-stable micro-extruded diets with exacting lysine-to-energy ratios for larval survival optimization.
Market Restraints
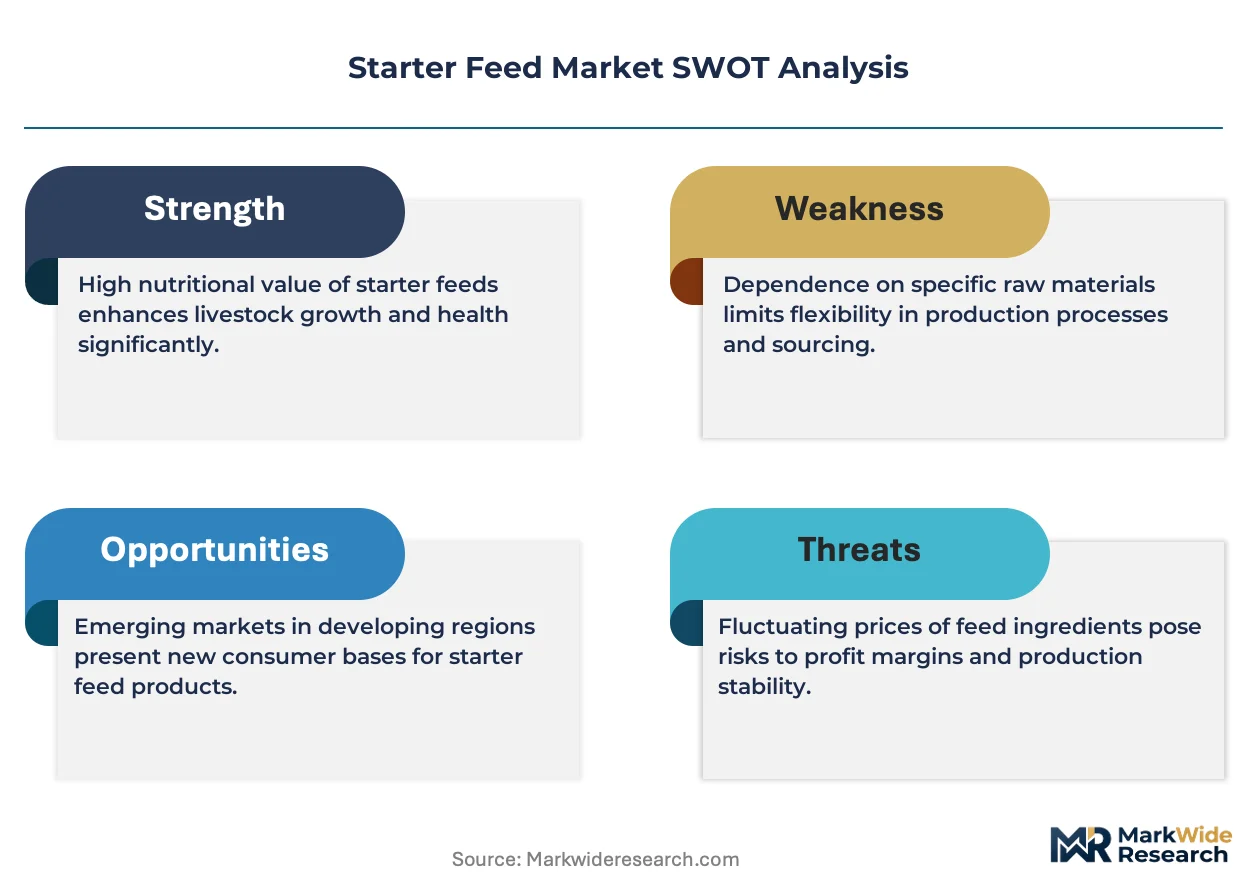
- Soybean meal price volatility:Heat-processed soybean meal constitutes 35-45% of starter formulations, exposing margin structures to Chicago Board of Trade futures swings and Argentine export tax policy shifts.
- Veterinary drug residue monitoring:EU Reference Laboratories and FDA's Veterinary Feed Directive enforce zero-tolerance antibiotic growth promoter protocols, requiring costly alternative additive validation.
- Single-source amino acid dependence:Lysine and methionine supply concentrates among three multinational fermentation producers, creating input bottleneck risks during logistics disruptions.
Strategic Opportunities
- Phytogenic additive authorization:EFSA's novel feed additive pathway offers first-mover advantages for botanical extract suppliers demonstrating gut health benefits in immature gastrointestinal tracts.
- Recirculating aquaculture systems:Indoor salmon and trout hatcheries in Norway and Scotland demand precision-formulated starter diets with extended water stability and reduced nitrogen leaching profiles.
- Direct-to-farm digital platforms:Vietnamese and Indonesian poultry integrators are bypassing traditional distributor networks through mobile-ordering applications that aggregate smallholder demand.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in immature digestive physiology and gut microbiome modulation commands premium compensation, constraining R&D team expansion at mid-tier compounders.
- Dual certification timelines:Simultaneous pursuit of FAMI-QS and GMP+ feed safety certifications extends market entry timelines by 18-24 months for new manufacturing facilities.
- Pellet durability testing standardization:Inconsistent tumble-drum protocols across ISO, ASAE, and regional standards create specification mismatches between contract hatcheries and feed suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starter Feed Market |
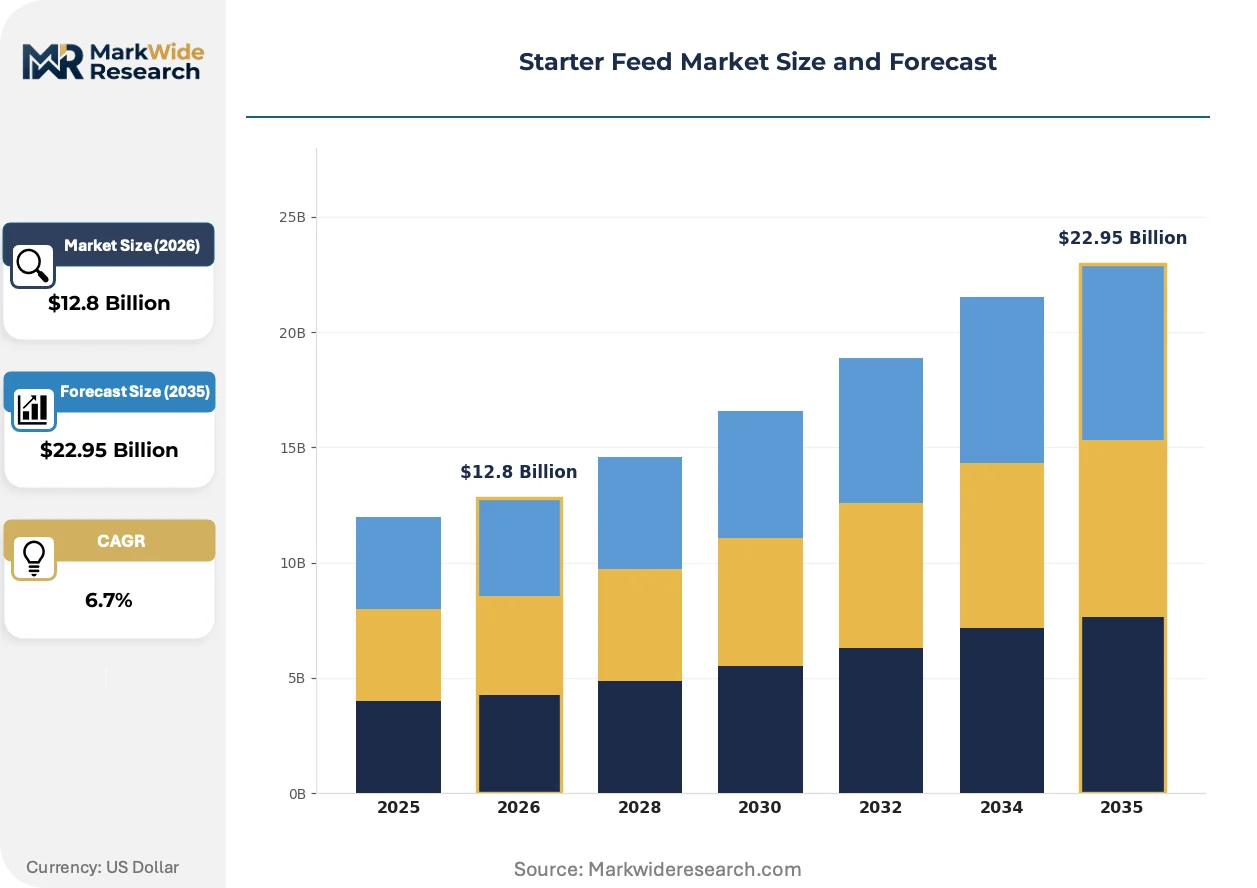
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry Feed, Swine Feed, Ruminant Feed, Aquaculture Feed Ingredient: Protein Sources, Energy Sources, Vitamins & Minerals, Additives Form: Pellets, Crumbles, Mash, Liquids Packaging Type: Bags, Bulk, Totes, Boxes |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Alltech Inc, Evonik Industries AG, Nutreco, Land O'Lakes Inc, De Heus Voeders, Charoen Pokphand Foods PCL, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starter Feed Market Emerging Trajectories
Starter feed formulation is pivoting from commodity protein substitution toward functional additive integration, with microbiome-targeted ingredients and processing technologies commanding disproportionate R&D investment relative to conventional nutrient density optimization.
Precision fermentation-derived single-cell proteins are fragmenting conventional fishmeal and soybean meal inclusion rates in marine fish and shrimp starter diets. Norwegian salmon hatcheries and Vietnamese pangasius nurseries are piloting bacterial biomass and algal protein concentrates at 15-30% substitution levels. This protein source diversification is fragmenting long-term supply contracts with commodity oilseed processors and compressing price discovery mechanisms in regional spot markets.
EU F-Gas Regulation phase-down schedules are accelerating adoption of mechanical vapor recompression and heat pump technologies in feed pelleting operations. Industrial consequence includes 40-60% reduction in thermal energy intensity for extrusion processes, though capital retrofit requirements disadvantage smaller regional blenders. Poultry-dominant markets in Poland and Spain are responding fastest due to integrated energy-carbon cost accounting under national decarbonization frameworks.
Certification-driven procurement preferences are displacing spot-market purchasing among Southeast Asian contract growers. Thai broiler integrators and Indonesian shrimp farming clusters now mandate FAMI-QS or equivalent third-party verification as a condition of supply relationship continuation. This behavioral shift concentrates volume among accredited compounders and marginalizes informal blenders in Vietnam's Mekong Delta and Java's coastal aquaculture zones.
Starter Feed Market Segmentation
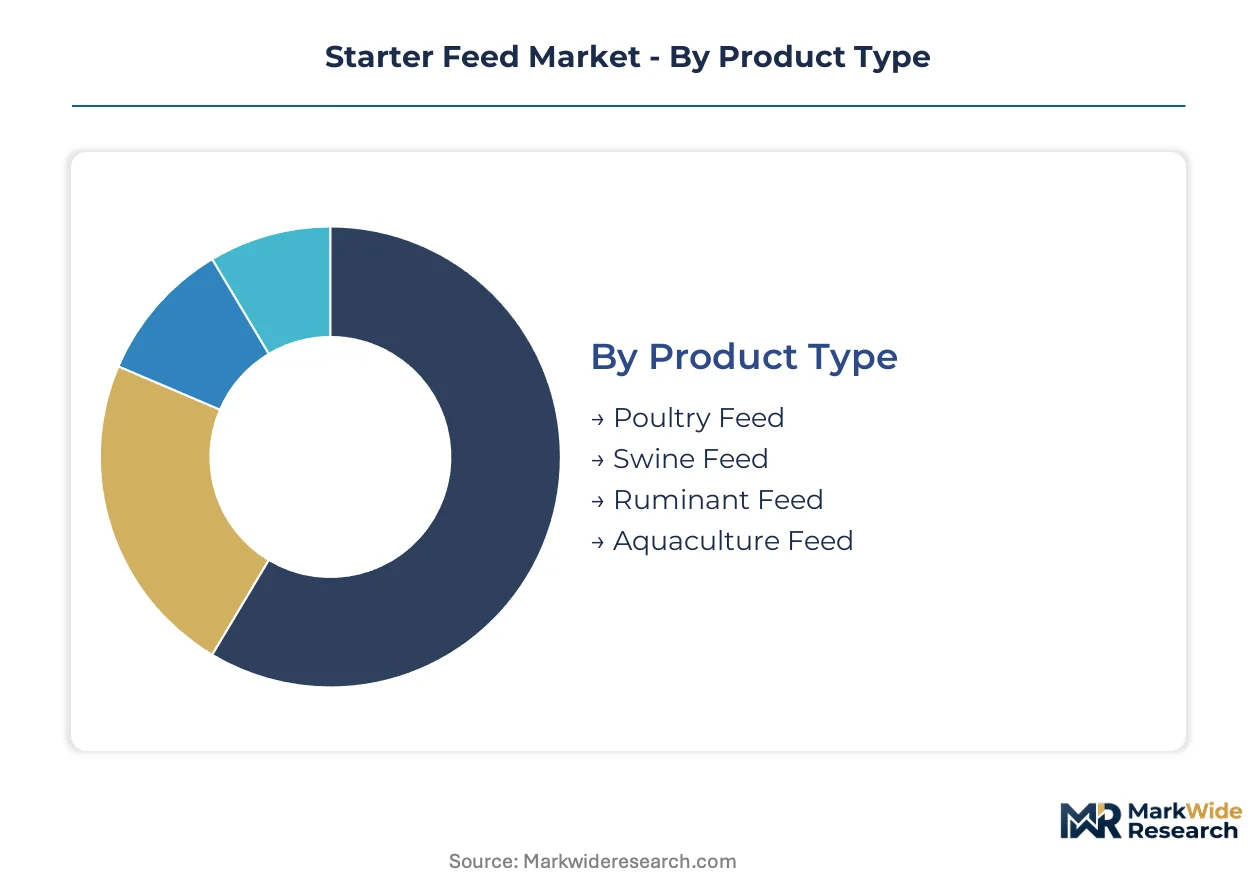
Starter feed segmentation reveals divergent margin architectures across species-specific physiology requirements, ingredient functional hierarchies, and processing intensity tiers. Procurement patterns cluster around form factors that balance digestibility optimization against manufacturing capital recovery timelines.
Product Type:
Margin pools concentrate in species where early-stage mortality carries the highest replacement cost and where integrators mandate certified nutrition protocols.
- Poultry Feed:Formulations targeting broiler chicks and layer pullets carry 22-24% crude protein with heat-processed soybean meal as the primary nitrogen source. Vietnamese Mekong Delta contract farming clusters now standardize these rations across vertically coordinated operations, locking in volume commitments that sustain compounder margin structures.
- Aquaculture Feed:Water-stable micro-extruded diets for shrimp and marine fish larvae command premium positioning through lysine-to-energy precision and extended submersion integrity. Thai and Indonesian hatcheries specify these formulations for larval survival optimization, with pellet durability testing protocols varying across ISO and ASAE standards.
- Swine Feed:Post-weaning piglet diets emphasize gut microbiome establishment through acidification and prebiotic inclusion at lower inclusion rates than poultry equivalents.
- Ruminant Feed:Calf starter rations prioritize rumen papillae development through physically effective fiber and gradual concentrate transition protocols.
The dominant share belongs to poultry feed, while aquaculture feed is closing the gap fastest.
Ingredient:
Cost tier differentiation separates commodity protein inputs from functional additive categories where patent protection and regulatory authorization create pricing power.
- Protein Sources:Heat-processed soybean meal constitutes 35-45% of conventional formulations, with precision fermentation-derived single-cell proteins now substituting at 15-30% in Norwegian salmon and Vietnamese pangasius hatcheries. This fragmentation is compressing long-term oilseed processor contracts and regional spot market price discovery mechanisms.
- Additives:Phytogenic botanical extracts and probiotic cultures are redirecting R&D investment as FDA's Veterinary Feed Directive and EU Reference Laboratory protocols enforce zero-tolerance antibiotic growth promoter restrictions. EFSA's novel feed additive pathway offers first-mover advantages for suppliers demonstrating gut health benefits in immature gastrointestinal tracts.
- Energy Sources:Extruded corn and wheat middlings provide metabolizable energy density calibrated to species-specific digestive enzyme maturation timelines.
- Vitamins & Minerals:Micronutrient premixes target skeletal mineralization rates and immune competence establishment during the 7-21 day critical window.
Protein sources retain volume leadership, though additives are gaining share fastest through regulatory-driven substitution dynamics.
Form:
Processing capital intensity and durability testing standardization gaps create specification mismatches between contract hatcheries and regional blenders.
- Pellets:Extruded forms for aquaculture applications command water stability premiums through mechanical vapor recompression and heat pump technologies that reduce thermal energy intensity 40-60%. EU F-Gas Regulation phase-down schedules are accelerating adoption in Polish and Spanish poultry corridors.
- Crumbles:Intermediate particle sizes dominate conventional broiler starter programs where cost minimization governs procurement decisions and mash-to-pellet transition timing optimizes feed conversion ratios.
- Mash:Unprocessed blends serve early-stage poultry where gizzard development benefits from structural fiber presence.
- Liquids:Emulsified formats for precision delivery in recirculating aquaculture systems enable exact micronutrient dosing in Norwegian salmon and Scottish trout indoor hatcheries.
Pellets hold the largest share position, while liquids are expanding most quickly through RAS hatchery specification trends.
Packaging Type:
Logistics configuration and contamination risk profiles determine procurement preferences across integrated operations versus independent grower networks.
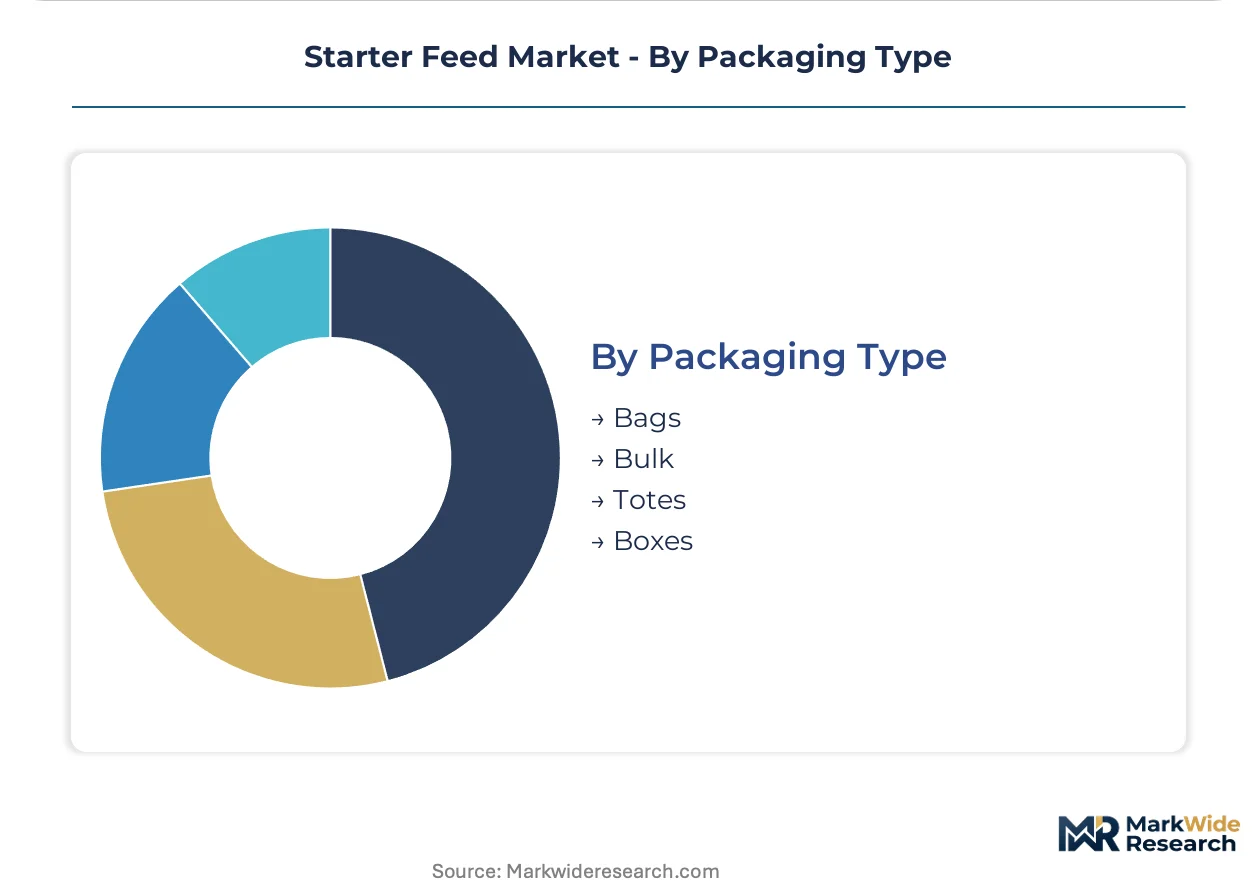
- Bulk:Tanker and pneumatic delivery systems serve vertically integrated poultry complexes in Vietnam and Thailand where FAMI-QS certification is now mandatory for supply relationship continuation. This behavioral shift marginalizes informal blenders lacking accredited quality assurance infrastructure.
- Bags:25-50kg woven polypropylene remains standard for smallholder aggregation through Indonesian mobile-ordering platforms that bypass traditional distributor networks.
- Totes:Intermediate bulk containers reduce handling labor in mid-scale aquaculture operations with limited silo storage capacity.
- Boxes:Corrugated formats protect pellet integrity in specialty marine fish hatchery shipments requiring extended distribution chains.
Bulk packaging dominates integrated channel volume, though bags are climbing the fastest through digital platform-enabled smallholder demand aggregation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Vietnam's Mekong Delta exhibit the highest price elasticity, squeezing margins among informal blenders, while Norwegian salmon hatcheries absorb premium pricing for water-stable precision formulations without volume sacrifice.
Vietnam
Mekong Delta poultry zones are consolidating under vertically coordinated contract farming models that standardize early-stage nutrition protocols. The Ministry of Agriculture's GB standards enforcement is professionalizing quality assurance infrastructure across feed manufacturing facilities. Can Tho and An Giang provinces now host integrated broiler operations that lock in starter feed offtake volumes through multi-year supply agreements.
Norway
Indoor salmon and trout hatcheries are specifying precision-formulated starter diets with extended water stability and reduced nitrogen leaching profiles. The EU F-Gas Regulation phase-down schedules are accelerating adoption of mechanical vapor recompression in feed pelleting operations. Bergen and Trondheim coastal clusters are piloting bacterial biomass and algal protein concentrates at 15-30% substitution levels in marine fish starter diets.
Thailand
Shrimp and marine fish operations are demanding water-stable micro-extruded diets with exacting lysine-to-energy ratios for larval survival optimization. The national feed hygiene framework mandates HACCP-based hazard analysis across manufacturing facilities. Samut Sakhon and Surat Thani aquaculture clusters now require FAMI-QS certification as a condition of supply relationship continuation.
Indonesia
Broiler integrators and shrimp farming clusters are bypassing traditional distributor networks through mobile-ordering applications that aggregate smallholder demand. The Ministry of Agriculture's veterinary drug residue monitoring enforces zero-tolerance antibiotic growth promoter protocols. Java's coastal aquaculture zones and East Java poultry corridors are marginalizing informal blenders lacking accredited quality assurance infrastructure.
Poland
Poultry-dominant markets are responding fastest to integrated energy-carbon cost accounting under national decarbonization frameworks. The EU Green Deal's feed-to-food sustainability mandates are compressing formulation timelines and elevating compliance costs. Greater Poland and Lower Silesia voivodeships are retrofitting extrusion processes with heat pump technologies that reduce thermal energy intensity 40-60%.
Starter Feed Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes in starter feed, with multinational compounders commanding premium positioning through captive amino acid production while regional blenders compete on logistics proximity. The market structure bifurcates between capital-intensive integrated operators and mid-tier specialists. Three archetypes dominate: grain-origination conglomerates with backward integration into protein processing, aquaculture-focused hatchery integrators controlling channel access, and fermentation-derived additive specialists. Competitive moves concentrate on portfolio diversification toward phytogenic alternatives and geographic expansion through distributor network digitization.
Within the integrated grain-origination tier, Cargill Incorporated exemplifies the archetype of captive supply chain control across North American poultry corridors. Charoen Pokphand Foods PCL anchors the hatchery-integrated model through upstream control over Thai and Indonesian shrimp farming clusters. Evonik Industries AG occupies a position representing fermentation-derived amino acid specialists where lysine and methionine supply concentrates among multinational producers.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Alltech Inc |
| Evonik Industries AG |
| Nutreco |
| Land O'Lakes Inc |
| De Heus Voeders |
| Charoen Pokphand Foods PCL |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Precision fermentation-derived single-cell proteins substituting for conventional fishmeal and soybean meal are redrawing supply geography toward Norwegian and Vietnamese fermentation hubs while fragmenting long-term oilseed processor contracts and compressing regional spot market price discovery mechanisms.
Pricing Analysis
After-sales nutrition advisory and extended technical service contracts drive lifetime value for compound feed manufacturers serving integrated poultry and aquaculture operations. Three-tier pricing structure across premium certified, standard accredited, and economy unbranded levels separates FAMI-QS-verified formulations from informal blender alternatives. Cost compression in economy tiers is intensifying because Vietnamese Mekong Delta contract growers exhibit extreme price elasticity and bypass distributors through mobile-ordering platforms. Least price-sensitive buyers operate Norwegian salmon hatcheries specifying water-stable precision formulations with extended submersion integrity.
Supply Chain Analysis
Strait of Malacca transit chokepoints expose Argentine soybean meal shipments and Indonesian palm kernel cake flows to logistics disruption risks that cascade through Southeast Asian compound feed operations. Supply concentrates in Argentina, Brazil, and the United States for heat-processed soybean meal; China, Thailand, and Vietnam for aquaculture feed manufacturing; and Germany, Japan, and South Korea for fermentation-derived lysine and methionine. Raw material dependencies rest on oilseed crush volumes, amino acid fermentation capacity, and marine ingredient harvest quotas. Single-source amino acid vulnerability from three multinational producers creates input bottleneck exposure. Distribution runs through vertically integrated poultry complexes with tanker delivery and digital platform-aggregated smallholder bagged shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Starter feed procurement is approaching a platform-economics inflection as Vietnamese and Indonesian mobile-ordering applications aggregate fragmented smallholder demand and disintermediate traditional distributor networks, creating interoperability standards around certification verification and volume pooling.
For Market Incumbents: Compound captive amino acid production advantages through backward integration into fermentation capacity or long-term offtake agreements with lysine and methionine suppliers, defending against precision fermentation protein entrants and regional blender price aggression. Lock in multi-year supply relationships with Thai and Indonesian shrimp farming clusters through mandatory FAMI-QS certification as a condition of contract continuation.
For New Entrants and Emerging Players: EFSA's novel feed additive fast-track authorization pathway offers first-mover positioning for botanical extract suppliers demonstrating gut health benefits in immature gastrointestinal tracts. Target Vietnamese Mekong Delta informal blender displacement through digital platform partnerships that aggregate smallholder demand and bypass legacy distributor networks. Lead with phytogenic additive validation data and mobile-ordering integration as the go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-derived additive specialists and aquaculture hatchery integrators controlling channel access. Long-term viability over the next decade rests on regulatory authorization capabilities and backward integration depth rather than commodity scale. Acquisition target archetype: mid-tier compounders with FAMI-QS certification infrastructure and established relationships with Vietnamese or Indonesian contract farming clusters. Watch EFSA novel feed additive approval velocity as the inflection indicator for phytogenic category expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Protein Scale-Up | Norwegian salmon hatcheries pilot bacterial biomass at 15-30% substitution levels, fragmenting oilseed processor contracts. |
| Mechanical Vapor Recompression Retrofit | Polish and Spanish poultry corridors reduce thermal energy intensity 40-60% under EU F-Gas Regulation phase-down schedules. |
| FAMI-QS Certification Mandate | Thai broiler integrators now require third-party verification, marginalizing informal blenders lacking accredited infrastructure. |
| Direct-to-Farm Digital Platform Launch | Indonesian mobile-ordering applications aggregate smallholder demand and bypass traditional distributor networks. |
| Phytogenic Additive EFSA Authorization | Botanical extract suppliers gain first-mover advantages through novel feed additive pathway for gut health benefits. |
Methodological Framework
A standing panel of compound feed plant managers, aquaculture hatchery nutritionists, veterinary procurement leads at integrated poultry operations, and amino acid fermentation technical directors provided ongoing calibration across primary interview rounds. Secondary validation drew from EU Feed Hygiene Regulation 183/2005 implementation reports, FDA Veterinary Feed Directive enforcement data, FAMI-QS certification registry updates, and customs trade flows for oilseed meal and marine ingredients. Bottom-up volume modeling triangulated against top-down protein demand projections across species-specific early-stage nutrition requirements.
Consistency checks validated volume and value outputs against external benchmarks including national feed industry association production statistics and integrated poultry operator procurement disclosures across the projection horizon. Segmentation dimensions modeled encompassed species physiology requirements, ingredient functional hierarchies, processing intensity tiers, and regional regulatory compliance clusters. CAGRs derived from fitted growth curves incorporating broiler integration velocity in Vietnam, EU Green Deal formulation mandate timelines, and precision fermentation protein substitution rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU F-Gas Regulation enforcement, zero-tolerance antibiotic growth promoter protocols, and stable amino acid fermentation supply; material deviation in regulatory stringency or input cost volatility would warrant model refresh. Practitioners should keep alternative scenarios live as phytogenic additive authorization pathways and recirculating aquaculture system hatchery specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
China Horse Riding Equipment Market
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Goat Handling Equipment Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Cattle Grooming Chute Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Silage Tube Market
Livestock Equipment
Russia Horse Riding Equipment Market