
 Poultry Brooder Market | 2026-2036
Poultry Brooder Market Size, Share, and Industry Trends Forecast 2026-2036
Poultry Brooder Market Analytics
Modular brooder systems bundled with automated feeding and ventilation controls is recalibrating procurement decisions across mid-sized operations. Big Dutchman leverages its integrated house-system architecture to anchor premium positioning in European markets. Chore-Time competes through feed-delivery compatibility that extends its brooder attach rate in North American turnkey contracts. Vencomatic Group specializes in colony-style configurations that dominate Netherlands-based layer-to-broiler conversion projects.
A poultry brooder is a climate-controlled enclosure maintaining precise temperature gradients between 32°C and 35°C for day-old chicks, utilizing radiant or convective heat distribution through ceramic elements, gas burners, or electric coils to ensure thermal uniformity and minimize piling mortality during the critical first fourteen days. Indirect heaters command the largest installed base due to lower fire risk and compatibility with controlled-atmosphere housing, though infrared brooders capture margin pools in antibiotic-free operations where localized microclimate precision reduces stress-induced disease susceptibility. Electric brooders lead in solar-hybrid installations where grid reliability varies, while direct heaters retain cost-sensitive small-scale farmer demand despite higher ventilation engineering requirements.
USDA biosecurity protocols and EPA ammonia emission thresholds shape product design for equipment sold into United States integrated chains, while EU F-Gas Regulation and national animal welfare ordinances in Germany and the Netherlands mandate heat-source efficiency minimums that filter import eligibility. China's GB standards for agricultural machinery safety and India's BIS electrical certification create divergent compliance burdens for manufacturers serving Asia's fragmented procurement landscape. Stakeholders must monitor how carbon-accounting rules in multiple jurisdictions redefine total-cost-of-ownership calculations for gas versus electric heating architectures.
Market Dynamics
Contract farming mandates across Southeast Asian integrators are forcing standardization of brooder specifications, compressing procurement cycles and privileging suppliers with modular, climate-controlled system architectures over component vendors.
Growth Catalysts
- EU F-Gas Regulation:Heat-source efficiency minimums in Germany and the Netherlands are filtering import eligibility and accelerating replacement cycles for gas-fired brooders with electric and solar-hybrid alternatives.
- Antibiotic-free operations:Infrared brooders with localized microclimate precision are reducing stress-induced disease susceptibility, creating specification pull from premium poultry chains in North America and Western Europe.
- Brazil's animal welfare tightening:ANVISA-aligned national standards for intensive production are scaling climate-controlled brooder installations across commercial farms in São Paulo and Paraná states.
Market Restraints
- Steel and aluminum input volatility:Raw material price swings for brooder housing construction are compressing margins for equipment fabricators serving cost-sensitive smallholder segments.
- Electrical certification fragmentation:Divergent BIS requirements in India, GB standards in China, and NEC compliance in the United States create multi-jurisdictional testing burdens that delay product launches.
- Direct heater fire risk:Higher ventilation engineering requirements for gas-fired direct heating systems limit their deployability in controlled-atmosphere housing configurations preferred by large integrators.
Strategic Opportunities
- Solar-hybrid electric architectures:Grid reliability gaps across Indonesia, Vietnam, and the Philippines are creating attach-rate expansion for battery-backed brooder systems that reduce diesel generator dependency.
- Carbon-accounting rule convergence:Emerging Scope 1 emission tracking requirements in the European Union and California are repositioning total-cost-of-ownership calculations toward electric heating.
- Layer-to-broiler conversion projects:Netherlands-based facility repurposing is driving colony-style brooder demand for operations switching egg production to meat bird rearing.
Industry Challenges
- Controls integration complexity:Retrofitting automated feeding and ventilation interfaces into legacy brooder infrastructure requires specialized technician labor that concentrates in regional service hubs.
- Biosecurity certification timelines:USDA protocol compliance for equipment sold into integrated chains demands extended validation periods that strain working capital for smaller manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poultry Brooder Market |
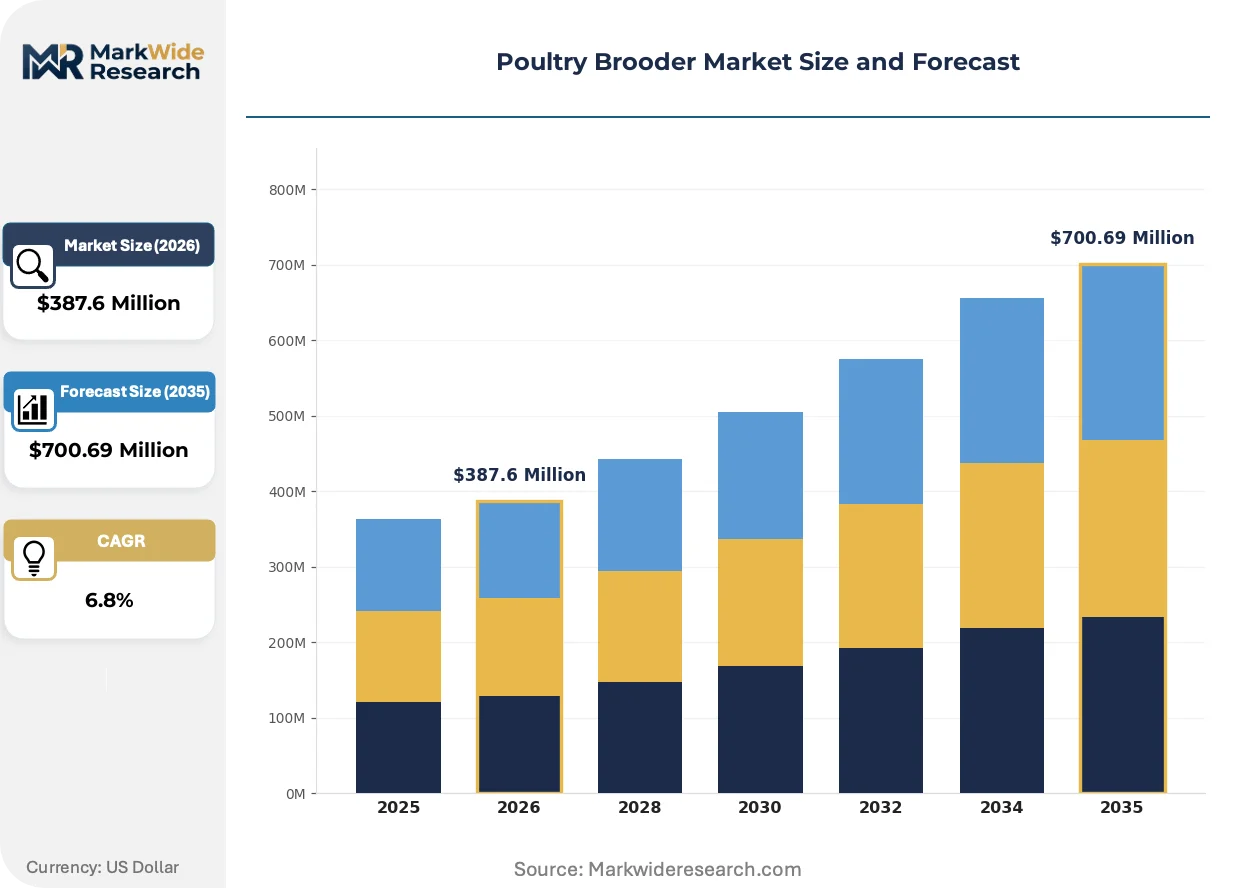
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indirect Heaters, Direct Heaters, Infrared Brooders, Electric Brooders End User: Small-Scale Farmers, Commercial Poultry Farms, Hatcheries, Cooperative Farms Material: Metal, Plastic, Fiberglass, Aluminum Power Source: Electric, Gas, Solar, Propane |
| Companies Covered | Big Dutchman, Chore-Time, Vencomatic Group, Roxell, Farmer Automatic, Plasson, Valco Companies, Tecno Poultry Equipment, Petersime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poultry Brooder Market Evolving Landscape
Sensor-driven climate management is compressing mortality differentials between early-stage operations and established integrators, while regulatory pressure on thermal efficiency redefines equipment replacement economics.
IoT-enabled environmental monitoring is automating real-time temperature gradient adjustment across brooder zones. Mid-sized operations in Poland and Thailand are adopting these systems fastest, often through integrator-mandated upgrade programs. The technology is automating labor previously dedicated to manual thermostat checks and emergency heat-source intervention, reducing piling mortality during the critical fourteen-day window.
China's GB standards for agricultural machinery safety are tightening electrical enclosure and fail-safe requirements for heating elements. Domestic manufacturers must redesign ceramic emitter housings and control panel ingress protection to maintain market access. Layer operations in Shandong and Guangdong provinces are delaying procurement until certified equipment availability stabilizes.
Integrator-controlled specification setting is displacing independent farm operator discretion in brooder selection. Southeast Asian contract farming clusters now mandate uniform brooder architectures across their supplier networks, consolidating vendor relationships. Vietnam's Mekong Delta and Indonesia's Java corridor exhibit this concentration most acutely, with procurement decisions centralized at processing company headquarters rather than farm level.
Poultry Brooder Market Segmentation
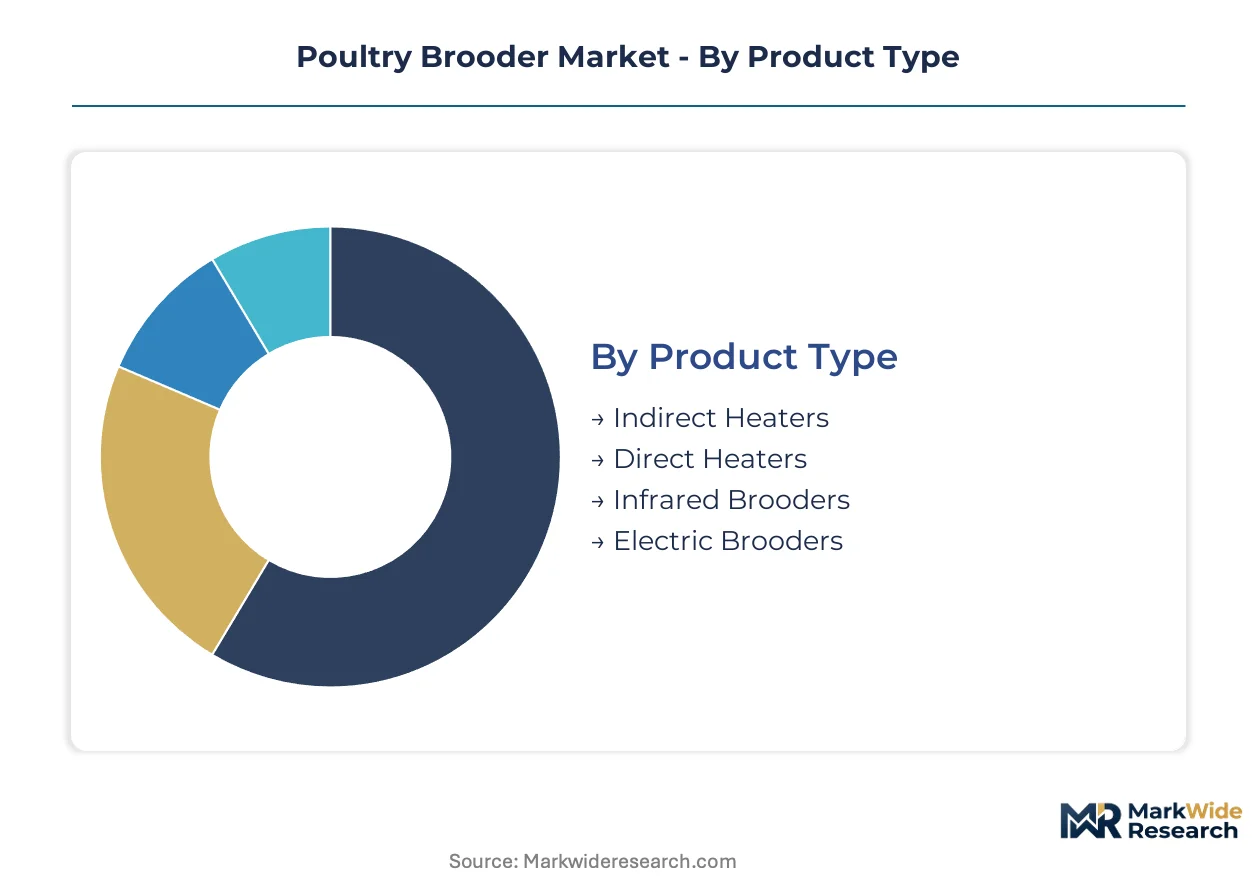
Capital allocation across brooder segments varies dramatically by heating architecture and housing integration depth. Procurement patterns diverge sharply between integrator-mandated specifications and independent operator discretion.
Product Type:
Indirect heaters demand the highest upfront capital outlay due to ducting infrastructure and controlled-atmosphere housing compatibility requirements.
- Indirect Heaters:These systems distribute heat through air ducts or radiators without combustion gases entering the brooder space. Commercial poultry farms in Brazil's São Paulo and Paraná states are scaling these installations as ANVISA-aligned welfare standards tighten ventilation and fire-safety requirements for intensive production.
- Infrared Brooders:Ceramic or quartz elements emit radiant heat directly to chick-level zones without warming entire air volumes. Premium poultry chains in North America and Western Europe specify these for antibiotic-free operations where localized microclimate precision reduces stress-induced disease susceptibility and mortality differentials.
- Direct Heaters:Gas-fired units release combustion heat directly into the brooder space. Small-scale farmer demand persists in cost-sensitive segments despite higher ventilation engineering requirements and fire-risk premiums.
- Electric Brooders:Resistance coils or heating elements provide thermal output with zero on-site emissions. Solar-hybrid installations across Indonesia, Vietnam, and the Philippines favor these architectures where grid reliability varies and diesel generator dependency carries fuel cost volatility.
Indirect heaters absorb the bulk of installed capacity across large integrated operations; electric brooders are expanding most quickly in solar-hybrid configurations.
End User:
Volume concentration tilts toward operations with integrator-backed financing and centralized procurement authority.
- Commercial Poultry Farms:Climate-controlled house systems with automated feeding and ventilation integration dominate capital deployment. Southeast Asian contract farming clusters in Vietnam's Mekong Delta and Indonesia's Java corridor mandate standardized brooder specifications across supplier networks, compressing procurement cycles.
- Hatcheries:Day-old chick uniformity requirements drive precision heating investments. These facilities prioritize thermal gradient control within 32°C to 35°C ranges to minimize piling mortality during the critical fourteen-day brooding window.
- Small-Scale Farmers:Cost-minimization dominates equipment selection, with direct heaters and basic electric models prevailing despite higher operational labor intensity.
- Cooperative Farms:Shared infrastructure spreads capital burden across member operations, enabling access to modular systems otherwise beyond individual farm budgets.
Commercial poultry farms command the dominant share of equipment value; hatcheries are gaining share fastest as day-old chick quality standards tighten.
Material:
Corrosion resistance and thermal conductivity properties dictate material selection for housing construction and heat distribution components.
- Metal:Galvanized steel enclosures dominate structural housing for durability and impact resistance in high-density rearing environments.
- Aluminum:Lightweight heat reflectors and emitter housings offer thermal efficiency advantages with reduced structural load.
- Plastic:Polymer feed pans, waterers, and guard rails reduce corrosion maintenance in high-humidity brooder environments.
- Fiberglass:Insulated panel systems improve thermal retention in controlled-atmosphere housing configurations.
Metal construction retains the largest installed base; aluminum components are climbing the fastest as weight reduction and thermal efficiency gain priority.
Power Source:
Energy cost trajectories and carbon-accounting rules are repositioning total-cost-of-ownership calculations across heating architectures.
- Electric:Grid-connected and battery-backed systems enable precise zone control and zero direct emissions. EU F-Gas Regulation efficiency minimums in Germany and the Netherlands are filtering import eligibility and accelerating replacement of gas-fired alternatives.
- Gas:Natural gas and LPG systems retain cost advantages where pipeline infrastructure exists, though ventilation engineering requirements limit deployability in controlled-atmosphere housing.
- Solar:Photovoltaic arrays with battery storage reduce diesel generator dependency across Indonesia, Vietnam, and the Philippines where grid reliability gaps persist.
- Propane:Portable cylinder systems serve remote operations lacking grid or pipeline access, with higher per-unit energy costs accepted for location flexibility.
Gas power sources retain the greatest installed capacity; solar configurations are gaining share fastest where carbon-accounting rules and grid unreliability coincide.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication concentrates in Northern European engineering clusters while procurement demand shifts toward Southeast Asian contract farming corridors and Brazilian commercial expansion zones.
United States
Integrated poultry chains drive specification standardization across the Southeast and Midwest production belts. USDA biosecurity protocols and EPA ammonia emission thresholds shape equipment design for houses supplying Tyson Foods and Pilgrim's Pride networks. Georgia's poultry corridor anchors the densest concentration of climate-controlled brooder retrofits.
Brazil
ANVISA-aligned welfare standards for intensive production are accelerating replacement cycles in São Paulo and Paraná states. Commercial farms are scaling indirect heater installations to meet ventilation and fire-safety mandates. The southern production belt exhibits the fastest procurement velocity for modular house systems.
Germany
EU F-Gas Regulation efficiency minimums are filtering import eligibility and privileging domestic electric and solar-hybrid fabricators. Lower Saxony's livestock engineering cluster anchors R&D investment in heat-source optimization. National animal welfare ordinances mandate thermal gradient precision that exceeds baseline CE requirements.
Vietnam
Contract farming mandates from CP Group and Japfa Comfeed are centralizing procurement decisions at processing company headquarters. The Mekong Delta exhibits acute specification standardization across supplier networks. Grid reliability gaps are expanding attach rates for battery-backed electric brooders in solar-hybrid configurations.
Netherlands
Layer-to-broiler conversion projects are driving colony-style brooder demand as egg producers repurpose facilities for meat bird rearing. National animal welfare ordinances and EU F-Gas Regulation create dual compliance burdens that privilege integrated system architects. Brabant's equipment manufacturing corridor dominates European export capacity.
Poultry Brooder Market Competitive Landscape
The competitive structure tilts toward integrated house-system architects over component specialists. Vendor relationships consolidate around suppliers offering bundled climate control, feeding, and ventilation modules. Three archetypes dominate: European turnkey house-system providers, North American feed-delivery-integrated fabricators, and Asian cost-optimized component assemblers. Capacity expansion and strategic partnerships represent the dominant competitive moves as procurement cycles compress under integrator mandates.
Within the integrated-system tier, Big Dutchman and Vencomatic Group occupy anchor positions exemplifying divergent specialization vectors. Big Dutchman represents the German-engineered house-system architecture that dominates European premium procurement. Vencomatic Group exemplifies Netherlands-based colony-style configuration expertise serving layer-to-broiler conversion demand. Chore-Time anchors the North American feed-delivery compatibility vector that extends brooder attach rates in turnkey contracts.
| Leading Market Players |
|---|
| Big Dutchman |
| Chore-Time |
| Vencomatic Group |
| Roxell |
| Farmer Automatic |
| Plasson |
| Valco Companies |
| Tecno Poultry Equipment |
| Petersime |
| Others |
Value Network & Pricing Analysis
Integrator-mandated specification standardization across Southeast Asian contract farming clusters is compressing procurement cycles and forcing suppliers to absorb certification costs, which compresses margins for component specialists while privileging bundled system architects with pricing power.
Pricing Analysis
Cost-down pressure on economy-tier brooders accelerates because steel and aluminum input volatility strains fabricators serving smallholder segments. Pricing stratifies across premium, standard, and economy tiers, with differentiation anchored in CE certification grade and after-sales service bundling. Margin tightening in the standard tier traces to volume scale demands from Vietnamese and Indonesian integrators. Small-scale farmers exhibit highest price sensitivity, while commercial poultry farms prioritize thermal efficiency over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from European integrators mandate multi-supplier qualification for heating element and control panel procurement. Manufacturing concentrates in Germany, the Netherlands, and China, with ceramic emitter housings and galvanized steel enclosures drawing from specialized metalworking clusters. Single-source vulnerability persists for precision temperature sensors sourced from East Asian semiconductor fabricators. Distribution runs through integrator-approved equipment dealers and regional service hubs rather than direct farm sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over climate-control software and sensor calibration to lock in recurring service revenue and defend against modular competitors.
For Market Incumbents: Deploy certification investment as the primary lever. Accelerate EU F-Gas Regulation pre-qualification for electric and solar-hybrid architectures before import eligibility gates tighten further. Consolidate regional service hub coverage to reduce technician deployment costs for retrofit installations, countering emerging Asian component assemblers with lower labor rates.
For New Entrants and Emerging Players: Battery-backed solar-hybrid control systems offer the clearest technology-first wedge. Target Indonesia's Java corridor and Vietnam's Mekong Delta where grid reliability gaps persist and incumbent service networks remain thin. Pursue integrator pilot programs with guaranteed uptime service-level agreements rather than equipment-only sales.
For Investors and Strategic Acquirers: Re-rating potential sits with colony-style configuration specialists given layer-to-broiler conversion demand in the Netherlands and Germany. Long-term viability hinges on carbon-accounting rule convergence repositioning total-cost-of-ownership calculations. Watch for Scope 1 emission tracking mandate announcements in California and EU member states as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of IoT temperature probes reduces calibration drift warranty exposure for climate-control system vendors. |
| CE Marking Pre-Certification for Solar-Hybrid Architectures | Early EU F-Gas Regulation alignment secures import eligibility before efficiency minimums filter competitor eligibility. |
| Regional Service Hub Expansion | Technician concentration in Poland and Thailand compresses emergency response times for automated brooder retrofits. |
| Integrator Pilot Program Partnerships | CP Group and Japfa Comfeed validation in Vietnam's Mekong Delta creates specification pull across Southeast Asian networks. |
| Software-Defined Climate Control Platform | Real-time gradient adjustment algorithms differentiate premium offerings from commodity heating hardware in antibiotic-free operations. |
Research Methodology
Trade association filings, agricultural machinery customs records, and EU regulatory impact assessments formed the secondary backbone. Primary interviews with poultry farm operations managers, integrator procurement directors, and climate-control equipment R&D heads validated demand assumptions. Bottom-up and top-down triangulation reconciled equipment shipment data with installed capacity estimates across Brazil's São Paulo state, Germany's Lower Saxony cluster, and Vietnam's Mekong Delta corridor.
Bottom-up modeling aggregated segment-level unit economics across heating architecture, housing integration depth, and power source configurations. Top-down validation cross-checked against national livestock census data and integrator capacity expansion announcements. CAGRs were derived from regression analysis of replacement cycle compression and regulatory mandate acceleration. Key inputs included ANVISA welfare standard implementation timelines and F-Gas Regulation efficiency threshold phase-in schedules.
Several conditions sit outside the modeled scope, including extreme weather event frequency impacts on mortality differentials and trade policy shifts affecting steel and aluminum input costs. Forecasts reflect documented assumptions about integrator consolidation velocity and carbon-accounting rule adoption pace. Deviation in EU member state transposition timelines for F-Gas Regulation efficiency minimums would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poultry Farming Equipment
Poultry Farming Equipment Market
Poultry Farming Equipment
Poultry Incubator Market
Poultry Farming Equipment
Poultry Keeping Machinery Market
Poultry Farming Equipment
Egg Grading Machines Market
Poultry Farming Equipment
Poultry Brooders, Feeders, and Waterers Market
Poultry Farming Equipment
Poultry House Ventilation System Market
Poultry Farming Equipment
Commercial Chicken Plucker Market
Poultry Farming Equipment
Multi-Layer Poultry Cage Market
Poultry Farming Equipment
Poultry Plucker Market
Poultry Farming Equipment
Rabbit Cages Market
Poultry Farming Equipment
Turkey Poultry Market
Poultry Farming Equipment
Egg Breaking Machine Market
Poultry Farming Equipment
Asia Pacific Poultry Market
Poultry Farming Equipment
Automated Poultry Farm Market
Poultry Farming Equipment
Duck Plucker Machine Market