
 Cattle Blower Market | 2026-2036
Cattle Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Cattle Blower Market Outlook
Polymer composites are repositioning metal housings in cattle blower construction, cutting unit weight and improving corrosion resistance in barn environments. The Toro Company leverages its outdoor power equipment supply chain to source electric motor platforms for livestock applications. Stihl anchors its position through two-stroke engine expertise, though the firm now navigates tightening emissions rules. Sullivan Supply specializes in show-ring grooming tools, occupying a premium niche among competitive livestock exhibitors.
A cattle blower is a forced-air drying and grooming device, typically generating airflow velocities exceeding 200 mph through a tapered nozzle, designed to remove moisture and debris from bovine coats in dairy, beef, and show contexts. Electric blowers are gaining share as brushless DC motor costs decline and farm electrical infrastructure improves, while gas-powered units retain dominance in remote pasture operations lacking grid access. Among end users, livestock breeders represent the fastest-growing segment as embryo transfer programs and show circuits professionalize their animal preparation protocols.
EPA Phase 3 small spark-ignition engine standards restrict exhaust emissions from gas-powered units, compelling redesigns or electrification strategies. The USDA Organic certification program indirectly shapes demand by encouraging animal welfare investments that include grooming equipment for herd health monitoring. Stakeholders must weigh motor technology bets against the pace of rural electrification and the durability expectations of all-day dairy operations.
Market Dynamics
The cattle blower market faces a decisive technology inflection as brushless DC motor economics cross the threshold for commercial livestock operations, compressing the traditional gasoline-engine replacement cycle and rewiring supplier R&D priorities toward electrification platforms.
Growth Catalysts
- EPA Phase 3 Emissions Standards:Exhaust limits on small spark-ignition engines are forcing manufacturers to accelerate electric platform development, creating regulatory pull for cleaner livestock grooming equipment.
- Midwest CAFO Density:Concentrated animal feeding operations across Iowa, Wisconsin, and Minnesota generate predictable replacement demand through standardized herd management protocols and volume purchasing.
- Polymer Composite Adoption:Glass-reinforced nylon housings are displacing cast aluminum, cutting unit weight and eliminating galvanic corrosion in high-humidity barn environments.
Market Restraints
- Copper Magnet Wire Volatility:Brushless DC motor stators depend on copper windings, exposing manufacturers to London Metal Exchange price swings that compress motor assembly margins.
- Rural Electrification Gaps:Pasture operations in Wyoming, Montana, and the Dakotas lack three-phase grid access, locking in gasoline-engine dependence regardless of regulatory pressure.
- Neodymium Rare Earth Concentration:Permanent magnet supply chains concentrate in Chinese processing facilities, creating geopolitical exposure for motor manufacturers scaling production.
Strategic Opportunities
- Battery Interchangeability:Lithium-ion packs compatible with existing farm equipment ecosystems could unlock cordless blower adoption among operations already invested in electric tool platforms.
- Show Circuit Professionalization:Junior livestock exhibition circuits are formalizing grooming standards, creating demand for precision airflow control and noise reduction in premium units.
- USDA Organic Certification Tailwinds:Animal welfare documentation requirements incentivize hygiene investments, positioning cattle blowers as herd health monitoring tools rather than cosmetic accessories.
Industry Challenges
- Brushless Motor Controller Calibration:Dairy operations demand 8-12 hour continuous runtime, requiring thermal management expertise scarce among traditional small-engine technicians.
- IP69K Ingress Protection Certification:High-pressure washdown protocols in modern parlors necessitate sealed electronics, extending validation timelines for new product introductions.
- Legacy Dealer Network Competency Gaps:Rural equipment distributors lack electrical diagnostic training, complicating after-sales support for electrified product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cattle Blower Market |
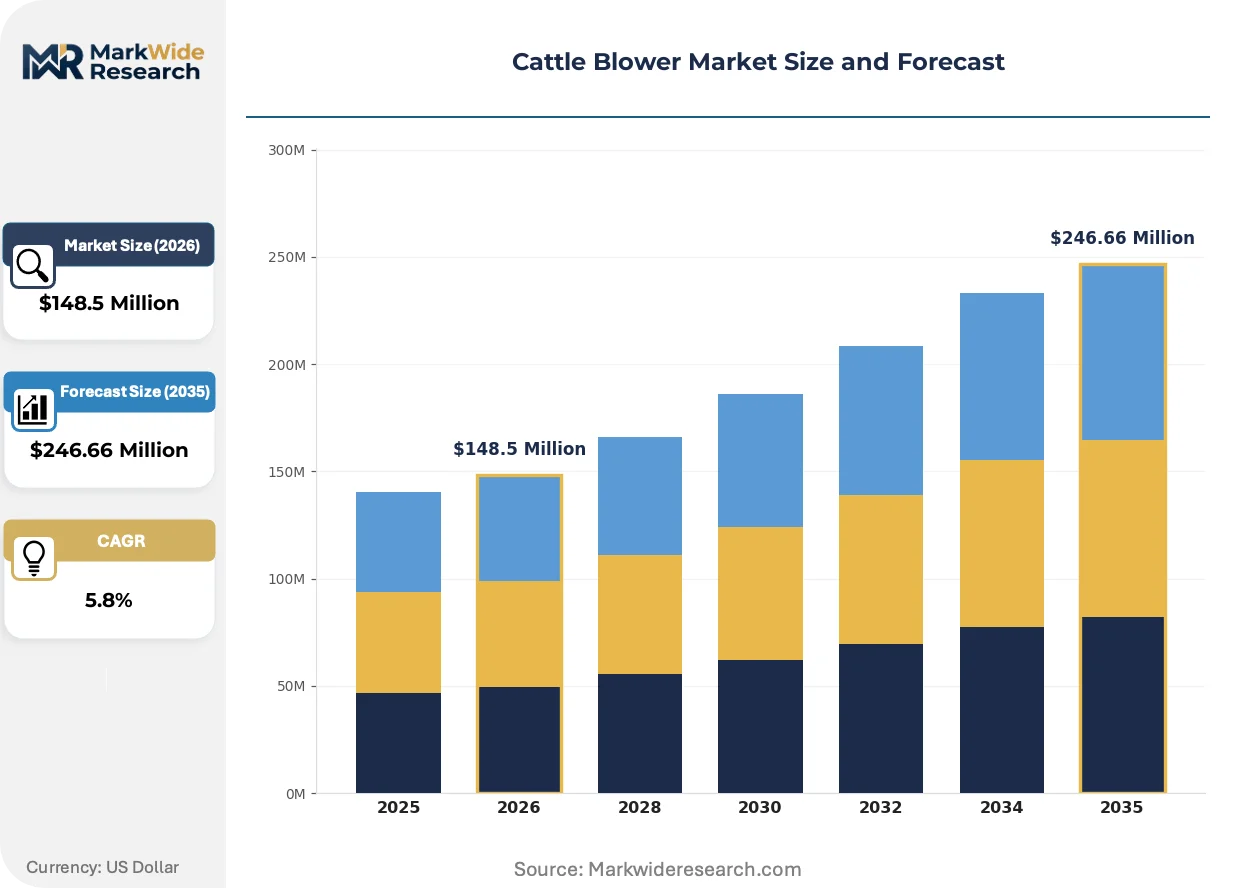
| Market Size in 2026 | $148.5 Million |
| Market Size in 2035 | $246.66 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Blowers, Gas-Powered Blowers, Portable Blowers, Industrial Blowers Application: Dairy Farming, Livestock Handling, Agricultural Use, Veterinary Care End User: Farmers, Livestock Breeders, Veterinary Clinics, Agricultural Suppliers Power Rating: Low Power, Medium Power, High Power, Extra High Power |
| Companies Covered | The Toro Company, Husqvarna, LEISTER Technologies AG, Weaver Livestock, Boss Blower, Sullivan Supply, Circuiteer, Stihl, Echo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cattle Blower Market Strategic Shifts
Livestock grooming equipment is undergoing a platform shift from combustion-centric engineering to electromechanical system design, with implications for supplier capabilities, distribution economics, and end-user operating costs.
Brushless DC motor architectures are electrifying the cattle blower category. These motors eliminate carbon brush maintenance while delivering torque curves optimized for livestock coat penetration. Large-scale dairies in California's Central Valley and Wisconsin's Fox River Valley are piloting corded electric units for parlors with dedicated 240V drops. The technology is electrifying competitive dynamics by eroding the service-revenue moat that gasoline-engine incumbents built around carburetor rebuilds and seasonal tune-ups.
EPA Phase 3 small spark-ignition engine standards are tightening exhaust emission limits for handheld outdoor power equipment. Manufacturers must either redesign two-stroke combustion systems with catalytic after-treatment or abandon gasoline platforms entirely. Gas-powered blower SKUs face the steepest compliance cost escalation, pushing engineering resources toward battery-electric development and compressing the timeline for portfolio transition.
Buying committees at multi-site dairy operations are consolidating vendor relationships and demanding cross-compatible battery platforms. Equipment managers at operations running Toro, DeWalt, or Milwaukee outdoor tool fleets prefer blowers sharing those ecosystems, reducing charger proliferation and spare battery inventory. This preference shift is most pronounced in the Southwest, where large integrated dairy processors operate standardized equipment pools across multiple parlors.
Cattle Blower Market Segmentation
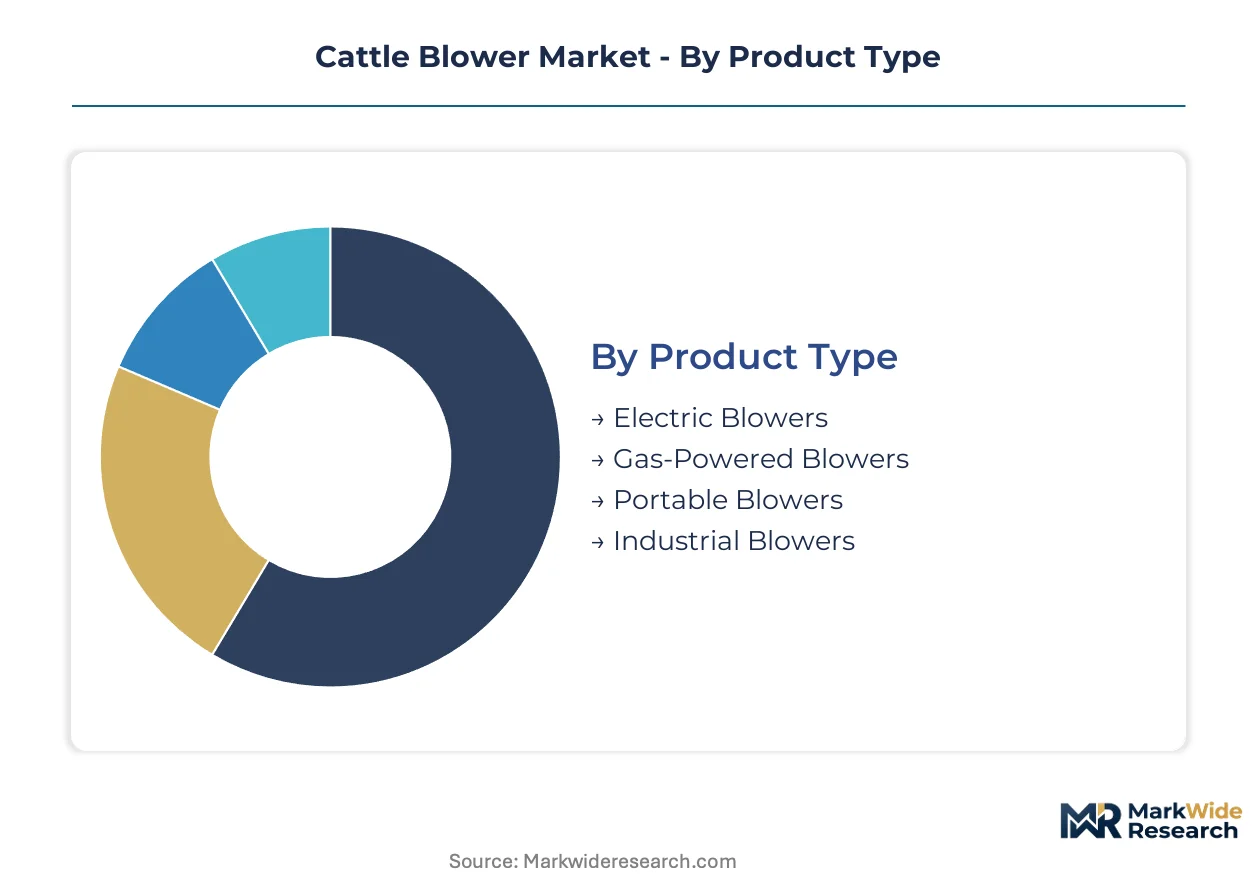
Cattle blower segmentation reveals how electrification pressures and CAFO operational requirements are splitting demand across incompatible technology platforms. Understanding these divides helps suppliers allocate R&D resources between compliance-driven redesigns and performance-focused premium tiers.
Product Type:
Volume sales concentrate in entry-level electric units for parlors with grid access, while premium margins attach to specialized gas-powered designs for remote operations.
- Electric Blowers:Brushless DC motors eliminate carbon brush maintenance while delivering torque curves optimized for coat penetration. Demand clusters in California's Central Valley and Wisconsin's Fox River Valley dairies with dedicated 240V drops, driven by EPA Phase 3 compliance costs that make gasoline platforms uneconomical for new purchases.
- Gas-Powered Blowers:Two-stroke engines retain dominance where three-phase grid infrastructure is absent. Wyoming and Montana pasture operations depend on these units regardless of tightening emissions standards, though catalytic after-treatment redesigns are compressing manufacturer margins.
- Portable Blowers:Cordless lithium-ion designs target show-ring exhibitors needing mobility without generator noise.
- Industrial Blowers:Fixed-mount high-velocity systems integrate into automated parlor washdown protocols.
Today's leader: Electric Blowers. Tomorrow's challenger: Portable Blowers.
Application:
End-use concentration tracks herd size and facility capital intensity, with the largest operations driving standardization.
- Dairy Farming:High-throughput parlors demand 8-12 hour continuous runtime with IP69K ingress protection for high-pressure washdown protocols. Iowa and Minnesota CAFOs generate predictable replacement cycles through volume purchasing agreements with integrated processors.
- Livestock Handling:Beef feedlot operations prioritize durability over precision airflow control.
- Agricultural Use:Mixed-operation farms require multi-species compatibility.
- Veterinary Care:Mobile practitioners need lightweight units for field sedation recovery.
Procurement authority is shifting toward equipment managers at multi-site dairy processors, consolidating vendor relationships around cross-compatible battery platforms.
End User:
Customer sophistication varies from price-sensitive commodity producers to welfare-focused premium breeders.
- Livestock Breeders:Embryo transfer programs and junior exhibition circuits professionalize grooming standards, creating demand for precision airflow control and noise reduction. USDA Organic certification requirements position blowers as herd health monitoring tools rather than cosmetic accessories.
- Farmers:Commodity dairy operators prioritize total cost of ownership and dealer service network proximity.
- Veterinary Clinics:Mobile large-animal practices need rapid dry-down for post-procedure hypothermia prevention.
- Agricultural Suppliers:Distributor purchasing decisions hinge on inventory turns and warranty claim rates.
Livestock Breeders are climbing the fastest as show circuits formalize preparation protocols and documentation requirements.
Power Rating:
Motor sizing correlates with facility scale and animal throughput requirements.
- High Power:Units exceeding industrial airflow thresholds serve large CAFO parlors processing 500+ head daily, where dry-time efficiency directly affects milking schedule throughput.
- Medium Power:Balanced output for mid-size operations with intermittent use patterns.
- Low Power:Entry-tier corded designs target hobby farms and 4-H exhibitors.
- Extra High Power:Specialized units for dense-hair heritage breeds and emergency hypothermia treatment.
Specification creep is pushing medium-power buyers toward high-power units as herd sizes expand and labor costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The American Midwest anchors cattle blower demand through concentrated animal feeding operations in Iowa, Wisconsin, and Minnesota. These states generate predictable replacement cycles through standardized herd management protocols. Regional electrification gaps and emissions regulations are fragmenting technology adoption across North American markets.
United States
Midwest CAFOs in Iowa and Wisconsin drive volume purchasing through integrated dairy processors. EPA Phase 3 small spark-ignition engine standards compel manufacturers toward electric platforms in states with grid access. California's Central Valley dairies pilot corded electric units with dedicated 240V infrastructure, compressing gasoline-engine replacement timelines.
Canada
Alberta and Ontario beef operations prioritize durability for feedlot grooming amid harsh winter conditions. Health Canada's PMRA regulates pesticide co-application near livestock facilities, indirectly shaping equipment washdown protocols. The Prairie Provinces concentrate demand among large-scale ranchers with limited three-phase electrical access.
Mexico
Northern border states supply beef to US processors, creating equipment standardization pressure from American buyers. Mexico's federal environmental regulator SEMARNAT enforces emissions norms that lag EPA stringency, preserving gasoline-engine viability. The Bajío Region's expanding dairy sector imports grooming equipment through cross-border distributor networks.
Germany
Baden-Württemberg's precision engineering clusters supply brushless DC motor components to livestock equipment manufacturers. ECHA's REACH regulations restrict chemical treatments in polymer composite housings, reshaping material specifications. Bavarian dairy cooperatives standardize on European electric platforms with CE marking compliance.
Australia
New South Wales and Victoria export premium beef to Asian markets, demanding show-ring grooming standards for genetic stock presentation. The country's national agricultural regulator enforces biosecurity protocols that include animal hygiene documentation. Queensland feedlots adopt industrial blowers for dense-hair heritage breeds in tropical humidity conditions.
Cattle Blower Market Competitive Environment
Global majors compete with regional champions across motor technology platforms and distribution reach. The vendor base splits between outdoor power equipment conglomerates diversifying into livestock applications and specialized grooming equipment fabricators serving show circuits. Three archetypes dominate: diversified outdoor power conglomerates, specialized livestock grooming specialists, and agricultural equipment generalists. Competitive moves concentrate on electrification platform development and strategic partnerships with dairy processor buying committees.
Among outdoor power equipment conglomerates, The Toro Company and Stihl occupy positions representing divergent technology bets—Toro leveraging electric motor supply chains and Stihl anchored in two-stroke engine expertise navigating emissions compliance. Sullivan Supply exemplifies the specialized grooming tier, occupying a premium niche among competitive livestock exhibitors. These three represent the competitive spectrum from mass-market electrification to premium show-ring specialization.
| Leading Market Players |
|---|
| The Toro Company |
| Husqvarna |
| LEISTER Technologies AG |
| Weaver Livestock |
| Boss Blower |
| Sullivan Supply |
| Circuiteer |
| Stihl |
| Echo |
| Others |
Value Chain & Pricing Dynamics
Backward integration into brushless DC motor assembly anchors pricing power for manufacturers with captive stator winding capabilities, while outsourced motor sourcing leaves assemblers exposed to copper magnet wire volatility and Chinese rare earth processing premiums. This integration choice separates premium-tier suppliers serving Iowa CAFOs from price-competitive entrants dependent on spot-market component procurement.
Pricing Analysis
Copper magnet wire pass-through from London Metal Exchange pricing compresses margins on electric blower assemblies, forcing tiered pricing stratification across premium brushless units, standard brushed-motor designs, and economy gasoline-engine alternatives. Price differentiation hinges on IP69K ingress protection certification and EPA Phase 3 compliance tier, with certified units commanding substantial premiums. Pricing pressure intensifies downward on gas-powered SKUs as catalytic after-treatment redesigns escalate production costs without commensurate buyer willingness to absorb increases. Commodity dairy operators in Minnesota and Wisconsin exhibit highest price sensitivity, while competitive livestock breeders prioritize performance specifications over unit economics.
Supply Chain Analysis
Neodymium permanent magnet supply rests on Chinese rare earth processing facilities, with secondary concentration in Japanese magnet fabrication and German precision machining for motor housings. Copper winding wire draws from Chilean mining output and US scrap recovery streams, while glass-reinforced nylon housings source from German and US polymer compounders. Single-source vulnerability concentrates in Chinese rare earth separation capacity, exposing motor manufacturers to export restriction risk. Distribution runs through rural equipment dealer networks with limited electrical diagnostic competency, complicating aftermarket support for electrified product lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cattle blower market functions as a stable compounder, with Midwest CAFO replacement cycles and EPA regulatory compliance mandates generating predictable demand continuity across economic cycles.
For Market Incumbents: Lock in multi-site dairy processor contracts through cross-compatible battery platform integration with existing Toro, DeWalt, or Milwaukee farm equipment fleets. Defend against specialized grooming entrants by embedding IP69K washdown certification as a baseline specification rather than premium upsell, while accelerating thermal management R&D to meet 8-12 hour continuous runtime requirements. For New Entrants and Emerging Players: Brushless DC motor controller calibration expertise offers entry leverage into the show-ring grooming segment, where precision airflow control commands premium positioning. Target junior livestock exhibition circuits in Texas and Oklahoma with cordless lithium-ion designs emphasizing noise reduction and mobility. Pursue direct-to-exhibitor digital channels bypassing legacy dealer network competency gaps. For Investors and Strategic Acquirers: Roll-up economics work for regional grooming equipment fabricators because dairy processor consolidation is compressing vendor counts and creating scale advantages for multi-brand portfolios. Five-to-ten year viability depends on electrification platform positioning. Watch EPA Phase 3 enforcement intensity as the inflection signal determining gasoline-engine SKU obsolescence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Integration | Cross-compatibility with Toro, DeWalt, or Milwaukee ecosystems reduces charger proliferation for multi-site dairy processors. |
| IP69K Certification Investment | Sealed electronics validation meets high-pressure washdown protocols in modern Wisconsin and Iowa parlors. |
| Thermal Management R&D | Extended runtime engineering addresses California Central Valley dairy 8-12 hour continuous operation requirements. |
| Show Circuit Partnership | Junior livestock exhibition formalization in Texas and Oklahoma creates premium positioning for precision airflow units. |
| Dealer Network Training | Electrical diagnostic capability building closes competency gaps threatening electrified product aftermarket support. |
Study Parameters
Bottom-up dairy parlor equipment modeling reconciled against top-down outdoor power equipment supply tracking forms the analytical core of this study. Primary interviews with maintenance directors at Iowa and Minnesota CAFOs, plant engineers at Wisconsin dairy processors, procurement leads at integrated livestock operations, and aftermarket service heads at rural equipment distributors combined with secondary validation from EPA Phase 3 regulatory filings, USDA organic certification databases, SEC 10-K disclosures from outdoor power equipment conglomerates, and customs trade data on brushless DC motor component imports.
Input-output matrices map motor technology platform adoption against herd size distributions, parlor electrification infrastructure penetration, and replacement cycle timing across the projection horizon. Segmentation dimensions include power source architecture, application intensity tier, end-user sophistication level, and regional grid access quality. CAGRs derive from installed base depreciation curves and compliance-driven replacement acceleration. Forecast inputs incorporate copper price volatility bands and rural electrification project pipelines from USDA Rural Development.
The model holds under stable EPA enforcement trajectory and gradual rural three-phase grid expansion; deviation in rare earth export restrictions or accelerated emissions standard phase-in would shift replacement timelines. Forecasts reflect documented assumptions regarding technology cost curves and buyer procurement consolidation. Copper magnet wire pricing, Chinese rare earth policy, and dairy processor M&A activity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Milking Equipment Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Slaughtering Equipment Market
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Europe Livestock Monitoring Market
Livestock Equipment
Rabbit Hutches Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Cattle Feeder Panels Market
Livestock Equipment
Cattle Supplies Market