
 Milking Equipment Market | 2026-2036
Milking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Milking Equipment Market Intelligence
Leasing and pay-per-milk financing is reshaping capital access for mid-sized dairy operations across Europe and Oceania. DeLaval leverages its integrated service contracts to anchor recurring revenue streams beyond hardware sales. GEA Group sustains competitive positioning through captive supply of vacuum pumps and cooling components. Lely specializes in fully autonomous robotic milking systems that reduce labor dependency for herds above 150 cows.
Milking equipment encompasses vacuum-driven extraction systems, pulsation-controlled teat cups, electronic herd monitoring sensors, and robotic milking arms engineered to maintain udder health while maximizing throughput per labor hour. Stainless steel construction with food-grade rubber liners ensures compliance with dairy hygiene standards, while automated cleaning-in-place protocols minimize bacterial contamination risks. Automated milking systems command premium positioning as dairy farms prioritize 24-hour unmanned operation, whereas milking parlors retain volume dominance in emerging markets where capital constraints limit robotic adoption. Electronic monitoring technology is expanding fastest as producers integrate mastitis detection and fertility tracking into single-platform investments.
FDA dairy equipment sanitation standards in the United States, EU Ecodesign directives on vacuum pump efficiency, and ISO 5707 specifications for milking machine construction collectively define product compliance thresholds and market access conditions. Dairy farms in California and Wisconsin face escalating OSHA scrutiny on repetitive strain injuries, accelerating ergonomic redesign demand. Stakeholders must weigh energy efficiency certification timelines against robotic system payback periods when allocating capital across herd expansion cycles.
Market Dynamics
The EU Ecodesign directive on vacuum pump energy efficiency is compressing equipment replacement cycles across European dairy operations, forcing manufacturers to reengineer core components ahead of regulatory deadlines.
Growth Catalysts
- EU Ecodesign mandates:Vacuum pump efficiency standards are accelerating hardware refresh rates among Dutch and Danish cooperatives operating herds above 200 cows.
- Robotic milking convergence:Automated teat cup attachment combined with electronic mastitis detection is displacing conventional parlor configurations in New Zealand pasture-based systems.
- OSHA ergonomic enforcement:Repetitive strain injury scrutiny in California and Wisconsin dairy operations is driving demand for automated lifting and positioning mechanisms.
Market Restraints
- Stainless steel input volatility:Grade 304 and 316 price swings compress margin stability for tank and pipeline fabricators.
- Capital intensity threshold:Robotic milking systems require payback periods exceeding five years, freezing adoption among sub-100-cow operations in emerging markets.
- Technical integration complexity:Legacy parlor infrastructure lacks data architecture compatibility with sensor-based herd management platforms.
Strategic Opportunities
- Pay-per-milk financing expansion:Usage-based leasing models are penetrating mid-sized German operations previously excluded from robotic system procurement.
- Sensor convergence:Fertility tracking algorithms merged with milk conductivity analysis create single-platform value propositions for precision livestock farming.
- Cleaning-in-place automation:Chemical dosing optimization and automated line flushing reduce labor hours in 24-hour unmanned operations across Oceania.
Industry Challenges
- Electromechanical technician scarcity:Robotic arm maintenance and pulsation calibration require specialized skills unavailable in rural labor pools.
- Multi-vendor integration friction:Proprietary data protocols between milking equipment, cooling systems, and herd management software create interoperability failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milking Equipment Market |
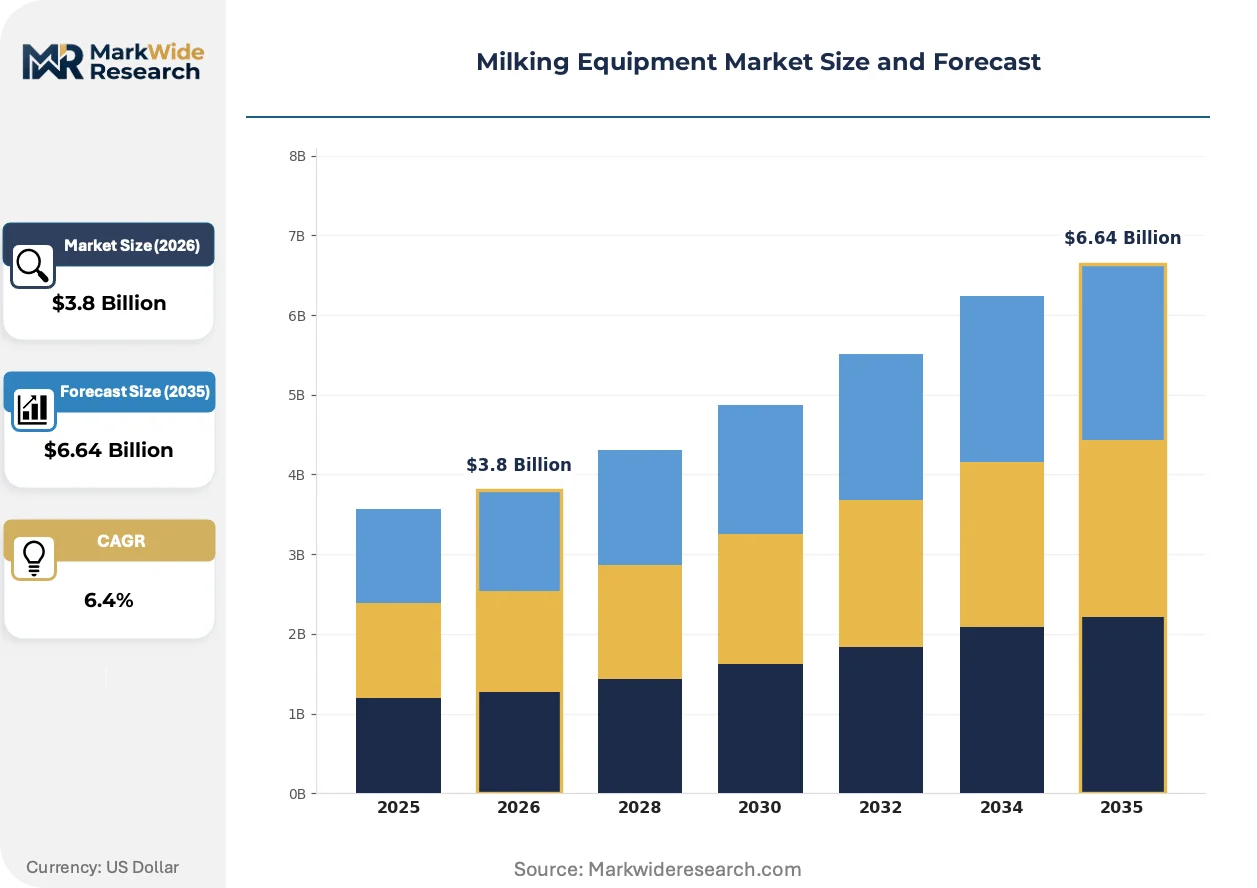
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milking Parlor, Automated Milking Systems, Milking Machines, Accessories End User: Dairy Farms, Livestock Producers, Agricultural Cooperatives, Research Institutions Technology: Vacuum Technology, Pulsation Control, Electronic Monitoring, Robotic Milking Installation: On-premise, Mobile, Semi-permanent, Fixed |
| Companies Covered | DeLaval, GEA Group, Lely, BouMatic, Afimilk, Nedap, Fullwood Packo, Waikato Milking Systems, Dairymaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milking Equipment Market Strategic Shifts & Innovations
Sensor fusion and autonomous operation protocols are compressing the labor-technology frontier, enabling continuous milking cycles without human intervention. Equipment manufacturers now compete on data integration depth rather than mechanical throughput alone.
Electronic herd monitoring is digitizing udder health management through real-time somatic cell count analysis and automated teat condition scoring. Large-scale operations in the Netherlands are deploying these systems at replacement rates exceeding conventional parlors. The technology is digitizing veterinary decision-making by flagging individual cows for selective dry-off protocols.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in bulk milk cooling systems, with propane and CO2 architectures displacing hydrofluorocarbon-dependent units. German equipment suppliers face compressed certification timelines for new cooling circuit designs. Dairy cooperatives in Denmark are absorbing retrofit costs through energy-efficiency subsidy programs.
Service contract unbundling is fragmenting traditional bundled maintenance relationships, with specialized firms now competing for vacuum pump overhaul and pulsator calibration separately from OEM service arms. Mid-sized Wisconsin operations are sourcing aftermarket support through independent technicians. This pattern concentrates in North American markets where dealer density supports competitive service fragmentation.
Milking Equipment Market Segmentation
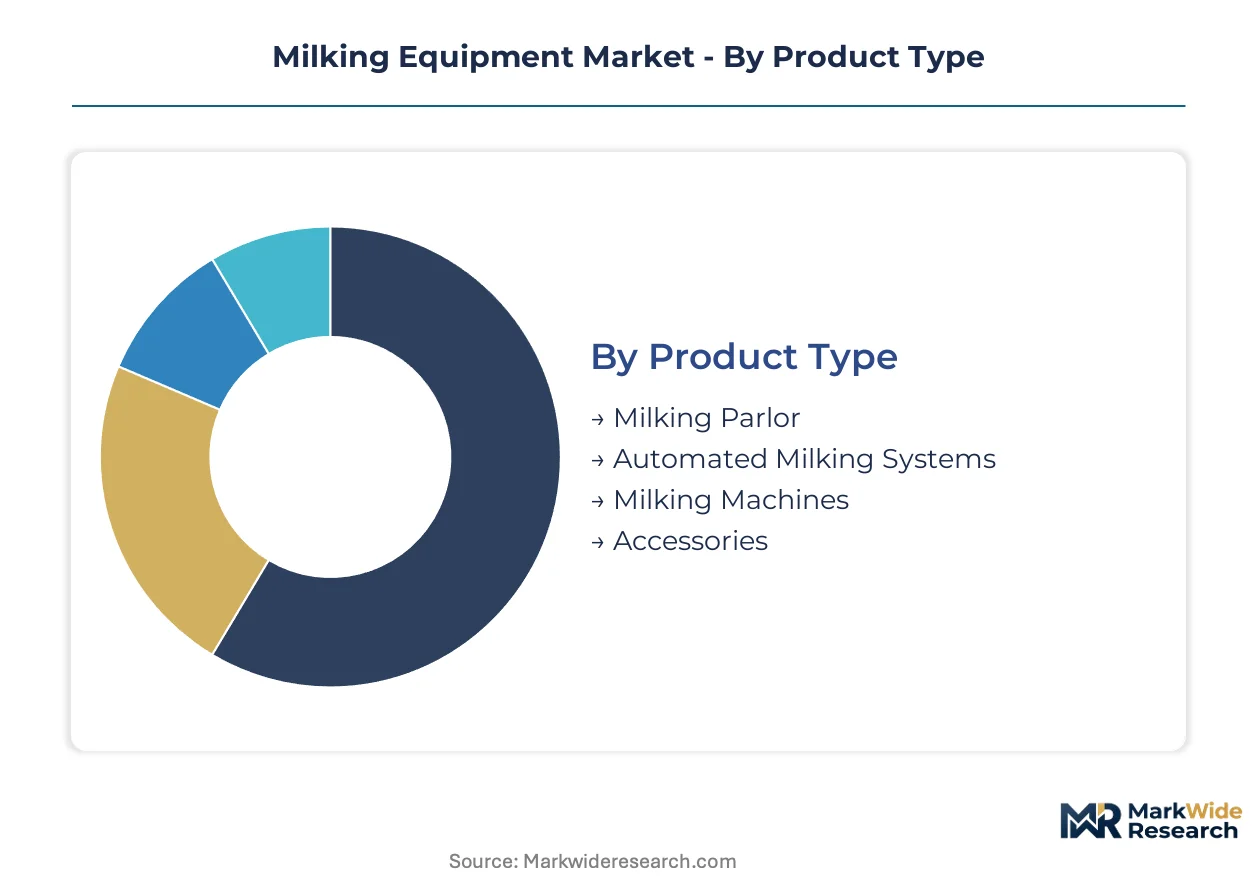
Milking equipment segmentation reflects divergent capital strategies across herd scales and regulatory environments. Equipment categories span from standardized parlor hardware to sensor-integrated robotic platforms, each serving distinct operational constraints and compliance timelines.
Product Type:
Mature parlor configurations dominate installed base volume, while emerging autonomous platforms reshape capital allocation patterns among large-scale operators.
- Milking Parlor:Herringbone and rotary configurations built from stainless steel pipelines and vacuum-driven clusters remain the volume backbone across emerging markets. Dairy cooperatives in India and Brazil prioritize these systems for herds between 50 and 200 cows where robotic payback periods exceed operational planning horizons.
- Automated Milking Systems:Robotic arms with teat-detection cameras and automated gate systems enable 24-hour unmanned operation. German and Dutch farms above 150 cows are concentrating procurement here as labor contracts tighten and EU Ecodesign deadlines approach.
- Milking Machines:Portable bucket and direct-to-can units serve smallholder operations with sub-50-cow herds across Sub-Saharan Africa and Central Asia.
- Accessories:Pulsators, vacuum regulators, and cleaning-in-place modules constitute recurring replacement demand.
Milking parlors handle the majority of throughput; automated milking systems are climbing the fastest on share.
End User:
Cost tier stratification separates integrated cooperatives from fragmented smallholder procurement patterns.
- Dairy Farms:Independent operations with 100-500 cows represent the core revenue pool for mid-tier equipment suppliers. Wisconsin and California operations face OSHA ergonomic mandates that accelerate replacement cycles for manual lifting equipment.
- Livestock Producers:Diversified agricultural operations with secondary dairy lines prioritize mobile and semi-permanent installations. Australian pasture-based systems favor these configurations for seasonal flexibility.
- Agricultural Cooperatives:Pooled procurement entities in Denmark and the Netherlands negotiate volume discounts on robotic systems and shared service contracts.
- Research Institutions:Veterinary schools and breeding centers drive demand for precision monitoring components with open data architectures.
Dairy farms absorb the largest equipment volume; agricultural cooperatives are expanding most quickly as collective financing models mature.
Technology:
Application intensity varies from mechanical vacuum systems to algorithm-driven health monitoring platforms.
- Vacuum Technology:Oil-sealed and oil-free vacuum pumps constitute the foundational extraction mechanism across all system tiers. EU Ecodesign efficiency mandates are forcing hardware refreshes ahead of standard replacement cycles.
- Pulsation Control:Electronic pulsators with adjustable ratios protect teat condition and optimize milk flow rates. These components see replacement demand every 5-7 years across European installed bases.
- Electronic Monitoring:Conductivity sensors and flow meters enable real-time somatic cell count estimation. New Zealand pasture operations are integrating these with cloud-based herd management platforms.
- Robotic Milking:Autonomous teat attachment with 3D vision and machine learning algorithms eliminates manual intervention. Premium positioning targets operations above 200 cows with 24-hour production schedules.
Vacuum technology underpins the majority of installed systems; electronic monitoring is gaining share fastest as precision livestock farming converges on single-platform investments.
Installation:
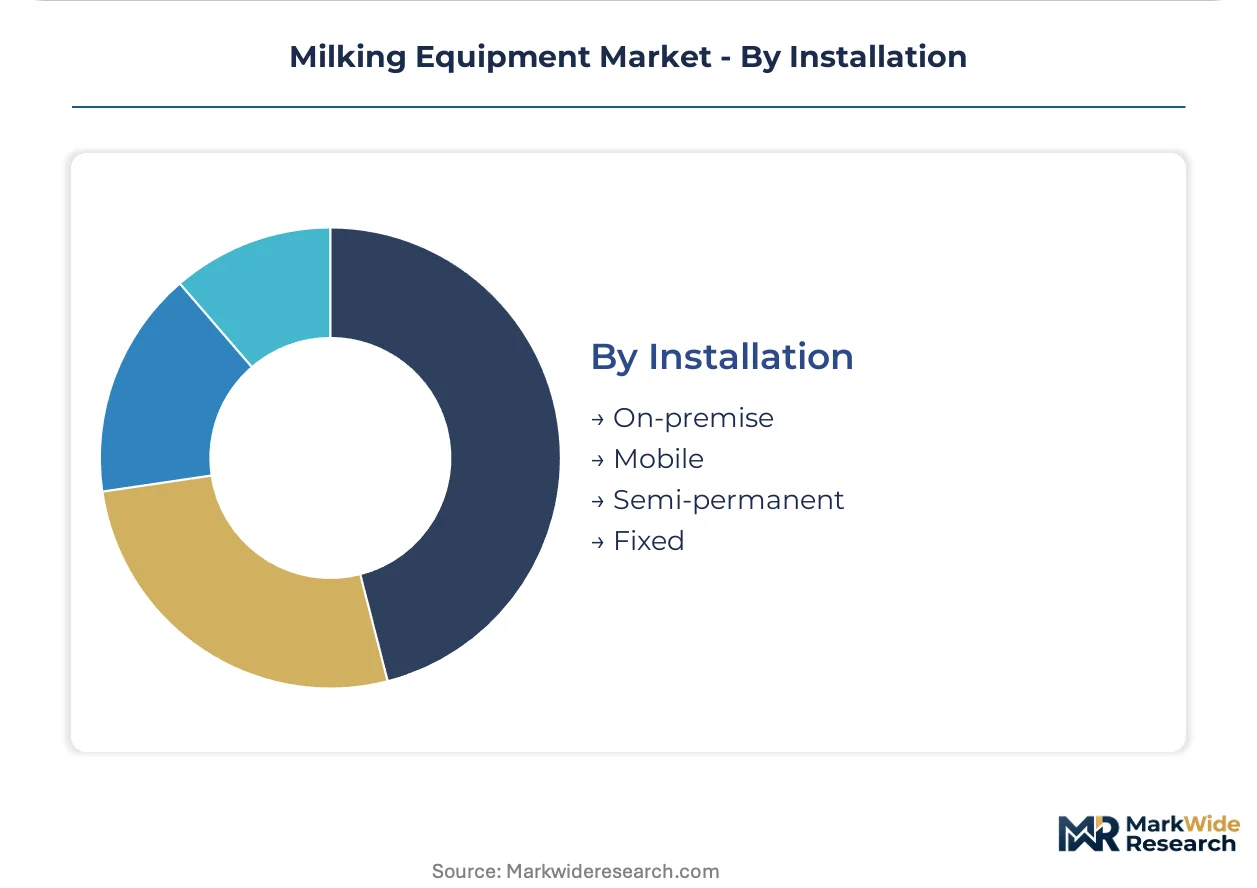
Customer type and geography dictate mobility requirements across permanent infrastructure and seasonal deployments.
- On-premise:Fixed concrete foundations with embedded pipeline networks serve large-scale operations with decade-long facility horizons. These installations dominate North American and European markets with established dairy infrastructure.
- Mobile:Trailer-mounted units with self-contained power and vacuum systems enable rotational grazing across extensive pasture operations. Australian and Argentine systems favor this approach for seasonal herd movements.
- Semi-permanent:Modular skid-mounted configurations balance relocation flexibility with operational stability. Emerging markets in Eastern Europe and Southeast Asia deploy these for intermediate-scale cooperatives testing expansion viability.
- Fixed:Purpose-built parlors with integrated cooling and waste management represent the highest capital commitment tier.
Fixed installations anchor the majority of capital deployed; mobile systems are expanding most quickly in pasture-dominated geographies with land tenure constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Ecodesign mandates on vacuum pump efficiency are accelerating equipment replacement cycles across European dairy operations, while labor cost pressures in Oceania and ergonomic enforcement in North America reshape procurement priorities.
Germany
Dairy cooperatives in Lower Saxony and Bavaria are consolidating robotic milking procurement through shared service contracts. The EU Ecodesign directive forces vacuum pump replacements ahead of standard cycles. Equipment manufacturers in Baden-Württemberg are reengineering cooling circuit designs to meet compressed F-Gas Regulation certification timelines.
United States
Wisconsin and California dairy operations face escalating OSHA scrutiny on repetitive strain injuries, driving demand for automated lifting mechanisms. FDA dairy equipment sanitation standards define compliance thresholds for interstate commerce. The Midwest dairy belt around Madison and Green Bay concentrates precision livestock farming technology deployment.
Netherlands
Farms above 200 cows in Friesland and Gelderland are concentrating procurement in fully autonomous systems as labor contracts tighten. EU Green Deal subsidies absorb retrofit costs for energy-efficient cooling architectures. The Dutch dairy cluster around Leeuwarden leads European adoption of sensor-integrated herd management platforms.
New Zealand
Pasture-based operations in Waikato and Canterbury are expanding robotic milking adoption as agricultural labor costs escalate. The country's national agricultural regulator enforces dairy hygiene standards that favor stainless steel construction with automated cleaning protocols. Equipment suppliers in Hamilton anchor service networks across the North Island dairy belt.
Denmark
Agricultural cooperatives in Jutland negotiate volume discounts on robotic systems and shared maintenance contracts. National energy-efficiency subsidy programs offset cooling system retrofit costs. The central dairy region around Viborg and Herning concentrates automated milking deployment at replacement rates exceeding conventional parlors.
Milking Equipment Market Key Industry Players
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where integrated service capabilities anchor customer retention. The vendor base stratifies between full-system integrators with captive component supply and modular equipment specialists serving aftermarket replacement demand. Two dominant archetypes emerge: vertically integrated platform providers bundling hardware with recurring service contracts, and component-focused fabricators supplying vacuum pumps and pulsation equipment to third-party assemblers. Competitive moves center on pay-per-milk financing expansion and sensor convergence into single-platform investments.
Within the integrated platform tier, DeLaval and GEA Group exemplify archetypes combining hardware manufacturing with long-term service anchoring. Lely occupies a position representing fully autonomous robotic specialization for large-herd unmanned operations. Among these, DeLaval and GEA Group sit within the European-origin cohort leveraging regional regulatory pressure to accelerate customer upgrade cycles, while Lely anchors the Dutch-based cluster serving pasture-system automation demand.
| Leading Market Players |
|---|
| DeLaval |
| GEA Group |
| Lely |
| BouMatic |
| Afimilk |
| Nedap |
| Fullwood Packo |
| Waikato Milking Systems |
| Dairymaster |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese stainless steel fabrication is compressing margin buffers for European tank and pipeline manufacturers, forcing procurement teams to rebalance cost-quality tradeoffs while OEMs defend premium positioning through ISO 5707 certification anchoring.
Pricing Analysis
Certification level creates the primary spread between economy-grade portable units and FDA-validated robotic platforms. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 5707 compliance depth, after-sales service bundling, and geographic delivery cost layering. Pricing pressure stems from Grade 304 and 316 stainless steel volatility, with spot market swings compressing fabricator margins in the tank and pipeline tier. Smallholder operations across Sub-Saharan Africa exhibit highest price sensitivity, while Dutch cooperatives above 200 cows prioritize total-cost-of-ownership over upfront capital outlay.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are emerging as competitive weapons among German and Dutch equipment financiers. Component sourcing concentrates in Germany for vacuum pump assemblies, China for electronic sensor modules, and New Zealand for pasture-optimized robotic arm fabrication. Raw material dependencies rest on nickel-alloyed stainless steel grades, food-grade rubber liner compounds, and rare-earth magnets for precision motor drives. Single-source vulnerability in semiconductor-based teat-detection cameras creates chokepoint exposure. Distribution runs through authorized dealer networks in mature markets and agricultural cooperative procurement pools in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
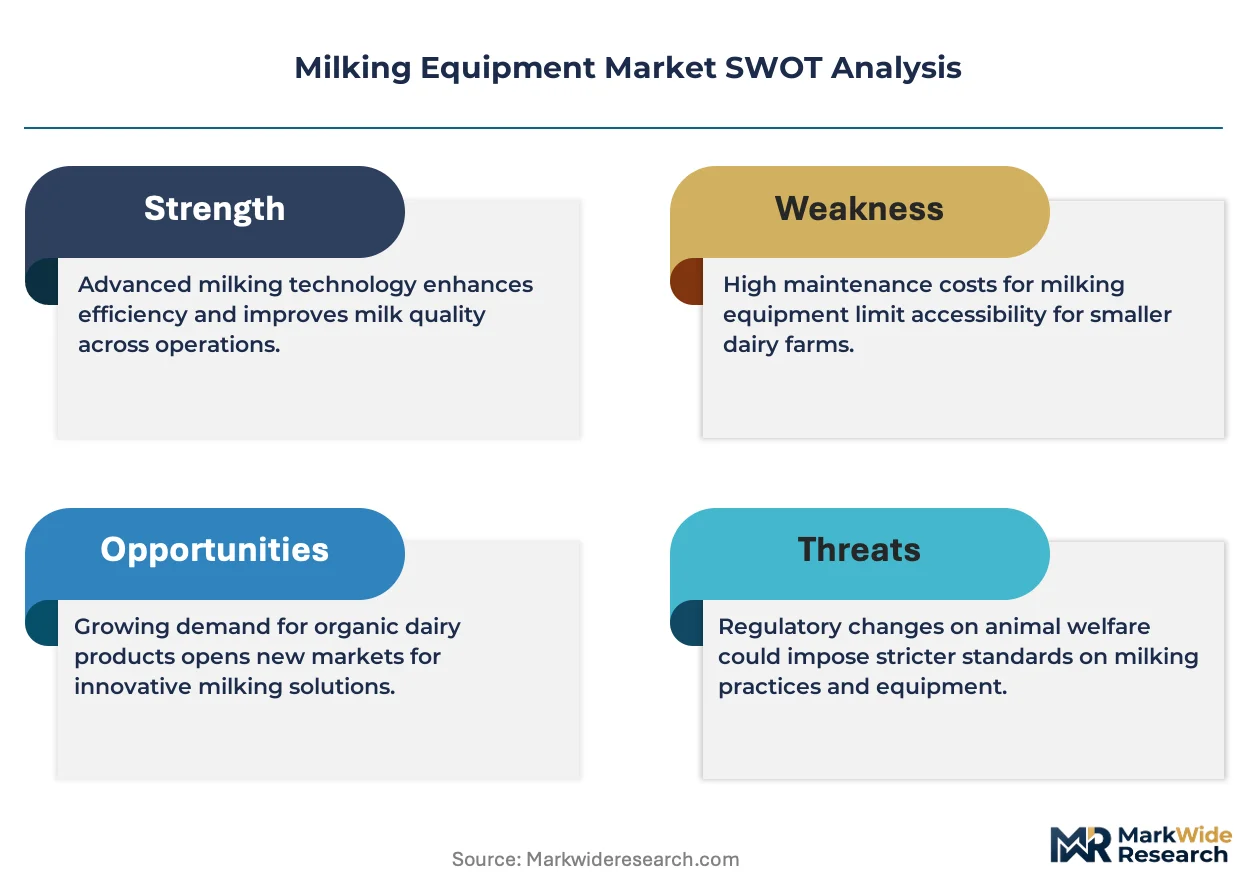
The milking equipment market operates as a defensive-moat structure where regulatory entrenchment through FDA and EU Ecodesign compliance creates high switching costs that cement incumbent positions.
For Market Incumbents: Entrench service contract density through predictive maintenance platforms that lock in recurring revenue streams. Deepen backward integration into vacuum pump and cooling component supply to offset stainless steel margin compression. Defend against pay-per-milk financing disruptors by embedding usage-based pricing within existing customer relationships. For New Entrants and Emerging Players: Pursue aftermarket service fragmentation in North American markets where independent technician networks challenge OEM service arms. Target mid-sized Wisconsin and California operations facing OSHA ergonomic mandates with retrofit automation kits. Lead with sensor convergence platforms that merge fertility tracking and mastitis detection into single-dashboard investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across pay-per-milk financing models as hardware-as-a-service structures reduce customer acquisition friction. Viable acquisition targets include specialized sensor-software hybrids with open data architectures compatible with multi-vendor dairy operations. Monitor EU F-Gas Regulation phase-down schedules as inflection signals for cooling system retrofit demand waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Pump Manufacturing | Captive supply of Ecodesign-compliant components secures margin control against stainless steel volatility. |
| Sensor Convergence Platform Development | Merged fertility-mastitis algorithms create single-platform value propositions for precision livestock farming adopters. |
| Pay-per-Milk Financing Expansion | Usage-based leasing penetrates mid-sized German operations previously excluded from robotic procurement. |
| Cleaning-in-Place Automation Investment | Automated chemical dosing reduces labor hours in 24-hour unmanned Oceania operations. |
| Electromechanical Technician Training Programs | Specialized calibration skills address scarcity constraints in rural labor pools across pasture-based systems. |
Research Approach
Initial hypotheses were tested against primary input from dairy farm operations managers, agricultural cooperative procurement directors, OEM service technicians, and herd management software integrators and refined through secondary validation against EU Ecodesign directive filings, FDA dairy equipment sanitation standards, ISO 5707 certification databases, and agricultural machinery trade flow records. Bottom-up equipment shipment data triangulated against top-down dairy herd size and replacement cycle estimates.
Demand-supply balance modeling across the projection horizon incorporated vacuum pump efficiency upgrade cycles, robotic system payback period sensitivity, and labor cost trajectory assumptions. Segmentation dimensions spanned product type, herd scale tier, installation mobility, and regional regulatory cluster. CAGRs derived from equipment replacement rate elasticity and technology adoption S-curve positioning. Industry-specific inputs included EU F-Gas Regulation phase-down schedules and OSHA ergonomic enforcement intensity indices.
Sensitivities concentrate around stainless steel price volatility, electromechanical technician availability, and multi-vendor data protocol standardization. Forecasts reflect documented assumptions on herd consolidation trajectories and subsidy program continuity. Macroeconomic deviation, regulatory timeline acceleration, or autonomous teat-attachment breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Sheep Supplies Market
Livestock Equipment
Chicken Feeder and Drinkers Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Animal Workstations Market
Livestock Equipment
Livestock Carrier Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Animal Feeding Equipment Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Electric Fencing Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Cow Lifting Harness Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Wire Livestock Panels Market
Livestock Equipment
Russia Horse Riding Equipment Market