
 Live Chat Software Market | 2026-2036
Live Chat Software Market Size, Share, and Industry Trends Forecast 2026-2036
Live Chat Software Market Intelligence
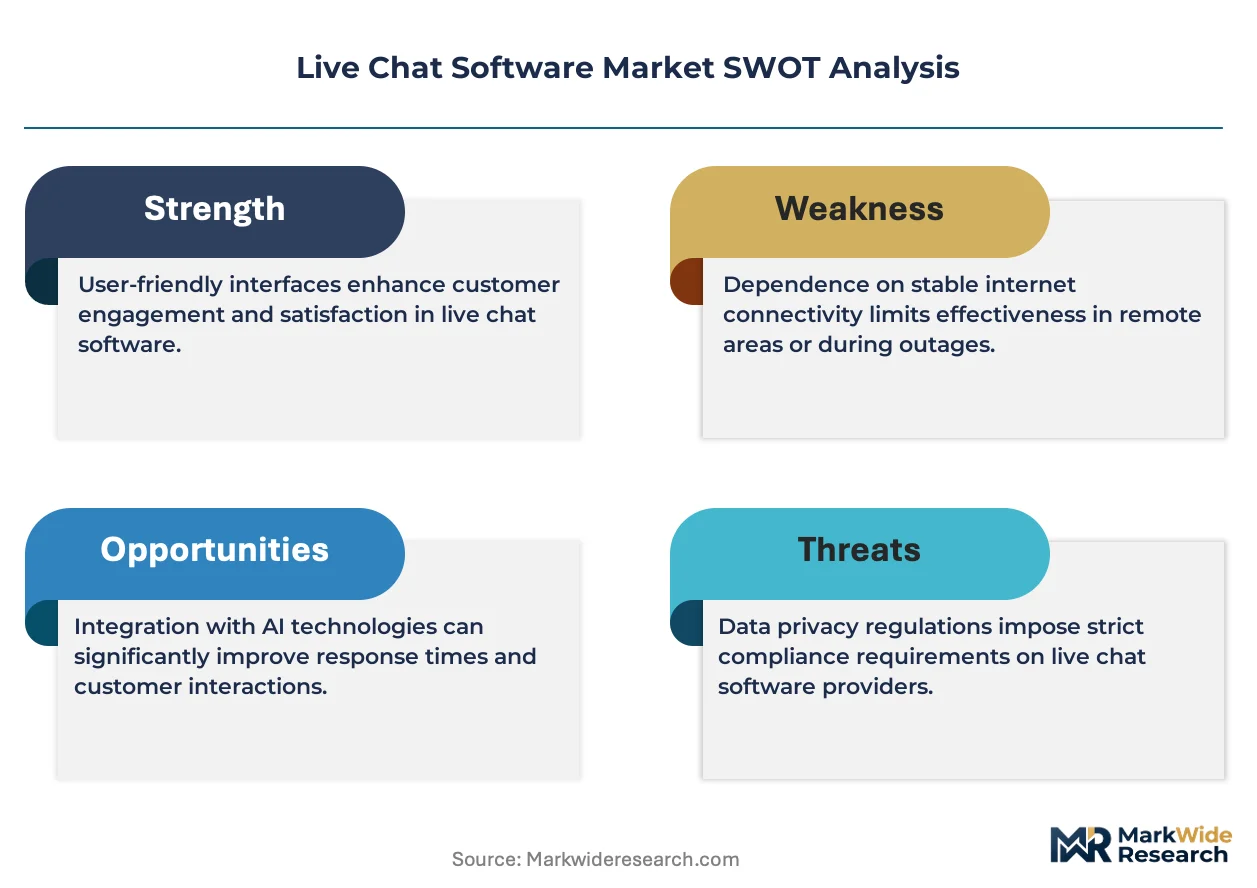
Enterprise-grade security certification is unwinding competitive dynamics across the live chat software landscape. Zendesk leverages its established ticketing infrastructure to anchor multi-channel service suites. Tidio specializes in AI-powered conversational automation for mid-market retailers. LiveChat.com sustains brand recognition through dedicated channel control in European markets.
Live chat software constitutes real-time messaging platforms enabling synchronous text-based communication between businesses and customers, typically integrating natural language processing engines and sub-second response latency thresholds for operational effectiveness. Cloud-based deployment leads structural adoption as organizations prioritize elastic scaling and reduced infrastructure overhead, while multichannel support capabilities capture expanding margin pools as vendors bundle voice, social, and messaging APIs into unified agent dashboards. Small businesses represent the fastest-growing user tier, drawn by freemium entry points and low-code customization interfaces.
FCC guidelines on telecommunications data handling and GDPR requirements in Europe constrain cross-border data routing architectures for live chat providers serving multinational clients. ISO 27001 certification has become a de facto market access threshold for enterprise procurement committees evaluating vendor shortlists. Stakeholders must monitor evolving AI disclosure mandates from regulators as automated response features proliferate across customer-facing deployments.
Market Dynamics
AI-native agent architectures are forcing incumbent live chat vendors to rebuild core inference stacks rather than bolt automation onto legacy messaging rails, compressing R&D timelines and recalibrating competitive moats around model latency rather than interface design.
Growth Catalysts
- GDPR Article 32 compliance mandates:European enterprises face binding technical and organizational measures for personal data security in customer communications, accelerating procurement of certified live chat platforms with built-in encryption and audit trails.
- Small business digitalization:Sub-50-employee retailers adopt freemium live chat tools to close conversion gaps against larger competitors, drawn by no-code bot builders and native e-commerce platform integrations.
- Natural language processing engines:Transformer-based intent classification now operates at sub-500-millisecond latency, enabling real-time sentiment routing that reduces agent handling costs for high-volume service operations.
Market Restraints
- Cloud infrastructure concentration:Three hyperscalers control the majority of GPU compute availability for AI inference workloads, creating supply risk and pricing volatility for live chat vendors training or fine-tuning proprietary models.
- FCC telecommunications data handling guidelines:US-based providers serving financial services clients must maintain call and chat records under specific retention and accessibility standards, adding compliance overhead that slows feature release cycles.
- API rate limiting:Messaging platform dependencies—particularly WhatsApp Business and Apple Business Chat—impose hard throughput ceilings that constrain enterprise scale deployments during peak traffic periods.
Strategic Opportunities
- India data localization requirements:The Reserve Bank of India and Ministry of Electronics and Information Technology mandate domestic data storage for financial and government customer interactions, creating whitespace for regional hosting partnerships and in-country infrastructure investment.
- Voice-to-text convergence:Real-time speech recognition integrated with live chat threading enables unified agent desktops that collapse voice and messaging into single-pane workflows, opening new subscription tiers for contact center modernization.
- ISO 27001 certification as procurement filter:Enterprise security committees now exclude non-certified vendors from RFP shortlists, creating a certification tailwind for compliant providers to capture mid-market accounts upgrading from consumer-grade tools.
Industry Challenges
- Machine learning operations talent scarcity:Live chat vendors struggle to hire ML engineers capable of deploying, monitoring, and retraining production intent models, forcing reliance on expensive contractor networks or delayed automation roadmaps.
- Legacy CRM integration complexity:Enterprises running on-premise Salesforce or Oracle Service Cloud instances require custom middleware development to sync real-time chat transcripts, extending implementation timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Chat Software Market |
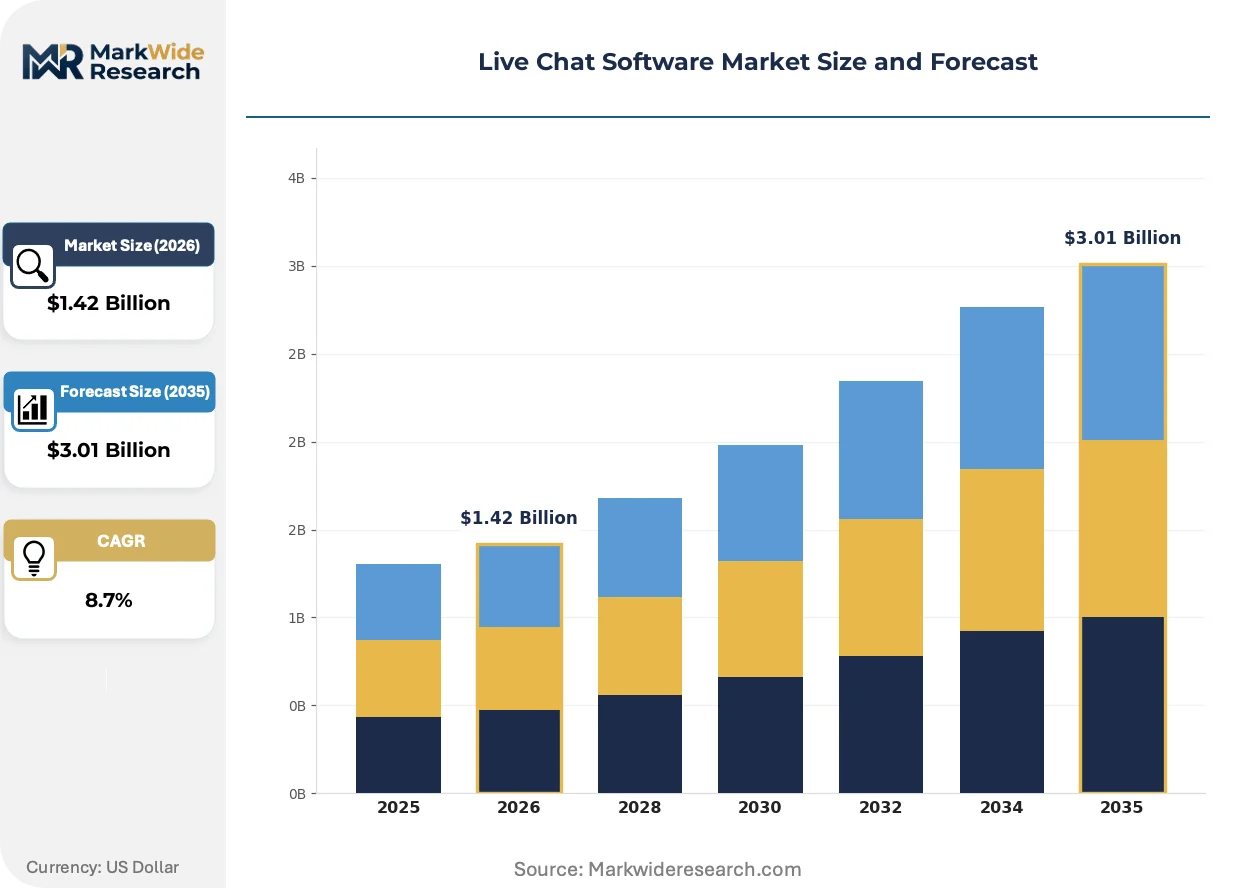
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $3.01 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, E-commerce, Healthcare, Telecommunications Feature Set: Automated Responses, Multichannel Support, Analytics, Customization Business Size: Small Businesses, Medium Enterprises, Large Corporations, Startups |
| Companies Covered | Tidio, Superchat, Zendesk, MessengerPeople, Smartsupp, LiveChat.com, Chatarmin, Brevo, Lime Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Chat Software Market Strategic Shifts & Innovations
Monolithic customer service suites are fragmenting into composable API stacks, allowing buyers to assemble best-of-breed messaging, automation, and analytics layers rather than accepting bundled vendor lock-in.
Large language model fine-tuning is decomposing the traditional chatbot build process. Mid-market retailers now deploy domain-specific conversational agents within weeks rather than quarters, bypassing the intent-mapping bottleneck that previously required months of manual training data curation. This compression is enabling smaller vendors to compete on implementation velocity against established ticketing incumbents.
EU AI Act risk classification requirements are reshaping procurement criteria for automated customer-facing systems. Live chat platforms deploying generative response features must now document model training data provenance and establish human oversight protocols for high-risk use cases, particularly in financial services and healthcare verticals. German and French enterprise buyers are leading this compliance-driven vendor re-evaluation.
Subscription packaging is rotating toward consumption-based metering. E-commerce merchants increasingly reject per-agent seat models in favor of per-conversation or per-resolution pricing that aligns vendor revenue with actual customer outcomes. This shift is most pronounced among direct-to-consumer brands in the United States operating seasonal demand spikes.
Live Chat Software Market Segmentation
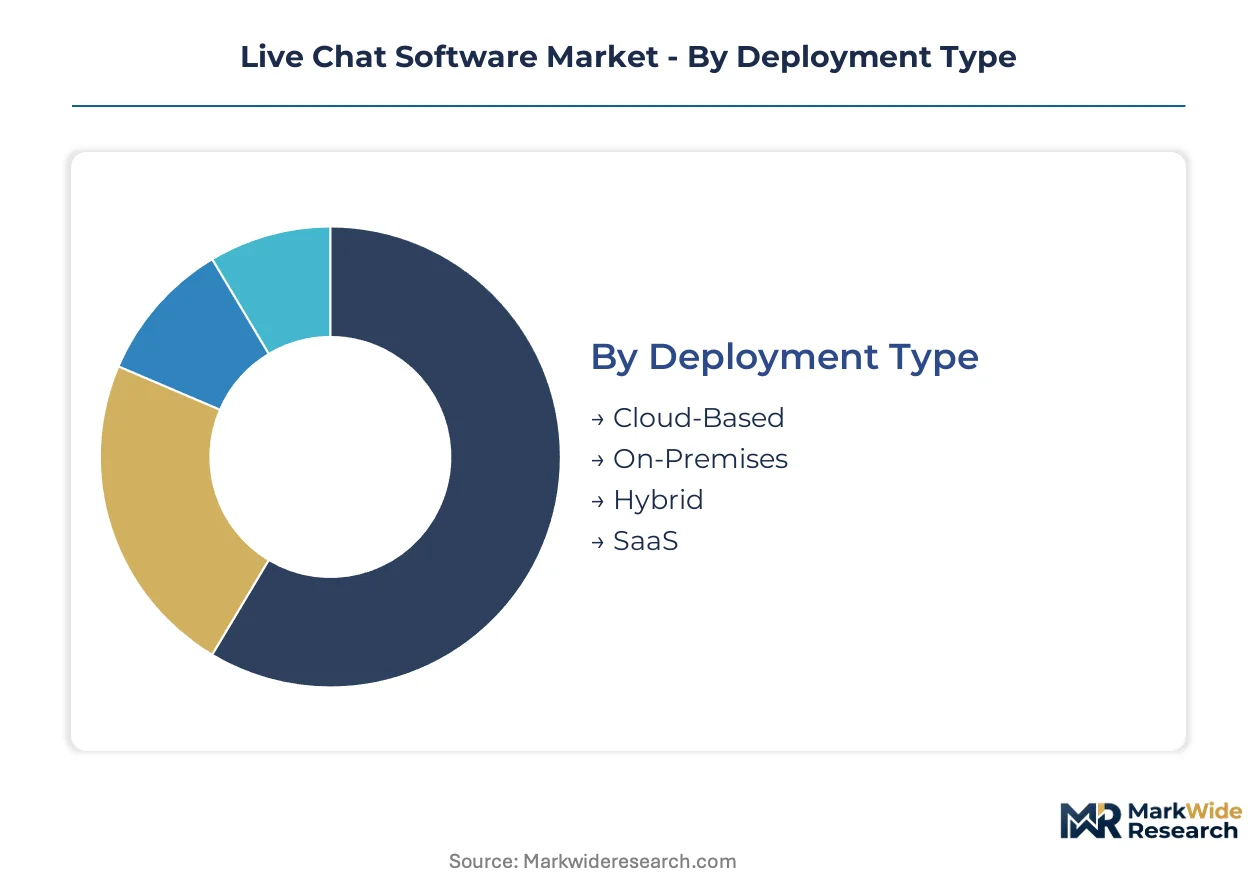
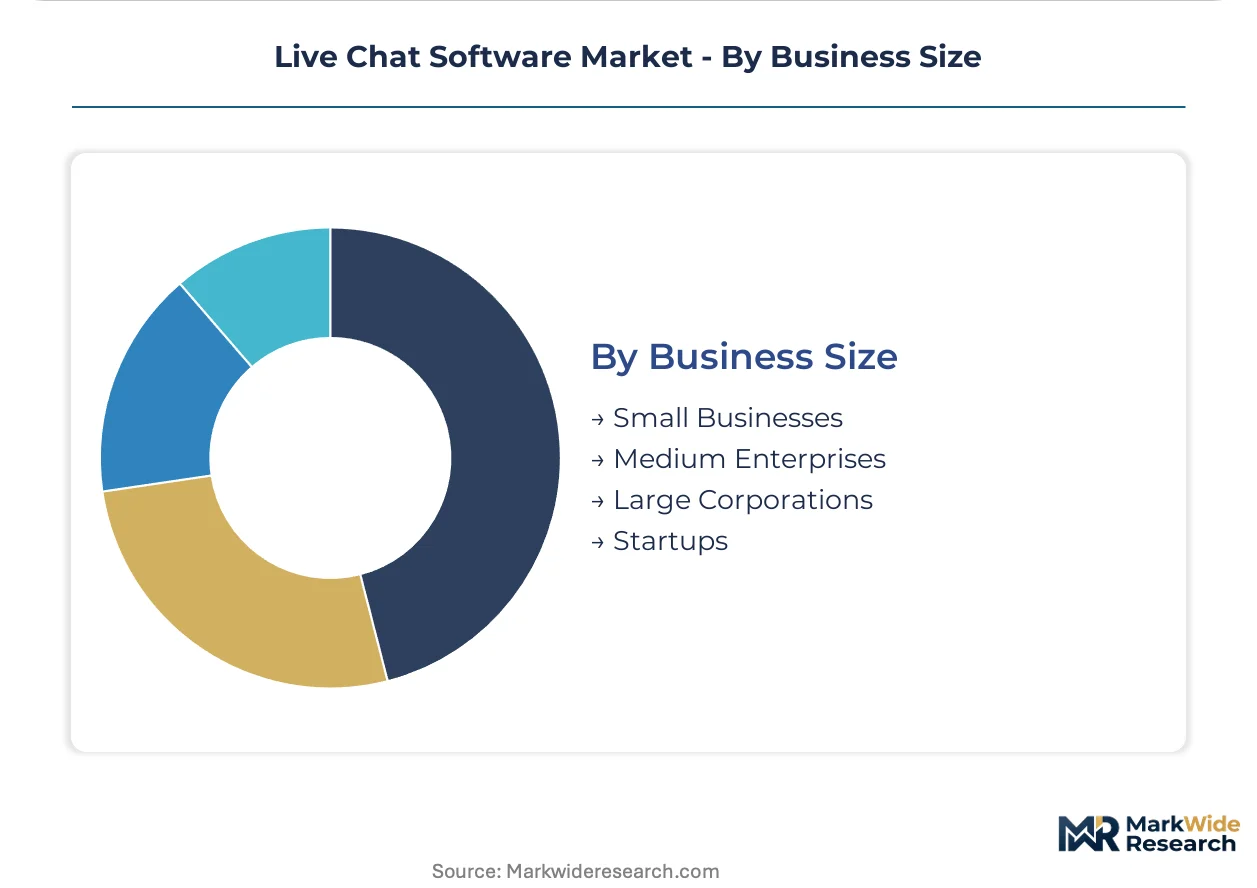
Live chat software vendors architect product roadmaps around four distinct segmentation axes. Deployment preferences determine infrastructure investment patterns, while end-user verticals dictate compliance and integration requirements that separate winning platforms from also-rans.
Deployment Type:
Geographic spread varies sharply across deployment modes, with cloud-based solutions dominating cross-border enterprise rollouts while on-premises installations concentrate in data-sovereignty-sensitive domestic markets.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning enable sub-second latency across distributed edge nodes. Demand concentrates among United States e-commerce merchants scaling through seasonal traffic spikes, constrained by GDPR Article 32 encryption mandates for European customer data.
- On-Premises:Single-tenant installations on customer-managed hardware with full source code escrow. German financial services and Indian public sector banks drive procurement, compelled by Bundesbank and RBI data localization directives that prohibit cross-border data transit.
- Hybrid:Split architectures routing sensitive conversations through on-premises cores while offloading routine queries to cloud inference endpoints.
- SaaS:Fully managed subscription tiers with zero infrastructure ownership, capturing sub-50-employee retailers through freemium entry points and native platform integrations.
Cloud-based deployment holds the largest share; momentum sits with hybrid configurations as enterprises balance AI capability access against sovereignty requirements.
End User:
Customer lifetime value and conversation complexity create tiered pricing power across vertical applications, with healthcare and telecommunications commanding premium seat rates due to specialized compliance overhead.
- Retail:High-volume, low-complexity interactions requiring real-time inventory lookup and promotional code validation. United States direct-to-consumer brands deploy AI-native agents for cart abandonment recovery, facing FTC disclosure requirements for automated response systems.
- E-commerce:Transactional platforms integrating payment gateways, order tracking, and return processing into threaded conversation flows. European marketplaces accelerate procurement following EU AI Act risk classification mandates for customer-facing automation.
- Healthcare:HIPAA-compliant messaging with encrypted PHI handling and audit-grade transcript retention. United States hospital systems and telehealth providers drive demand, constrained by FDA oversight of diagnostic chatbot claims.
- Telecommunications:Technical support workflows integrating network status APIs and subscription management into unified agent desktops.
E-commerce holds the largest share; healthcare represents the steepest expansion trajectory as HIPAA-compliant automation penetrates hospital system procurement cycles.
Feature Set:
Capability bundling determines competitive positioning, with AI-powered features commanding 40-60% seat rate premiums over baseline messaging tiers while analytics modules anchor enterprise renewal decisions.
- Automated Responses:Transformer-based intent classification with sub-500-millisecond inference latency, enabling real-time sentiment routing. Indian BPOs and United States high-volume service operations deploy these systems to compress agent handling costs, navigating EU AI Act documentation requirements for high-risk financial services deployments.
- Multichannel Support:Unified threading across WhatsApp Business, Apple Business Chat, SMS, and proprietary web widgets. European retailers prioritize this capability to meet consumer channel preferences, limited by API rate ceilings during peak traffic periods.
- Analytics:Conversation mining for intent clustering, agent performance scoring, and predictive churn signals.
- Customization:No-code workflow builders and white-label interface branding for mid-market differentiation.
Automated responses hold the largest share; multichannel support is gaining share fastest as vendors bundle voice-to-text convergence into subscription tiers.
Business Size:
Procurement authority and implementation complexity fragment vendor go-to-market strategies, with enterprise accounts demanding ISO 27001 certification while small businesses prioritize instant activation over security depth.
- Small Businesses:Freemium tiers with conversation volume caps and self-service onboarding. Sub-50-employee United States retailers adopt these tools to close conversion gaps against larger competitors, drawn by no-code bot builders and Shopify-native integrations.
- Medium Enterprises:Professional tiers with SLA guarantees, custom API access, and dedicated success management. German and French mid-market manufacturers drive regional demand, compelled by CSRD reporting requirements for customer service metrics.
- Large Corporations:Enterprise agreements with custom model fine-tuning, on-premises deployment options, and professional services bundles.
- Startups:Growth-stage pricing with deferred billing and investor-friendly usage reporting.
Medium enterprises hold the largest share; small businesses are expanding most quickly as digitalization accelerates among sub-50-employee retailers competing against larger e-commerce platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The live chat software trade balance tilts toward net service exports from established SaaS hubs, with import demand concentrated in jurisdictions enforcing strict data sovereignty mandates. Cross-border procurement flows through regional hosting partnerships rather than direct vendor-to-customer relationships.
United States
Enterprise SaaS procurement and direct-to-consumer e-commerce expansion anchor domestic demand. FTC disclosure requirements for automated response systems constrain AI-native feature rollouts. Silicon Valley and New York Metro clusters concentrate vendor headquarters and enterprise sales operations.
Germany
Mid-market manufacturers and automotive suppliers drive professional-tier adoption for customer service modernization. Bundesbank data localization directives and GDPR Article 32 compliance mandates restrict cross-border data routing. Bavaria and Baden-Württemberg industrial corridors host dense concentrations of ISO 27001-certified deployments.
India
Domestic BPOs and high-volume service operations deploy transformer-based intent classification to compress agent handling costs. RBI and Ministry of Electronics and Information Technology data localization rules mandate domestic storage for financial customer interactions. Bangalore and Hyderabad technology clusters anchor regional hosting infrastructure investments.
United Kingdom
Financial services and telecommunications verticals sustain premium-tier demand for multichannel support capabilities. UK GDPR alignment post-Brexit maintains encryption and audit trail requirements equivalent to EU standards. London fintech corridor concentrates procurement authority for enterprise agreements.
Japan
Telecommunications and retail verticals adopt unified agent desktops integrating voice-to-text convergence. METI guidelines on AI disclosure shape procurement criteria for automated customer-facing systems. Tokyo-Osaka corridor hosts concentrated demand for HIPAA-equivalent healthcare messaging compliance.
Live Chat Software Market Key Industry Players
Listed leaders compete with private specialists across certification depth and AI-native architecture maturity. The vendor base separates into three tiers: enterprise suite providers with established ticketing infrastructure, mid-market automation specialists, and freemium-native platforms targeting sub-50-employee retailers. Strategic archetypes include multi-channel consolidators, AI-first conversational platforms, and regional compliance-focused hosts. Dominant competitive moves center on ISO 27001 certification acquisition for enterprise RFP access and voice-to-text convergence bundling for contact center modernization.
Within the AI-native tier, Tidio and Chatarmin exemplify mid-market automation specialists leveraging transformer-based intent classification for rapid deployment velocity. Among established platform providers, Zendesk occupies a position representing enterprise suite consolidation with embedded ticketing infrastructure. On the regional compliance vector, LiveChat.com anchors European market presence through dedicated channel control and GDPR-aligned hosting architectures.
| Leading Market Players |
|---|
| Tidio |
| Superchat |
| Zendesk |
| MessengerPeople |
| Smartsupp |
| LiveChat.com |
| Chatarmin |
| Brevo |
| Lime Connect |
| Others |
Cost & Logistics Intelligence
ISO 27001 certification gates both vendor qualification and price tiering in enterprise live chat procurement, compressing margins for uncertified providers while enabling compliant vendors to capture premium subscription rates from security-sensitive buyers.
Pricing Analysis
Enterprise SaaS buyers anchor subscription pricing around per-agent seat models, though consumption-based metering gains traction among seasonal e-commerce merchants. Three-tier pricing structure across premium AI-native, standard multichannel, and economy self-service levels separates vendors by automation depth and compliance grade. Cost compression in mid-market tiers intensifies as freemium-native platforms expand feature parity. Small businesses exhibit highest price sensitivity, while healthcare and financial services verticals absorb premium rates for HIPAA-aligned and audit-grade deployments.
Supply Chain Analysis
GPU inventory lead times for AI inference hardware stretch vendor procurement cycles, forcing reliance on cloud hyperscaler reservations rather than dedicated infrastructure ownership. Compute provisioning concentrates in United States, Ireland, and Singapore data center clusters. Transformer model development rests on licensed training data and open-source foundation weights. Single-source vulnerability sits with three hyperscalers controlling GPU availability. Distribution runs through direct vendor sales for enterprise accounts and self-serve platforms for sub-50-employee retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power shifts toward enterprise procurement committees consolidating vendor shortlists around ISO 27001 certification, fragmenting competitive access for uncertified specialists.
For Market Incumbents: Compound defensive moats by embedding voice-to-text convergence into existing ticketing infrastructure before AI-native challengers capture contact center modernization budgets. Acquire regional hosting partnerships in India and Germany to satisfy RBI and Bundesbank data localization mandates. Prioritize certification maintenance over feature velocity as procurement committees harden security requirements.
For New Entrants and Emerging Players: Differentiate on implementation velocity for mid-market retailers seeking rapid AI bot deployment without legacy integration complexity. Target sub-50-employee United States e-commerce merchants underserved by enterprise suite configurability. Pursue native Shopify and WooCommerce integrations as primary go-to-market channel.
For Investors and Strategic Acquirers: EU AI Act risk classification mandates reshape the acquisition landscape toward vendors with documented model provenance and human oversight protocols. Five-to-ten year viability favors AI-native architectures with transformer-based intent classification over legacy rule-based systems. Monitor FDA and EMA guidance on diagnostic chatbot claims as inflection indicator for healthcare vertical expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 27001 Certification Acquisition | Unlocks enterprise RFP access as procurement committees exclude non-certified vendors from shortlists. |
| Voice-to-Text Convergence Bundling | Enables unified agent desktops that collapse voice and messaging into single-pane contact center workflows. |
| Regional Hosting Partnership | Satisfies RBI and Bundesbank data localization directives prohibiting cross-border customer data transit. |
| AI-Native Architecture Migration | Replaces legacy rule-based bots with transformer-based intent classification for sub-500ms response latency. |
| Consumption-Based Pricing Launch | Aligns vendor revenue with per-conversation outcomes for seasonal e-commerce merchant demand patterns. |
Research Approach
Desk research of vendor pricing disclosures, hyperscaler infrastructure reports, and regulatory filing databases preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across United States, German, and Indian technology clusters. Primary intelligence combined with secondary validation from SEC filings, App Annie mobile platform data, and hyperscaler capex disclosures. Bottom-up deployment estimates triangulated against top-down SaaS market sizing.
Variance decomposition across deployment model, organization size, vertical compliance requirements, and regional adoption patterns anchored the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated AI inference cost curves and data localization mandate implementation timelines.
Material uncertainties — regulatory enforcement intensity, hyperscaler GPU allocation policies, and EU AI Act interpretation guidance — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these industry-specific risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Ccaas Software Market
Software & Services
Statistics Software Market
Software & Services
Global Pre-Employment Testing Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Content As a Service (Caas) Market
Software & Services
Systems Administration Management Tools Market
Software & Services
Mobile Application Stores Market
Software & Services
Saas-Based SCM Market
Software & Services
Pay-Per-Click (PPC) Software Market
Software & Services
Website Builder Tool Market
Software & Services
Hydraulic Modeling Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Geophysical Software Service Market
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Payroll - HR Solutions and Services Market