
 Content As a Service (Caas) Market | 2026-2036
Content As a Service (Caas) Market Size, Share, and Industry Trends Forecast 2026-2036
Content As a Service (Caas) Market Outlook
E-commerce and digital retail is hardening as the dominant demand vertical for headless content infrastructure. Contentful leverages extensive API-first architecture to sustain developer mindshare across mid-market and enterprise accounts. Sitecore anchors premium positioning through deep personalization capabilities and hybrid deployment flexibility. Sanity competes aggressively on real-time collaboration features that differentiate its offering for editorial-intensive workflows.
Content As a Service denotes a cloud-native delivery model where structured content repositories expose data through REST or GraphQL APIs, decoupling content storage from presentation layers and enabling omnichannel distribution across web, mobile, IoT, and emerging interfaces. Content Management services currently occupy the largest revenue pool within the Service Type dimension, while Cloud-based and SaaS deployment models are capturing the fastest growth as organizations abandon on-premise maintenance burdens. Video content within the Content Type segment is expanding rapidly as short-form and interactive formats strain legacy CMS architectures.
FCC guidelines on digital accessibility and the EU AI Act's transparency mandates are pressuring vendors to embed compliance tooling directly into editorial workflows, altering procurement evaluation criteria. GDPR data residency requirements and ISO 27001 certification demands are narrowing the vendor shortlist for European enterprise buyers. Stakeholders must monitor how generative AI integration reshapes content creation economics and whether regulatory clarity on synthetic media attribution forces platform architecture redesigns.
Market Dynamics
Headless API architectures are restructuring competitive positioning in content infrastructure as enterprise marketing teams abandon monolithic CMS platforms for modular, omnichannel delivery systems.
Growth Catalysts
- EU AI Act transparency mandates:Automated content generation tools now require audit trails and human oversight documentation, creating procurement urgency for compliant CaaS platforms with embedded governance workflows.
- E-commerce personalization at scale:Digital retailers demand real-time content variation across thousands of SKU pages, pulling investment toward API-first repositories that decouple content from presentation logic.
- Short-form video explosion:TikTok-style interactive formats strain legacy CMS bandwidth, accelerating migration to cloud-native delivery infrastructure optimized for streaming media assets.
Market Restraints
- GDPR data residency compliance:Strict EU storage requirements fragment vendor operations, forcing redundant infrastructure deployment that elevates operational costs for cross-border content delivery.
- Technical debt in legacy migrations:Enterprises with decade-old SharePoint or Adobe Experience Manager installations face 18-24 month transition timelines that delay CaaS adoption.
- Substitution by low-code website builders:Webflow and Framer capture mid-market budgets with visual editing tools that satisfy simpler omnichannel needs without API complexity.
Strategic Opportunities
- Underpenetrated German Mittelstand:Mid-sized industrial manufacturers in Baden-Württemberg and Bavaria remain anchored to on-premise systems, representing conversion potential as digital export strategies mature.
- Convergence of CaaS and edge computing:Content delivery networks integrating Cloudflare Workers or AWS Lambda@Edge enable sub-50ms personalization, opening premium pricing tiers for latency-sensitive applications.
- French ANSM healthcare content rules:Strict medical device documentation requirements create specialized demand for audit-ready content platforms in pharmaceutical marketing operations.
Industry Challenges
- Scarce GraphQL engineering talent:API schema design and federated query optimization skills command 40% salary premiums, constraining implementation velocity for enterprise deployments.
- ISO 27001 certification timelines:12-18 month security audit cycles delay vendor qualification for financial services and government contracts, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content As a Service (Caas) Market |
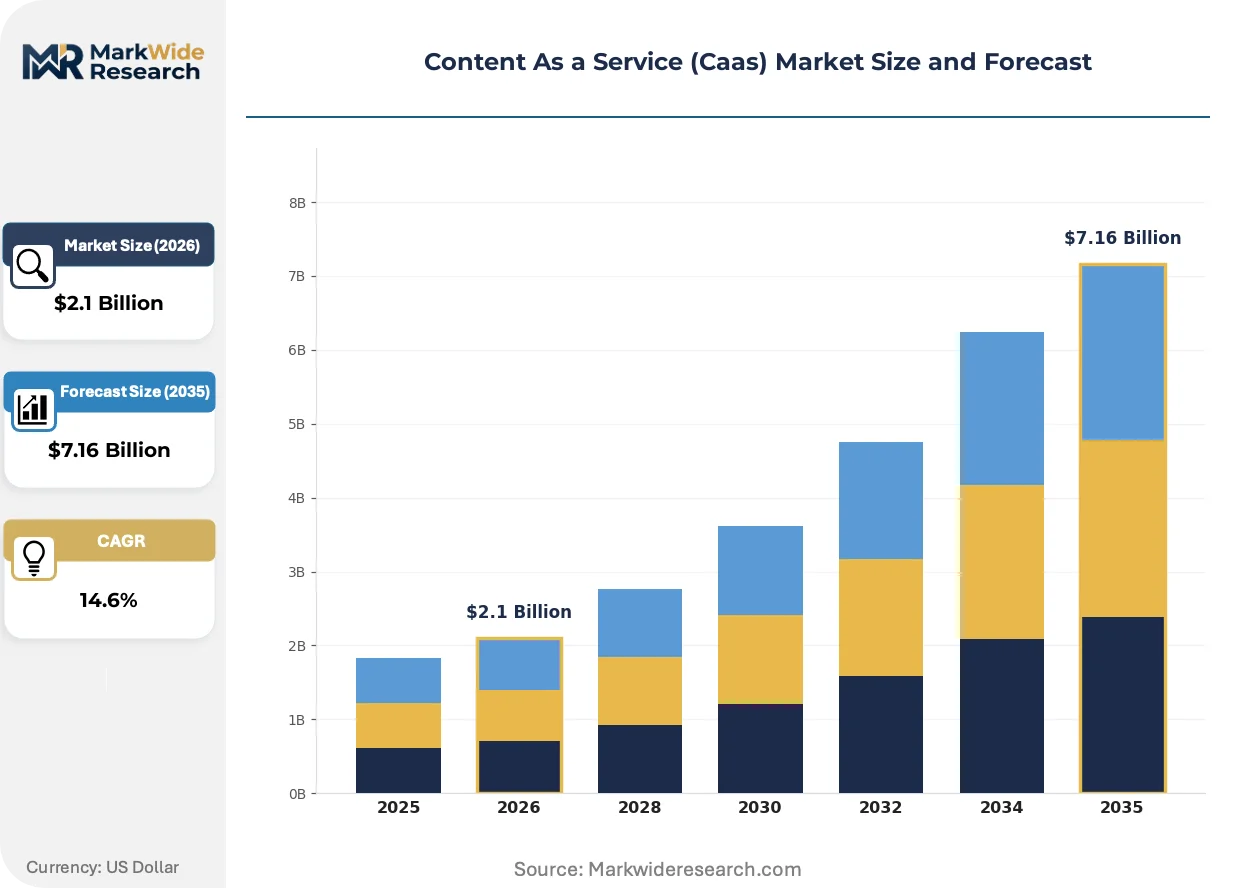
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Content Creation, Content Distribution, Content Management, Content Strategy Deployment Model: On-premise, Cloud-based, Hybrid, SaaS End User: Enterprises, Startups, Agencies, Freelancers Content Type: Video, Blog, Podcast, E-book |
| Companies Covered | Contentful, Contentstack LLC, Sitecore, Core dna, Scrivito, Agility CMS, Prismic.io, Sanity, Ingeniux Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content As a Service (Caas) Market Strategic Shifts
Generative AI integration is compressing content production economics while regulatory pressure forces architectural redesign around transparency and attribution.
Real-time collaborative editing is overtaking asynchronous workflow tools in editorial-intensive environments. Magazine publishers and newsrooms in London and Paris deploy shared canvas interfaces that eliminate version-control bottlenecks. This capability is overtaking traditional approval chains, collapsing production cycles from days to hours for time-sensitive campaigns.
The EU AI Act's synthetic media disclosure requirements are mandating embedded provenance metadata in AI-assisted content. Vendors must now build automated tagging systems that flag machine-generated text and images before publication. German automotive marketers and French luxury brands face the strictest enforcement timelines, accelerating compliance tooling procurement ahead of 2026 deadlines.
Subscription-based procurement is displacing perpetual licensing in enterprise content technology. Chief marketing officers in the United Kingdom now prioritize operational expenditure models that align costs with content velocity rather than fixed capacity. This shift concentrates vendor relationships with platforms offering usage-based metering and automatic scaling for seasonal campaign spikes.
Content As a Service (Caas) Market Segmentation
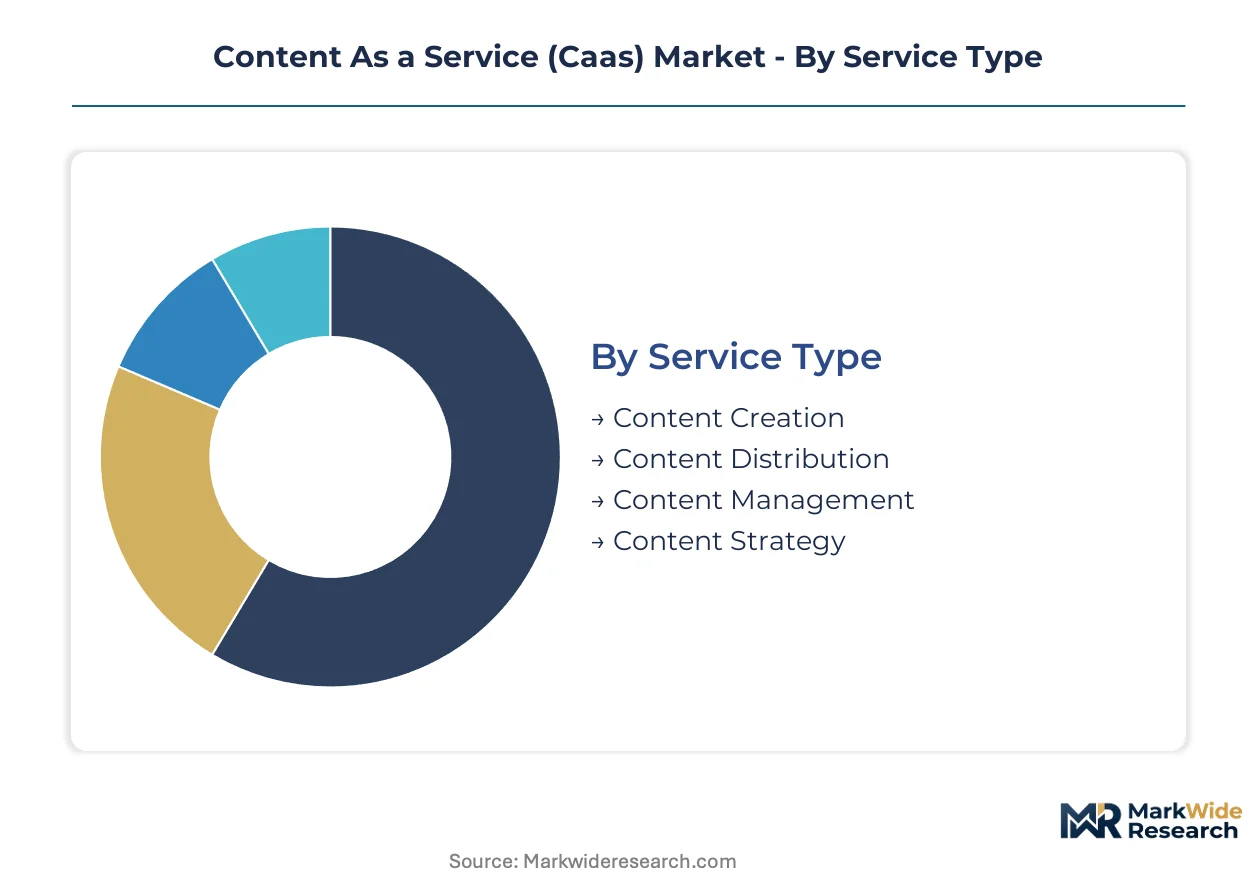
Content As a Service architectures fragment across four distinct dimensions that determine procurement priorities. Service type dictates workflow integration depth, while deployment model governs compliance posture and total cost of ownership. End user scale shapes feature requirements, and content format drives infrastructure specifications.
Service Type:
Enterprise buyers in Germany and France differentiate procurement decisions by operational maturity and editorial workflow complexity.
- Content Management:Structured repositories expose content through REST or GraphQL APIs, decoupling storage from presentation layers. German automotive and industrial manufacturers in Bavaria anchor procurement here, driven by omnichannel distribution requirements across dealer networks and export documentation systems.
- Content Creation:Generative AI tooling and collaborative editing environments compress production cycles from days to hours. French luxury brand marketing teams in Paris concentrate demand, pulled by EU AI Act transparency mandates requiring embedded audit trails for synthetic media.
- Content Distribution:Edge-optimized delivery networks enable sub-50ms personalization across web, mobile, and IoT endpoints.
- Content Strategy:Analytics-driven planning tools align editorial calendars with search performance and audience segmentation data.
Volume sits with Content Management; growth tilts toward Content Creation.
Deployment Model:
Cost tier and compliance burden segment buyer preferences across the European market.
- Cloud-based:Fully managed infrastructure eliminates data center overhead while auto-scaling for seasonal campaign spikes. United Kingdom retail and media enterprises drive adoption, prioritizing operational expenditure models over capital-intensive on-premise builds.
- SaaS:Subscription metering aligns costs with content velocity, attracting mid-market agencies in London and Berlin seeking predictable budgeting without capacity planning.
- Hybrid:Sensitive assets remain on-premise while public-facing content leverages cloud edge nodes, satisfying GDPR data residency requirements for cross-border publishers.
- On-premise:Legacy installations persist among defense contractors and government bodies with air-gapped security mandates.
Revenue concentrates in Cloud-based deployments; Hybrid configurations expand most quickly as compliance complexity deepens.
End User:
Organizational scale determines feature sophistication and integration requirements.
- Enterprises:Multi-region governance, SSO integration, and ISO 27001 certification dominate procurement checklists. French pharmaceutical marketers under ANSM jurisdiction require audit-ready platforms for medical device documentation.
- Agencies:Client isolation, white-label capabilities, and rapid tenant provisioning support multi-account workflows. Berlin and Amsterdam creative shops drive regional demand.
- Startups:API-first architectures and pay-as-you-grow pricing reduce entry barriers for venture-backed teams.
- Freelancers:Simplified editorial interfaces and template libraries serve solo practitioners with limited technical resources.
Enterprise accounts generate the largest revenue pool; Agencies provide the steepest expansion trajectory as outsourced content production scales.
Content Type:
Infrastructure specifications diverge sharply by media format and bandwidth requirements.
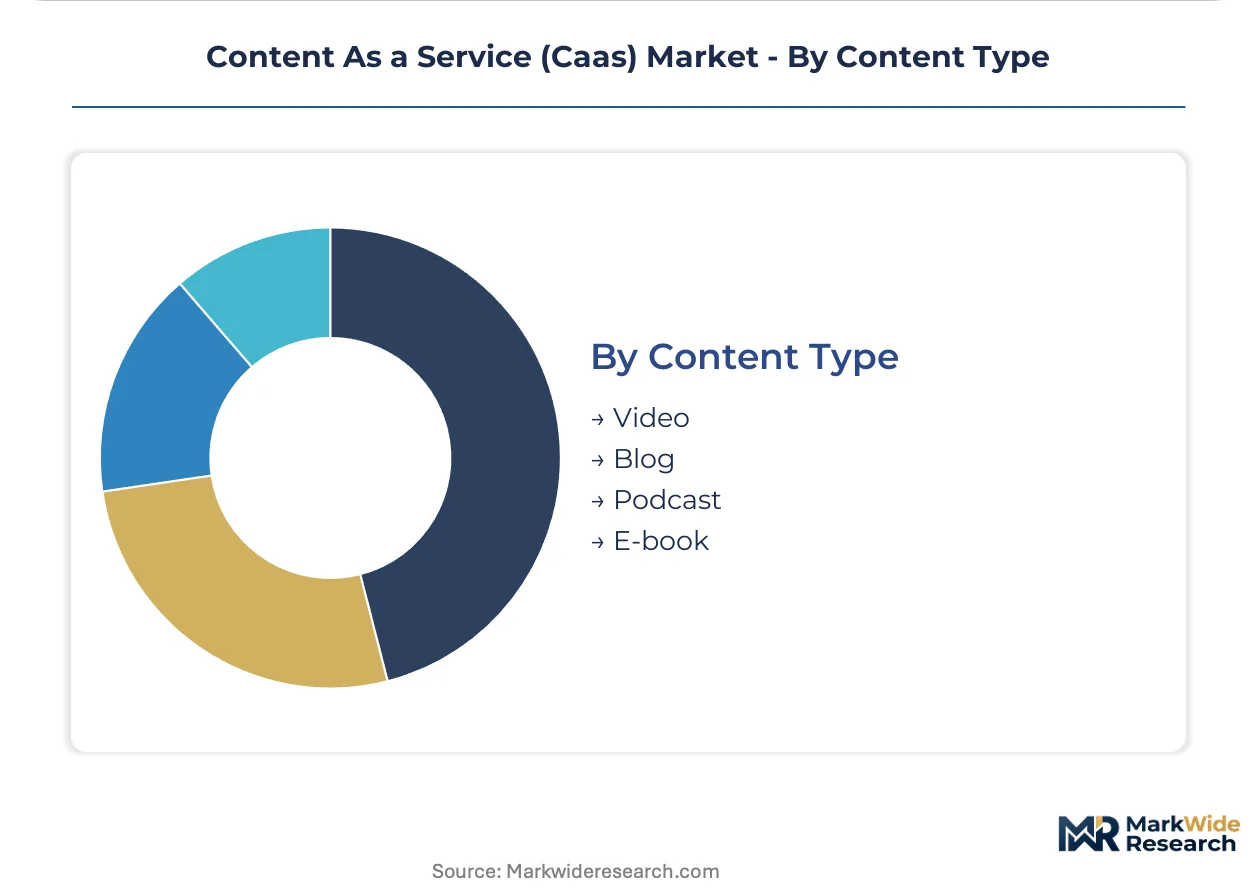
- Video:Streaming-optimized delivery and adaptive bitrate encoding strain legacy CMS architectures. Short-form interactive formats for German automotive and UK retail campaigns accelerate cloud-native migration.
- Blog:Structured text repositories with SEO optimization and multi-language localization support editorial-intensive publishing operations.
- Podcast:Audio asset management with transcription, chapter marking, and distribution feed automation serves media producers.
- E-book:Long-form document workflows with DRM, accessibility compliance, and multi-format export target educational and B2B publishers.
Investment intensity peaks with Video infrastructure; Blog content maintains the broadest installed base across enterprise content stacks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production gravity sits with North American software vendors, while consumption concentrates in European enterprise marketing teams modernizing digital experience stacks. Germany, the United Kingdom, and France anchor procurement volume as GDPR and EU AI Act deadlines reshape vendor selection criteria.
Germany
Automotive exporters and industrial manufacturers in Bavaria and Baden-Württemberg drive demand for omnichannel content distribution across dealer networks. The EU AI Act mandates automated audit trails for AI-generated marketing materials, accelerating compliance tooling procurement. Berlin hosts a growing cluster of SaaS-native agencies serving Mittelstand clients transitioning from on-premise SharePoint installations.
United Kingdom
London-based retail and media enterprises prioritize subscription-based procurement models aligning costs with campaign velocity. The Information Commissioner's Office enforces strict GDPR data residency requirements, narrowing vendor shortlists to platforms with UK-based infrastructure. Manchester and Leeds emerging as secondary hubs for mid-market agency consolidation.
France
Parisian luxury brand marketing teams concentrate investment in real-time collaborative editing environments. ANSM pharmaceutical documentation rules create specialized demand for audit-ready content platforms in medical device marketing. Île-de-France agencies lead adoption of generative AI tooling with embedded provenance metadata for synthetic media compliance.
United States
FCC digital accessibility guidelines pressure vendors to embed compliance tooling into editorial workflows. California and New York enterprise marketing teams drive API-first architecture adoption for e-commerce personalization at scale. Austin and Boston emerging as developer talent clusters for headless CMS implementation.
Netherlands
Amsterdam-based creative agencies and logistics technology firms demand multi-language localization capabilities for pan-European campaigns. Dutch data protection authority interpretations of GDPR cross-border transfer rules influence hybrid deployment preferences. Rotterdam port technology cluster generates specialized demand for IoT-integrated content delivery.
Content As a Service (Caas) Market Competitive Environment
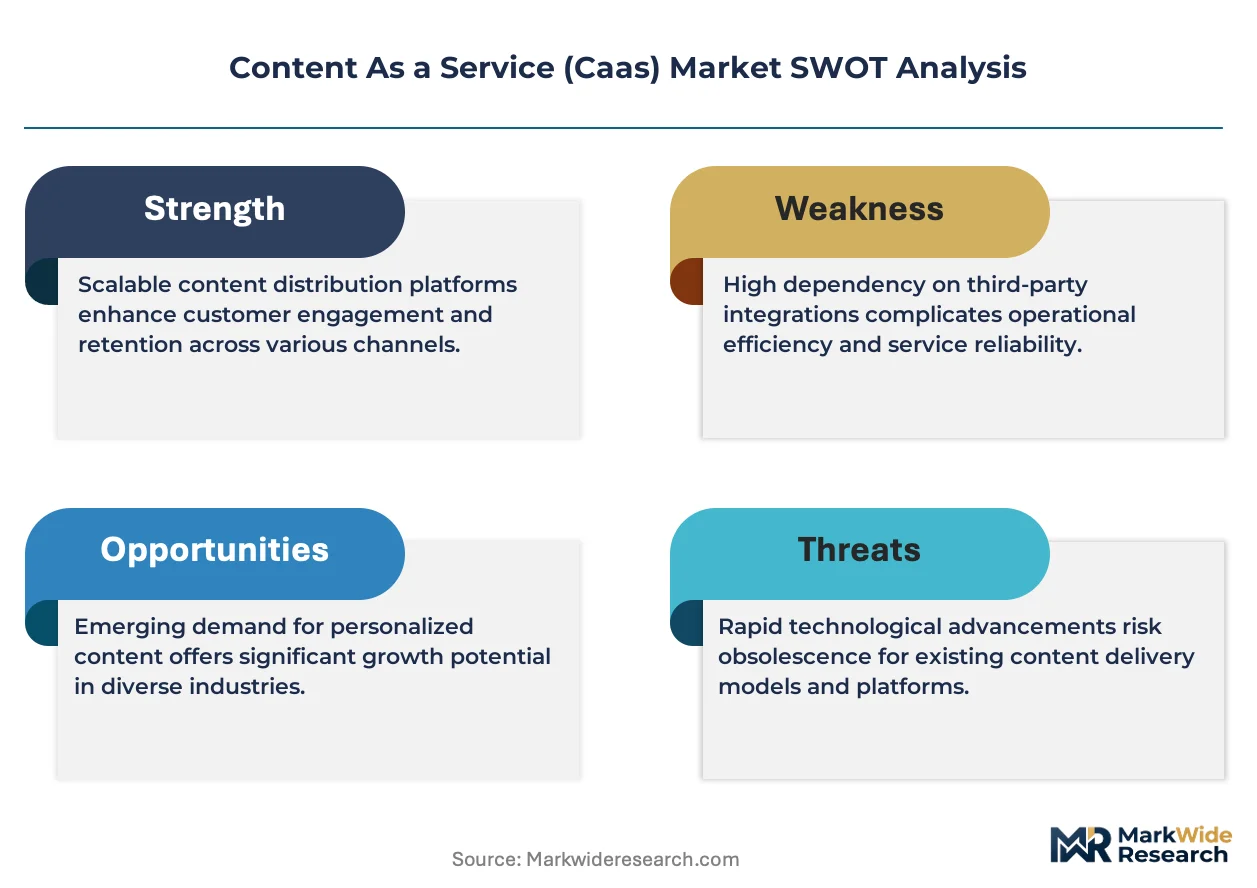
Top-tier vendors anchor enterprise accounts with ISO 27001 certification and multi-region governance capabilities, while mid-market specialists compete on implementation velocity and sector-specific templates. The vendor base fragments across API-first pure-plays, legacy CMS incumbents pivoting to headless architectures, and vertical specialists targeting regulated industries. Three archetypes dominate: developer-centric platforms emphasizing GraphQL flexibility, marketer-friendly tools prioritizing visual editing interfaces, and compliance-focused offerings embedding regulatory audit trails. M&A activity concentrates on acquiring real-time collaboration capabilities and edge computing integration technologies.
Within the API-first developer platform tier, Contentful and Sanity exemplify contrasting positioning strategies—Contentful anchors broader enterprise adoption through extensive integration ecosystems, while Sanity occupies a position emphasizing real-time collaborative editing for editorial-intensive workflows. Sitecore represents the legacy incumbent archetype, leveraging hybrid deployment flexibility to defend installed base relationships during cloud migration cycles. These three companies collectively illustrate how competitive differentiation in CaaS increasingly depends on workflow-specific optimization rather than generic content repository capabilities.
| Leading Market Players |
|---|
| Contentful |
| Contentstack LLC |
| Sitecore |
| Core dna |
| Scrivito |
| Agility CMS |
| Prismic.io |
| Sanity |
| Ingeniux Corporation |
| Others |
Value Chain & Pricing Dynamics
GraphQL engineering talent concentration in Berlin and Amsterdam drives labor-cost differentials that widen pricing-tier spreads between premium enterprise deployments and mid-market SaaS configurations. API schema specialists command salary premiums that cascade into implementation pricing, while GDPR-compliant infrastructure requirements add fixed-cost layers that vendors recover through tiered subscription structures.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects competitive pressure from low-code website builders capturing simpler use cases without API complexity. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 27001 certification status and edge-computing integration depth. Cost-down pressure on enterprise deployments accelerates because scarce implementation talent elongates sales cycles and elevates professional services discounts. Startups and venture-backed teams exhibit highest price sensitivity; financial services and pharmaceutical buyers under ANSM jurisdiction show lowest sensitivity due to compliance-driven procurement urgency.
Supply Chain Analysis
Regional distribution centers in Frankfurt, London, and Paris anchor hub-and-spoke patterns for cloud-native content delivery infrastructure. Supply concentration centers on Ireland and the Netherlands for EU data residency-compliant hosting, with secondary capacity in Germany and France. Raw material dependencies include hyperscaler compute contracts, CDN edge node partnerships, and API gateway licensing. Single-source vulnerability sits with hyperscaler concentration for underlying infrastructure. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and self-serve SaaS provisioning for smaller accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Headless API architectures are displacing monolithic CMS platforms as the dominant content infrastructure paradigm, creating transition-phase investment and positioning imperatives across vendor categories.
For Market Incumbents: Acquire real-time collaboration capabilities to defend against editorial-workflow specialists eroding mid-market share. Acquire edge-computing integration technologies to capture latency-sensitive personalization premiums. Consolidation pressure from generative AI tooling mandates defensive R&D investment in automated audit-trail systems ahead of EU AI Act enforcement timelines. For New Entrants and Emerging Players: Begin with German Mittelstand manufacturers in Baden-Württemberg and Bavaria, where on-premise SharePoint installations create conversion whitespace as digital export strategies mature. Target French pharmaceutical marketing operations under ANSM jurisdiction, where audit-ready platform requirements narrow competitive fields. Pursue agency channel partnerships in Amsterdam and Berlin as the primary go-to-market angle, leveraging multi-tenant provisioning capabilities to accelerate land-and-expand velocity. For Investors and Strategic Acquirers: Re-rating potential sits with compliance-focused platform archetypes given EU AI Act transparency mandates accelerating procurement urgency. Long-term viability favors vendors embedding governance workflows directly into editorial interfaces rather than bolt-on compliance modules. Monitor ISO 27001 certification timelines as the critical signal—vendors completing audits within compressed windows capture financial services and government contract opportunities that competitors forfeit.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture consolidation enables seamless connection to e-commerce personalization engines and edge delivery networks. |
| Acquisition of Specialist Firm | Real-time collaboration capabilities address editorial-intensive workflow demands from Parisian luxury brand marketing teams. |
| Geographic Expansion | German Mittelstand penetration targets industrial manufacturers transitioning from legacy on-premise SharePoint installations. |
| Strategic Partnership | Hyperscaler alliances secure GDPR-compliant data residency infrastructure for UK retail and media enterprise procurement. |
| Product Launch | Generative AI tooling with embedded provenance metadata satisfies EU AI Act synthetic media disclosure requirements ahead of deadlines. |
Study Parameters
Document review covered regulatory filings from EMA and national data protection authorities, complemented by interviews with CTOs, marketing technology procurement officers, platform engineers, and systems integration specialists. Secondary validation drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures, and EU regulatory impact assessments. Bottom-up deployment estimates triangulated against top-down market sizing from industry association data.
Cross-reference between historical adoption curves and expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, content format bandwidth requirements, and regional regulatory cluster. CAGRs derived from trend extrapolation adjusted for technology substitution effects and compliance-driven procurement accelerations. Forecast inputs incorporated generative AI integration pace and ISO 27001 certification completion rates as industry-specific variables.
Underlying measurement precision varies by segment; Cloud-based and SaaS deployment models carry tighter precision than Hybrid configurations where compliance complexity introduces forecasting uncertainty. Forecasts reflect assumptions around regulatory enforcement timelines and technology adoption S-curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Preparation Tools Market
Software & Services
Vertical Software Market
Software & Services
Co-Browsing Software Market
Software & Services
Content Moderation Software Market
Software & Services
Photobooth Software Market
Software & Services
Business Analytics Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Business Productivity Software Market
Software & Services
PCB Design Software Market
Software & Services
Europe Drone Software Market
Software & Services
Human Capital Management (HCM) Saas Market
Software & Services
Global Construction Punch List Software Market
Software & Services
Credit Management Software Market
Software & Services
Global Project Software Market
Software & Services
HSM-As-A-Service Market
Software & Services
Europe Integration Platform As a Service Market