
 Payroll - HR Solutions and Services Market | 2026-2036
Payroll - HR Solutions and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Payroll - HR Solutions and Services Market Outlook
Cloud-native architecture is fragmenting the traditional payroll technology stack, replacing monolithic enterprise systems with modular APIs and embedded finance integrations. ADP sustains its position through massive scale across tax filing jurisdictions and deep compliance databases. Workday differentiates by unifying human capital management with financial planning in a single data model. Rippling leverages its identity-centric platform to extend payroll into device management and global contractor payments.
Payroll - HR solutions and services encompass software platforms and managed services that automate wage calculation, tax withholding, benefits enrollment, time tracking, and regulatory reporting across employer workforces, typically processing multi-jurisdiction tax codes and integrating with general ledger systems via standardized APIs. The primary commercial purpose centers on reducing compliance exposure, accelerating pay cycles, and consolidating fragmented HR data into actionable workforce analytics. Cloud-Based deployment now leads across all customer tiers as vendors retire on-premises maintenance streams and redirect R&D toward real-time payment rails and AI-assisted anomaly detection. Small Enterprises and Medium Enterprises represent the fastest-growing customer type segment, drawn by per-employee pricing models that lower entry barriers previously reserved for large corporations with dedicated payroll staff.
Employers in the United States navigate overlapping requirements from the IRS, state revenue departments, and the Department of Labor, creating sustained demand for platforms that automate multi-layered compliance calculations and audit trails. The IRS and individual state regulators shape product roadmaps through annual tax table updates, ACA reporting mandates, and evolving gig-worker classification rules. Stakeholders must monitor how emerging state-level pay transparency laws and real-time payment infrastructure investments reshape platform architecture and vendor selection criteria.
Market Dynamics
Cloud-native payroll architectures are dismantling the monolithic enterprise systems that dominated workforce management for decades, forcing vendors to reconstitute their platforms around modular APIs and real-time data synchronization. This structural shift compresses implementation timelines from quarters to weeks while exposing legacy providers to displacement by agile challengers.
Growth Catalysts
- IRS Tax Table Automation:Annual federal and state tax code revisions compel employers to upgrade from manual spreadsheet calculations to automated compliance engines, accelerating platform refresh cycles across the United States.
- Real-Time Payment Rails:The Federal Reserve's FedNow infrastructure and similar instant settlement networks enable same-day wage disbursement, transforming payroll from a back-office function into a competitive talent retention tool.
- Gig Economy Classification Rules:Evolving Department of Labor guidance on contractor versus employee status forces platforms to build dynamic worker categorization engines that adapt to jurisdictional variations.
Market Restraints
- Multi-State Compliance Fragmentation:The United States lacks federal preemption of state-level wage and hour laws, forcing vendors to maintain parallel tax calculation engines for all fifty states plus territories, inflating R&D overhead.
- Data Residency Requirements:European GDPR and emerging national privacy frameworks mandate localized data storage, complicating cloud architecture for vendors pursuing cross-border expansion.
- Legacy System Entrenchment:Large enterprises with decades of customized on-premises payroll configurations face prohibitive migration costs and change management resistance, slowing cloud adoption at the high end.
Strategic Opportunities
- Embedded Finance Convergence:The integration of payroll data with lending, insurance, and savings products creates new revenue streams as platforms become financial services distribution channels.
- Pay Transparency Mandates:State-level laws in California, Colorado, and New York requiring salary disclosure in job postings drive demand for compensation benchmarking tools integrated directly into HR platforms.
- Small Enterprise White Space:Businesses with under fifty employees remain underserved by complex enterprise suites, creating openings for simplified, mobile-first payroll solutions with transparent per-employee pricing.
Industry Challenges
- Specialized Compliance Engineering Talent:Vendors struggle to recruit professionals fluent in both software development and the arcana of multi-jurisdiction tax withholding, benefits administration, and labor law interpretation.
- Interoperability with Heterogeneous Tech Stacks:Enterprise buyers demand seamless integration with hundreds of disparate time-tracking, accounting, and benefits systems, forcing vendors to maintain expensive connector libraries and API partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Payroll - HR Solutions and Services Market |
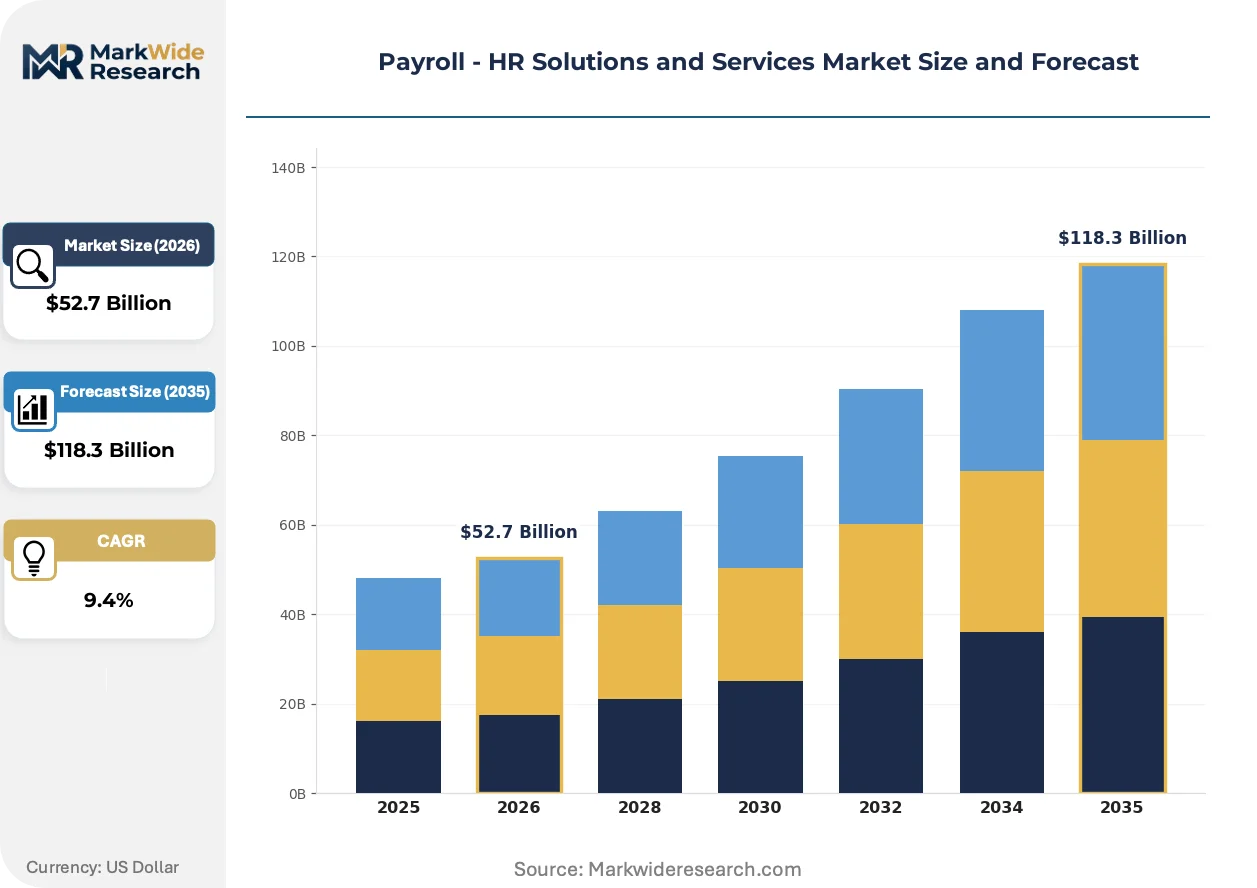
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $118.3 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payroll Processing, Tax Compliance, Benefits Administration, Workforce Management Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Startups Industry Vertical: Healthcare, Retail, Manufacturing, Education |
| Companies Covered | ADP, Paycom, Workday, Paylocity, Dayforce, Paychex, Paycor, Rippling, Gusto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Payroll - HR Solutions and Services Market Strategic Shifts
Artificial intelligence is penetrating payroll operations at multiple points, from anomaly detection in wage calculations to predictive modeling of workforce costs, compressing error rates and accelerating decision cycles for finance leaders.
Machine learning algorithms trained on historical payroll patterns are digitizing the exception-handling workflows that previously consumed hours of analyst time each pay period. Mid-sized enterprises with limited dedicated payroll staff are adopting these tools fastest, as they lack the headcount to manually review every outlier. The technology is digitizing compliance risk assessment by flagging discrepancies against regulatory databases before they trigger audit exposure.
The Department of Labor's evolving stance on overtime eligibility under the Fair Labor Standards Act is forcing platforms to rebuild exemption classification engines. Vendors must now track hours across multiple work locations and job roles to determine eligibility thresholds. Technology and professional services firms with distributed workforces face the steepest recalibration, as they reconfigure time-tracking infrastructure to capture granular activity data.
Subscription pricing models are displacing perpetual licenses and professional services engagements as the dominant commercial structure. Buyers now expect consumption-based billing tied to active employee counts rather than upfront capital expenditure. This shift is most pronounced among technology startups and professional services firms in coastal United States markets, where finance teams prioritize operational expenditure classification for cash flow management.
Payroll - HR Solutions and Services Market Segmentation
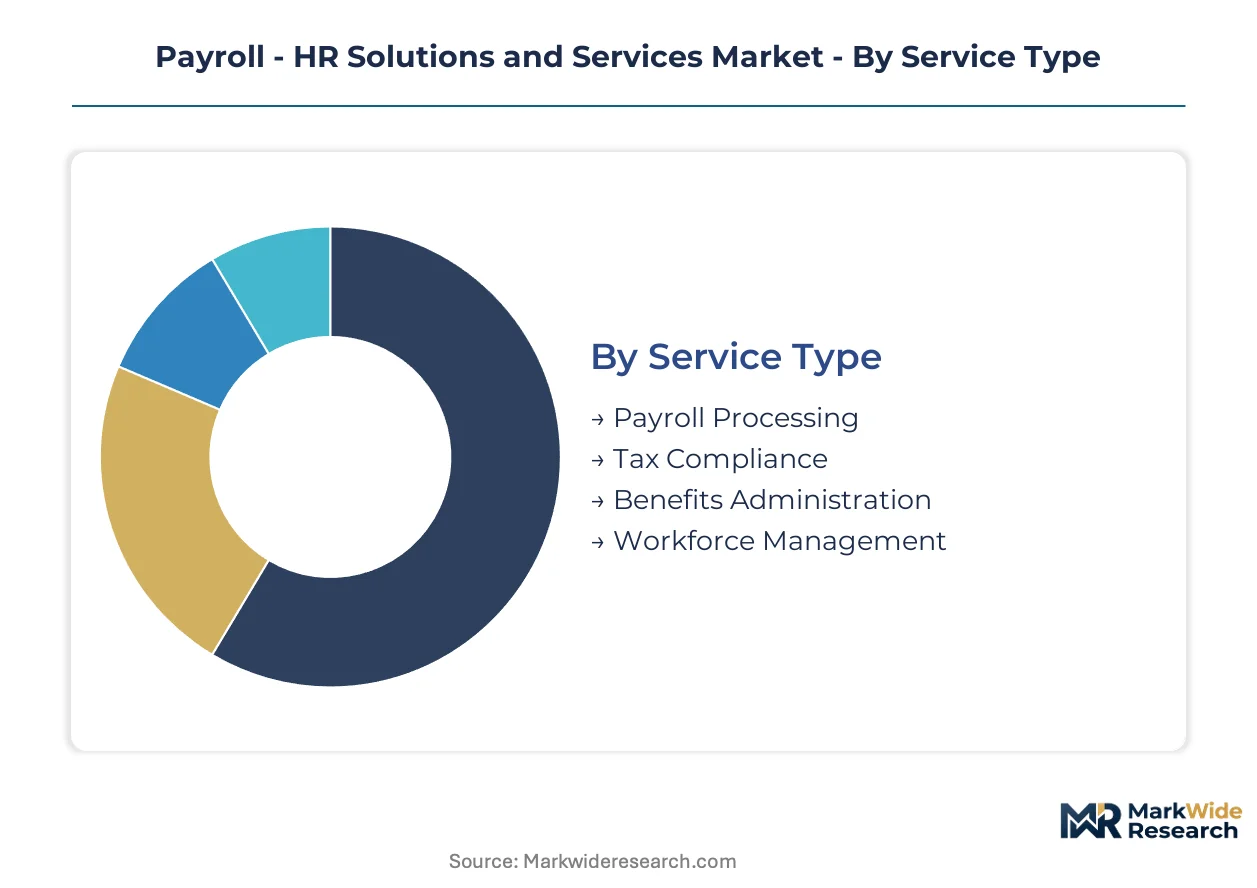
Segmentation in payroll and HR services reveals how vendor capabilities align with divergent compliance burdens, technical maturity, and workforce scale across employer types. Understanding these divides clarifies why cloud-native platforms capture mid-market share while legacy systems retain entrenched enterprise accounts.
Service Type:
Use-case spectrum spans from pure transaction processing to integrated workforce intelligence, with complexity escalating as services intersect with regulatory filing requirements.
- Payroll Processing:Core wage calculation engines handle gross-to-net computations, direct deposit execution, and pay stub generation across hourly and salaried workforces. Demand concentrates among small enterprises in the United States seeking to outsource arithmetic complexity without building internal tax expertise.
- Tax Compliance:Automated withholding engines synchronize with IRS and state revenue department tables, managing quarterly filings, W-2 distribution, and penalty risk assessment. Healthcare employers in California and New York prioritize these capabilities as state-level reporting mandates proliferate.
- Benefits Administration:Enrollment portals, COBRA management, and ACA reporting modules integrate carrier feeds with payroll deduction workflows.
- Workforce Management:Time capture, scheduling optimization, and labor cost forecasting tools extend payroll data into operational planning.
The dominant share belongs to Payroll Processing, while Tax Compliance is closing the gap fastest.
Deployment:
Architecture choices reflect IT resource constraints, data sovereignty requirements, and the pace of regulatory change forcing platform refresh cycles.
- Cloud-Based:Multi-tenant SaaS platforms deliver automatic tax table updates, elastic scaling during pay cycles, and API-first integration with accounting systems. Medium enterprises across Texas and Florida adopt these most aggressively, drawn by zero-maintenance infrastructure and consumption pricing.
- On-Premises:Single-tenant installations behind corporate firewalls serve organizations with stringent data residency policies or customized legacy configurations.
- Hybrid:Split architectures retain sensitive payroll data locally while pushing analytics and employee self-service to cloud tiers.
- Mobile Solutions:Native applications for manager approvals, time clocking, and pay stub access address distributed workforces without desktop access.
Cloud-Based deployments command the largest installed base, with Mobile Solutions expanding most quickly among frontline industries.
Customer Type:
Organizational scale dictates feature complexity tolerance, pricing sensitivity, and the internal HR headcount available to manage platform configuration.
- Small Enterprises:Employers with under fifty employees favor simplified interfaces, transparent per-employee pricing, and rapid onboarding without implementation consultants. Demand clusters in professional services firms across Illinois and Georgia seeking to replace spreadsheet-based processes.
- Medium Enterprises:Organizations between fifty and one thousand employees require multi-state tax engines, benefits administration, and basic analytics without enterprise complexity. This tier is gaining share fastest as vendors target the white space between entry-level tools and monolithic suites.
- Large Corporations:Global workforces with tens of thousands of employees need customizable workflows, dedicated support tiers, and deep ERP integration.
- Startups:Venture-backed companies prioritize equity compensation management, contractor payments, and international expansion readiness.
Medium Enterprises hold the dominant position, while Startups are climbing the fastest as venture formation accelerates in coastal technology corridors.
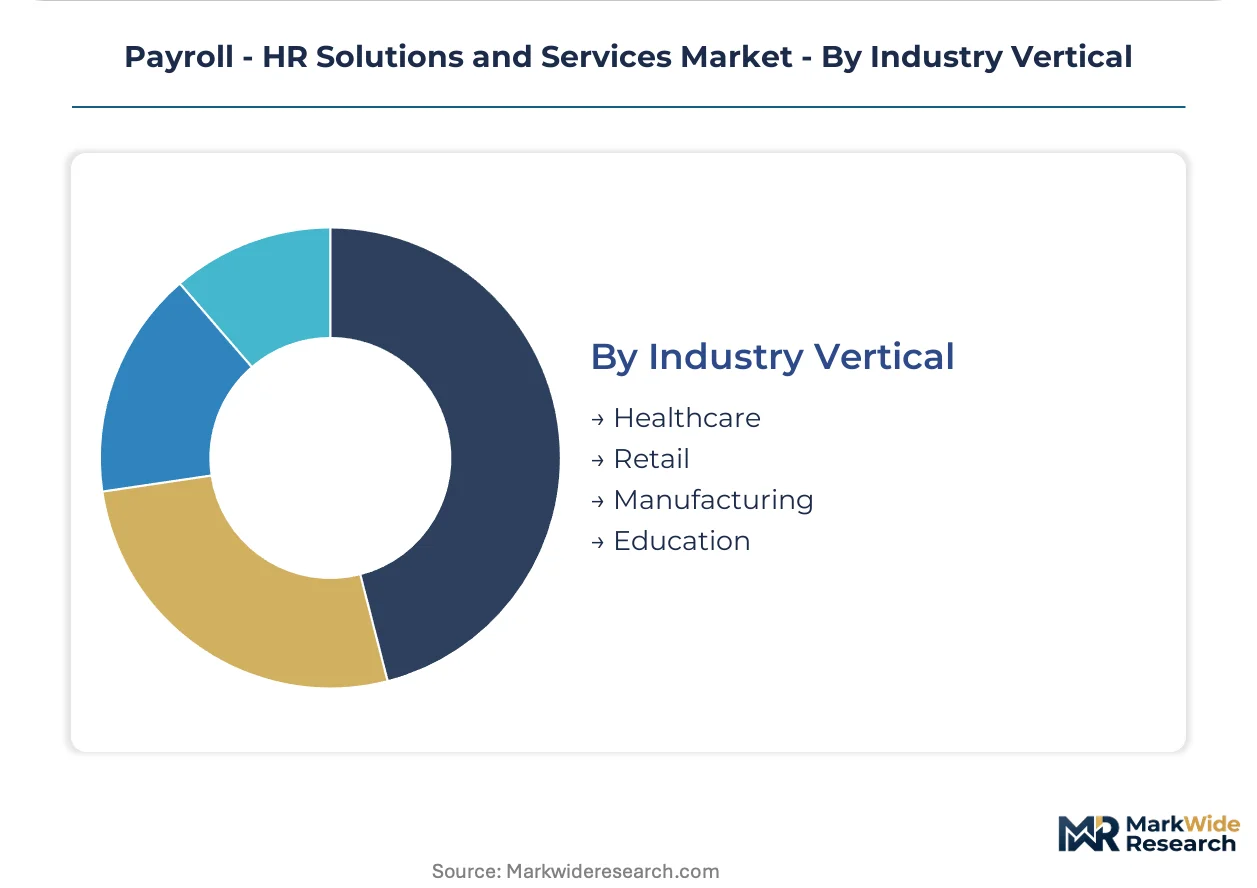
Industry Vertical:
Sector-specific labor regulations, shift patterns, and compensation structures shape platform requirements and vendor selection criteria.
- Healthcare:Complex shift differentials, union contract enforcement, and credential tracking for clinical staff drive demand for specialized scheduling and compliance modules. Hospital systems in Pennsylvania and Ohio upgrade platforms to manage overtime calculation under evolving Department of Labor guidance.
- Retail:High-turnover hourly workforces, seasonal scaling, and multi-location time tracking require rapid onboarding tools and flexible pay cycle options. National chains concentrate investment in mobile-first solutions for distributed store networks.
- Manufacturing:Piece-rate calculations, shop floor time capture, and union reporting obligations favor ruggedized hardware integration and legacy system compatibility.
- Education:Academic calendars, grant-funded position tracking, and adjunct faculty classification create unique pay cycle and benefits eligibility rules.
Healthcare captures the dominant vertical share, with Retail gaining ground fastest as wage pressure and turnover drive platform investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based payroll technology vendors export platform services to Canadian and Mexican employers navigating similar regulatory frameworks, while European demand concentrates in jurisdictions with strict data residency requirements.
United States
Mid-sized enterprises in Texas and Florida drive cloud migration as IRS tax table complexity and multi-state withholding rules overwhelm spreadsheet-based processes. The Department of Labor's evolving overtime exemption standards under the Fair Labor Standards Act force quarterly platform recalibrations. Silicon Valley technology corridors and New York financial services clusters anchor vendor R&D investment in real-time payment rails and AI-assisted compliance engines.
Canada
Provincial payroll tax fragmentation across Ontario, Quebec, and British Columbia sustains demand for automated calculation engines that synchronize with federal CRA requirements. Health Canada and provincial labor ministries coordinate on electronic record-keeping standards for benefits administration. Toronto's financial services concentration and Calgary's energy sector headquarters generate concentrated adoption of integrated HR platforms with pension administration modules.
Germany
Mittelstand manufacturers in Bavaria and Baden-Württemberg adopt cloud payroll solutions to manage complex collective bargaining agreements and works council consultation requirements. The Bundesdatenschutzgesetz and EU GDPR mandate localized data processing, complicating multi-tenant SaaS architectures. Berlin's startup ecosystem and Frankfurt's banking headquarters represent divergent demand poles—lean international contractor payments versus deep ERP integration.
United Kingdom
Post-Brexit regulatory divergence from EU employment law creates dual compliance burdens for cross-border employers, accelerating platform refresh cycles. HMRC's Real Time Information requirements and evolving off-payroll working rules reshape product roadmaps. London's professional services density and Manchester's emerging tech corridor drive contrasting priorities—sophisticated equity compensation management versus simplified mobile-first solutions.
India
IT services exporters in Bangalore and Hyderabad deploy global payroll platforms to manage distributed workforces across client jurisdictions, while domestic employers grapple with state-level professional tax variations. The Ministry of Labour and Employment's push toward digital compliance reporting and EPFO integration mandates platform modernization. Mumbai's financial services concentration and Delhi-NCR's government contractor ecosystem anchor divergent adoption patterns—multinational compliance suites versus statutory-first domestic solutions.
Payroll - HR Solutions and Services Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven incumbents defend tax-filing infrastructure advantages against API-native challengers. The vendor base stratifies into three archetypes: jurisdiction-scale processors with deep compliance databases, unified HCM suites with financial planning convergence, and identity-centric platforms extending payroll into adjacent workforce operations. Dominant competitive moves include vertical integration into embedded finance products and geographic expansion through modular API partnerships rather than full-stack replication.
Within the scale-driven tier, ADP and Paychex anchor positions through massive tax-filing jurisdiction coverage and small-enterprise channel density. Workday occupies the unified-suite vector, exemplifying convergence between human capital management and financial planning data models. Rippling represents the identity-centric challenger archetype, extending payroll infrastructure into device management and global contractor payments. Gusto and Paylocity sit within the mid-market specialization tier, targeting employers between fifty and one thousand employees with simplified onboarding and transparent per-employee pricing.
| Leading Market Players |
|---|
| ADP |
| Paycom |
| Workday |
| Paylocity |
| Dayforce |
| Paychex |
| Paycor |
| Rippling |
| Gusto |
| Others |
Value Chain & Pricing Dynamics
Silicon Valley cloud infrastructure clusters anchor the upstream compute capacity that payroll vendors consume, and their pricing volatility directly compresses margins for SaaS providers serving mid-sized enterprises. When hyperscaler compute rates shift, downstream platform pricing power erodes within quarterly contract cycles.
Pricing Analysis
Legacy on-premises licensing versus cloud-native subscription tiers versus emerging real-time payment bundles define the three-generation pricing spread. The dominant model is consumption-based SaaS billing tied to active employee counts, with price differentiation resting on compliance engine sophistication and API integration depth. Cost compression in the small-enterprise tier is intensifying because venture-backed challengers subsidize per-seat rates to capture market share. Healthcare employers demonstrate the lowest price sensitivity due to penalty avoidance priorities, while retail chains with seasonal workforces exhibit acute sensitivity to per-transaction fees.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers and supply-chain finance facilities for tax-table data licensors characterize upstream financing arrangements. Software development concentrates in the United States, India, and Ireland, with implementation services drawing from domestic professional services networks. Raw material dependencies include hyperscaler compute credits, proprietary regulatory databases, and banking partnership rails. Single-source vulnerability sits with IRS and state revenue department data feeds that synchronize quarterly. Distribution runs through direct sales teams for large enterprises and self-service digital channels for small employers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Payroll-HR platform spending follows employment cycle recovery patterns, with IRS filing deadline compression and state-level pay transparency mandates acting as cyclical accelerators that refresh upgrade timelines.
For Market Incumbents: Insulate tax-filing infrastructure advantages by deepening compliance database coverage across municipal jurisdictions and accelerating real-time payment rail certifications. Emerging API-native challengers threaten mid-market share through faster implementation timelines. Capacity addition in state-specific regulatory engineering teams represents the critical defensive lever. For New Entrants and Emerging Players: Establish a beachhead in the fifty-to-five-hundred-employee white space where legacy suites prove overbuilt and entry-level tools lack multi-state engines. Franchise networks and professional services firms in Texas and Florida present the most penetrable concentration. A mobile-first onboarding experience with transparent per-employee pricing constitutes the essential go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a compliance-data moat play because regulatory fragmentation across U.S. states creates durable switching costs that compound with each filing jurisdiction added. Acquisition targets should display dense state-level tax engine coverage rather than generic HCM feature breadth. The signal to watch is state-level pay transparency law proliferation, which accelerates platform replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Payment Rail Certification | FedNow integration transforms payroll from back-office function to talent retention tool for technology employers. |
| State-Level Compliance Engine Expansion | Municipal tax jurisdiction coverage deepens switching costs for mid-sized healthcare and retail employers. |
| Embedded Finance Partnership | Payroll data integration with earned wage access products creates new revenue streams for platform vendors. |
| AI-Assisted Anomaly Detection Launch | Machine learning compression of exception-handling workflows addresses headcount constraints at growing enterprises. |
| API-First Ecosystem Expansion | Modular integration with time-tracking and accounting systems reduces implementation friction for professional services buyers. |
Study Parameters
A spread of perspectives from payroll operations directors, HR technology procurement officers, compliance engineering leads, and channel integration specialists converged on the working assumptions that structure this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, state revenue department regulatory updates, IRS publication schedules, and hyperscaler infrastructure pricing disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation were cross-checked for consistency.
Demand-supply balance dynamics across employer formation rates, platform replacement cycles, and vendor capacity expansion shaped the analytical framework. Segmentation dimensions modeled include deployment architecture, organizational scale, industry vertical, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of employer technology refresh patterns and cloud adoption curves. Forecast inputs incorporated IRS tax table update frequency and Department of Labor guidance revision timelines.
Stress conditions across interest rate sensitivity for SaaS valuations, state regulatory divergence velocity, and hyperscaler pricing volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about employment growth and technology refresh cadence. Macroeconomic contraction, federal preemption of state wage laws, or breakthroughs in autonomous compliance processing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
OCR Scanning Software Market
Software & Services
Global Gamification Software Market
Software & Services
Lending Software Market
Software & Services
Global Core Human Resource Software Market
Software & Services
Online Project Management Software Market
Software & Services
Global Fixed Asset Management Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Public Financial Management Software Market
Software & Services
API Testing Market
Software & Services
Terminal Emulator Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Anti-Plagiarism Software Market
Software & Services
Global Workforce Management Software Market
Software & Services
Relational Database Management System Market