
 Geophysical Software Service Market | 2026-2036
Geophysical Software Service Market Size, Share, and Industry Trends Forecast 2026-2036
Geophysical Software Service Market Analysis
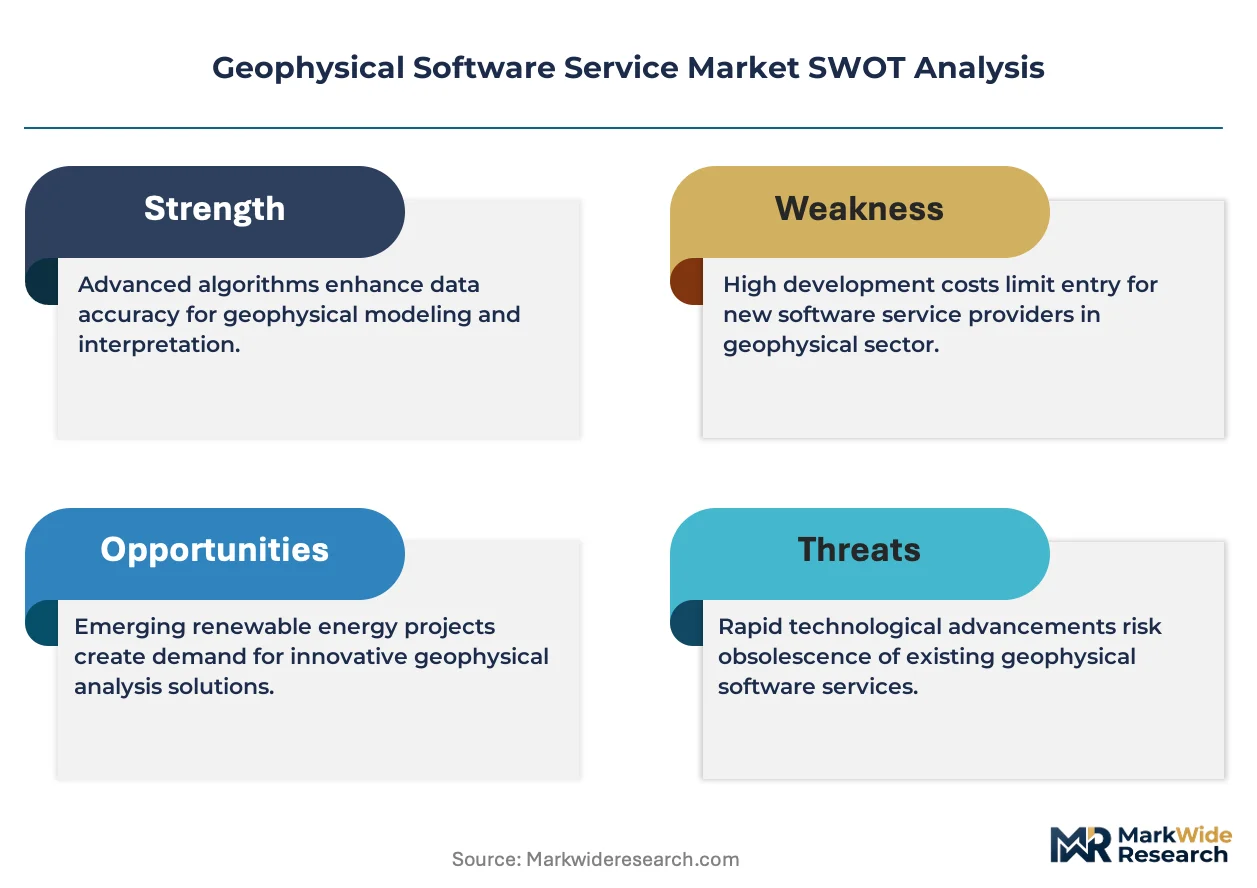
Subscription-based reservoir simulation licensing is recalibrating how geophysical vendors monetize intellectual property, shifting capital expenditure into operational budgets. Schlumberger Limited leverages its integrated software-hardware ecosystem to anchor long-term client relationships across deepwater basins. Halliburton Company competes through specialized drilling optimization modules that extend its service footprint beyond traditional seismic processing. PGS ASA differentiates by controlling proprietary multiclient data libraries that dominate the North Atlantic and West Africa licensing markets.
Geophysical software services encompass computational platforms that process seismic, electromagnetic, and gravitational data to characterize subsurface geology, typically handling terabyte-scale datasets through parallel computing architectures optimized for depth migration and full-waveform inversion. The primary commercial purpose centers on de-risking hydrocarbon exploration, mineral prospecting, and carbon storage site selection by converting raw geophysical measurements into interpretable structural and stratigraphic models. Seismic Processing commands the largest revenue share due to its indispensability across every exploration phase, while Machine Learning represents the fastest-expanding technology segment as operators deploy neural networks to automate fault detection and reservoir property prediction. Cloud-based Deployment is capturing margin pools from on-premise installations by eliminating upfront infrastructure costs and enabling elastic compute scaling during intensive processing campaigns.
FERC pipeline safety directives and EPA methane monitoring mandates in the United States are compelling operators to integrate continuous geophysical surveillance into asset management protocols, directly expanding software service procurement. The EU AI Act's risk classification framework for automated subsurface interpretation tools is reshaping product development roadmaps for vendors serving European environmental agencies and consulting firms. Stakeholders must monitor how regulatory pressure on Scope 3 emissions reporting transforms geophysical software from exploration support into mandatory compliance infrastructure.
Market Dynamics
Cloud-native seismic processing architectures are compressing project timelines from months to weeks, forcing incumbent vendors to reprice perpetual licenses against consumption-based alternatives or lose anchor clients in the Permian Basin and North Sea.
Growth Catalysts
- EU Green Deal methane mandates:Operators across the North Sea and Barents Sea must deploy continuous geophysical monitoring, creating mandatory software procurement cycles for emissions verification and leak detection.
- Full-waveform inversion:This computational technique delivers subsurface resolution previously requiring dense 3D acquisition, reducing exploration risk for deepwater frontier basins off Brazil and West Africa.
- US Permian Basin drilling intensity:Real-time geosteering analytics have become standard for lateral well placement, embedding software services into every rig contract across the Delaware and Midland sub-basins.
Market Restraints
- Specialized GPU cluster costs:Training neural networks for automated fault interpretation requires NVIDIA H100 or equivalent hardware, concentrating advanced capabilities among operators with $50 million-plus annual exploration budgets.
- Proprietary data lock-in:Multiclient seismic libraries controlled by PGS ASA and TGS restrict independent algorithm development, forcing smaller vendors into licensing dependencies for training datasets.
- Cross-border data sovereignty:Russia's 2023 subsoil data localization laws and China's cybersecurity reviews block cloud transfer of raw seismic, fragmenting processing workflows across jurisdictional boundaries.
Strategic Opportunities
- Carbon capture site characterization:The EU Innovation Fund and US 45Q tax credits are funding geophysical surveys for saline aquifer and depleted reservoir screening, opening a compliance-driven revenue stream separate from hydrocarbon exploration.
- Edge computing convergence:On-rig processing units from Dell and HPE paired with lightweight interpretation algorithms eliminate latency for real-time drilling decisions in remote West African and Australian basins.
- India's sedimentary basin revival:The Directorate General of Hydrocarbons has opened 26 new exploration blocks requiring modern seismic reprocessing, creating first-mover advantages for vendors establishing local cloud nodes.
Industry Challenges
- Geophysicist-data scientist hybrid shortage:Automated interpretation tools require staff who understand both wave propagation physics and TensorFlow pipelines, a combination rarely produced by traditional petroleum engineering programs.
- Legacy on-premise integration:Major operators in Norway and the UK North Sea maintain 15-20 year-old interpretation workstations that resist API connectivity with modern cloud-native platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geophysical Software Service Market |
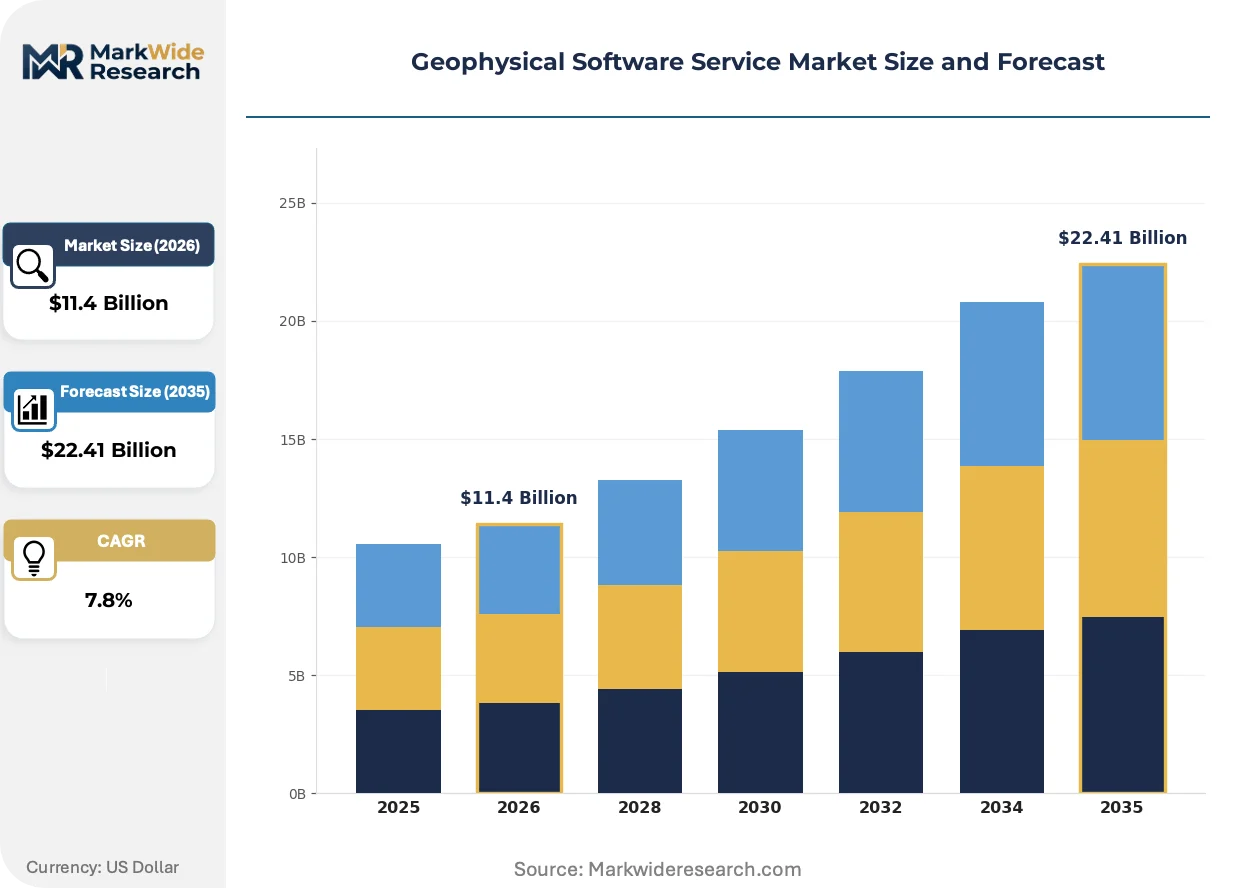
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $22.41 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seismic Processing, Geocellular Modeling, Reservoir Simulation, Exploration Planning Technology: Cloud Computing, Machine Learning, Artificial Intelligence, Advanced Visualization End User: Oil & Gas Companies, Mining Firms, Environmental Agencies, Consulting Firms Deployment: On-premise, Cloud-based, Hybrid, Remote Access |
| Companies Covered | PGS ASA, China Oilfield Services Limited, Schlumberger Limited, SensOre Ltd, Viridien, TGS ASA, Halliburton Company, Geoteric, CGG SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geophysical Software Service Market Emerging Trajectories
Neural network architectures trained on proprietary seismic libraries are compressing interpretation cycles while regulatory mandates transform geophysical software from exploration support into emissions compliance infrastructure.
Full-waveform inversion software is modularizing across the vendor landscape. This technique replaces ray-based velocity modeling with wave-equation solvers that handle complex salt bodies and basalt layers. Supermajors in the Gulf of Mexico and pre-salt Brazil are deploying it on 90% of new deepwater projects. The technology is modularizing service offerings, allowing operators to purchase specific inversion kernels without committing to full-platform licenses.
The EU AI Act's risk classification framework for automated subsurface interpretation tools is reshaping product roadmaps for vendors serving European environmental agencies. High-risk designation for AI systems influencing drilling decisions triggers conformity assessment requirements and audit trails. Environmental consultancies in Germany and the Netherlands are demanding explainable fault-detection algorithms to satisfy regulator scrutiny, forcing vendors to retrofit neural networks with attention-mapping visualization layers.
Consumption-based pricing for reservoir simulation is displacing perpetual license models across North American shale operators. Anadarko-scale independents now prefer hourly billing for compute-intensive history-matching workflows rather than capitalizing seven-figure upfront commitments. This shift is most visible in the Permian Basin, where private equity-backed producers optimize quarterly cash flow by aligning software spend with active drilling campaigns rather than maintaining year-round license pools.
Geophysical Software Service Market Segmentation
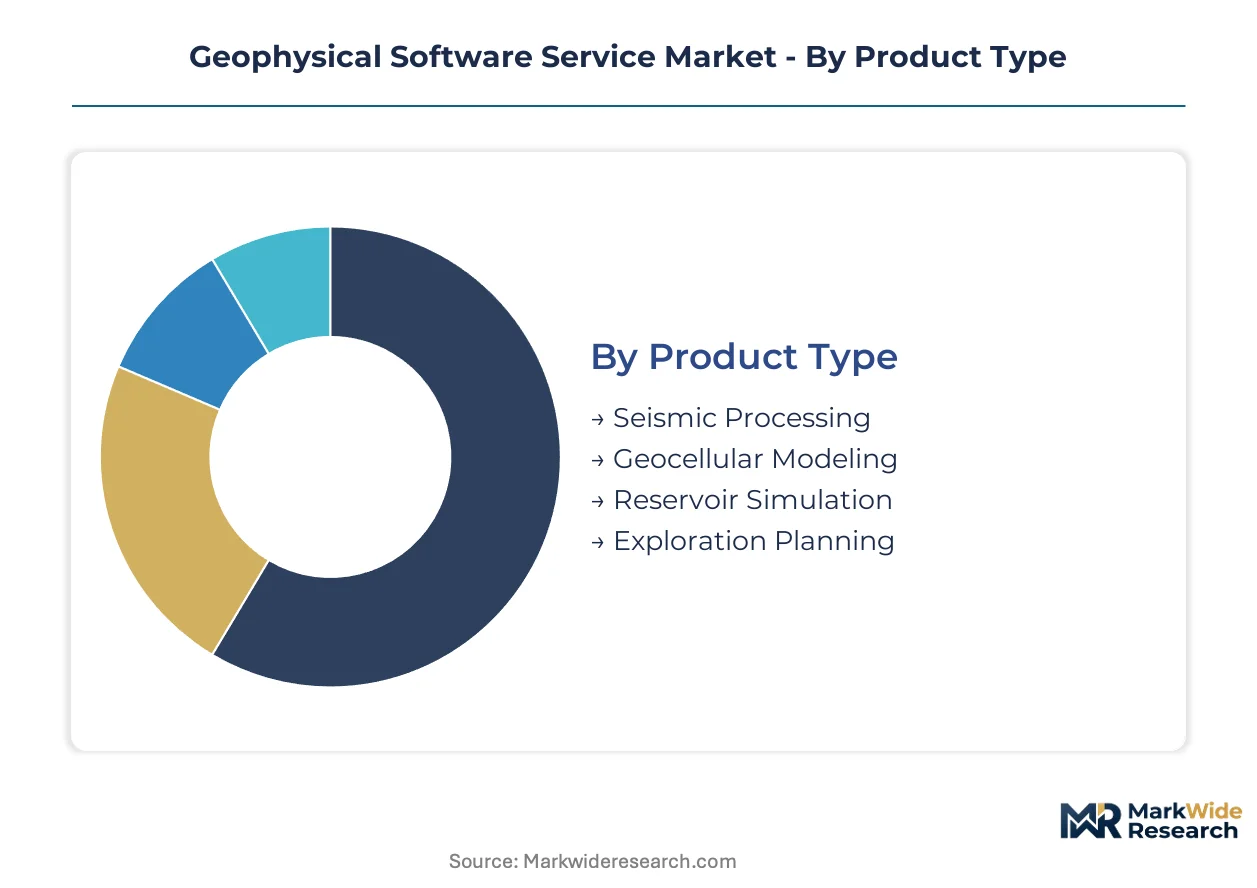
Geophysical software services fragment across four critical dimensions that determine procurement patterns, pricing power, and vendor positioning. Each segmentation axis reveals distinct margin pools and competitive dynamics that shape how Schlumberger, Halliburton, and specialized vendors capture value across exploration workflows.
Product Type:
Volume concentration sits with seismic processing, while premium pricing accrues to reservoir simulation and geocellular modeling platforms that anchor long-term client relationships.
- Seismic Processing:Computational platforms execute depth migration, noise attenuation, and velocity model building on terabyte-scale datasets. Operators in the US Permian Basin and Brazil's pre-salt basins deploy these tools across every exploration phase, with FERC pipeline safety directives mandating continuous subsurface monitoring that expands procurement cycles.
- Reservoir Simulation:Finite-difference and finite-element solvers forecast fluid flow, pressure depletion, and recovery factors across complex geologies. Supermajors in the Gulf of Mexico favor subscription-based licensing that shifts capital expenditure into operational budgets, aligning software spend with active drilling campaigns.
- Geocellular Modeling:Structural and stratigraphic grid construction for static reservoir characterization.
- Exploration Planning:Integrated workflows combining economic screening, acreage evaluation, and risk-weighted prospect ranking.
Today's leader: Seismic Processing. Tomorrow's challenger: Reservoir Simulation.
Technology:
Deployment cost tiers separate cloud-native architectures from legacy on-premise installations, with machine learning commanding premium pricing for automated interpretation capabilities.
- Cloud Computing:Elastic infrastructure eliminates upfront GPU cluster investments while enabling burst processing during intensive depth migration campaigns. North Sea operators leverage AWS and Azure nodes to compress project timelines from months to weeks, though Russia's subsoil data localization laws fragment workflows across jurisdictional boundaries.
- Machine Learning:Neural network architectures trained on proprietary seismic libraries automate fault detection, horizon tracking, and reservoir property prediction. The EU AI Act's high-risk designation for AI-influenced drilling decisions triggers conformity assessment requirements that reshape vendor product roadmaps for European environmental agencies.
- Artificial Intelligence:Broader cognitive computing applications spanning natural language processing of technical reports and automated well log interpretation.
- Advanced Visualization:Immersive 3D rendering and collaborative interpretation environments for distributed geoscience teams.
Cloud Computing anchors current procurement volumes. Machine Learning is climbing the fastest as operators seek to offset geophysicist-data scientist hybrid shortages.
End User:
Application maturity varies sharply across sectors, with oil and gas operators driving commercial scale while environmental agencies represent emerging compliance-driven demand.
- Oil & Gas Companies:Integrated supermajors and independents consume the majority of seismic processing and reservoir simulation capacity. US Permian Basin drilling intensity embeds real-time geosteering analytics into every rig contract, while deepwater frontier basins off West Africa demand full-waveform inversion for complex salt and basalt imaging.
- Environmental Agencies:Regulatory bodies deploy geophysical surveillance for methane emissions verification and carbon storage site characterization. The EU Green Deal's monitoring mandates and US EPA directives are transforming software from exploration support into mandatory compliance infrastructure.
- Mining Firms:Mineral prospecting applications including electromagnetic and gravitational surveys for ore body delineation.
- Consulting Firms:Specialized advisory services leveraging proprietary interpretation workflows for client-specific prospect evaluation.
Oil & Gas Companies dominate current revenue. Environmental Agencies represent the steepest expansion trajectory as regulatory pressure on Scope 3 emissions reporting intensifies.
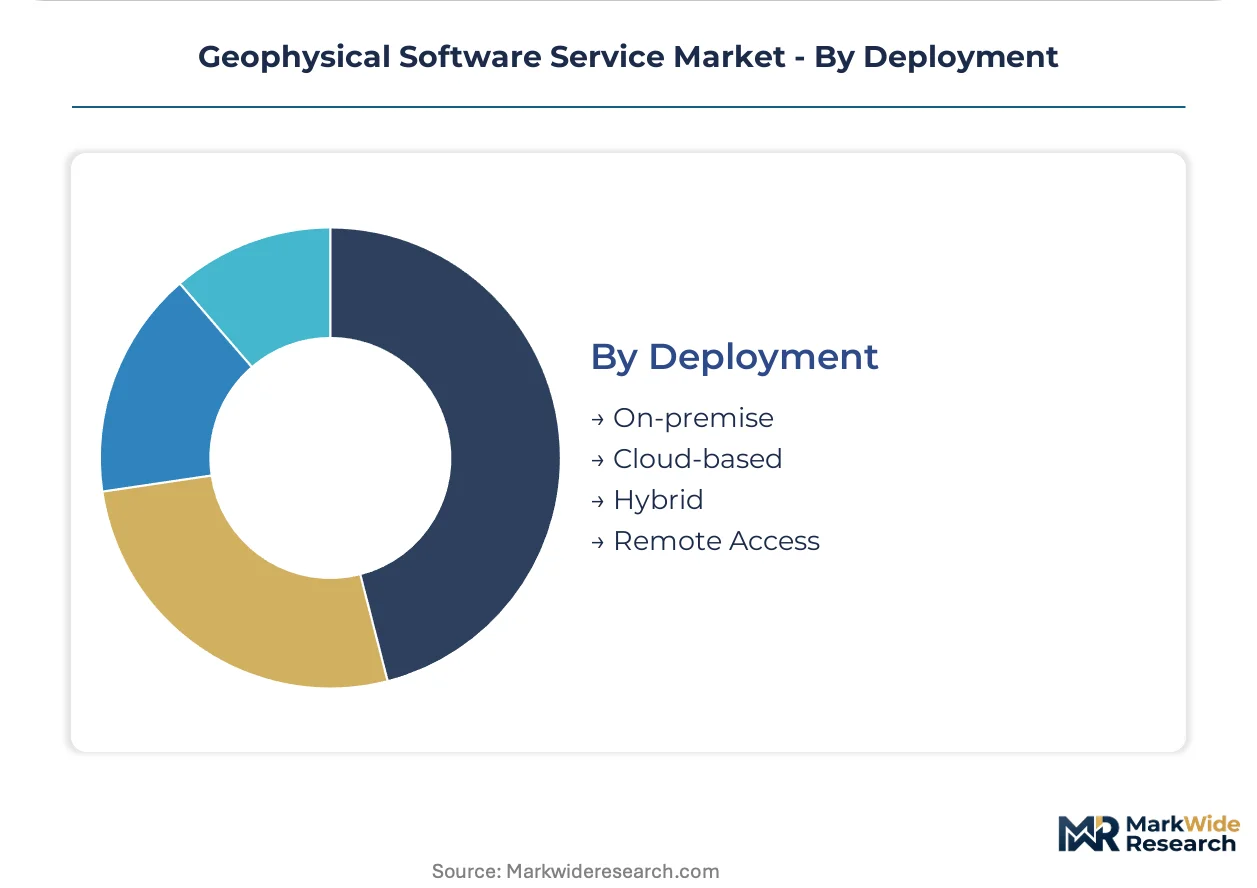
Deployment:
Customer type and security requirements dictate architecture selection, with hybrid models emerging as the compromise between performance and data sovereignty.
- Cloud-based:Consumption-based pricing eliminates perpetual license capital commitments while enabling elastic compute scaling. Private equity-backed producers in North American shale plays prefer hourly billing aligned with quarterly cash flow optimization rather than maintaining year-round license pools.
- On-premise:Legacy installations persist among major operators in Norway and the UK North Sea maintaining 15-20 year-old interpretation workstations that resist API connectivity with modern platforms.
- Hybrid:Sensitive processing stages execute on-premise while burst workloads leverage external cloud nodes.
- Remote Access:Lightweight client interfaces enabling distributed interpretation teams across multiple time zones.
Cloud-based deployment leads adoption curves. Hybrid architectures are gaining share fastest as cross-border data sovereignty concerns fragment processing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing procurement geography as operators migrate processing workloads toward jurisdictions with permissive data-transfer regimes and favorable tax treatment of cloud infrastructure. The United States and Norway currently capture the majority of high-value seismic processing spend, while India and Brazil emerge as cost-optimized alternatives for reprocessing legacy datasets.
United States
The Permian Basin in Texas and New Mexico drives the largest concentration of real-time geosteering software demand, with private equity-backed producers embedding analytics into every rig contract. EPA methane monitoring mandates under the Inflation Reduction Act compel continuous subsurface surveillance, expanding procurement cycles for emissions verification tools. Houston anchors vendor operations, with Schlumberger and Halliburton maintaining integrated software-hardware ecosystems for deepwater Gulf of Mexico projects.
Norway
North Sea operators deploy full-waveform inversion software across 90 percent of new deepwater developments, leveraging elastic cloud compute on AWS and Azure nodes to compress project timelines. The country's petroleum regulator requires detailed subsurface characterization for carbon storage site licensing, creating mandatory demand for geocellular modeling platforms. Stavanger and Oslo host specialized consultancies serving both hydrocarbon exploration and emerging CCS project screening.
Brazil
Pre-salt basin exploration off Rio de Janeiro and Espírito Santo demands complex salt-body imaging capabilities, with Petrobras and international partners licensing advanced depth migration tools. The national petroleum regulator ANP mandates comprehensive seismic data submission for block relinquishment, preserving multiclient library value for vendors. São Paulo hosts the primary software development centers serving Latin American operations.
India
The Directorate General of Hydrocarbons has opened 26 new exploration blocks under the Open Acreage Licensing Policy, requiring modern seismic reprocessing of legacy 2D data. Domestic operators prefer cloud-based deployment to avoid capital-intensive GPU cluster investments, creating first-mover advantages for vendors establishing Mumbai and Hyderabad processing nodes. The country's central bank guidelines on data localization complicate cross-border transfer of raw seismic, favoring indigenous service providers.
United Kingdom
North Sea decommissioning and carbon storage site characterization drive demand for geophysical environmental compliance tools, with the North Sea Transition Authority requiring detailed subsurface models for CCS licensing. London and Aberdeen host specialized consultancies integrating seismic interpretation with emissions monitoring workflows. Legacy on-premise installations from the 2000s resist API connectivity with modern cloud-native platforms, creating hybrid architecture opportunities.
Geophysical Software Service Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated supermajors controlling proprietary data libraries while independent vendors compete on algorithmic differentiation. The vendor base concentrates around three strategic archetypes: full-platform providers bundling hardware-software ecosystems, specialized interpretation boutiques, and multiclient data aggregators monetizing proprietary seismic libraries. M&A activity targets machine learning capabilities for automated fault detection, while strategic partnerships with cloud infrastructure providers enable elastic compute scaling without capital-intensive GPU cluster ownership.
Among full-platform providers, Schlumberger Limited and Halliburton Company occupy positions anchoring long-term client relationships through integrated service offerings. PGS ASA exemplifies the multiclient data archetype, controlling proprietary seismic libraries that dominate licensing markets. These three companies represent distinct competitive vectors: ecosystem breadth, drilling optimization specialization, and exclusive data access.
| Leading Market Players |
|---|
| PGS ASA |
| China Oilfield Services Limited |
| Schlumberger Limited |
| SensOre Ltd |
| Viridien |
| TGS ASA |
| Halliburton Company |
| Geoteric |
| CGG SA |
| Others |
Supply Flow & Price Mechanics
EU Green Deal methane mandates gate qualified supply for emissions-verification software suites, reserving premium-tier pricing access to vendors with certified environmental compliance modules and established regulator relationships.
Pricing Analysis
Capacity additions in India are reshaping price floors for cloud-native seismic processing, compressing margins on standard-tier offerings while premium reservoir simulation subscriptions anchored to full-waveform inversion capabilities sustain pricing power. Three-tier pricing structure across premium, standard, and economy levels separates perpetual-license incumbents from consumption-based challengers, with price differentiation driven by GPU cluster scale and algorithmic customization depth. Cost compression in standard tiers is intensifying because hyperscaler infrastructure commoditizes basic migration workflows. Private equity-backed shale operators exhibit highest price sensitivity, while supermajors in deepwater basins prioritize performance over hourly billing rates.
Supply Chain Analysis
Software license returns and workstation refurbishment flows create secondary markets that extend asset life cycles among North Sea operators maintaining legacy on-premise installations. Supply concentrates in the United States, Norway, and India, with proprietary multiclient seismic libraries anchoring value capture for data aggregators. Raw material dependencies span NVIDIA H100 GPU clusters, high-bandwidth memory modules, and specialized geophysical sensor arrays. Single-source vulnerability concentrates in Taiwan Semiconductor's advanced node production for AI training chips. Distribution runs through direct vendor relationships with supermajors and channel partnerships serving independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-based deployment transitions represent a margin-expansion story as consumption-based pricing eliminates perpetual-license discounting and shifts revenue recognition toward recurring, premium-tier subscriptions.
For Market Incumbents: Cement ecosystem lock-in by integrating proprietary multiclient seismic libraries with automated interpretation modules that resist modular unbundling. Expand GPU cluster partnerships with hyperscalers to neutralize capital intensity advantages threatening smaller cloud-native entrants. Prioritize certification investment for EU AI Act high-risk system conformity to defend against European environmental agency procurement shifts.
For New Entrants and Emerging Players: Enter via India's Open Acreage Licensing Policy reprocessing demand, where legacy 2D data modernization creates first-mover opportunities without incumbent data library dependencies. Target carbon capture site characterization workflows for environmental agencies, the steepest expansion trajectory with compliance-driven procurement cycles. Pursue joint-venture structures with domestic cloud node operators to navigate data localization requirements.
For Investors and Strategic Acquirers: Roll-up economics work for specialized machine learning boutiques because automated fault detection capabilities command acquisition premiums amid geophysicist-data scientist hybrid shortages. Five-to-ten-year viability hinges on neural network explainability retrofit costs for EU regulatory compliance. Monitor EPA methane monitoring mandate enforcement intensity as inflection indicator for emissions-verification software procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Elastic AWS and Azure compute nodes compress Permian Basin project timelines from months to weeks. |
| Machine Learning Capability Acquisition | Neural network architectures for automated fault detection offset critical geophysicist-data scientist staffing gaps. |
| Carbon Storage Site Characterization | EU Innovation Fund and US 45Q tax credits fund saline aquifer screening workflows outside hydrocarbon exploration. |
| Multiclient Data Library Expansion | Proprietary seismic archives in the North Atlantic and West Africa dominate licensing markets and anchor recurring revenue. |
| Edge Computing Partnership | On-rig Dell and HPE processing units eliminate latency for real-time geosteering decisions in remote West African basins. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with geoscience technology officers, petroleum engineering directors, environmental compliance leads, and cloud procurement specialists with secondary validation against SEC 10-K filings, FERC pipeline safety directives, EU regulatory databases, and hyperscaler infrastructure capex disclosures. Bottom-up segment sizing and top-down market triangulation cross-checked vendor revenue disclosures against end-user procurement patterns.
Comparable-period anchoring linked projection horizons to historical seismic processing campaign durations and reservoir simulation license renewal cycles across the modeling period. Segmentation dimensions spanned product type, deployment architecture, technology tier, end-user sector, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating drilling intensity metrics, carbon storage project pipelines, and cloud infrastructure adoption slopes.
Inputs from primary stakeholder interviews were available through the study window; gaps in real-time rig-level software utilization data introduce uncertainty bands around Permian Basin demand estimates. Forecasts embed assumptions regarding EPA methane mandate enforcement timelines and EU AI Act conformity assessment rollout schedules. Practitioners should monitor hyperscaler data center expansion announcements and national data localization policy developments for early signals of cloud-native processing capacity constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
ITSM Market
Software & Services
On-Demand Wellness Software Market
Software & Services
Global Decision Making Software Market
Software & Services
Animation Design Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Hackathon Management Software Market
Software & Services
Laboratory Management Software Market
Software & Services
Job Description Management Software Market
Software & Services
App Creation Software Market
Software & Services
Cemetery Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Performing Arts Software Market
Software & Services
Global Open API Market
Software & Services
Association Management Software Market
Software & Services
Patent Management Software Market
Software & Services
Dental Practice Management Software Market