
 Saas-Based SCM Market | 2026-2036
Saas-Based SCM Market Size, Share, and Industry Trends Forecast 2026-2036
Saas-Based SCM Market Intelligence
ISO 27001 certification is rotating as the primary gate for SaaS-Based SCM vendor selection among Fortune 500 procurement teams. SAP SE leverages its embedded ERP footprint to sustain cross-sell momentum into supply chain modules. Oracle Corporation anchors its competitive stance through database-to-cloud continuity for logistics workloads. Manhattan Associates specializes in warehouse-centric execution layers for high-velocity fulfillment operations.
SaaS-Based SCM denotes cloud-native software platforms that orchestrate procurement, logistics, inventory, and supplier coordination through multi-tenant architectures with API-first integration protocols and sub-second data synchronization across distributed nodes. These systems serve industrial and commercial users by replacing on-premises planning silos with real-time demand sensing and automated replenishment triggers. Inventory Management solutions dominate current revenue pools as manufacturers prioritize working-capital optimization, while Supplier Collaboration modules represent the fastest-expanding segment as tiered visibility requirements deepen. Public Cloud deployments capture the majority of new implementations given elastic scaling needs, though Hybrid Cloud configurations are gaining traction among regulated industries with data-residency constraints.
FDA validation requirements for pharmaceutical track-and-trace systems shape SCM feature roadmaps in life sciences, while EU GDPR mandates enforce data-sovereignty architectures for European deployments. The SEC's climate-disclosure rules are pressuring listed enterprises to embed emissions tracking into supplier scorecards. Procurement teams must evaluate whether vendor certification breadth matches their industry's compliance perimeter before committing to multi-year SaaS contracts.
Market Dynamics
API-first integration protocols are decomposing monolithic ERP silos into modular, composable supply chain stacks that enterprises assemble from specialized vendors rather than single-suite providers.
Growth Catalysts
- PLI scheme in India:Domestic manufacturing expansion under India's production-linked incentive framework is forcing legacy enterprises to modernize supplier coordination systems. Tier-1 automotive and electronics manufacturers are mandating real-time visibility into tier-2 and tier-3 vendor inventories.
- E-commerce fulfillment velocity:Distributed fulfillment networks require sub-second inventory synchronization across nodes. Direct-to-consumer brands are driving demand for warehouse-centric execution layers that orchestrate same-day and next-day delivery promises.
- GDPR data-sovereignty architectures:European enterprises must maintain residency-compliant supplier data storage. This regulatory pressure is accelerating hybrid cloud deployments that split processing between public infrastructure and local data centers.
Market Restraints
- ISO 27001 certification concentration:Fortune 500 procurement teams have elevated information security certification to a hard gate. Vendors lacking this credential face automatic disqualification from multi-year enterprise contracts regardless of functional capability.
- API standard fragmentation:Logistics data exchange lacks unified protocols across ocean freight, air cargo, and last-mile providers. Buyers must maintain multiple integration layers, inflating total cost of ownership and implementation timelines.
- Legacy ERP lock-in:Embedded on-premises supply chain modules from incumbent vendors create switching friction. Enterprises face multi-million dollar migration costs and operational risk during transition periods.
Strategic Opportunities
- Supplier Collaboration modules:Tiered visibility requirements are deepening as manufacturers seek predictive risk signals from sub-tier vendors. This application segment offers expansion potential beyond core inventory management functionality.
- SEC climate-disclosure integration:Listed enterprises must embed emissions tracking into supplier scorecards. SaaS vendors that natively integrate carbon accounting with procurement workflows capture compliance-driven replacement cycles.
- Hybrid cloud configurations:Regulated industries with data-residency constraints are adopting split architectures. Vendors offering seamless orchestration between elastic public scaling and captive private infrastructure differentiate against pure-cloud competitors.
Industry Challenges
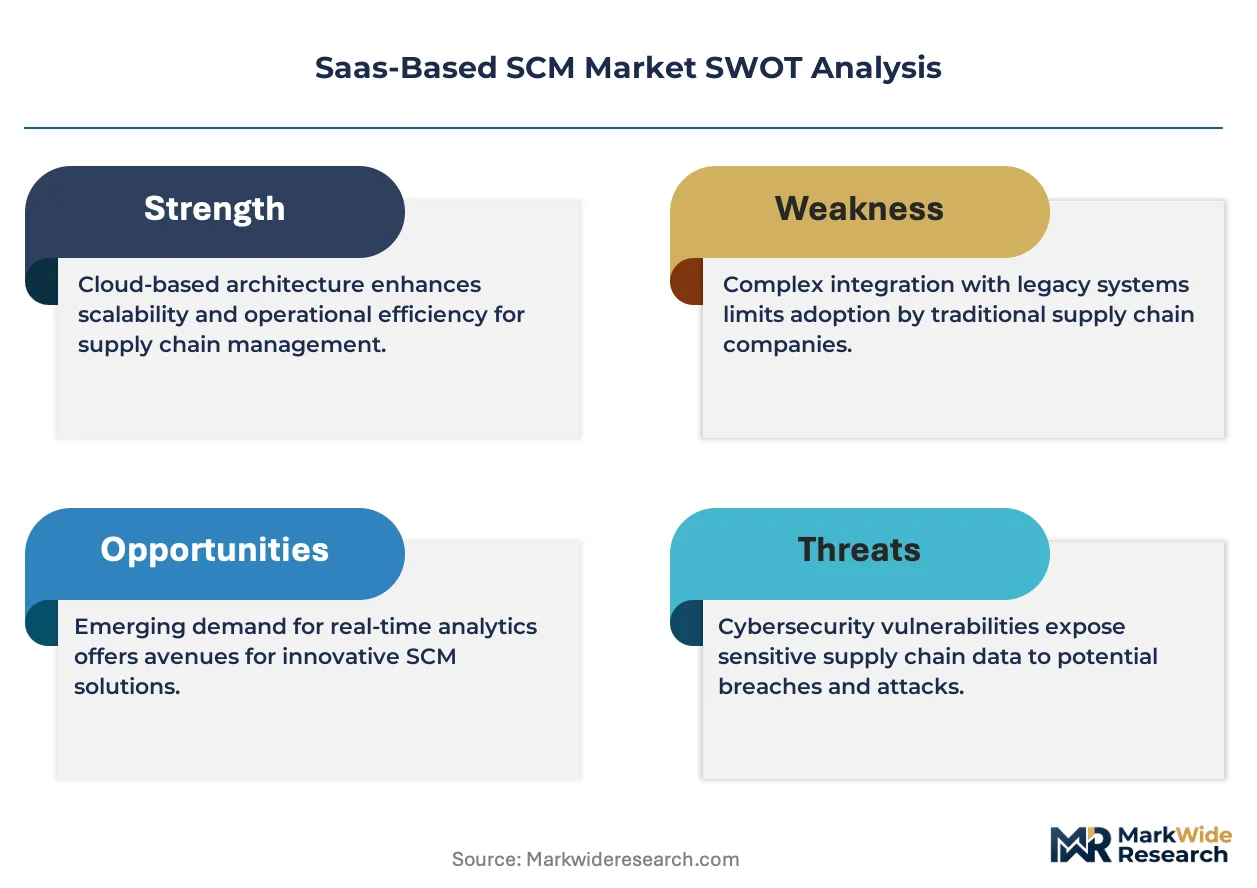
- Multi-tenant security architecture complexity:SaaS providers must isolate customer data while maintaining sub-second synchronization across distributed nodes. Breach incidents in shared environments trigger cascading contract terminations.
- Legacy system integration friction:Enterprises operate decades-old warehouse management and transportation planning systems. API-first vendors must build and maintain connectors for obsolete protocols, draining engineering resources from innovation roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saas-Based SCM Market |
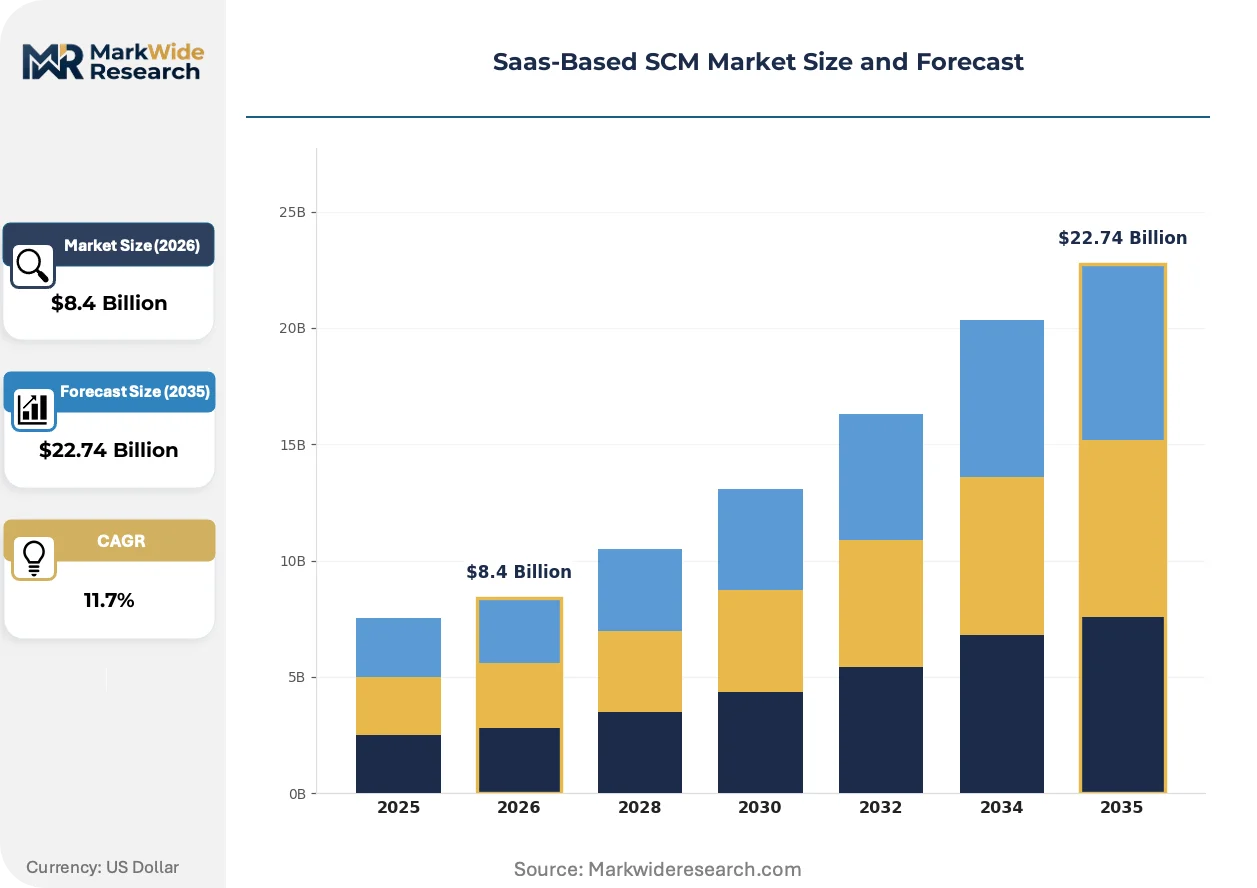
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Inventory Management, Supplier Collaboration, Order Management, Fleet Management End User: Manufacturers, Retailers, Distributors, E-commerce Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Integration, Support & Maintenance, Training |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, Infor, Blue Yonder Group, Inc., Manhattan Associates, Kinaxis Inc., Epicor Software Corporation, International Business Machines Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saas-Based SCM Market Strategic Shifts & Innovations
Microservices architecture is fragmenting supply chain software into specialized, interoperable components that buyers compose into custom stacks rather than accepting monolithic suite limitations.
Composable microservices are decomposing traditional ERP supply chain modules into discrete, API-connected functions for demand sensing, inventory optimization, and supplier risk monitoring. E-commerce platforms and third-party logistics providers are adopting these modular stacks fastest, replacing three-year implementation cycles with incremental capability deployment. This architectural shift is compressing vendor consolidation economics and elevating specialized execution-layer providers against suite incumbents.
EU CSRD mandates are forcing listed enterprises to collect and audit Scope 3 emissions data across supplier networks. Life sciences and automotive manufacturers face the steepest compliance burdens as their multi-tier supply chains span thousands of small vendors lacking carbon accounting capabilities. German and French industrial buyers are prioritizing SaaS vendors with embedded emissions tracking and automated CSRD reporting templates in procurement decisions.
Subscription pricing for supply chain software is displacing perpetual license models across mid-market manufacturing segments. CFOs prefer operational expenditure treatment and demand consumption-based scaling aligned with seasonal volume fluctuations. This preference shift is most visible among North American contract manufacturers and industrial distributors managing volatile demand patterns post-pandemic.
Saas-Based SCM Market Segmentation
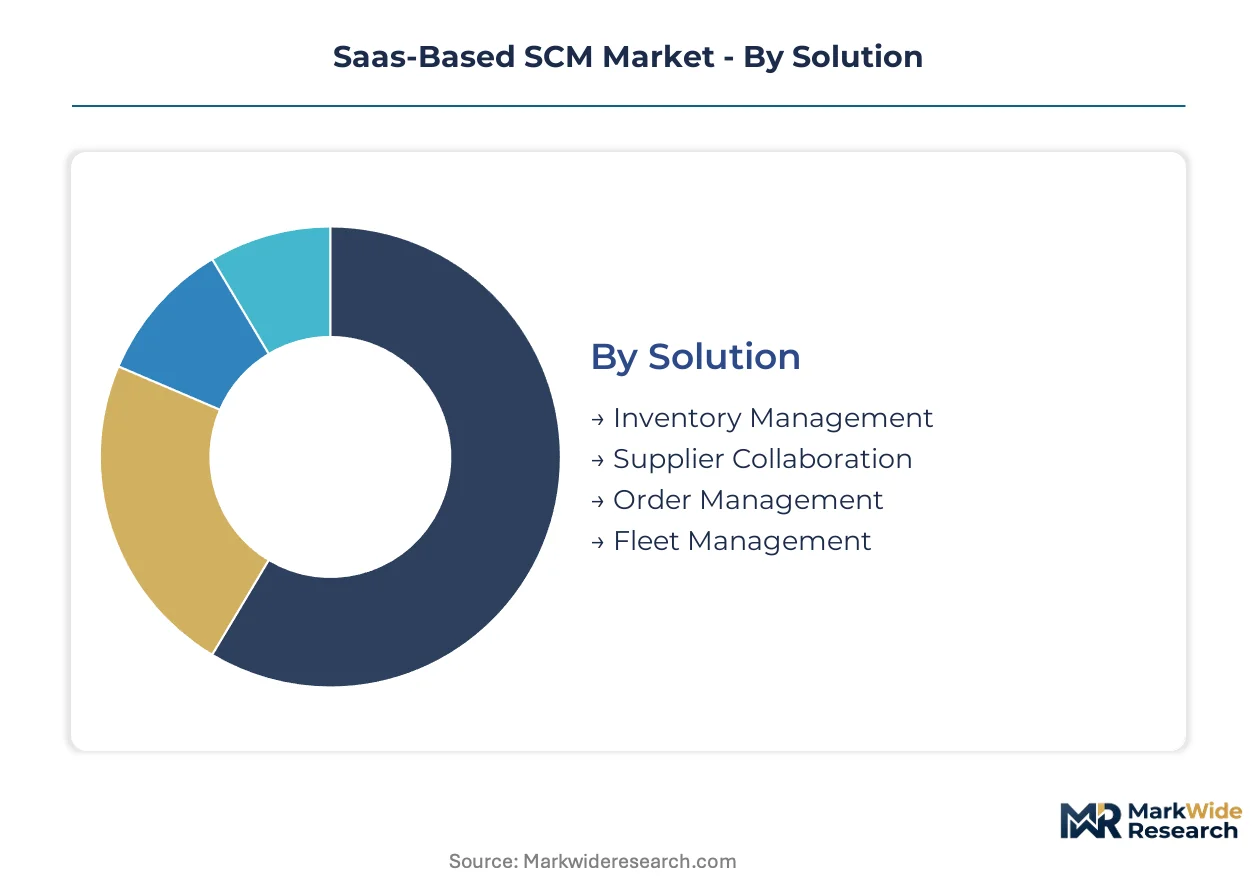
Segmentation in SaaS-Based SCM reveals how procurement priorities diverge across buyer archetypes. Cloud deployment preferences and solution modularity determine vendor selection criteria and contract structures.
Solution:
Channel mix varies sharply by solution type, with direct enterprise sales dominating high-complexity implementations while self-service platforms capture mid-market inventory modules.
- Inventory Management:Real-time stock visibility and automated replenishment algorithms form the technical core. Manufacturers in India under PLI scheme mandates are concentrating demand here as working-capital optimization becomes critical for competitive qualification.
- Supplier Collaboration:Tiered visibility portals enable predictive risk signals from sub-tier vendors. E-commerce platforms and automotive OEMs are driving fastest expansion as multi-tier traceability requirements deepen under EU CSRD emissions tracking mandates.
- Order Management:Omnichannel orchestration engines unify purchase-to-fulfillment workflows across fragmented sales channels.
- Fleet Management:GPS-integrated route optimization and carrier performance analytics for transportation asset utilization.
Inventory Management dominates installed base. Supplier Collaboration is where expansion concentrates.
End User:
Cost tier segmentation separates enterprise manufacturers with multi-year implementation budgets from velocity-focused e-commerce operators prioritizing month-to-month scalability.
- Manufacturers:Discrete and process industries deploy SCM for supplier quality gates and production scheduling synchronization. German automotive suppliers under KBA traceability requirements are mandating ISO 27001-certified platforms with embedded emissions accounting.
- E-commerce:Direct-to-consumer brands require sub-second inventory synchronization across distributed fulfillment nodes. Same-day delivery promises are forcing adoption of warehouse-centric execution layers with elastic scaling.
- Retailers:Brick-and-mortar and omnichannel operators managing seasonal demand volatility through demand sensing.
- Distributors:Industrial and consumer goods intermediaries optimizing cross-dock operations and vendor-managed inventory programs.
Manufacturers anchor current revenue pools. E-commerce is gaining share fastest.
Deployment:
Volume concentration in public cloud reflects elastic scaling needs, though margin profiles favor hybrid configurations with higher professional services attachment.
- Public Cloud:Multi-tenant architectures with API-first integration protocols serve high-velocity fulfillment networks. GDPR data-sovereignty constraints are limiting European adoption for sensitive supplier data categories.
- Hybrid Cloud:Split processing between public infrastructure and local data centers addresses regulated industries with data-residency requirements. Life sciences manufacturers under FDA validation protocols are adopting this architecture for pharmaceutical track-and-trace systems.
- Private Cloud:Single-tenant dedicated instances for defense contractors and critical infrastructure operators.
- On-Premises:Legacy perpetual license retention in highly regulated sectors with air-gapped security requirements.
Public Cloud captures majority of new implementations. Hybrid Cloud shows steepest expansion trajectory.
Service Type:
Customer type determines service mix, with enterprise manufacturers demanding consulting-heavy transformations while mid-market buyers prioritize rapid integration over strategic advisory.
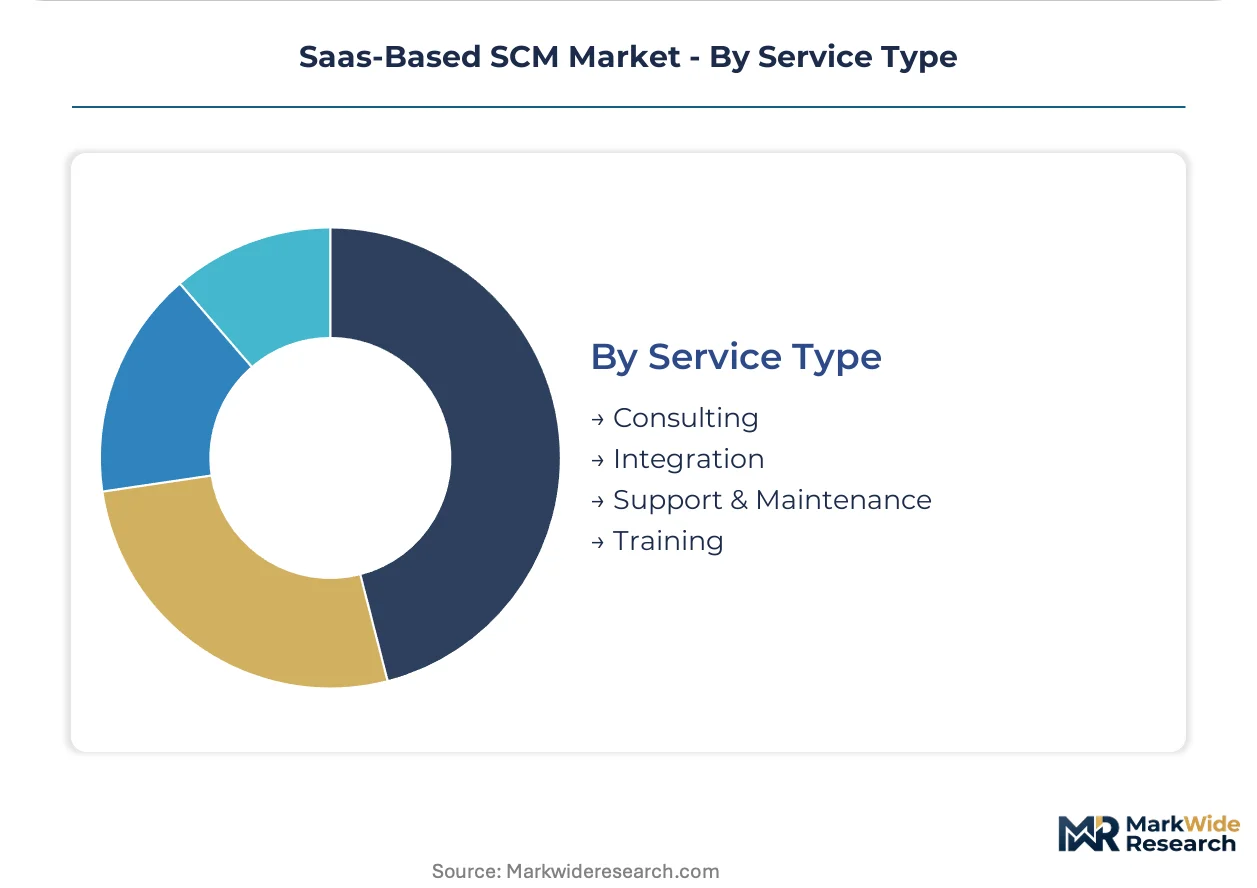
- Integration:API connector development and legacy ERP migration services consume the largest professional services budgets. Oracle and SAP embedded footprints create substantial switching friction requiring specialized migration expertise.
- Support & Maintenance:24/7 incident response and release management subscriptions generate recurring revenue stability. Fortune 500 procurement teams mandate ISO 27001-certified support operations as a hard gate.
- Consulting:Supply chain network design and change management advisory for complex multi-site deployments.
- Training:Certification programs and user enablement for self-sufficient platform administration.
Integration services dominate professional services revenue. Support & Maintenance provides the most predictable recurring streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme is reshaping supply chain infrastructure requirements across manufacturing corridors. Germany's cloud-first procurement mandates are accelerating vendor qualification timelines. These policy drivers are concentrating SaaS SCM demand in specific industrial clusters with compliance-heavy operational profiles.
United States
E-commerce fulfillment networks and automotive OEMs drive sub-second inventory synchronization demand. SEC climate-disclosure rules pressure listed enterprises to embed emissions tracking into supplier scorecards. The Detroit-Windsor automotive corridor and Seattle-Tacoma logistics hub concentrate warehouse-centric execution layer deployments.
Germany
Automotive suppliers under KBA traceability requirements mandate ISO 27001-certified platforms with embedded emissions accounting. EU CSRD mandates force listed enterprises to audit Scope 3 emissions across multi-tier supplier networks. The Stuttgart industrial region and Munich tech corridor anchor demand for hybrid cloud configurations with data-sovereignty compliance.
India
Domestic manufacturing expansion under the PLI scheme forces tier-1 automotive and electronics manufacturers to modernize supplier coordination systems. DGFT export documentation requirements intersect with real-time inventory visibility mandates. The Chennai-Sriperumbudur automotive belt and Bengaluru electronics corridor drive fastest SCM modernization cycles.
China
Dual carbon goals and MIIT smart manufacturing directives accelerate cloud-native supply chain adoption among state-owned manufacturers. SAMR data-localization requirements shape hybrid deployment architectures for foreign-invested enterprises. The Yangtze River Delta and Pearl River Delta manufacturing clusters concentrate demand for API-first integration protocols.
United Kingdom
Post-Brexit customs complexity drives demand for trade-compliance modules within SCM platforms. FCA disclosure requirements intersect with supply chain risk reporting for listed industrials. The Midlands manufacturing belt and London-Heathrow logistics corridor anchor professional services-intensive implementations.
Saas-Based SCM Market Key Industry Players
Player mix skews toward embedded ERP incumbents with cross-sell infrastructure and pure-play specialists with execution-layer depth. Market structure exhibits tiered consolidation around three strategic archetypes: suite incumbents leveraging database continuity, warehouse-centric execution specialists, and API-first composability vendors. Dominant competitive moves include M&A to fill capability gaps and strategic partnerships to bypass legacy integration friction.
Within the suite-incumbent tier, SAP SE and Oracle Corporation exemplify database-to-cloud continuity strategies that sustain cross-sell momentum into supply chain modules. Manhattan Associates occupies a position among execution-layer specialists targeting high-velocity fulfillment operations. These three anchors represent divergent architectural bets: embedded ERP extension versus modular composability versus warehouse-centric depth.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Infor |
| Blue Yonder Group, Inc. |
| Manhattan Associates |
| Kinaxis Inc. |
| Epicor Software Corporation |
| International Business Machines Corporation |
| Others |
Cost & Logistics Intelligence
API-first integration protocols replacing legacy EDI systems are simultaneously redrawing supply chain geography toward cloud infrastructure hubs and compressing implementation pricing tiers as engineering resource requirements fall.
Pricing Analysis
Cost-plus contracts indexed to public cloud compute unit pricing dominate enterprise SaaS SCM procurement, with subscription tiers stratifying across premium ISO 27001-certified deployments, standard multi-tenant configurations, and economy self-service platforms. Price differentiation centers on data-residency certification grade and professional services attachment depth. Pricing pressure intensifies in the mid-market segment as consumption-based scaling models displace fixed-seat licensing. E-commerce operators exhibit highest price sensitivity due to margin-thin fulfillment economics, while life sciences manufacturers under FDA validation requirements show lowest sensitivity given compliance-driven replacement cycles.
Supply Chain Analysis
Ireland and Singapore anchor primary cloud infrastructure hosting for European and Asia-Pacific SaaS SCM deployments respectively, with secondary processing nodes in Germany and India expanding under data-sovereignty mandates. The supply chain draws from specialized API connector engineering talent pools, hyperscaler compute capacity, and ISO certification audit services. Single-source vulnerability concentrates in hyperscaler infrastructure dependencies where AWS, Azure, and GCP outages cascade across multi-tenant customer bases. Distribution runs through direct enterprise sales teams for complex implementations and self-service digital channels for mid-market inventory modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SaaS-Based SCM penetration remains below saturation across tier-2 manufacturing segments in India and Southeast Asia, creating runway for vendors capturing PLI scheme-driven modernization budgets.
For Market Incumbents: Compound defensive positioning by embedding emissions accounting modules ahead of EU CSRD enforcement waves and acquiring specialized warehouse execution layer vendors before pure-play competitors consolidate that space. ISO 27001 certification maintenance and hybrid cloud orchestration capabilities serve as the priority defensive levers against API-first challengers eroding mid-market share.
For New Entrants and Emerging Players: ISO 27001 fast-track certification programs unlock Fortune 500 procurement gates previously closed to uncredentialed vendors. White-space opportunity concentrates in supplier collaboration modules for Indian automotive tier-1 manufacturers under PLI visibility mandates and in carbon accounting integrations for German industrial mid-caps facing KBA traceability requirements. A channel partnership route through systems integrators already embedded in SAP and Oracle migration projects offers the most penetrable go-to-market angle.
For Investors and Strategic Acquirers: The market sits at an early expansion phase that favors execution-layer specialists with warehouse-centric depth over suite incumbents facing composability disruption. Long-term viability over a five-to-ten year window hinges on API-first architectural positioning and hybrid cloud deployment capability. Acquisition target archetypes include ISO 27001-certified mid-caps with proven India PLI scheme customer references. The signal to watch is Fortune 500 procurement team shifts from security certification gating toward native emissions tracking as a hard requirement.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Certification | GDPR data-sovereignty compliance unlocks German automotive supplier contracts under KBA requirements. |
| API-First Platform Integration | Modular composability displaces monolithic ERP lock-in among e-commerce fulfillment operators. |
| Acquisition of Warehouse Execution Specialist | Same-day delivery promises demand sub-second inventory synchronization capabilities. |
| Embedded Emissions Accounting Launch | EU CSRD mandates force Scope 3 auditing across multi-tier supplier networks. |
| ISO 27001 Fast-Track Program | Fortune 500 procurement gates exclude uncertified vendors regardless of functional capability. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with supply chain directors at Indian automotive manufacturers, German industrial procurement leads, e-commerce fulfillment executives, and cloud infrastructure procurement officers. Secondary validation drew from SEC climate-disclosure filings, EU CSRD implementation guidance documents, DGFT export documentation requirements, and hyperscaler regional infrastructure expansion announcements. Bottom-up demand sizing across deployment models and solution types was triangulated against top-down market envelope estimates derived from public cloud SCM revenue disclosures.
Across the analysis window, the forecasting framework modeled segmentation dimensions including deployment architecture, organization size tier, vertical industry, integration complexity level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves fitted to historical cloud migration patterns and policy-mandated replacement timelines. Industry-specific inputs included PLI scheme qualification deadlines in India and FDA validation protocol requirements in life sciences.
Decision-makers should treat outputs as directional under assumptions of sustained cloud infrastructure investment and stable regulatory enforcement timelines; material deviation in hyperscaler pricing or trade policy would warrant model refresh. Recalibration cycles align with material shifts in PLI scheme disbursement rates and EU CSRD audit standard finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Smartphone OS Market
Software & Services
On-Call Scheduling Software Market
Software & Services
Semiconductor Fabrication Software Market
Software & Services
PCB Design Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Server Virtualization Software Market
Software & Services
Cloud-Based Dental Practice Management Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Workstation Software Market
Software & Services
Network Bandwidth Management Software Market
Software & Services
Global Translation Software Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
Enterprise Application Market
Software & Services
Spain HR Payroll Software Market