
 Global Chemical Indicator Inks Market | 2026-2036
Global Chemical Indicator Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemical Indicator Inks Market Foresight
A shortage of formulation chemists skilled in colorimetric stability engineering is unwinding capacity expansion plans across specialty ink producers. 3M leverages its polymer science infrastructure to sustain captive supply of pH-sensitive microencapsulation systems. STERIS Corporation anchors North American healthcare demand through sterilization process validation protocols that mandate chemical indicator integration. NiGK Corporation competes on thermal ink precision for autoclave monitoring applications in East Asian medical device supply chains.
Chemical indicator inks are color-change formulations containing leuco dyes, pH-sensitive chromophores, or redox-active compounds that undergo irreversible visual transitions when exposed to defined threshold conditions such as temperature, radiation, or chemical sterilants; these formulations typically achieve color transition accuracy within ±2°C for thermal grades and serve as passive verification tools in sterilization assurance, food spoilage detection, and environmental hazard warning systems. Thermal indicator inks dominate volume demand from healthcare sterilization workflows where autoclave cycle validation represents a non-discretionary compliance spend, while UV reactive inks represent the fastest-expanding margin pool as pharmaceutical cold-chain integrity monitoring adopts photochromic tamper evidence. Redox indicator inks occupy a mature niche in water quality test strips where price competition limits premium positioning despite stable replacement demand from municipal utilities and analytical services.
FDA sterilization assurance guidance, EU MDR Annex I general safety and performance requirements, and ISO 11140-1 chemical indicator classification standards collectively mandate documented color-change reliability for steam, ethylene oxide, and radiation sterilization processes. EPA and REACH frameworks constrain solvent selection and heavy metal content in indicator formulations, pushing manufacturers toward aqueous-based polymer systems with lower toxicity profiles. Stakeholders must monitor evolving harmonization between FDA recognition of ISO standards and EU notified body interpretation of MDR technical documentation requirements to anticipate qualification pathway divergence that could fragment product registration strategies.
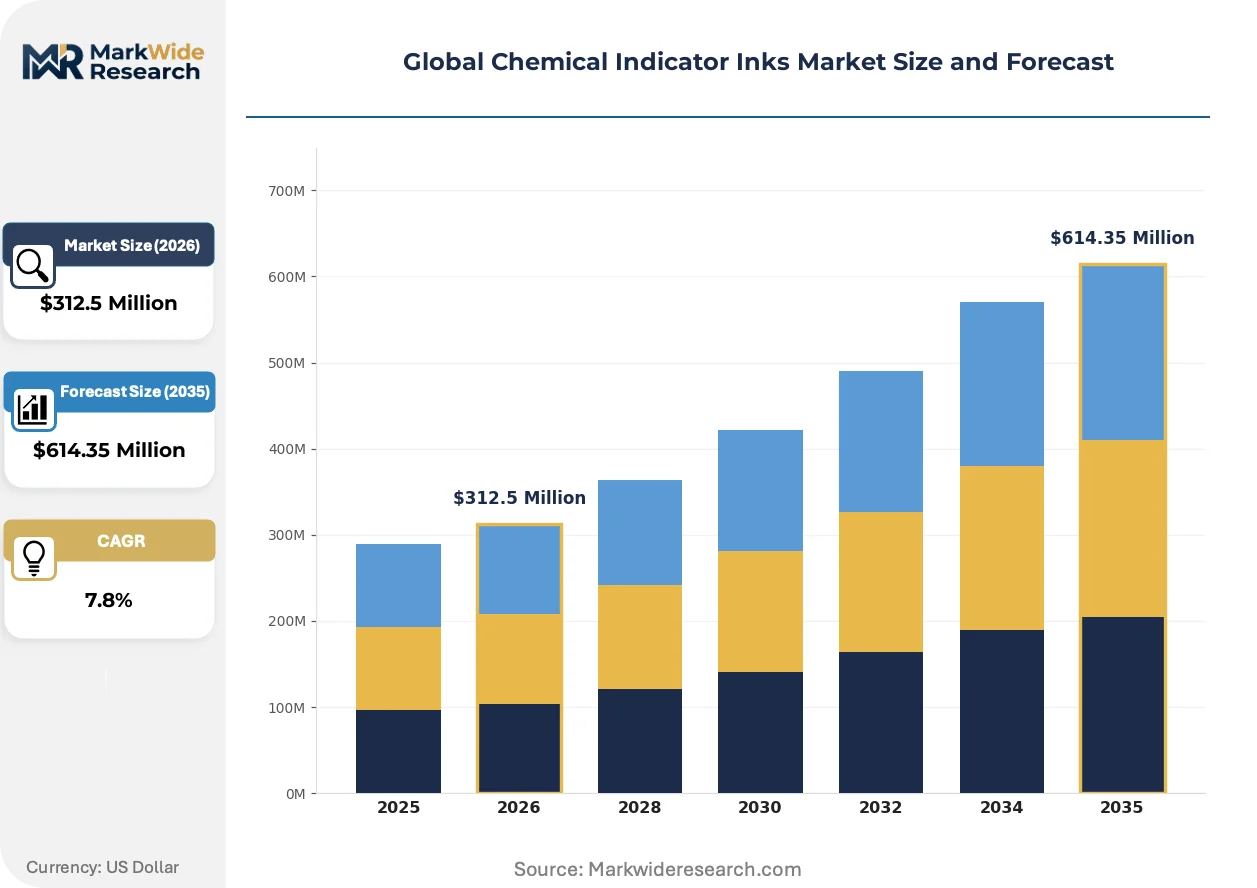
Market Dynamics
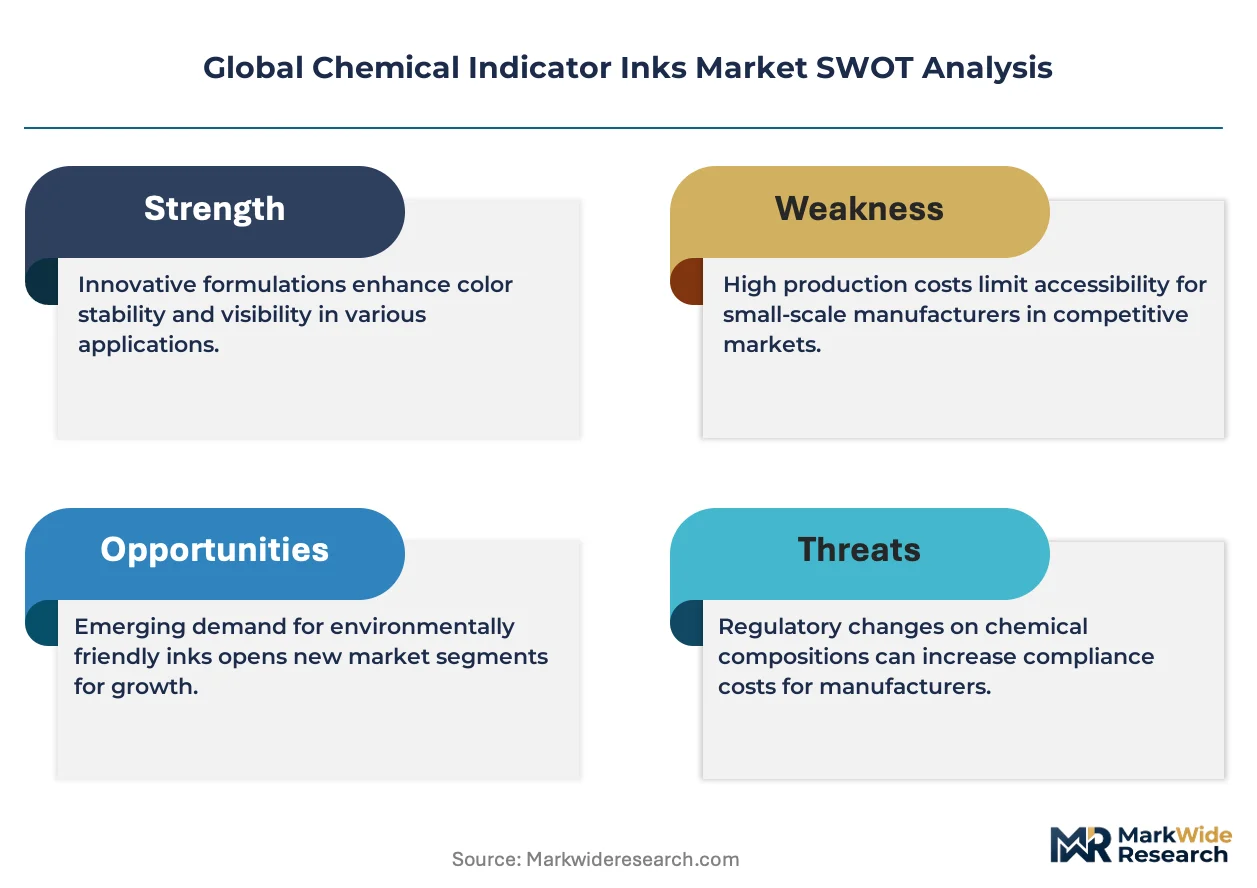
REACH and EU MDR compliance deadlines are forcing wholesale reformulation of leuco dye systems toward aqueous polymer bases, compressing legacy solvent-dependent supply chains while elevating technical qualification costs for specialty ink producers.
Growth Catalysts
- FDA sterilization assurance guidance:Mandated chemical indicator integration for steam and ethylene oxide validation protocols drives non-discretionary spend from healthcare kit manufacturers across North American hospital supply chains.
- Photochromic cold-chain monitoring:Pharmaceutical distribution networks adopt UV-reactive tamper-evidence inks for temperature excursion documentation, expanding addressable application scope beyond sterilization assurance.
- Japan's medical device export concentration:Precision thermal ink demand accelerates from East Asian autoclave monitoring requirements tied to surgical instrument sterilization workflows.
Market Restraints
- Petroleum-derived leuco dye volatility:Crude oil price swings transmit directly to chromophore raw material costs, squeezing margin stability for mid-tier formulation houses lacking long-term supply contracts.
- German specialty chemical supplier concentration:Three producers control high-purity redox-active compound supply, creating single-source vulnerability for indicator ink manufacturers dependent on consistent batch-to-batch colorimetric performance.
- Aqueous system technical ceiling:Water-based polymer matrices currently fail to achieve equivalent shelf-life stability versus solvent-borne formulations, limiting full regulatory-driven transition speed.
Strategic Opportunities
- Indian pharmaceutical packaging expansion:CDSCO-aligned sterilization assurance mandates create first-mover advantage for indicator ink suppliers establishing local formulation partnerships ahead of domestic medical device manufacturing scale-up.
- ISO 11140-1 Type 1 process indicators:Harmonized global classification standards enable single-SKU qualification across multiple regulatory jurisdictions, reducing registration friction for standardized thermal ink portfolios.
- Printed electronics convergence:Integration of conductive traces with colorimetric indicator layers enables smart packaging with wireless readability, opening diagnostic-grade monitoring applications beyond passive visual verification.
Industry Challenges
- Colorimetric stability engineering talent scarcity:Formulation chemists capable of engineering ±2°C transition accuracy across variable humidity conditions command premium compensation, constraining R&D bandwidth at specialty ink producers.
- Dual REACH-MDR documentation burden:ECHA substance registration requirements and EU notified body technical file reviews operate on asynchronous timelines, fragmenting product launch coordination for European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemical Indicator Inks Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $614.35 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: pH Indicator Inks, Redox Indicator Inks, Thermal Indicator Inks, UV Reactive Inks, Fluorescent Inks Application: Food Packaging, Water Quality Monitoring, Healthcare Kits, Industrial Safety, Environmental Testing End User: Packaging Manufacturers, Diagnostic Laboratories, Safety Equipment Providers, Analytical Services, Research Institutions Packaging Type: Cartridge, Bottle, Drum, Tube, Sachet |
| Companies Covered | Riken Chemical Co Ltd., 3M, STERIS Corporation, NiGK Corporation, LA-Co Industries, North American Science Associates Inc. (NAMSA), Propper Manufacturing Company, Inc., SteriTec Products Inc., GKE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemical Indicator Inks Market Shifts & Advancements
Microencapsulation architectures and photochromic molecular engineering are compressing indicator footprint dimensions while expanding functional integration possibilities across pharmaceutical and medical device packaging workflows.
Microencapsulated pH-sensitive dye systems is miniaturizing indicator geometries to sub-millimeter feature sizes compatible with narrow-gauge catheter packaging and microfluidic diagnostic cartridge surfaces. Medical device manufacturers in Switzerland and the United States adopt these formats for integration into minimally invasive instrument sterile barriers where visual verification space is constrained. The technology is miniaturizing passive indicator deployment from package exterior labels to direct product-contact surfaces, compressing sterilization assurance into geometries previously inaccessible to conventional ink deposition.
EU MDR Annex I general safety and performance requirements now explicitly reference chemical indicator reliability documentation for sterile barrier systems, elevating technical file scrutiny intensity for Class IIa and above medical devices. Notified bodies in Germany and the Netherlands demand extended accelerated aging data for color-change permanence, extending qualification timelines by six to eighteen months for reformulated aqueous systems. Thermal indicator ink producers serving European healthcare markets respond by front-loading stability testing investments to secure Article 10 technical documentation acceptance.
Hospital procurement consortia consolidate sterilization consumable purchasing through centralized distribution agreements, compressing supplier count from fragmented regional distributors to national-scale logistics platforms. Group purchasing organizations in the United States and United Kingdom aggregate chemical indicator demand across multi-hospital networks, displacing direct manufacturer relationships with tiered volume-commitment contracts. This concentration shifts pricing leverage toward buyers capable of committing to multi-year sterilization assurance program standardization, favoring ink suppliers with scale-tolerant cost structures and documented FDA 510(k) or MDR Article 10 compliance histories.
Global Chemical Indicator Inks Market Segmentation
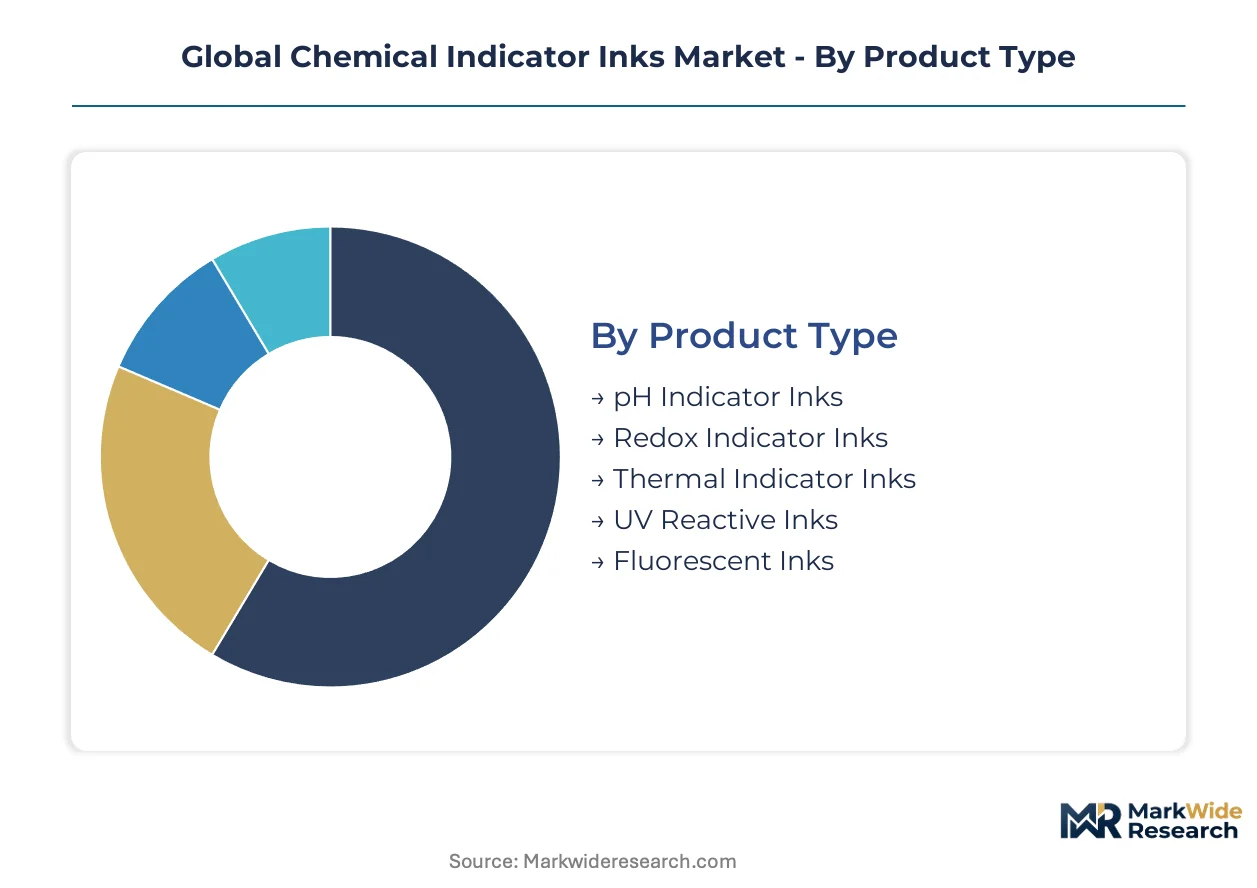
Chemical indicator inks fragment across functional chemistries, application environments, and packaging logistics that each impose distinct formulation constraints. Segmentation clarity enables suppliers to align R&D investments with the technical qualification pathways and volume concentration patterns that govern profitability in this compliance-driven market.
Product Type:
Thermal and pH indicator formulations face the most acute substitution pressure from emerging photochromic and conductive-polymer alternatives, forcing incumbents to defend performance premiums through precision engineering.
- Thermal Indicator Inks:Leuco dye systems encapsulated in polymer matrices undergo irreversible color transitions at defined temperature thresholds, typically achieving ±2°C accuracy. Demand concentrates in German and Japanese autoclave sterilization workflows where FDA and PMDA validation protocols mandate documented thermal excursion evidence.
- UV Reactive Inks:Photochromic molecular architectures enable reversible or irreversible color shifts upon ultraviolet exposure, supporting pharmaceutical cold-chain tamper evidence applications. Swiss and United States pharmaceutical packaging networks adopt these formats for temperature excursion documentation where visual verification must survive extended logistics cycles.
- pH Indicator Inks:Chromophore systems responsive to hydrogen ion concentration changes serve food spoilage detection and diagnostic test strip applications.
- Redox Indicator Inks:Electron-transfer-active compounds signal oxidation-reduction potential shifts in water quality monitoring and industrial process control.
- Fluorescent Inks:Emissive dye systems provide high-visibility signaling under specific excitation wavelengths for safety equipment and environmental hazard marking.
Thermal indicator inks anchor the volume base while UV reactive inks gain share at the steepest rate.
Application:
Cost-tier stratification separates premium healthcare validation spend from price-commoditized industrial safety applications, with mid-tier environmental testing occupying an unstable competitive position.
- Healthcare Kits:Sterilization assurance applications demand ISO 11140-1 Type 1 process indicators with documented batch-to-batch colorimetric reliability. United States hospital procurement consortia and EU notified body technical file requirements in Germany and the Netherlands drive non-discretionary formulation investments.
- Food Packaging:Freshness indicators and intelligent packaging formats integrate pH-sensitive layers directly into barrier films. Japanese and Swiss food exporters deploy these systems to satisfy extended cold-chain documentation requirements for premium perishable distribution.
- Water Quality Monitoring:Municipal utilities and analytical services consume redox indicator formats for residual chlorine and dissolved oxygen detection.
- Industrial Safety:Chemical hazard warning systems and gas detection applications utilize fluorescent and colorimetric formats for high-visibility alerting.
- Environmental Testing:Field-deployable test kits for soil and air quality assessment employ portable indicator chemistries with simplified interpretation protocols.
Healthcare kits command the highest margin tier while food packaging applications expand most quickly as intelligent packaging adoption accelerates.
End User:
Customer-type concentration favors packaging manufacturers with scale-tolerant cost structures, while diagnostic laboratories impose the most demanding technical qualification timelines.
- Packaging Manufacturers:Medical device and pharmaceutical sterile barrier producers integrate indicators directly into primary packaging formats. German and United States contract packaging organizations consolidate purchasing through multi-year sterilization assurance program standardization.
- Diagnostic Laboratories:Clinical and research testing facilities demand precise pH and redox indicator performance for assay validation. CDSCO-aligned mandates in India and FDA quality system regulations in the United States extend supplier qualification cycles.
- Safety Equipment Providers:Industrial hygiene and personal protective equipment manufacturers incorporate visual hazard indicators into product designs.
- Analytical Services:Third-party testing laboratories consume standardized indicator formats for environmental and food safety compliance documentation.
- Research Institutions:Academic and government laboratories drive early-stage formulation evaluation for next-generation indicator chemistries.
Packaging manufacturers represent the largest volume channel while diagnostic laboratories generate the steepest expansion trajectory through precision assay integration.
Packaging Type:
Logistics-scale concentration shapes format preferences, with high-throughput healthcare kit production favoring cartridge and bottle configurations over bulk drum supply.
- Cartridge:Precision dispensing systems compatible with automated inkjet and flexographic deposition equipment serve high-volume medical device packaging lines. United States and German sterile barrier manufacturers specify cartridge formats for cleanroom-compatible changeover protocols.
- Bottle:Hand-dispensing containers support mid-scale formulation applications and laboratory-scale validation work. Swiss and Japanese specialty ink producers package aqueous-based thermal indicators in bottle formats for regional distributor networks.
- Drum:Bulk liquid containment serves industrial-scale water quality monitoring and safety equipment manufacturing with lower per-unit logistics costs.
- Tube:Collapsible aluminum or plastic tubes enable precise manual application for repair, maintenance, and small-batch diagnostic cartridge production.
- Sachet:Single-use pouches support field-deployed environmental testing kits and emergency response applications requiring portable, contamination-protected supply.
Cartridge formats dominate healthcare volume while bottle configurations climb fastest through diagnostic laboratory and research institution procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA sterilization assurance guidance anchors the United States as the dominant geography, with Germany, Japan, India, and Switzerland forming the remaining demand concentration nodes for high-grade thermal and redox indicator formulations.
United States
Hospital procurement consortia and group purchasing organizations aggregate chemical indicator demand across multi-hospital networks. FDA 510(k) clearance requirements and quality system regulations extend supplier qualification cycles for sterile barrier manufacturers. Greater Boston and Research Triangle Park host contract packaging organizations standardizing sterilization assurance programs through multi-year volume commitments.
Germany
Notified bodies in Berlin and Munich demand extended accelerated aging data for EU MDR Article 10 technical documentation. REACH substance registration requirements and ECHA compliance deadlines compress legacy solvent-dependent supply chains. The Rhine-Ruhr industrial corridor concentrates specialty chemical suppliers controlling high-purity redox-active compound production.
Japan
PMDA validation protocols mandate documented thermal excursion evidence for surgical instrument sterilization workflows. METI industrial standards support precision thermal ink demand from medical device export supply chains. The Kansai region around Osaka anchors autoclave monitoring application manufacturing for East Asian markets.
India
CDSCO-aligned sterilization assurance mandates create first-mover positioning for indicator ink suppliers establishing local formulation partnerships. Pharmaceutical packaging expansion and domestic medical device manufacturing scale-up drive diagnostic laboratory procurement. Maharashtra and Gujarat host emerging contract packaging organizations adopting ISO 11140-1 Type 1 process indicators.
Switzerland
Swissmedic technical file requirements elevate scrutiny for Class IIa and above medical device sterile barrier systems. Microencapsulated pH-sensitive dye systems miniaturize indicator geometries for minimally invasive instrument packaging. Basel and Zurich medical device manufacturers deploy sub-millimeter feature sizes for narrow-gauge catheter packaging integration.
Global Chemical Indicator Inks Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with polymer science infrastructure and sterilization process validation protocols serving as primary differentiation vectors. Three strategic archetypes populate the competitive terrain: diversified materials conglomerates with captive ink formulation capabilities, sterilization equipment specialists with integrated indicator supply, and precision chemical specialists focused on colorimetric stability engineering. Dominant competitive moves include backward integration into chromophore raw material production and strategic partnerships with medical device contract packaging organizations.
Among diversified materials conglomerates, 3M leverages polymer science infrastructure to sustain captive supply of pH-sensitive microencapsulation systems. STERIS Corporation anchors North American healthcare demand through sterilization process validation protocols. NiGK Corporation occupies a position within the precision thermal ink specialist tier, serving East Asian autoclave monitoring applications.
| Leading Market Players |
|---|
| Riken Chemical Co Ltd. |
| 3M |
| STERIS Corporation |
| NiGK Corporation |
| LA-Co Industries |
| North American Science Associates Inc. (NAMSA) |
| Propper Manufacturing Company, Inc. |
| SteriTec Products Inc. |
| GKE GmbH |
| Others |
Supply & Pricing Matrix
FDA sterilization assurance guidance and EU MDR Article 10 technical documentation requirements gate both supplier qualification and price differentiation simultaneously, compressing mid-tier formulation houses while rewarding incumbents with documented compliance histories. Certification-grade thermal inks command substantial premiums over industrial safety grades, yet hospital procurement consortia extract volume concessions that erode margin buffers for non-integrated producers.
Pricing Analysis
German thermal ink formulations trade at substantial premiums to Indian-sourced alternatives, reflecting batch-to-batch colorimetric reliability investments and REACH registration sunk costs. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 11140-1 Type 1 certification status and autoclave validation protocol documentation depth. Pricing pressure stems from petroleum-derived leuco dye cost volatility transmitting directly to chromophore raw material expenses. Packaging manufacturers with multi-year sterilization assurance program commitments exhibit lowest price sensitivity, while municipal water utilities purchasing redox indicator formats remain most cost-responsive.
Supply Chain Analysis
Germany, Japan, and the United States anchor high-purity redox-active compound and precision thermal ink production, with the Rhine-Ruhr corridor hosting three dominant specialty chemical suppliers. Formulation chemistry draws from petroleum-derived leuco dyes, aqueous polymer matrices, and pH-sensitive chromophores sourced through long-term offtake agreements. Single-source vulnerability concentrates in high-purity redox-active compound supply, where batch-to-batch colorimetric performance consistency limits qualified alternative sources. Distribution runs through medical device contract packaging organizations and hospital group purchasing organization platforms, displacing fragmented regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as pharmaceutical cold-chain integrity monitoring adopts photochromic tamper-evidence formats, extending addressable application scope beyond sterilization assurance into temperature excursion documentation.
For Market Incumbents: Compound formulation chemistry expertise into printed electronics convergence opportunities, integrating conductive traces with colorimetric indicator layers for wireless-readable smart packaging. Deepen backward integration into chromophore raw material production to offset petroleum-derived leuco dye cost volatility squeezing mid-tier competitors. Secure extended accelerated aging data investments ahead of EU notified body technical file intensification for aqueous system qualifications.
For New Entrants and Emerging Players: Anchor in Indian pharmaceutical packaging expansion ahead of CDSCO-aligned sterilization assurance mandate enforcement, establishing local formulation partnerships before domestic medical device manufacturing scale-up consolidates supplier relationships. Target diagnostic laboratory precision assay integration as the most penetrable end-user segment, leveraging ISO 11140-1 Type 1 process indicator standardization to reduce multi-jurisdiction registration friction. Pursue university technology transfer partnerships for microencapsulation architecture access.
For Investors and Strategic Acquirers: EU MDR Annex I general safety and performance requirements reshapes the acquisition landscape toward formulation houses with documented Article 10 technical documentation acceptance and aqueous polymer matrix stability engineering capabilities. Long-term viability favors precision chemical specialists with colorimetric stability engineering talent depth over commodity industrial safety ink producers. Watch harmonization progress between FDA recognition of ISO standards and EU notified body interpretation divergence as the signal indicating qualification pathway fragmentation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromophore Production | Captures margin from petroleum-derived leuco dye volatility while securing batch-to-batch colorimetric consistency for FDA-validated formulations. |
| Microencapsulation Architecture Miniaturization | Enables sub-millimeter indicator deployment for Swiss and United States minimally invasive instrument sterile barrier integration. |
| Aqueous Polymer Matrix Reformulation | Addresses REACH and EU MDR compliance deadlines while extending shelf-life stability to match solvent-borne legacy performance. |
| Printed Electronics Convergence Partnership | Opens diagnostic-grade wireless-readable monitoring applications beyond passive visual verification for pharmaceutical cold-chain networks. |
| Indian Local Formulation Partnership | Positions ahead of CDSCO-aligned mandate enforcement and domestic medical device manufacturing scale-up in Maharashtra and Gujarat. |
Research Methodology
A spread of perspectives from sterilization process validation engineers, medical device packaging procurement leads, specialty ink formulation chemists, and EU notified body technical file reviewers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with hospital group purchasing organization contract managers and biomedical engineers overseeing sterile barrier qualification. Secondary validation drew from FDA 510(k) filings, ECHA substance registration databases, ISO 11140-1 standard documentation, and SEC disclosures from diversified materials conglomerates with indicator ink segments. Bottom-up volume modeling triangulated against top-down healthcare sterilization consumable expenditure patterns.
Segmentation dimensions modeled include functional chemistry type, application environment, end-user category, and packaging logistics format across the projection horizon. Thermal indicator ink demand anchored volume projections through autoclave cycle validation spend analysis, while UV reactive ink growth rates derived from pharmaceutical cold-chain integrity monitoring adoption curves. CAGRs were synthesized from regulatory mandate enforcement timelines and hospital procurement consortia consolidation patterns. Industry-specific forecast inputs incorporated REACH registration deadline impacts and EU MDR technical documentation review cycle extensions.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and petroleum feedstock price stability; material deviation in either would warrant model refresh. Specific risk factors include asynchronous ECHA-EU notified body timeline fragmentation and aqueous system shelf-life stability technical ceiling constraints. Recalibration cycles align with material shifts in harmonization between FDA and EU MDR qualification pathway divergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Ink-Cartridge Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Ink Resins Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Security Printing Market
Printing Inks
North America Printing Inks Market
Printing Inks
Global Decorative Print Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Specialty Ink Market
Printing Inks
Global Printing Blanket Market