
 Global Digital Textile Printing Inks Market | 2026-2036
Global Digital Textile Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Digital Textile Printing Inks Market Foresight
Market Context
Home furnishing demand is decoupling from traditional bulk textile orders as interior decorators and printing service providers shift toward short-run, customized fabric production. Huntsman Corporation leverages its reactive dye chemistry portfolio to serve high-color-fastness apparel applications across Asian manufacturing hubs. BASF SE anchors European supply chains with pigment ink formulations that meet stringent chemical safety protocols. DuPont de Nemours competes through aqueous inkjet technologies optimized for technical textiles and automotive seating fabrics.
Technical Definition and Segment Structure
Digital textile printing inks comprise formulated colorant systems—reactive, acid, pigment, disperse, sublimation, and UV-curable chemistries—designed for direct deposition onto fabric substrates via piezoelectric or thermal inkjet printheads at resolutions typically exceeding 300 dpi, enabling on-demand pattern generation without rotary screen or gravure cylinder setup. Sublimation inks dominate transfer printing for polyester sportswear, while pigment inks are gaining structural share in cotton apparel as water-based formulations reduce volatile organic compound emissions. UV-curable segments occupy premium margin pools in technical textiles and automotive seating, where durability standards exceed conventional wash-fastness requirements.
Regulatory Framework and Outlook
EPA regulations in the United States, REACH in Europe, and China's MEE enforcement of dual carbon goals are collectively restricting solvent-based formulations and accelerating water-based and UV-curable ink adoption across all major manufacturing regions. OEKO-TEX and ZDHC certification standards are reshaping procurement criteria for fabric manufacturers and garment producers sourcing inks at scale. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions and biocide regulations, as these chemical classes appear in multiple ink formulations and face intensifying scrutiny from environmental agencies and brand sustainability mandates.
Market Dynamics
The shift from rotary screen to inkjet deposition is compressing minimum order quantities from thousands of meters to single-digit yardage, forcing reformulation of supply economics across textile chemistry value chains.
Growth Catalysts
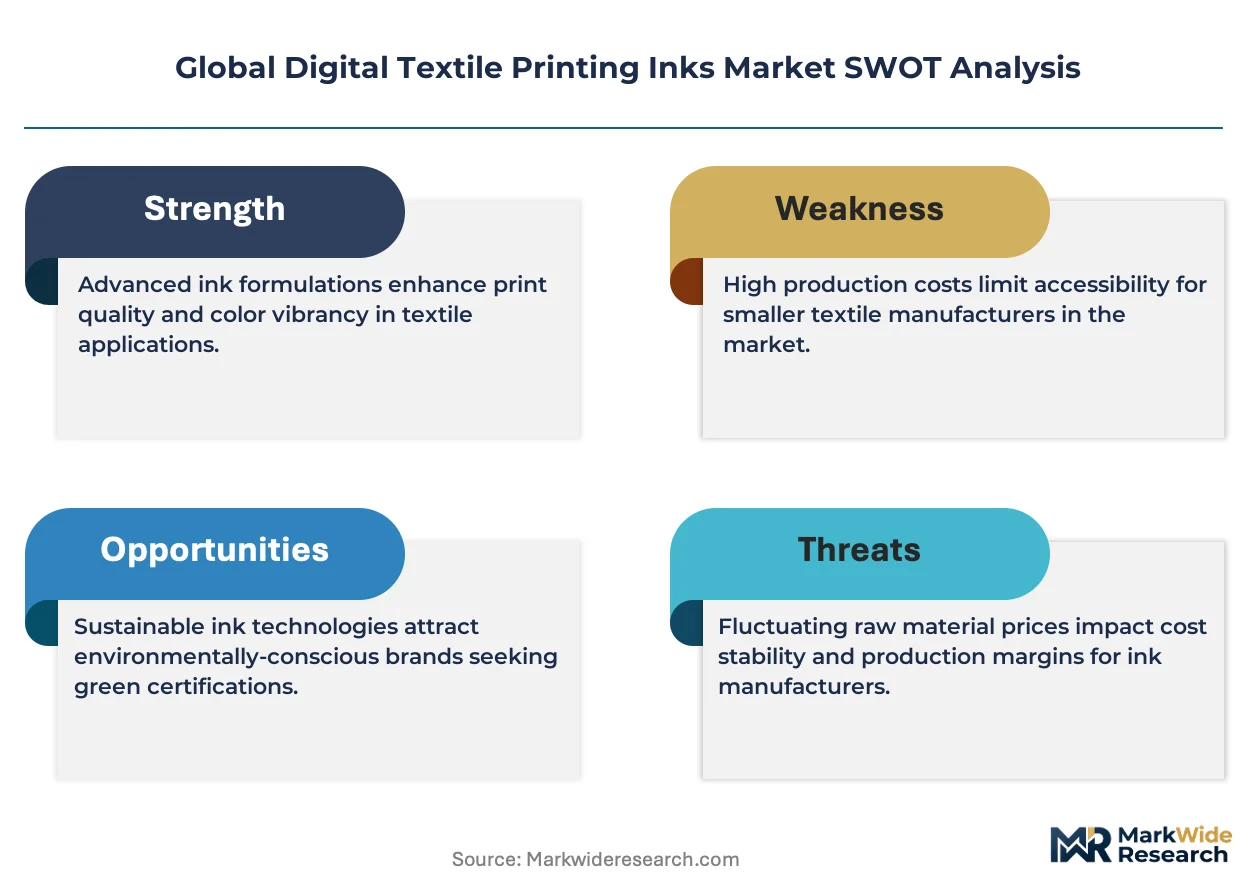
- REACH chemical safety mandates:European fabric printers face binding restrictions on aromatic amines and heavy metals, accelerating certified water-based pigment adoption across Portugal and Italy dye houses.
- Polyester sportswear on-demand production:Sublimation transfer printing enables same-day pattern-to-garment workflows, with athletic apparel brands in Vietnam and Bangladesh deploying single-pass inkjet systems for team uniform customization.
- UV-curable ink chemistry advances:Technical textile manufacturers serving automotive seating in Germany and Japan specify cationic UV formulations for abrasion resistance exceeding 50,000 Martindale cycles.
Market Restraints
- Petrochemical feedstock volatility:Acrylate monomers and polyurethane dispersions constitute 35-45% of UV and water-based ink costs, with pricing tied to propylene oxide supply concentrated in US Gulf Coast and Northeast Asian crackers.
- Printhead supply concentration:Piezoelectric MEMS fabrication for industrial textile printheads depends on Kyocera, Ricoh, and Xaar manufacturing concentrated in Japan and UK cleanroom facilities.
- Color gamut limitations of pigment systems:Reactive dyes retain superior cellulose fiber penetration and wash fastness, constraining pigment ink share in premium cotton apparel despite lower effluent treatment burdens.
Strategic Opportunities
- India technical textile expansion:The country's PLI scheme for man-made fiber and technical textiles creates formulation demand for flame-retardant and antimicrobial inkjet coatings in automotive and medical applications.
- Digital textile rental/subscription channels:Interior design platforms in the Netherlands and UK offer fabric-by-the-meter with 48-hour custom printing, opening B2C ink volumes previously captured by wholesale converters.
- EU Green Deal circularity requirements:Upcoming textile waste regulations mandate fiber-to-fiber recyclability, favoring pigment inks that avoid covalent fiber bonds and enable easier depolymerization of printed polyester.
Industry Challenges
- Color management specialist scarcity:ICC profile creation for multi-fabric workflows requires expertise in spectrophotometry and RIP software calibration, with training pipelines lagging system deployment in Mexican and Indonesian print service providers.
- OEKO-TEX and ZDHC certification timelines:Third-party chemical verification for MRSL conformance adds 4-6 months to ink formulation commercialization, compressing R&D amortization windows for mid-scale producers.
Report Scope
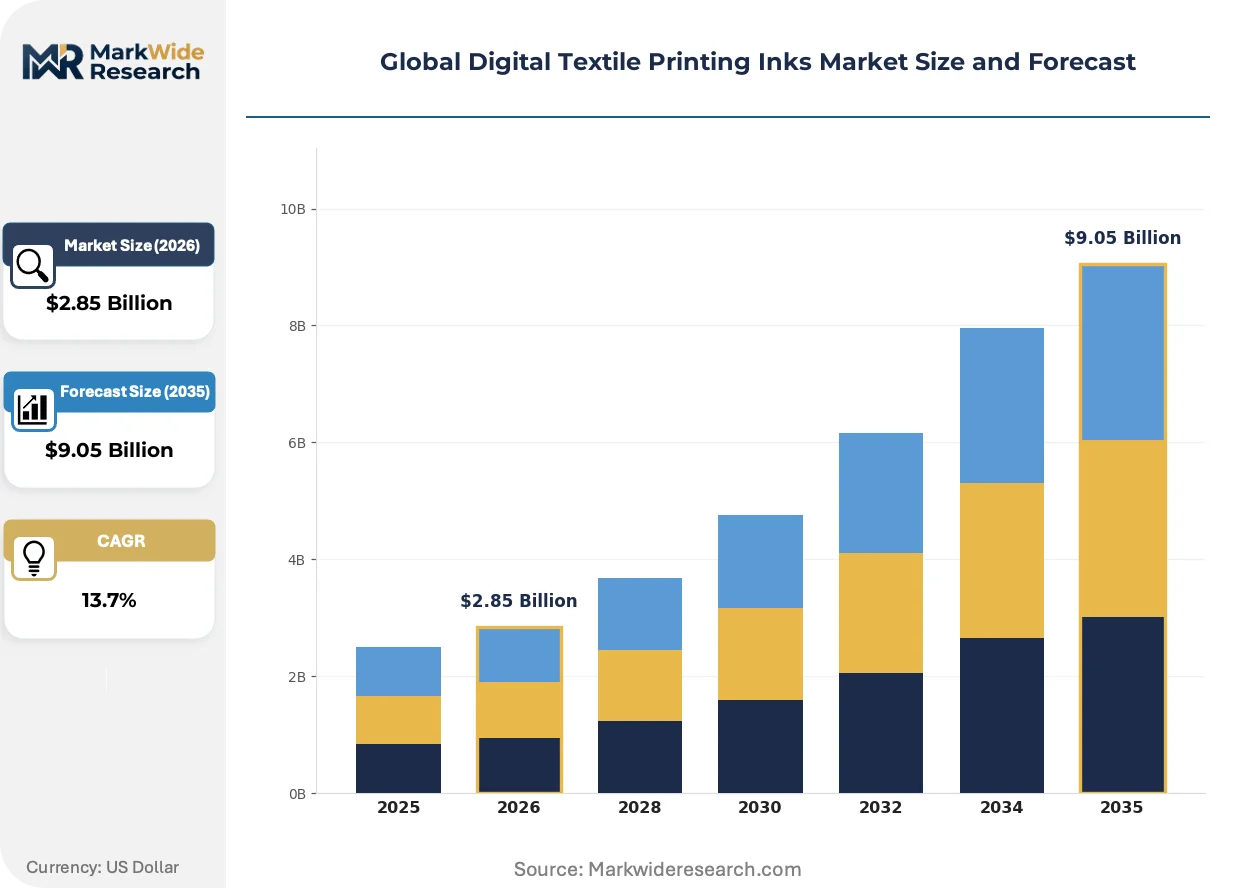
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Digital Textile Printing Inks Market |
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $9.05 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Reactive, Acid, Pigment, Disperse, Sublimation, UV Application: Apparel, Home Furnishing, Technical Textiles, Promotional Textile, Automotive Seating Raw Material: Water-Based, Solvent-Based, UV-Curable, Eco-Solvent, Latex End User: Fabric Manufacturers, Garment Manufacturers, Printing Service Providers, Interior Decorators, Event Organizers |
| Companies Covered | Huntsman Corporation, InkTec Co., Ltd., BASF SE, Heubach GmbH, AM Printex Solutions, Clariant AG, The Dow Chemical Company, Gans Ink & Supply Co., DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Digital Textile Printing Inks Market Shifts & Advancements
Single-pass inkjet architectures and AI-driven color matching are collapsing the cost gap between digital and analog textile decoration, while regulatory chemistry restrictions force simultaneous innovation in deposition hardware and formulation science.
Water-based pigment dispersions with nano-scale particle distribution are consolidating position in cotton and viscose printing as European and North American brands enforce ZDHC MRSL compliance across tier-one suppliers. Fashion retailers in Spain and California specify these systems for capsule collections requiring 72-hour turnaround from design approval to retail floor. The technology is consolidating demand previously fragmented across reactive dye houses, screen printers, and rotary equipment service networks.
EPA enforcement of TSCA Section 6 restrictions on per- and polyfluoroalkyl substances is forcing reformulation of stain-resistant textile finishes and ink additives across US-based converters. The industrial consequence extends beyond chemistry substitution to require requalification of entire print workflows for outdoor and performance apparel categories. California and New York textile printers face the most acute compliance timelines, with some operators accelerating UV-curable system adoption to bypass aqueous chemistry scrutiny entirely.
Brand procurement teams now specify lot-level chemical traceability as a standard contract term, displacing certificate-based compliance for OEKO-TEX and bluesign certifications. This behavioral shift concentrates ink sourcing decisions among formulation houses with in-house analytical laboratories and ERP-integrated batch records. The transformation is most visible in German and Swiss sportswear supply chains, where material passports and digital product identifiers are becoming mandatory for supplier qualification.
Global Digital Textile Printing Inks Market Segmentation
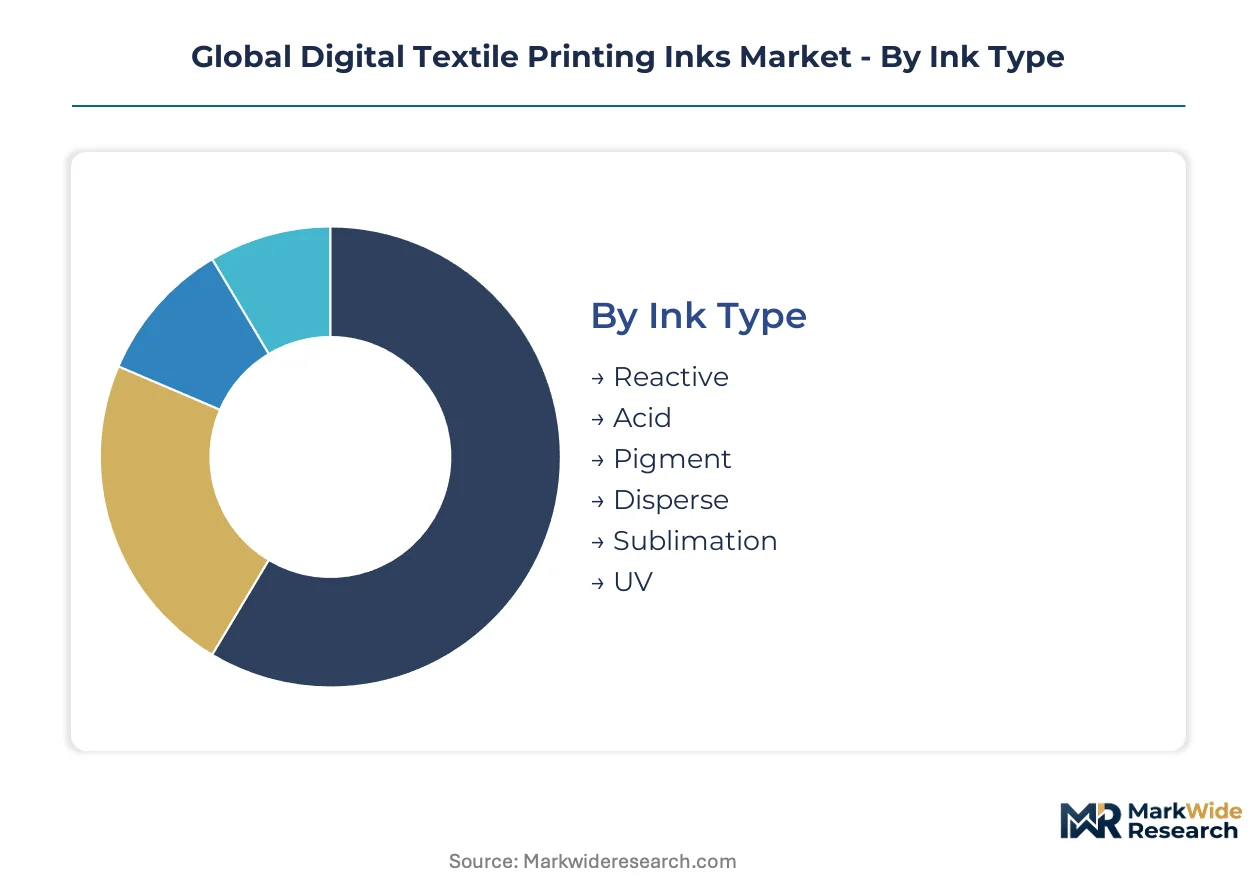
Digital textile printing inks fragment across four structural axes: chemical formulation, substrate application, carrier chemistry, and buyer type. Each axis carries distinct margin profiles, regulatory exposure, and supply chain concentration that reshape procurement decisions.
Ink Type:
Formulation chemistry determines fiber compatibility, color fastness, and effluent treatment burden.
- Sublimation:Disperse dyes suspended in low-viscosity aqueous carriers penetrate polyester fibers under heat and pressure. Vietnam and Bangladesh sportswear manufacturers deploy these systems for same-day team uniform customization, though the chemistry offers no adhesion to natural fibers.
- Pigment:Nano-scale colorant particles bind to fiber surfaces via acrylic or polyurethane binders without covalent reaction. Water-based variants are consolidating share in cotton apparel across Portugal and Italy as REACH aromatic amine restrictions tighten.
- Reactive:Dye molecules form permanent covalent bonds with cellulose hydroxyl groups, delivering superior wash fastness for premium cotton apparel in Indian and Turkish dye houses.
- Acid:Protein fiber specificity for silk and wool applications in luxury scarf and tie manufacturing clusters around Como, Italy.
- Disperse:Direct-to-polyester printing without transfer paper, serving flag and banner producers in Germany with lower equipment cost than sublimation workflows.
- UV:Cationic and free-radical photopolymer systems cure instantly under LED exposure, specified by German and Japanese automotive seating suppliers for abrasion resistance exceeding 50,000 Martindale cycles.
Pigment leads on scale; UV leads on momentum.
Application:
End-use verticals separate by run length tolerance, color precision requirements, and durability standards.
- Apparel:Sportswear brands in Vietnam and Bangladesh compress design-to-retail cycles through on-demand sublimation workflows. Fast fashion retailers in Spain specify pigment systems for 72-hour capsule collection turnaround.
- Home Furnishing:Interior decorators in the Netherlands and UK shift from bulk orders to fabric-by-the-meter with 48-hour custom printing, opening B2C ink volumes previously captured by wholesale converters.
- Technical Textiles:Flame-retardant and antimicrobial coatings for automotive and medical applications in India, supported by PLI scheme incentives for man-made fiber expansion.
- Promotional Textile:Event merchandise and corporate gifting with short-run, multi-design requirements across North American and European trade show circuits.
- Automotive Seating:UV-curable formulations dominate German and Japanese supply chains where abrasion and light-fastness specifications exceed residential textile standards.
Apparel dominates volume; home furnishing climbs the fastest.
Raw Material:
Carrier chemistry selection trades volatile organic compound emissions against substrate versatility and cure energy requirements.
- Water-Based:Pigment and dye dispersions in aqueous media dominate cotton and viscose printing. ZDHC MRSL compliance across tier-one suppliers accelerates substitution of solvent alternatives.
- UV-Curable:Acrylate and epoxy-functional oligomers cure instantly under UV-LED exposure, eliminating thermal drying and enabling direct printing onto non-absorbent technical substrates.
- Solvent-Based:Hydrocarbon and ketone carriers retain niche position in vinyl banner and outdoor flag applications where water-based adhesion remains inadequate.
- Eco-Solvent:Glycol ether formulations with reduced VOC profiles serve mid-market signage converters transitioning from full solvent systems.
- Latex:Aqueous resin dispersions with thermal curing requirements, positioned between water-based and UV systems for durability without photoinitiator chemistry.
Water-based commands installed base; UV-curable shows steepest expansion trajectory.
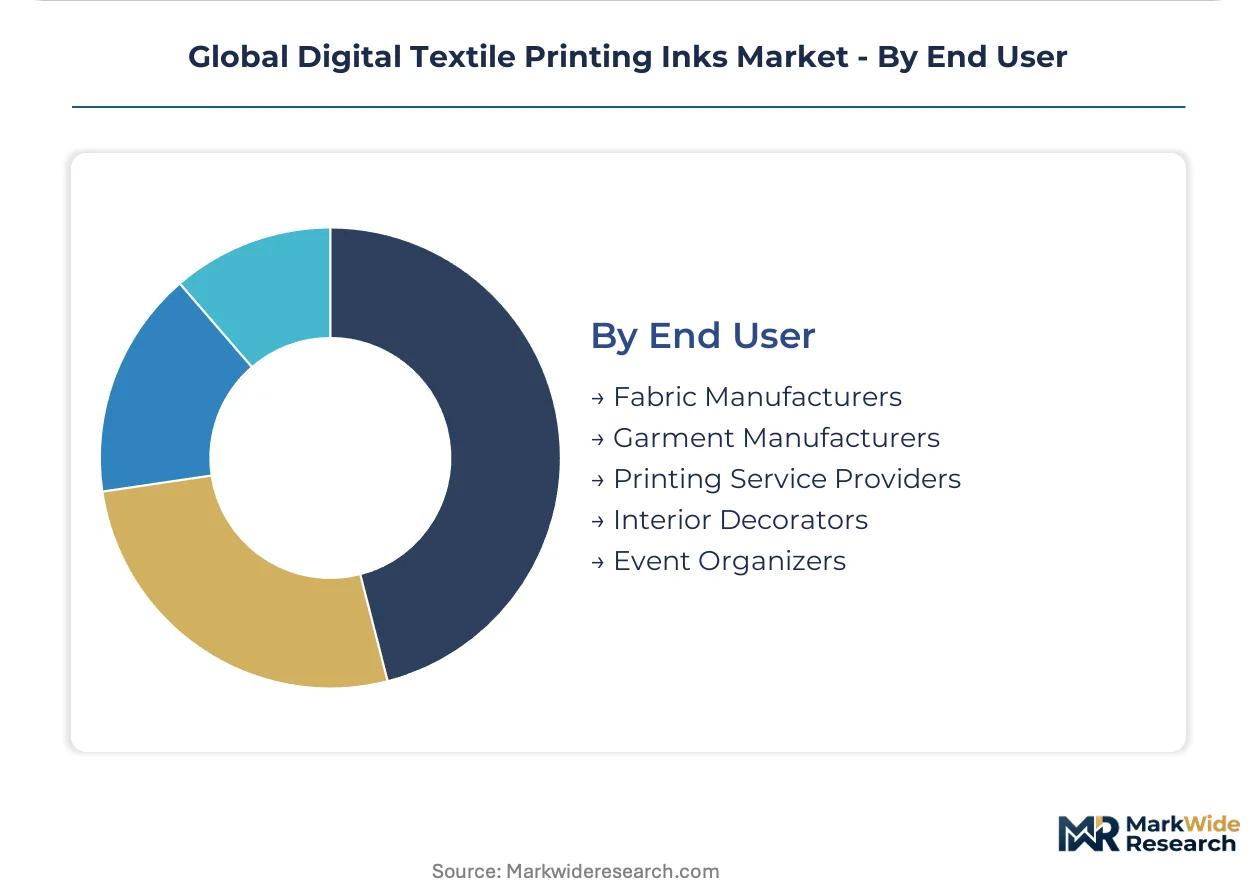
End User:
Buyer sophistication and scale separate formulation procurement patterns and technical service requirements.
- Printing Service Providers:Independent converters in Mexico and Indonesia face color management specialist scarcity, with ICC profile creation lagging system deployment.
- Fabric Manufacturers:Vertical mills in China and India integrate inkjet deposition into weaving and knitting operations, capturing margin previously lost to external finishers.
- Garment Manufacturers:Cut-and-sew operations in Vietnam and Bangladesh add in-house printing for customization and reduced inventory risk.
- Interior Decorators:Design platforms in the Netherlands and UK source direct-to-consumer printed fabrics, bypassing traditional wholesale converter relationships.
- Event Organizers:Corporate and trade show clients with episodic, high-visibility textile needs driving short-run promotional textile demand.
Fabric manufacturers anchor volume; printing service providers gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting digital textile printing ink production toward jurisdictions with lower compliance costs, while REACH and EPA enforcement in mature markets forces premium pricing for certified formulations. Manufacturers now site capacity in Vietnam and Bangladesh to serve sportswear brands, while European and North American facilities pivot to technical textiles with higher margin tolerance for chemical safety overhead.
United States
EPA enforcement of TSCA Section 6 restrictions on per- and polyfluoroalkyl substances is forcing reformulation of stain-resistant textile finishes across California and New York converters. The agency's evolving standards for volatile organic compound emissions accelerate water-based pigment adoption in Los Angeles and North Carolina printing clusters. Some operators bypass aqueous chemistry scrutiny entirely through UV-curable system deployment.
Germany
Automotive seating manufacturers in Bavaria and Baden-Württemberg specify cationic UV formulations for abrasion resistance exceeding 50,000 Martindale cycles. ECHA's REACH mandates on aromatic amines and heavy metals bind fabric printers in North Rhine-Westphalia to certified water-based pigment systems. The country's national chemical regulator maintains Europe's strictest formulation disclosure requirements.
China
MEE enforcement of dual carbon goals restricts solvent-based ink production in Yangtze River Delta manufacturing zones. The country's environmental ministry pressures Guangdong and Zhejiang apparel clusters toward shorter-run, customized production models with lower effluent burdens. Domestic pigment dispersion capacity expands to serve cotton printing demand from Bangladesh and Vietnam garment exporters.
India
The PLI scheme for man-made fiber and technical textiles creates formulation demand for flame-retardant and antimicrobial inkjet coatings in Maharashtra and Gujarat automotive and medical applications. BIS certification timelines for imported raw materials extend ink commercialization cycles for mid-scale producers in Tamil Nadu. Tirupur's cotton knitwear cluster experiments with reactive dye digital workflows for premium export contracts.
Vietnam
Sportswear brands accelerate same-day team uniform customization through sublimation transfer printing in Ho Chi Minh City and Dong Nai Province facilities. The country's apparel manufacturing clusters attract single-pass inkjet system deployment from Bangladesh and China equipment suppliers. Local ink formulation remains import-dependent, creating margin capture opportunities for regional distributors.
Global Digital Textile Printing Inks Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation houses capturing premium pricing in technical textiles while toll producers serve high-volume apparel workflows. The vendor base concentrates among European and Asian chemical conglomerates with integrated dye and pigment operations, plus regional specialists in UV-curable and water-based dispersions. Three archetypes dominate: multinational chemical conglomerates with textile chemistry heritage, Asian equipment-integrated ink suppliers, and niche UV formulation specialists. Competitive moves center on certification pre-positioning for OEKO-TEX and ZDHC standards, plus backward integration into pigment and resin raw materials.
Among multinational chemical conglomerates, Huntsman Corporation, BASF SE, and DuPont de Nemours exemplify the integrated-dye-chemistry archetype, leveraging reactive and pigment portfolios across Asian manufacturing hubs. These entities anchor European and North American supply chains with formulation houses that maintain in-house analytical laboratories and ERP-integrated batch records for lot-level chemical traceability. Their positioning reflects the premium-tier vector where brand procurement teams now mandate material passports and digital product identifiers as standard contract terms.
| Leading Market Players |
|---|
| Huntsman Corporation |
| InkTec Co., Ltd. |
| BASF SE |
| Heubach GmbH |
| AM Printex Solutions |
| Clariant AG |
| The Dow Chemical Company |
| Gans Ink & Supply Co. |
| DuPont de Nemours |
| Others |
Supply & Pricing Matrix
Acrylate monomer and polyurethane dispersion costs, comprising 35-45% of UV and water-based ink formulations, flow from US Gulf Coast and Northeast Asian crackers through formulation houses to apparel printers in Vietnam and Bangladesh, with certified water-based pigments commanding premium positioning in European REACH-regulated markets.
Pricing Analysis
Distributor margins compress as formulation houses in Germany and Switzerland bypass wholesale channels to serve sportswear brands directly with lot-level traceability and material passports. Three-tier pricing structure separates OEKO-TEX certified premium formulations from standard ZDHC-compliant grades and uncertified economy alternatives, with certification tier and volume scale as primary differentiation drivers. Pricing pressure stems from petrochemical feedstock volatility tied to propylene oxide supply. Garment manufacturers in Vietnam show highest price sensitivity, while automotive seating suppliers in Germany absorb premium UV-curable costs for abrasion performance.
Supply Chain Analysis
Piezoelectric MEMS fabrication for industrial textile printheads rests on Kyocera, Ricoh, and Xaar manufacturing concentrated in Japan and UK cleanroom facilities, creating single-source vulnerability for deposition hardware. Raw material sourcing draws from Chinese pigment dispersion capacity, Indian reactive dye chemistry, and German oligomer resin production. Distribution runs through regional distributors in Southeast Asia serving Bangladesh and Vietnam garment clusters, with formulation houses in Portugal and Italy anchoring European supply. Tariff exposure on acrylate imports threatens margin structures for mid-scale producers in Mexico and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in certified water-based pigment systems as ZDHC MRSL compliance costs filter uncertified competitors from tier-one supplier lists, while single-pass inkjet hardware deployment compresses per-meter ink economics for high-volume converters.
For Market Incumbents: To counter Asian equipment-integrated ink suppliers capturing share in Vietnam and Bangladesh, BASF SE and Huntsman Corporation should deepen backward integration into nano-scale pigment dispersion production in India and Germany, while pre-positioning formulations for EU Green Deal circularity requirements that favor pigment inks enabling fiber-to-fiber recyclability. For New Entrants and Emerging Players: Capture white-space in technical textile coatings for India's PLI-supported automotive and medical applications, where flame-retardant and antimicrobial inkjet formulations face limited domestic competition. Target Maharashtra and Gujarat manufacturing clusters with localized formulation partnerships bypassing extended BIS certification timelines for imported raw materials. For Investors and Strategic Acquirers: Roll-up economics work for niche UV-curable formulation specialists because automotive seating and technical textile specifications create sticky supplier relationships with multi-year qualification cycles. Watch cationic UV chemistry patent filings as inflection indicator for next-generation abrasion resistance standards exceeding 50,000 Martindale cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Dispersion | Huntsman Corporation's captive supply of reactive dye chemistry secures margin control across Asian manufacturing hubs. |
| ZDHC MRSL Certification Pre-Positioning | Early compliance investment locks out uncertified competitors from Spanish fast fashion retailer procurement lists. |
| Single-Pass Inkjet System Deployment | Vietnam sportswear manufacturers compress design-to-retail cycles through same-day team uniform customization workflows. |
| Technical Textile Formulation Partnership | Localized production in Maharashtra serves India's PLI-incentivized automotive seating and medical textile expansion. |
| Material Passport Integration | German and Swiss sportswear supply chains mandate digital product identifiers as standard supplier qualification terms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ink formulation R&D directors, textile printer procurement managers, and ZDHC program implementation leads with secondary validation through customs trade data, SEC 10-K chemical segment disclosures, and OEKO-TEX certification databases. Bottom-up triangulation across ink type, application, and end-user segments converged with top-down macroeconomic anchoring.
Segment-weighting approaches applied differential growth assumptions across sublimation, pigment, reactive, acid, disperse, and UV ink chemistries, with substrate compatibility and regulatory compliance tier as cross-cutting dimensions modeled across the projection horizon. CAGR derivation incorporated installed base of single-pass inkjet systems, REACH and EPA enforcement trajectories, and sportswear brand on-demand production adoption curves as industry-specific forecast inputs.
Underlying measurement precision varies by segment; UV-curable and water-based pigment categories carry tighter precision than solvent-based alternatives given disclosure concentration among multinational chemical conglomerates. Forecasts reflect documented assumptions regarding MEE dual carbon enforcement timelines and polyester sportswear demand elasticity. Material deviation in per- and polyfluoroalkyl substance regulatory scope or piezoelectric printhead supply disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Global Printing Blanket Market
Printing Inks
Food Grade Inks Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Global Printing Toners Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Roll-To-Roll Type UV Imprinting Machines Market
Printing Inks
Waterborne Ink Market
Printing Inks
Specialty Printing Consumables Market
Printing Inks
Flexible Letterpress Printing Ink Market
Printing Inks
North America Ink Market
Printing Inks
Europe Specialty Printing Consumables Market
Printing Inks
Printing Inks Market
Printing Inks
Water-Borne Inks and Paints Market
Printing Inks
Inkjet Colorants Market