
 Global Low Migration Inks Market | 2026-2036
Global Low Migration Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Migration Inks Market Foresight
Buyer concentration among European food packaging converters is rebalancing as multinational brand owners consolidate approved supplier lists while regional craft food producers fragment procurement across smaller print shops. Sun Chemical leverages its integrated pigment and resin capabilities to serve tier-one converters with certified low-migration systems. Siegwerk Druckfarben anchors its position through specialized regulatory consulting bundled with ink supply. Huber Group differentiates by controlling narrow-web flexo channels for pharmaceutical blister packs.
Low migration inks are formulated printing systems designed to minimize transfer of chemical components from printed packaging into packaged goods, typically achieving specific migration limits below 10 parts per billion for sensitive applications and relying on purified raw materials, controlled curing parameters, and exclusion of photoinitiator byproducts. These inks serve primarily food, pharmaceutical, and cosmetic packaging where consumer safety regulations prohibit contamination of ingestible or dermal-contact products. UV curable formulations command the strongest margin pool due to energy-efficient processing and instant polymerization that reduces volatile residue risk, while water-based systems gain share in flexible food packaging where heat-sensitive substrates limit radiation curing. Digital printing technology represents the fastest-expanding segment as brand owners demand shorter runs with variable data and converters require ink sets that comply with migration standards without plate changeover delays.
FDA food contact notification requirements, EU Framework Regulation EC 1935/2004, and Swiss Ordinance SR 817.021.23 collectively define the compliance perimeter for ink suppliers seeking access to North American and European packaged goods markets. EFSA's ongoing evaluations of photoinitiators and mineral oil hydrocarbons continue to tighten acceptable substance lists, compelling reformulation investments that favor suppliers with in-house analytical laboratories. Stakeholders must monitor regulatory divergence between EU member state implementations and FDA guidance updates to anticipate where compliance costs will concentrate and which formulation platforms will retain cross-border viability.
Market Dynamics
Brand owners in packaged goods are consolidating approved supplier lists while simultaneously demanding shorter production runs with full regulatory traceability, forcing ink formulators to absorb compliance costs without pricing power recovery.
Growth Catalysts
- EU Framework Regulation EC 1935/2004:Mandatory migration limits for food contact materials are compelling converters across Germany, France, and Italy to replace conventional ink systems with certified low-migration alternatives.
- Digital printing adoption:Variable data requirements for personalized packaging and anti-counterfeiting serialization are accelerating demand for UV-curable low-migration ink sets that cure instantly without thermal substrate damage.
- Pharmaceutical blister packaging:Stringent dermal-contact safety standards in Switzerland and the Netherlands are expanding addressable market for narrow-web flexo systems with photoinitiator-free formulations.
Market Restraints
- Purified raw material scarcity:Pharmaceutical-grade photoinitiators and mineral-oil-free hydrocarbon resins command 40-60% premiums over standard grades, compressing formulation margins.
- Specialized curing equipment:UV-LED systems with precise wavelength control for low-migration curing require capital outlays that small and mid-sized converters in Eastern Europe cannot justify.
- Regulatory fragmentation:Divergent Swiss Ordinance SR 817.021.23 implementation timelines versus FDA food contact notification requirements create dual-track compliance burdens for multinational suppliers.
Strategic Opportunities
- India packaged food expansion:FSSAI enforcement of food contact material standards is creating first-mover advantage for suppliers establishing local analytical laboratory capabilities.
- Water-based system hybridization:Convergence of water-based carrier fluids with UV-curable oligomers is opening flexible film applications previously blocked by heat-sensitive substrate limitations.
- Extended Producer Responsibility frameworks:EU Green Deal packaging waste directives are incentivizing mono-material packaging designs compatible with low-migration ink adhesion chemistry.
Industry Challenges
- Analytical chemist shortage:Migration testing protocols requiring gas chromatography-mass spectrometry expertise face talent scarcity across contract laboratories serving mid-tier converters.
- Photoinitiator substitution timelines:EFSA ongoing evaluations of benzophenone derivatives are forcing emergency reformulation cycles without guaranteed regulatory acceptance of replacement chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Migration Inks Market |
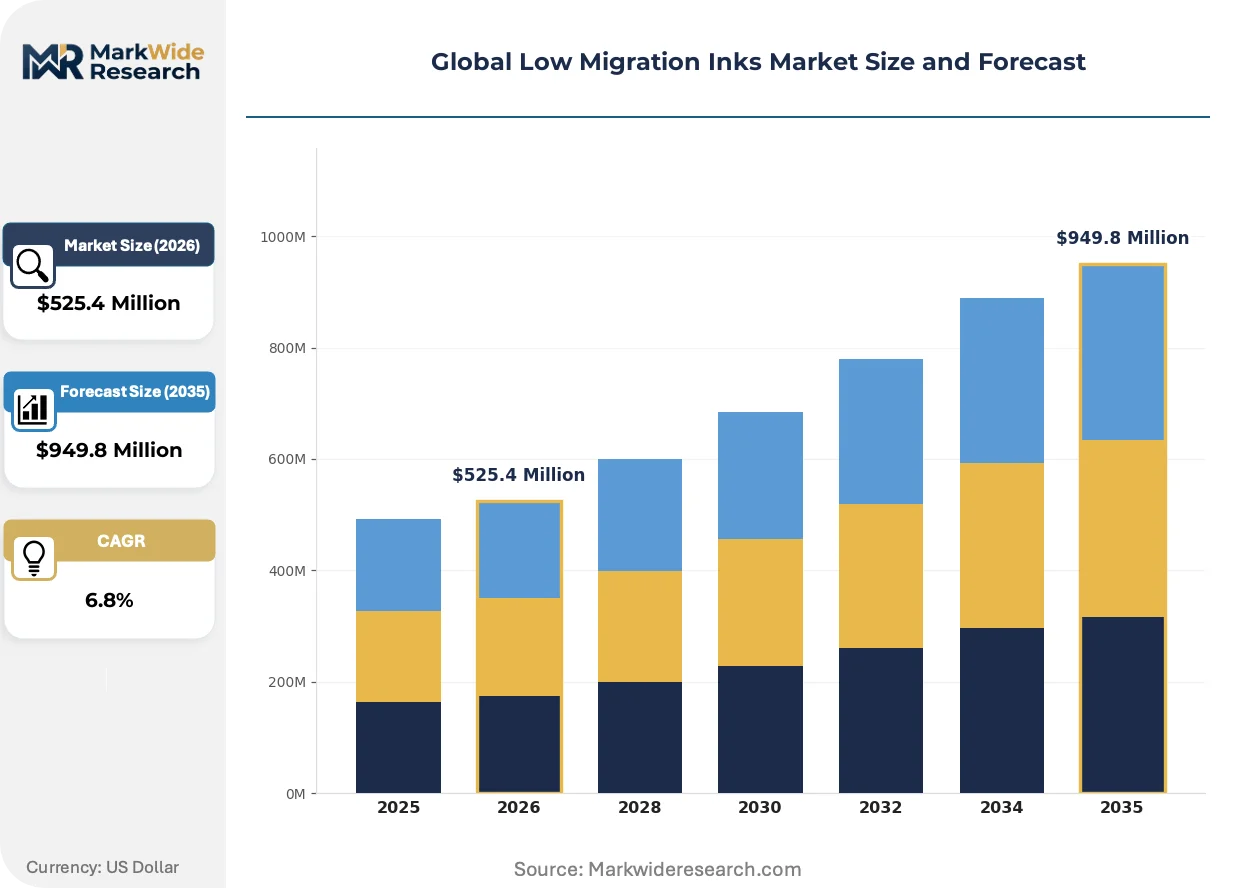
| Market Size in 2026 | $525.4 Million |
| Market Size in 2035 | $949.8 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: Solvent-Based, UV Curable, Water-Based, Hot Melt, Radiation Curable Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Packaging, Textile Printing, Labeling End User: Converters, Brand Owners, Package Printers, Labelling Companies, Printing Ink Manufacturers Printing Technology: Flexographic, Gravure, Digital, Offset, Screen |
| Companies Covered | Sun Chemical, Agfa-Gevaert, Flint Group, Huber Group, Siegwerk Druckfarben, INX International, Epple Druckfarben, Altana, Toyo Inks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Migration Inks Market Shifts & Advancements
Formulation chemistry and curing hardware are converging to eliminate migration risk at the molecular level rather than managing it through downstream testing protocols. This shift is redrawing competitive boundaries between integrated chemical suppliers and specialized ink compounders.
UV-LED curing systems with narrow-band wavelength specificity are electrifying adoption in heat-sensitive flexible packaging applications. Converters serving organic and premium food brands in Germany and Switzerland are replacing mercury arc lamps to eliminate ozone generation and reduce substrate thermal stress. The technology is compressing the viable window for water-based systems in high-speed narrow-web applications where instant polymerization delivers throughput advantages.
EFSA systematic re-evaluation of photoinitiator toxicological profiles is tightening substance authorization lists faster than reformulation cycles can accommodate. Ink suppliers with captive analytical capabilities are accelerating compliance submissions while compounders dependent on external laboratories face 12-18 month certification delays. Pharmaceutical blister pack manufacturers in Germany and the Netherlands are most exposed, with several established photoinitiator categories now under provisional restriction pending toxicological data submission.
Consolidation of brand owner procurement functions is compressing supplier qualification timelines and unbundling technical service from ink supply contracts. Tier-one converters are absorbing migration testing responsibilities previously borne by ink formulators, while regional craft food producers fragment orders across smaller print shops lacking in-house analytical capacity. This bifurcation is most visible in France and Italy, where mid-sized converters face margin pressure from both multinational consolidation above and artisanal fragmentation below.
Global Low Migration Inks Market Segmentation
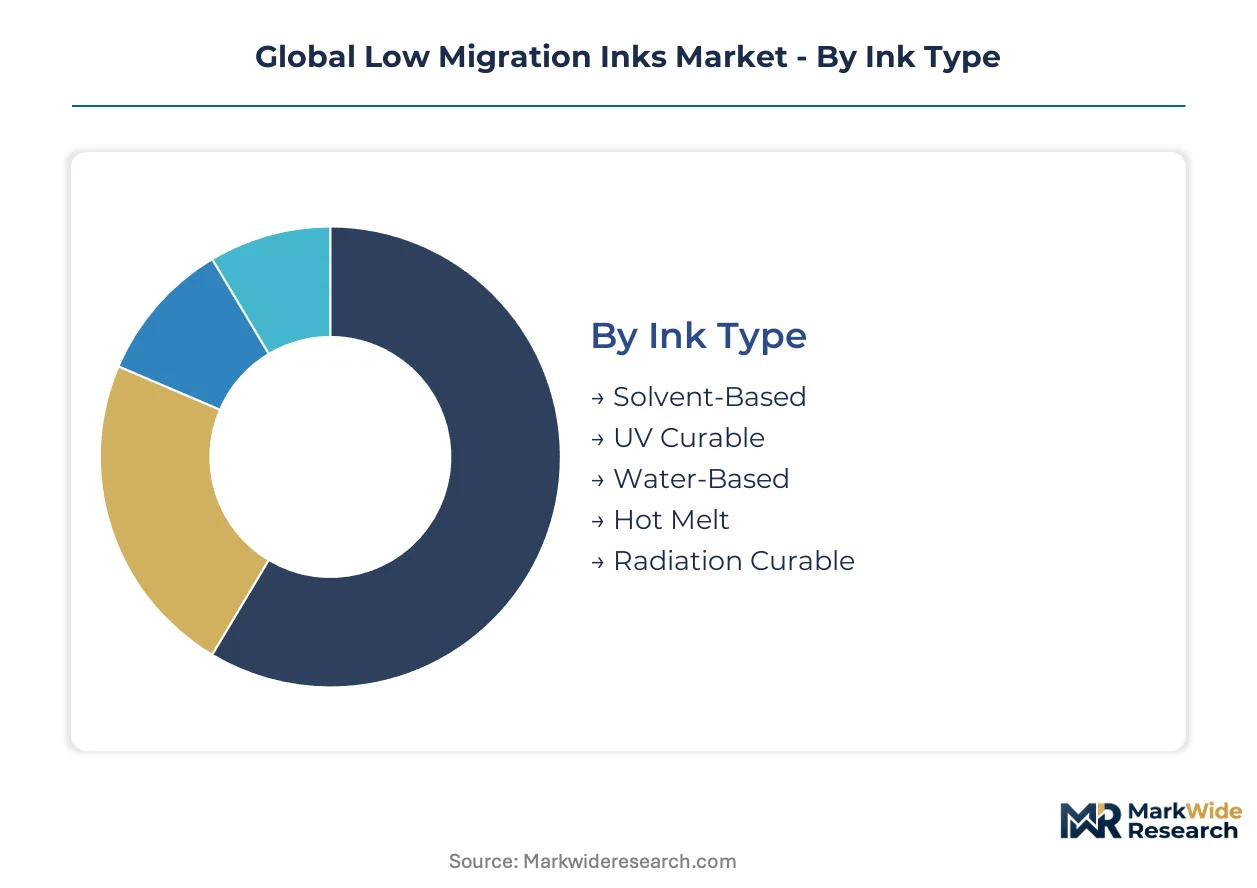
Low migration inks require precise matching between formulation chemistry, substrate compatibility, and regulatory compliance requirements. Segmentation reveals where formulation customization commands premium positioning versus where standardized systems compete on throughput efficiency.
Ink Type:
Customization intensity spans from commodity carrier systems to highly specified photoinitiator-free formulations requiring analytical certification.
- UV Curable:Photoinitiator-free and low-aromatic oligomer systems dominate premium food and pharmaceutical applications. German and Swiss converters serving organic brands specify narrow-band UV-LED curing to eliminate thermal substrate stress and ozone generation. EFSA's systematic re-evaluation of benzophenone derivatives is accelerating demand for Type II photoinitiator alternatives.
- Water-Based:Acrylic and polyurethane dispersions with mineral-oil-free hydrocarbon carriers address flexible film packaging where heat sensitivity precludes radiation curing. French and Italian converters handling short-run craft food packaging favor these systems for rapid changeover without plate delays.
- Solvent-Based:Low-aromatic hydrocarbon formulations retain niche positions in high-speed gravure applications for commodity food packaging where migration limits remain less stringent.
- Hot Melt:Thermoplastic formulations serve specialized labeling applications requiring immediate adhesion to non-polar substrates without solvent retention risk.
- Radiation Curable:Electron beam systems eliminate photoinitiator requirements entirely, commanding positions in pharmaceutical blister packs where dermal-contact standards are most stringent.
Most installed capacity flows through UV Curable systems. Expansion is steepest in Water-Based formulations gaining flexible packaging share.
Application:
Regulatory stringency tiers separate ingestible-contact applications from dermal-contact and non-contact decorative uses.
- Food Packaging:Direct and indirect food contact applications face the tightest migration limits under EU Framework Regulation EC 1935/2004. German converters supplying Central European retail chains dominate demand for certified systems achieving specific migration limits below 10 parts per billion for sensitive fatty food applications.
- Pharmaceutical Packaging:Blister packs, sachets, and secondary packaging for dermal-contact and ingestible products require photoinitiator-free formulations. Swissmedic and Netherlands-based manufacturers specify narrow-web flexo systems with complete substance traceability.
- Cosmetic Packaging:Dermal-contact standards under EU Cosmetics Regulation 1223/2009 drive demand for systems excluding identified skin sensitizers. French luxury cosmetic brands are consolidating approved supplier lists with mandatory migration testing documentation.
- Labeling:Pressure-sensitive and wrap-around labels for food and beverage containers require low-migration adhesives combined with compatible ink systems. Variable data printing for anti-counterfeiting serialization is expanding digital ink demand in this segment.
- Textile Printing:Non-contact decorative applications face less stringent migration requirements, though transfer-printing inks for infant clothing are shifting toward certified low-migration systems.
Food Packaging absorbs the majority of current formulation investment. Pharmaceutical Packaging is climbing the fastest as certification timelines compress supplier qualification windows.
End User:
Procurement sophistication varies dramatically between multinational brand owners with captive analytical capabilities and fragmented regional print shops.
- Converters:Mid-to-large format flexible packaging and label converters in Germany, France, and Italy represent the core demand base. Tier-one converters are absorbing migration testing responsibilities previously borne by ink suppliers, while mid-tier operations face margin compression from both multinational consolidation above and artisanal fragmentation below.
- Brand Owners:Multinational packaged goods companies are consolidating approved supplier lists and demanding full regulatory traceability. Unilever, Nestlé, and Danone procurement functions now specify ink certification as a condition of converter qualification.
- Package Printers:Specialized operations serving pharmaceutical and cosmetic sectors require photoinitiator-free and mineral-oil-free systems with batch-level analytical documentation.
- Labelling Companies:Narrow-web specialists handling variable data and serialization projects specify UV-curable ink sets compatible with digital printing platforms.
- Printing Ink Manufacturers:Captive demand from integrated suppliers producing certified systems for internal converter networks or licensed distribution arrangements.
Converters channel the largest volume of certified ink procurement. Brand Owners are gaining share fastest as direct specification authority consolidates.
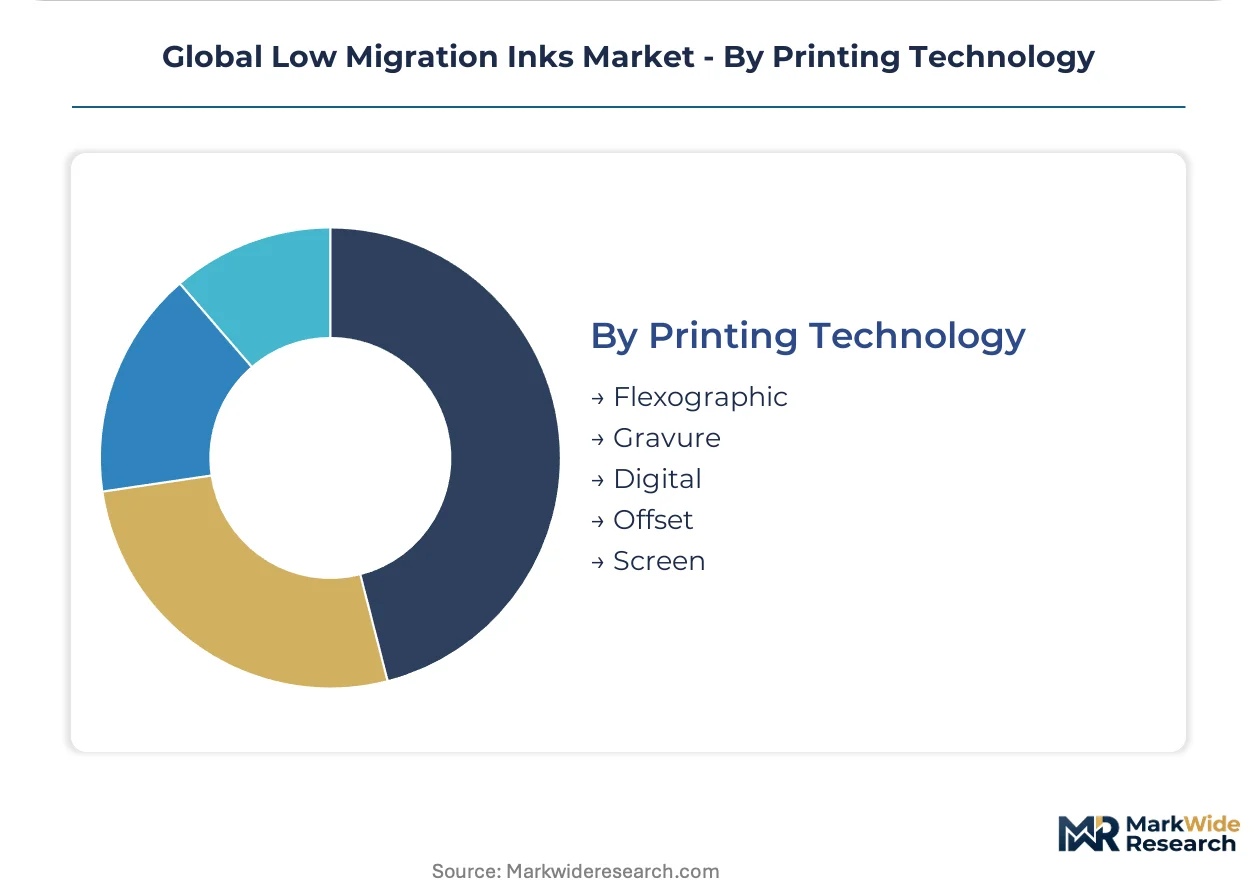
Printing Technology:
Speed-to-cure and substrate thermal tolerance determine technology-platform selection across application segments.
- Digital:Inkjet and toner-based systems with UV-curable and water-based low-migration formulations are expanding most quickly. Brand owners demand shorter runs with variable data for personalization and anti-counterfeiting serialization. Converters require ink sets that comply with migration standards without plate changeover delays.
- Flexographic:Narrow-web and wide-web flexo systems dominate food packaging and labeling applications. Central impression drum presses in German converter facilities are upgrading to UV-LED curing for low-migration compliance.
- Gravure:High-speed publication and commodity food packaging applications where solvent-based systems retain cost advantages despite regulatory pressure.
- Offset:Sheet-fed and web offset for folding carton applications requiring low-odor, low-migration formulations for premium food and cosmetic packaging.
- Screen:Specialized decorative and functional printing for glass and rigid plastic containers where ink film thickness requirements exceed other technologies' capabilities.
Flexographic systems deploy the broadest installed base of low-migration-capable equipment. Digital is expanding most quickly as run lengths shorten and variable data requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the largest share of low migration ink consumption in Europe, while India registers the fastest absolute growth as FSSAI enforcement tightens food contact standards. Regulatory divergence between EU member states and FDA notification requirements creates compliance complexity for multinational suppliers.
Germany
Converters in Baden-Württemberg and Bavaria supply Central European retail chains with certified UV-curable systems achieving sub-10 ppb migration limits. The country's implementation of EU Framework Regulation EC 1935/2004 through the Bundesinstitut für Risikobewertung (BfR) mandates batch-level analytical documentation. Stuttgart-based packaging clusters are upgrading central impression drum flexo presses to narrow-band UV-LED curing to eliminate thermal substrate stress.
United States
FDA food contact notification requirements drive reformulation investments among converters serving multinational brand owners with North American distribution. The agency's guidance updates on photoinitiator safety create uncertainty windows that favor suppliers with captive analytical laboratories. Chicago and Milwaukee converter corridors concentrate demand for water-based systems in flexible food packaging applications.
Switzerland
Swiss Ordinance SR 817.021.23 imposes migration limits stricter than baseline EU requirements, expanding demand for photoinitiator-free formulations in pharmaceutical blister packs. Swissmedic enforcement of dermal-contact standards compels narrow-web flexo operators to maintain complete substance traceability. Basel and Zurich packaging clusters specialize in high-value pharmaceutical serialization with electron beam-curable systems.
India
FSSAI enforcement of food contact material standards is accelerating first-mover advantage for suppliers establishing local analytical capabilities. The regulator's 2023 notification on printing inks for food packaging created compliance deadlines that domestic converters struggle to meet. Maharashtra and Gujarat flexible packaging corridors are retrofitting gravure lines with low-migration water-based alternatives.
France
Luxury cosmetic brand owners in Paris and Lyon are consolidating approved supplier lists with mandatory migration testing documentation under EU Cosmetics Regulation 1223/2009. ANSM oversight of pharmaceutical packaging drives demand for certified systems in Alsace converter clusters. The country's craft food producer fragmentation creates bifurcated procurement between tier-one converters and smaller print shops lacking analytical capacity.
Global Low Migration Inks Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation platforms, creating a tiered structure where integrated pigment manufacturers hold cost advantages and regulatory consulting bundling commands premium positioning. Three archetypes dominate: integrated chemical suppliers controlling raw material purification, specialized ink compounders with external laboratory dependencies, and digital-focused technology licensors. Consolidation through strategic partnerships and geographic licensing arrangements represents the primary competitive vector, while portfolio diversification into adjacent compliant coating systems offers secondary expansion paths.
Among integrated chemical suppliers, Sun Chemical leverages captive pigment and resin capabilities to serve tier-one converters, while Siegwerk Druckfarben anchors its position through specialized regulatory consulting bundled with ink supply. Huber Group occupies a distinct position controlling narrow-web flexo channels for pharmaceutical applications. These three represent the dominant competitive anchors, with remaining market share distributed across regional compounders and technology-focused licensors.
| Leading Market Players |
|---|
| Sun Chemical |
| Agfa-Gevaert |
| Flint Group |
| Huber Group |
| Siegwerk Druckfarben |
| INX International |
| Epple Druckfarben |
| Altana |
| Toyo Inks |
| Others |
Supply & Pricing Matrix
Multinational brand owner procurement consolidation across Germany, France, and Switzerland anchors pricing power with tier-one converters capable of batch-level analytical documentation, compressing margins for mid-tier compounders lacking captive laboratory capabilities.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for standard-grade water-based systems while premium photoinitiator-free formulations retain margin insulation through regulatory certification barriers. Three-tier pricing structure across certified premium, compliant standard, and economy grades reflects EFSA authorization status and migration testing completeness. Cost compression in flexible packaging segments intensifies as FSSAI deadlines force Indian converters toward rapid system upgrades. Regional craft food producers in Southern Europe exhibit highest price sensitivity, while Swiss pharmaceutical blister pack manufacturers accept substantial premiums for complete substance traceability.
Supply Chain Analysis
Freight cost volatility for purified photoinitiators and mineral-oil-free hydrocarbon resins amplifies working capital requirements across formulation networks. Raw material sourcing concentrates in Germany, China, and India, with pharmaceutical-grade photoinitiator production anchored in specialized chemical clusters near Basel and Frankfurt. Formulation draws from purified oligomer streams, controlled-purity pigment dispersions, and narrow-specification photoinitiator alternatives. Single-source vulnerability persists for EFSA-compliant Type II photoinitiators pending toxicological re-evaluation. Distribution runs through converter-direct technical service relationships rather than commodity distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where EFSA's systematic photoinitiator re-evaluation shifts procurement authority toward suppliers with captive analytical capabilities and documented compliance histories.
For Market Incumbents: Extend regulatory consulting bundling beyond ink supply to capture converter testing responsibilities, while accelerating backward integration into purified photoinitiator production to offset raw material scarcity premiums. Defensive consolidation of approved supplier lists by Nestlé and Unilever procurement functions threatens compounders dependent on external laboratory relationships. For New Entrants and Emerging Players: Begin with water-based system hybridization for India's flexible packaging retrofit cycle, where FSSAI enforcement has outpaced domestic analytical capacity. The most penetrable white space sits in regional Indian converter networks requiring technical service partnerships to meet compliance deadlines. A go-to-market angle anchored in local laboratory joint ventures bypasses established supplier qualification barriers. For Investors and Strategic Acquirers: Chemical conglomerates with pigment and resin assets are the most active acquirer in this space, seeking ink formulation capabilities to complete vertical portfolios. Long-term viability hinges on regulatory authorization durability rather than formulation performance alone. Acquisition targets should display captive analytical infrastructure and established EFSA submission track records. The signal to watch is EFSA's publication timeline for benzophenone derivative restrictions, which would force emergency reformulation cycles favoring prepared suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Consulting Bundling | Captures migration testing responsibilities from tier-one converters in Germany and Switzerland. |
| Backward Integration into Photoinitiators | Secures supply of EFSA-compliant Type II alternatives amid authorization uncertainty. |
| UV-LED Curing Equipment Partnerships | Accelerates converter adoption in heat-sensitive flexible packaging applications. |
| Local Analytical Laboratory Establishment | Creates first-mover positioning in India's FSSAI compliance enforcement window. |
| Photoinitiator-Free Formulation Development | Eliminates regulatory exposure from EFSA's ongoing benzophenone derivative evaluations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ink formulation chemists, converter procurement leads, brand owner packaging directors, and regulatory affairs specialists at EFSA and FDA with secondary validation through customs trade data, BfR guidance documents, SEC filings from diversified chemical suppliers, and FSSAI notification records. Bottom-up volume builds across ink type, application, and printing technology segments were triangulated against top-down market sizing from production capacity and consumption intensity benchmarks.
Segment-weighting approaches applied differential growth assumptions across the projection horizon based on regulatory enforcement timelines and technology substitution curves. Modeled dimensions included formulation chemistry tier, end-use regulatory stringency, substrate thermal tolerance, and regional compliance maturity. CAGRs were derived from installed base expansion rates, replacement cycle timing, and share-shift dynamics between UV-curable, water-based, and emerging hybrid systems. Industry-specific inputs incorporated photoinitiator authorization status updates and UV-LED curing equipment penetration trajectories.
Caveats apply where EFSA evaluation timelines, raw material purification bottlenecks, or converter capital expenditure delays could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization and technology adoption curves that may revise with policy announcements or equipment cost movements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Textile Printing Ink Market
Printing Inks
UV Fluorescing Ink Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Continuous Inkjet Ink Market
Printing Inks
Global Digital Fabrication Inkjet Inks Market
Printing Inks
Solvent-Based Inks Market
Printing Inks
Zink Printing Market
Printing Inks
Global Printing Toners Market
Printing Inks
United States Printing Inks Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Global Gravure Printing Inks Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Flexographic Printing Inks Market
Printing Inks
Packaging Inks and Coatings Market